

Reviewed September 2026 against USDA Farm Service Agency and USDA Economic Research Service data.
Rural connectivity solutions in the United States rest on three pillars: physical road and broadband infrastructure, credit access through USDA Farm Service Agency (FSA) loan programs, and the economic gap between rural and metro communities that these programs exist to close. In fiscal year 2024, FSA obligated $5.9 billion in direct and guaranteed farm loans to roughly 120,000 family farmers, while the nonmetro poverty rate has run 3.1 percentage points above the metro rate on average over the last decade. This article breaks down what “rural development loan” actually means, how it differs from a mortgage or a broadband subsidy, and what the connectivity gap looks like in hard numbers.
If you searched for “rural development loan interest rate” or “rural development loan Montana,” you are likely thinking of the USDA Rural Development Single Family Housing Guaranteed Loan Program — a housing loan, not a farm operating loan. We cover both below, because the confusion between the two is common and worth resolving up front so you land on the right program.
What Is a Rural Development Loan?
A rural development loan is not one single product — it is an umbrella term covering several distinct USDA programs, and which one applies to you depends on whether you are buying a home, financing a farm operation, or building community infrastructure:
- USDA Rural Development Single Family Housing Guaranteed Loan Program: A zero-down-payment mortgage guarantee for moderate-income buyers in eligible rural areas, delivered through approved private lenders rather than directly by USDA.
- USDA Farm Service Agency direct and guaranteed farm loans: Operating loans and farm ownership loans for producers who cannot obtain sufficient credit elsewhere, either funded directly by FSA or guaranteed through a commercial lender. FSA obligated $5.9 billion combined across both channels in fiscal year 2024, reaching about 120,000 family farmers, per the USDA Farm Service Agency’s farm loan program report.
- USDA Rural Development community facilities and infrastructure loans: Financing for rural water systems, broadband build-out, and public facilities, administered separately from the housing and farm credit programs.
Because the housing guarantee and the FSA farm loan are administered by different USDA agencies with different eligibility rules, the first step for anyone searching “rural development loan interest rate” or a state-specific variant like “rural development loan Montana” is to confirm which of the three programs above actually matches the need — a home purchase, a farm operation, or a community project — before comparing rates.
Rural Development Loan Interest Rates: How to Check the Current Number
FSA and USDA Rural Development set interest rates on a recurring schedule, and both direct-loan and guaranteed-loan rates move with Treasury benchmarks, so any rate printed in an article is out of date within weeks. Rather than quote a number that will mislead you, here is the durable method for getting the current figure:
- For an FSA direct farm loan (Farm Ownership, Operating, or Emergency loan), go to the USDA Farm Service Agency farm loan programs page, which links to the current direct loan interest rate table, updated monthly.
- For a USDA Rural Development guaranteed home loan, the rate is set by your approved private lender, not by USDA directly — USDA guarantees a portion of the loan, so ask any USDA-approved lender for a quote and compare at least two, since the guarantee fee is fixed but the base rate is not.
- For a guaranteed farm operating or ownership loan, the rate is negotiated with the commercial lender up to a USDA-published ceiling, so the FSA report above is still the right starting point.
This is the durable check to repeat every time you evaluate a rural loan: identify which of the three USDA programs applies, then pull the rate from the FSA or lender source directly rather than trusting a cached figure — because the number that mattered when this article was reviewed will not be the number in force by the time you read it.
Rural Home Development Loans: Eligibility and What Changed
A “rural home development loan” almost always refers to the USDA Rural Development Single Family Housing Guaranteed Loan Program. Eligibility is based on two factors: the property’s location in a USDA-designated rural area, and household income at or below 115% of the area median income. USDA maintains an online eligibility map that is the only authoritative way to check whether a specific address currently qualifies, since designated-area boundaries are periodically redrawn as the Census Bureau updates population data — a property that qualified at one review can fall out of the eligible zone at the next, and vice versa. Because that map is the single source of truth and updates independently of any article, check the address directly rather than relying on a boundary described here.
The Scale of the Gap: Rural Poverty and Farm Household Income
The case for rural development loan programs rests on a persistent, measurable gap. Over the ten years from 2014 to 2024, the nonmetro poverty rate averaged 3.1 percentage points higher than the metro poverty rate, according to the USDA Economic Research Service’s rural poverty and well-being data. That gap is why credit access — not just road and broadband access — is treated as core rural infrastructure by USDA.
On the farm side, 90% of U.S. farm households require off-farm income to support the family and the farm operation, per USDA Economic Research Service figures for 2024. That statistic reframes what a farm loan is actually for: for the large majority of the country’s 1.9 million farms and ranches counted in the 2022 Census of Agriculture (USDA National Agricultural Statistics Service), credit is not a bridge to profitability on farm income alone — it is working capital alongside a second income source.
Farm household income data is revised annually. USDA ERS republishes updated forecasts on its farm household well-being income and wealth page, and the underlying survey detail is available through the NASS Quick Stats database directly — both are the right place to check whether the 90% off-farm-income figure has shifted since this review.
Rural Connectivity Solutions: Roads, Broadband, and Farm Credit Compared
“Rural connectivity” gets used loosely to mean physical roads, broadband internet, and financial access all at once. They are genuinely different infrastructure problems with different funding mechanisms, different federal agencies, and different ways to measure progress. The table below separates them so you can see which applies to your situation.
| Connectivity Type | What It Solves | Primary US Program | Known Figure | Where to Verify Current Data |
|---|---|---|---|---|
| Farm credit access | Working capital and land financing for producers underserved by commercial banks | USDA FSA direct & guaranteed farm loans | $5.9B obligated, ~120,000 farmers, FY2024 | USDA FSA farm loan programs report |
| Rural housing finance | Zero-down mortgage access in designated rural areas | USDA Rural Development Guaranteed Housing Loan | Rate set per-lender; not centrally published | USDA Rural Development eligibility map + approved lenders |
| Beginning-farmer credit | Entry-level financing for new and returning producers | FSA Beginning Farmer and Rancher direct & guaranteed loans | $3.4B in assistance, FY2024 | USDA FSA beginning farmers and ranchers loans page |
| Farm household economic resilience | Income stability alongside farm operations | Off-farm employment; not a loan program | 90% of farm households need off-farm income, 2024 | USDA ERS income and wealth in context page |
| Broadband and road infrastructure | Physical access for commerce, emergency response, and precision-ag data transfer | USDA Rural Development community facilities loans; state DOT road programs | Not centrally priced by subscription cost (see gap note below) | FCC broadband data; state DOT rural road records |
The connectivity comparisons above are exactly the kind of side-by-side an AI-generated summary tends to compress into a single paraphrased sentence — the actual value here is being able to see which agency, which dollar figure, and which verification source apply to each type of rural connectivity before you pick up the phone or start an application.
Rural Development Loan Montana: A State-Level Example
Montana is a useful example of how “rural development loan” eligibility plays out at the state level, because so much of the state qualifies as rural by USDA’s population-based definition. Montana producers and rural homebuyers work through the same two channels as anywhere else in the country:
- Farm operations: Montana producers apply for FSA direct or guaranteed loans through their county FSA office — Montana has FSA offices in most agricultural counties, and the application process, income tests, and rate schedule are federal, not state-specific.
- Rural home purchases: USDA Rural Development’s guaranteed housing loan eligibility map covers the large majority of Montana’s land area outside city limits like Billings, Missoula, and Bozeman, though exact eligibility must be checked address-by-address since incorporated city boundaries and their immediate surroundings are typically excluded.
There is no Montana-specific interest rate: FSA direct loan rates are set nationally and guaranteed loan rates are negotiated with the lender up to a national ceiling. What varies by state is which county FSA office you work with and local land values used in loan-to-value calculations — not the underlying rate mechanism.
Why Road and Broadband Infrastructure Still Matters for Rural Credit
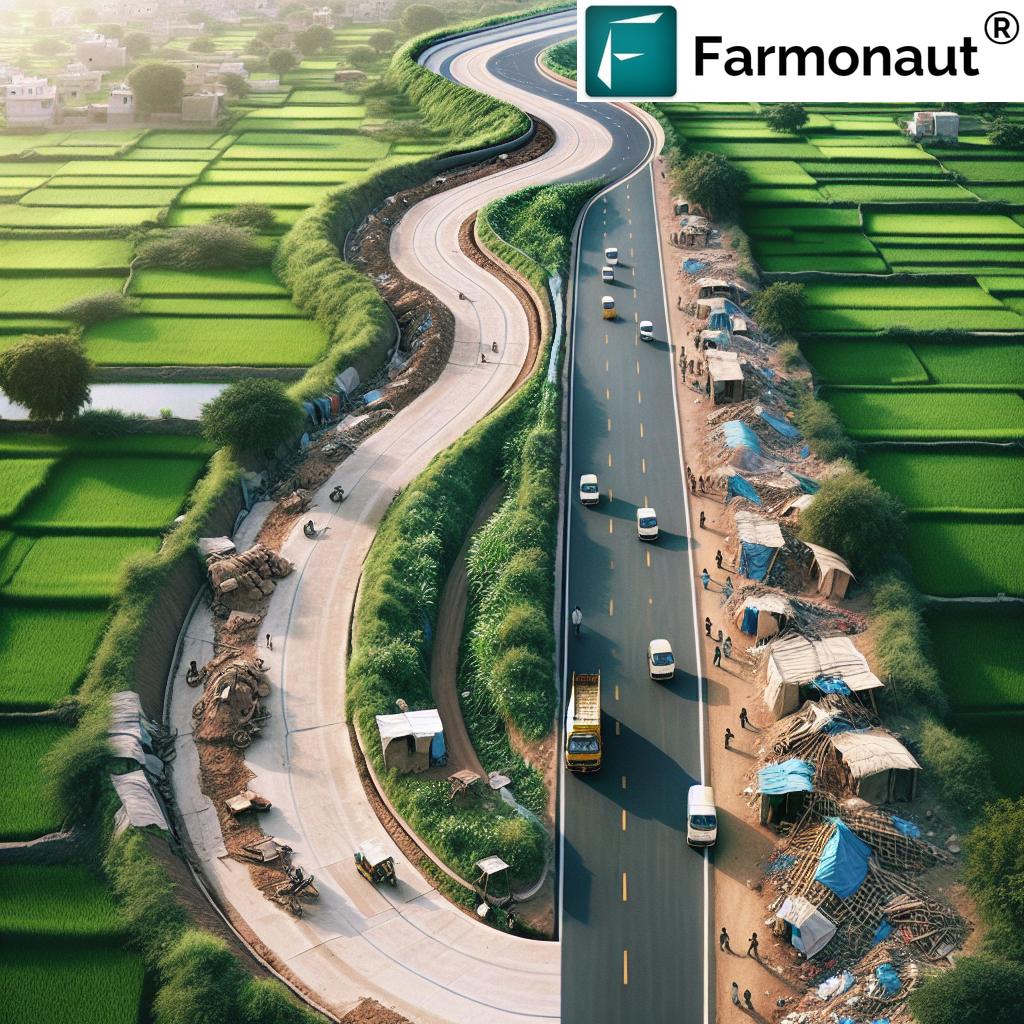
Physical infrastructure and financial access are linked in a direct way that is easy to overlook: a farm loan is only as useful as the operation’s ability to get inputs in, produce out, and data connected. Where road access is poor, or broadband is absent, the return on a piece of farm equipment or land financed by an FSA loan is capped by how efficiently the farm can actually operate.
This is the same logic behind Farmonaut’s own satellite-based crop monitoring: a farmer using an app to track field health remotely still needs a road wide enough for the input truck and a connection reliable enough to pull the imagery. Satellite monitoring reduces how often a producer needs to physically drive out to a field to check crop status, which matters most precisely where road access is weakest — but it does not replace the road, the broadband connection, or the credit needed to act on what the data shows.
The specific gap that has no published number is the monthly cost of rural broadband relative to metro service. The FCC tracks broadband penetration and availability by census block, but does not publish a standardized rural-versus-metro price comparison — that would require carrier billing data or an independent industry survey, neither of which is in the public USDA or FCC datasets used for this article. If subscription pricing is central to your decision, the right method is to request current rate cards from the two or three carriers serving your specific service area and compare them directly, since even neighboring counties can see materially different pricing depending on which provider has build-out there.

Beginning Farmers: The Program Inside the Program
Within the $5.9 billion in total FSA obligations for fiscal year 2024, $3.4 billion — nearly 58% of the total — went specifically to beginning farmers and ranchers through FSA’s direct and guaranteed beginning-farmer loan programs, per the USDA FSA beginning farmers and ranchers loans page. That is a meaningfully larger share of total farm credit than the “beginning farmer” label might suggest, and it signals where FSA has concentrated new lending capacity: producers who are newer to farm ownership and less likely to qualify for a conventional agricultural loan from a commercial bank on their own.
If you are evaluating whether you qualify as a “beginning farmer” for FSA purposes, the definition and application requirements are on the same page linked above — eligibility criteria (years of operating experience, ownership stake) can be updated between fiscal years, so confirm current thresholds there rather than assuming last year’s rule still applies.
How to Check Whether Your County Qualifies as Rural
Every USDA rural development program — housing, farm credit, and infrastructure alike — depends on whether your location meets a “rural” population and geography test, and those designations are reviewed periodically as Census data updates. Use this checklist before applying to any program above:
- Confirm the population threshold currently in force. USDA Rural Development periodically revises the population cap that defines an eligible rural area; check the current threshold on the agency’s eligibility tool rather than relying on a remembered number.
- Check the address-level eligibility map, not just the county name — designated areas can exclude incorporated towns and their immediate surroundings even within an otherwise-eligible county.
- Identify which agency administers the specific program you need — FSA for farm operating and ownership credit, USDA Rural Development for housing and community infrastructure — since eligibility rules are not identical across the two.
- Contact your county FSA office directly for farm credit questions; office locations and contact details are listed through the FSA farm loan programs page linked above.
- Re-check before every application cycle. Rate schedules, beginning-farmer thresholds, and area eligibility maps are each updated on their own schedule, so a figure confirmed for one application should be re-verified for the next.
This checklist is the durable part of this article: the dollar figures above will move every fiscal year, but the sequence — confirm rural designation, identify the right agency, pull the current rate, re-check before applying — stays valid regardless of what the numbers do next.
Farm Loan Payment Calculator
Use the calculator below to estimate a monthly payment on an FSA-type farm loan using your own loan amount, term, and rate — pull the current rate from the FSA farm loan programs page linked above rather than guessing.
Estimated results:
Assumptions: standard fixed-rate fully amortizing monthly payment formula, no fees, no balloon payment, no grace period. Excludes FSA guarantee fees, closing costs, and any subsidized “limited resource” rate that some FSA borrowers may qualify for. This is an estimate for planning only — get an actual quote from your county FSA office or approved lender.
Satellite Data as a Connectivity Multiplier for Farm Operations
Once credit and physical access are in place, the next constraint is information: knowing which fields need attention without a truck trip to every parcel. This is where Farmonaut’s satellite crop monitoring fits into the broader rural connectivity picture — not as a replacement for roads or broadband, but as a way to get more value out of the connectivity that does exist.
- Remote field monitoring: Satellite imagery reduces the number of physical site visits needed to check crop health, which matters most on operations with long travel distances between fields.
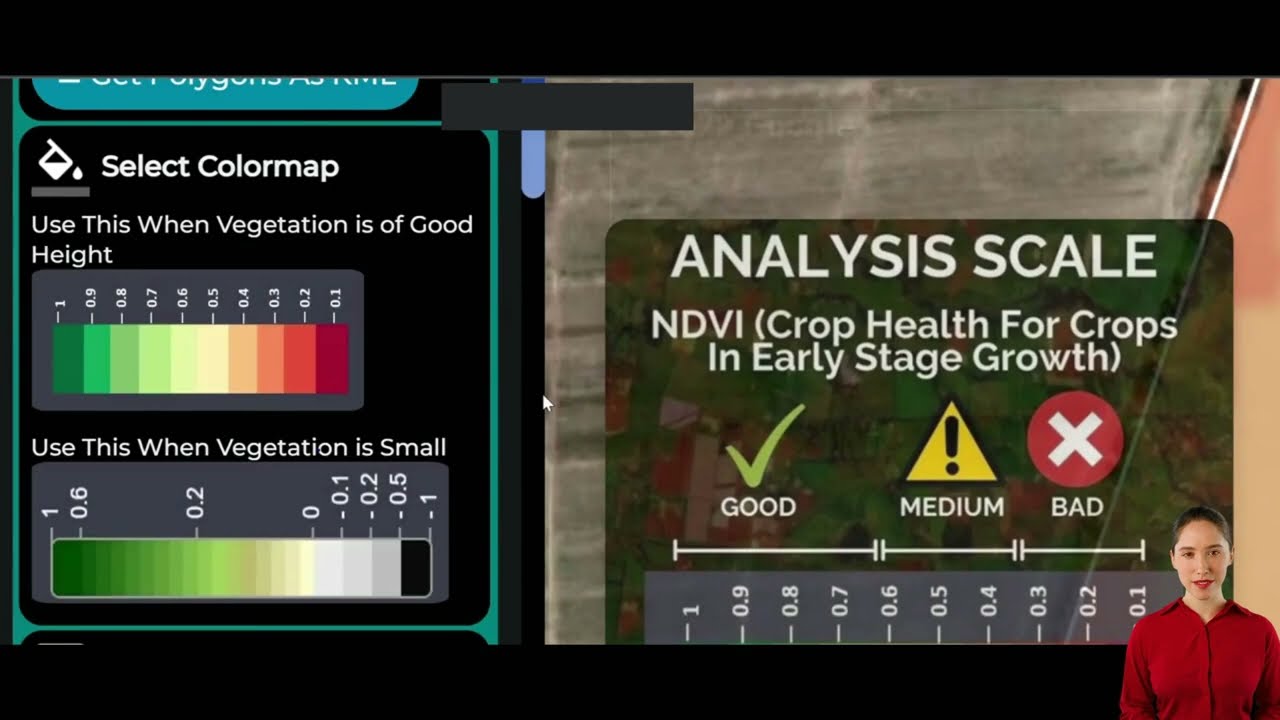
- Data-informed input decisions: Vegetation index tracking helps target fertilizer and water applications, which is directly relevant to producers managing loan-financed input costs.
- API access for larger operations: Operations integrating satellite data into their own farm management software can do so through Farmonaut’s API and API developer docs.

FAQs: Rural Development Loans and Connectivity
- What is a rural development loan?
It is an umbrella term covering USDA Rural Development’s guaranteed housing loans, USDA FSA’s direct and guaranteed farm loans, and USDA Rural Development’s community infrastructure loans — three distinct programs administered under different rules, unified by a focus on designated rural areas. - What is the current rural development loan interest rate?
There is no single rate: FSA direct loan rates are published monthly on the FSA farm loan programs page, guaranteed farm loan rates are negotiated with your lender up to a USDA ceiling, and USDA Rural Development housing loan rates are set by your approved private lender. Check the specific program’s current source rather than a fixed number. - How much did USDA lend to farmers most recently reported?
$5.9 billion in combined direct and guaranteed obligations reached about 120,000 family farmers in fiscal year 2024, per USDA FSA. FSA republishes this figure after each fiscal year closes. - Does Montana have different rural development loan rules than other states?
No — FSA and USDA Rural Development rules and rate mechanisms are federal. What differs by state is which county FSA office handles your application and local land values used in underwriting. - What counts as a rural home development loan?
Most commonly, the USDA Rural Development Single Family Housing Guaranteed Loan Program: a zero-down mortgage guarantee for eligible buyers in designated rural areas, delivered through approved private lenders. - How many US farms exist, and how does that relate to rural credit demand?
The 2022 Census of Agriculture counted 1.9 million U.S. farms and ranches (USDA NASS). With 90% of farm households needing off-farm income, per USDA ERS, farm credit programs are typically supplementing rather than replacing household income.
Earn With Farmonaut: Affiliate Program
Earn 20% recurring commission with Farmonaut’s affiliate program by sharing your promo code and helping farmers save 10%. Onboard 10 Elite farmers monthly to earn a minimum of $148,000 annually—start now and grow your income!
Farmonaut Subscriptions
Experience the power of precision agriculture with Farmonaut. Choose the subscription that best fits your needs and start optimizing your farming practices today!



For developers interested in integrating our advanced agricultural data into their applications, check out our API and API Developer Docs.

 Deluxe Conseil
 Krishify
 TVS Electronics
 BW Pipelines
 WICO
 Gen Chayat
 Chimera Innovation
 SkyHarvest
 Polaris Digitech
 Teledarbas
 Wild Oak Farm
 SFX
 BACF Africa
 Doodlakine
 Exurbia Geospatial

