

Farm finance · Calculator and rates
Farm Mortgage Calculator and Current Ag Loan Rates
FSA’s direct farm ownership rate is 6.25% for November 2026, and Midwest lenders averaged 6.79% on farm real estate loans in the second quarter. Use the calculator to test a payment and its debt coverage against your own numbers.
Key takeaways
- FSA direct rates for November 2026: ownership 6.25%, joint financing 4.25%, down payment 2.25%, operating 5.625%.
- Chicago Fed district banks and Farm Credit lenders averaged 6.79% on farm real estate loans in Q2 2026. A year earlier, when the survey covered banks only, the average was 7.02%.
- On a 25-year loan at 6.79%, each $100,000 costs about $693 a month and about $108,000 in total interest (our calculation).
- US farm real estate averaged $4,500 an acre in 2026: cropland $6,020, pasture $2,000 (USDA NASS).
- Farmer Mac is a US secondary market, so farmers apply through a lender; AMC is a separate UK lender.
In this article
- Farm mortgage calculator: payment and debt coverage
- Current agricultural mortgage rates by loan type
- What is an agricultural mortgage?
- Where to get a farm mortgage: lender types compared
- Monthly payments per $100,000 borrowed
- Farm loan amortization schedule example
- What affects farm land mortgage rates?
- Farmland values and the size of your loan
- Farm and ranch loans in Weatherford and other rural markets
- Farm debt: the national picture
- Agricultural Mortgage Corporation: Farmer Mac or AMC?
- How agricultural mortgage securitization affects your rate
- Underwriting: what lenders check
- Federal oversight of the American farm mortgage
A farm mortgage calculator turns a price, a rate and a term into a monthly payment, then shows whether the land can carry it. For rates, USDA’s Farm Service Agency (FSA) set its direct farm ownership loan at 6.25% for November 2026, in the FSA November lending rate release. Banks and Farm Credit lenders in the Chicago Fed’s Midwest district reported an average of 6.79% on farm real estate loans in the second quarter of 2026, according to the Chicago Fed AgLetter of August 2026.
This page gives you a calculator with a debt coverage check, payment and amortization tables, the official rates by loan type, and land values by region. It is written for farmers, ranchers and buyers comparing lenders. The figures are general information, not a loan offer. Get advice from your lender, an accountant or a farm finance adviser before you sign.
Farm mortgage calculator: payment and debt coverage
Enter the asking price per acre, your acres, your down payment and the rate and term from a written quote. The tool works out the fixed monthly payment. It then compares the yearly payment with the net farm income you expect the operation to have available for this loan, after other debt payments. A coverage result of 1.00 means income only just pays the loan, with nothing left for a bad year.
The calculator assumes a fixed rate, equal monthly payments and no balloon. It leaves out taxes, insurance, appraisal costs and lender fees. Some farm lenders set annual or semi-annual payments, so ask how your own schedule works and treat the result as a planning number.
Try the numbers for your own farm below.
Calculator
What would this farm mortgage cost, and can the land carry it?
Enter your own numbers from a written quote.
- Loan amount, US$: $675,000
- Yearly payment, US$: $56,169
- Debt coverage (income / payment): 1.00
- Total interest over the term, US$: $729,215
- Interest in month one, US$: $3,819
Example values only, set near break-even coverage. They are not a benchmark, forecast or loan offer. Price input is an example, use today’s price. Fixed rate, equal monthly payments, no taxes, insurance or fees.
Current agricultural mortgage rates by loan type
FSA publishes a national rate for its own loans each month. The rates below took effect in November 2026. Direct rates apply to the loans FSA makes itself. They do not tell you what a bank or a Farm Credit lender will quote.
| Loan | Rate, Nov 2026 | Main use |
|---|---|---|
| Direct ownership | 6.250% | Buying or improving farm real estate |
| Joint financing | 4.250% | Ownership loan shared with another lender |
| Down payment | 2.250% | Beginning farmers and ranchers buying land |
| Direct operating | 5.625% | Yearly inputs, livestock, equipment |
| Emergency (actual loss) | 3.750% | Recovery after a declared disaster loss |
The FSA current rate page carries the same figures and is the place to check before you rely on any number here. FSA ownership rates rose from 5.75% in April and May 2026 to 6.25% in October and November. Operating rates rose from 4.75% in April and May to 5.625% in November.
FSA’s rate table does not cover the whole market. FSA’s guaranteed loan page says that on guaranteed loans the rate and terms are negotiated between the lender and the applicant, up to FSA’s maximum. For banks and Farm Credit lenders in the Midwest, the Chicago Fed survey is a useful reference. It is a regional survey, not a national average, so written quotes remain the real test.
Chart
FSA direct loan rates by month
Percent, rate effective in each month, March to November 2026
What is an agricultural mortgage?
An agricultural mortgage is a long-term loan secured on farmland, ranch land or farm buildings. People use one to buy land, refinance older debt, or pay for lasting improvements such as irrigation, barns or grain storage. A lender looks at the borrower’s repayment ability and at the land that secures the loan. On a working farm, that usually brings farm income into the file, along with any off-farm wages.
That answers a common question about farm and ranch home financing: yes, income from the farm operation can count, depending on the lender and the program. FSA, for example, asks ownership applicants to show that they can repay. Ask each lender how it treats Schedule F income, lease income and off-farm pay. A house on a small acreage that earns little from farming may fit a rural home loan better. Our guide to USDA home loan rates covers that route.
Where to get a farm mortgage: lender types compared
In the United States, these are four common channels. Other sources exist, such as life insurers and seller financing, so this list is not complete.
| Lender type | How the rate is set | Best for |
|---|---|---|
| FSA direct | Published monthly by FSA | Eligible family farmers, loans up to $600,000 |
| FSA guaranteed | Negotiated with the lender, under FSA’s maximum | Larger loans a lender wants backed, up to $2,558,000 |
| Farm Credit | Set by each lending association | Buyers who want a specialist farm lender |
| Banks, credit unions | Set loan by loan | Borrowers with a local banking relationship |
FSA direct and guaranteed loans
The FSA farm ownership page lists direct loans of up to $600,000 and repayment of up to 40 years for real estate. It also describes a down payment program that needs 5% from a beginning farmer or rancher, with FSA funding up to 45% of the price or appraised value. Under joint financing, FSA covers up to 50% of the purchase cost and another lender provides the rest.
A guaranteed loan comes from an approved commercial lender, and FSA backs part of the lender’s loss. FSA’s guaranteed page gives a limit of $2,558,000 and a guarantee of up to 95%. The FSA loan guarantee fact sheet adds that the maximum is 90% for most loans, and 95% only in set cases. Limits change by fiscal year, so check the current one.
Farm Credit associations
The Farm Credit System is a nationwide network of lending institutions, regulated by the Farm Credit Administration. Federal rules cap what these lenders can advance on a long-term real estate loan. Under 12 CFR 614.4200, the balance generally cannot pass 85% of appraised value, or 97% where the Farm Credit Act allows it. Private mortgage insurance can cover the part above 85%. The rule also limits second liens: the institution must hold the first lien too. Your own lender’s limit may be lower.
Banks and credit unions
Local banks with an agricultural desk price each loan on its own file. Compare the rate, the term, how often the rate resets, prepayment terms and all fees. A lower rate that resets in five years is a different product from a higher rate fixed for the full term. Our comparison of farm loans in Tennessee shows how these options look within one state.
Monthly payments per $100,000 borrowed
Use this table for a quick check without the calculator. It shows the monthly principal and interest on each $100,000 of loan, rounded to the nearest dollar. We worked these out with the standard fixed-rate formula. The rates shown are example levels drawn from the official figures above, plus 8% as a stress test.
| Rate | 15 years | 20 years | 25 years | 30 years | 40 years |
|---|---|---|---|---|---|
| 4.25% | $752 | $619 | $542 | $492 | $434 |
| 5.625% | $824 | $695 | $622 | $576 | $524 |
| 6.25% | $857 | $731 | $660 | $616 | $568 |
| 6.79% | $887 | $763 | $693 | $651 | $606 |
| 8.00% | $956 | $836 | $772 | $734 | $695 |
The table shows two things. A longer term cuts the payment, but each added decade saves less. A one-point rise in rate adds more to a long loan, as a share of the payment, than to a short one.
Farm loan amortization schedule example
An amortization schedule shows how much of each payment goes to interest and how much pays down the loan. Early payments are mostly interest. Here is a $100,000 loan at 6.79% over 25 years, with a payment of about $693 a month. The numbers are our own calculation and only an example.
| End of year | Balance left | Interest paid so far |
|---|---|---|
| 1 | $98,420 | $6,741 |
| 5 | $90,914 | $32,520 |
| 10 | $78,167 | $61,379 |
| 15 | $60,284 | $85,103 |
| 20 | $35,196 | $101,621 |
| 25 | $0 | $108,032 |
After ten years, this borrower has paid about $61,000 in interest and cut the balance by about $22,000. That matters if you may sell or refinance early. Ask your lender for the full schedule on your own loan, because the payment dates and the way interest accrues can change the figures. Ask too whether extra principal payments carry a fee.
What affects farm land mortgage rates?
Several factors move the rate on land and acreage financing. Some are outside your control, and some you can change before you apply.
- Wider interest rates. The AgLetter shows farm real estate rates at 7.02% a year earlier, when it surveyed banks only. With Farm Credit lenders added, they were 6.74% in the first quarter of 2026 and 6.79% in the second.
- Loan-to-value. A larger down payment leaves the lender with more cushion against a fall in land value.
- Repayment capacity. Strong coverage of the payment from reliable income makes the file easier to approve.
- Fixed or variable. The length of the fixed period changes both the rate and your risk.
- Land use. Lenders look at what the land can earn. Irrigated cropland, dry pasture and recreation acreage are different risks.
- The credit cycle. The AgLetter reported weaker Midwest credit conditions in the second quarter of 2026 than a year earlier. Repayment rates on non-real-estate farm loans were lower too. Expect close questions on cash flow.
Farmland values and the size of your loan
Land value limits what a lender will advance. Farm Credit rules, for example, tie the limit to appraised value. The USDA NASS Land Values 2026 Summary, published in July 2026, put US farm real estate at $4,500 an acre, up 3.4% from 2025. Cropland averaged $6,020 an acre, up 3.3%. Pasture averaged $2,000 an acre, up 4.2%.
National averages hide wide gaps. In the same report, farm real estate ranged from $1,710 an acre in the Mountain region to $8,540 in the Corn Belt, among the regions charted here. Ranch buyers should use pasture values for a first check, since a ranch priced against the blended average can look far cheaper or dearer than it is.
Chart
Farm real estate value by region
US$ per acre, 2026, selected NASS regions and the US average
Farm and ranch loans in Weatherford and other rural markets
If you are searching for farm and ranch loans in a place such as Weatherford, Texas, start with the state line in the NASS report, then narrow down. Texas farm real estate averaged $3,100 an acre in 2026. Tennessee averaged $6,500. A state average still says little about one parcel, as water, soils, road access and nearby sales can move value a long way.
Chart
Pasture and cropland value by region
US$ per acre, 2026, selected NASS regions
Next, ask a local appraiser for recent comparable sales. Then talk to a county FSA office, a Farm Credit association and a local bank. For Texas borrowers, our page on farm land loans in Texas goes through the state’s options in more detail.
Farm debt: the national picture
The USDA Economic Research Service balance sheet forecast of 3 September 2026 expects total farm sector debt of $605.1 billion in 2026, up 4.6% from 2025. Farm real estate debt makes up $399.0 billion of that, also up 4.6% in nominal terms. Non-real estate debt is forecast at $206.1 billion.
ERS expects the sector’s debt-to-asset ratio to edge up from 13.34% in 2025 to 13.54% in 2026. That is a sector-wide forecast, and your own farm’s ratio matters far more to a lender. ERS revises these numbers through the year, so check the page for the newest release.
Agricultural Mortgage Corporation: Farmer Mac or AMC?
Searches for “Agricultural Mortgage Corporation” can mean two different institutions in two countries.
Farmer Mac (United States). The Federal Agricultural Mortgage Corporation was created in 1988. The Farm Credit Administration’s profile of Farmer Mac describes it as a stockholder-owned, federally chartered company that runs a secondary market for agricultural real estate, rural housing and rural cooperative loans. It buys eligible loans from lenders and also securitizes them. A farmer applies to a lender, and that lender may then work with Farmer Mac. Farmer Mac calls itself a secondary market provider.
AMC (United Kingdom). The UK’s Agricultural Mortgage Corporation does lend to farmers. Lloyds Bank’s AMC page lists secured business loans of 5 to 30 years with fixed or variable rates. AMC is a Lloyds subsidiary. If you farm in Britain, ask AMC for current rates, as our US figures do not apply there.
How agricultural mortgage securitization affects your rate
Securitization means pooling many loans and selling securities backed by those loans to investors. One example is a Farmer Mac deal from November 2024: Farmer Mac’s release on its FARM series deal describes a pool of 446 agricultural mortgage loans with about $318.8 million in principal.
The link to your rate is indirect. The FCA says Farmer Mac’s aim is to help lenders offer competitive financing and to give them more liquidity and lending capacity. A lender that can sell a loan does not need to hold it for decades, so it can make new loans. That does not promise a lower quote on your farm. It is one more reason to ask each lender whether it sells its loans, and whether your loan’s servicing could change hands.
Underwriting: what lenders check
Every lender has its own rules, so treat this as a list of things to prepare, and ask each lender for its own list.
- Income history. Expect to show several years of farm tax returns, such as Schedule F, along with projections.
- Appraised value. The lender’s limit runs on appraised value, so a price above appraisal means a bigger down payment.
- Debt coverage. The lender will compare income available for debt with all loan payments, old and new. Ask what minimum it wants.
- Management experience. FSA asks ownership applicants for education, training or experience in running a farm.
- Collateral detail. Soil types, water rights, buildings, access and any leases all affect value.
- Balance sheet. Have a current list of assets and debts ready.
Satellite records can add useful background to a field history. Farmonaut keeps season-by-season vegetation maps for the fields you draw, which you can bring to a lender meeting alongside your yield and tax records. Whether a lender gives them any weight is its own decision.
▶ How satellite crop health monitoring works across a large farm. · 4:09
Federal oversight of the American farm mortgage
Federal involvement runs along three lines. FSA makes and guarantees loans. The Farm Credit Administration regulates the Farm Credit System and Farmer Mac. Farmer Mac itself is federally chartered but owned by stockholders. The FCA also notes that Farmer Mac, though it counts as an institution of the Farm Credit System, is not liable for the debts of other System institutions, and they are not liable for its debts.
Developers building tools for farm lenders and monitoring can look at the satellite data API and the API developer documentation.
Checklist before you apply for a farm mortgage
- Check the current month’s FSA rate. It can change each month.
- Pull the NASS state value for your land type, then get an appraisal or comparable sales before you negotiate.
- Gather several years of farm income records and a current balance sheet.
- Run the calculator at your quoted rate, then again at a rate one or two points higher.
- Test coverage with a poor year’s income, not an average year’s.
- Get written quotes from at least one Farm Credit association and one bank with an agricultural desk. Ask an FSA office whether you qualify for its programs.
- Compare term, rate reset dates, payment dates, prepayment terms and all fees side by side.
- Have a lawyer or accountant review the loan papers and tax effects before signing.
The rates and land values above will change. The questions stay the same. For the app, go to the monitoring app page.
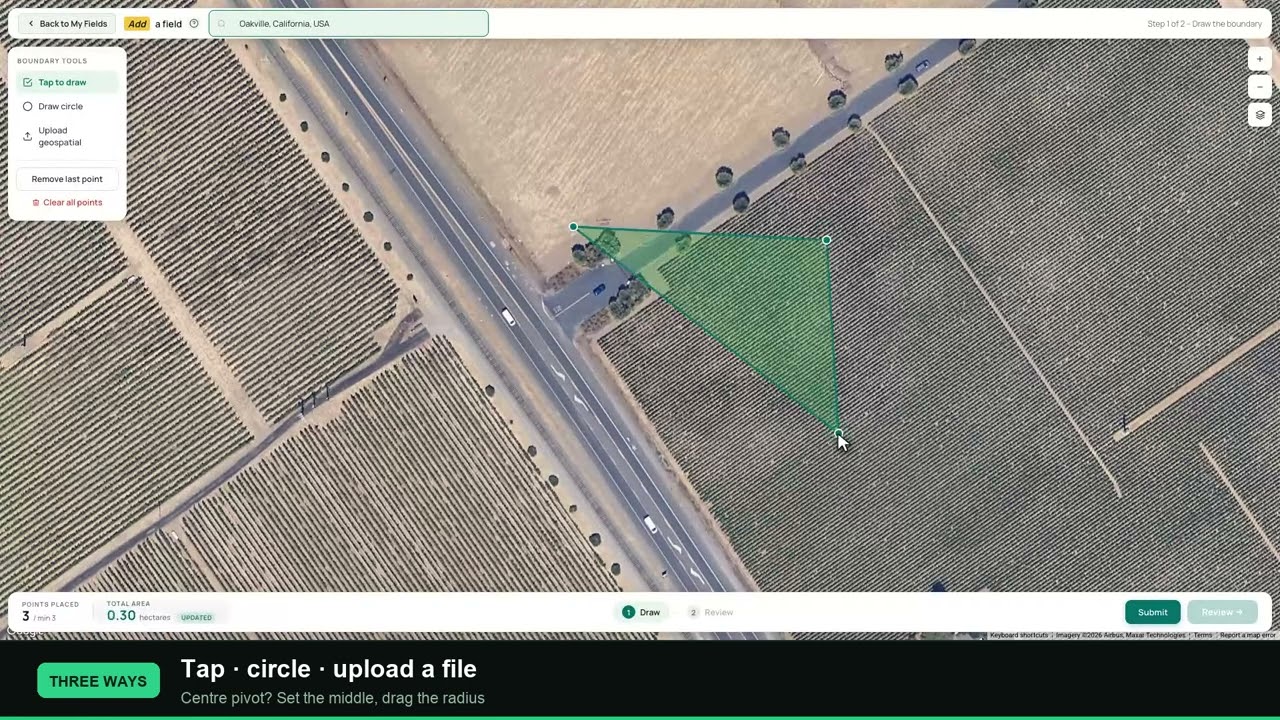
▶ How to draw or upload a field boundary in a farm mapping app. · 2:21
FAQ
What are current farm mortgage rates?
For November 2026, FSA direct ownership loans are 6.25%, joint financing 4.25% and down payment loans 2.25%. Midwest banks and Farm Credit lenders in the Chicago Fed survey averaged 6.79% on farm real estate loans in the second quarter of 2026. Your quote depends on your file and lender.
How do I use a farm mortgage calculator?
Enter price per acre, acres, down payment, rate and term. Then add the income you expect to have for debt. The result is your monthly payment and a coverage figure. Use a rate from a written quote where you can.
How much down payment does a farm loan need?
It depends on the lender. Farm Credit rules generally cap the balance at 85% of appraised value, with some exceptions. FSA’s down payment program asks beginning farmers for 5%. Other lenders may ask for more, so check each quote.
How long can a farm mortgage last?
FSA ownership loans can run for up to 40 years. AMC in the UK lists 5 to 30 years. Banks and Farm Credit lenders set their own terms, so ask for the term and any rate reset dates in writing.
Does Farmer Mac lend directly to farmers?
Farmer Mac runs a secondary market. It buys eligible loans from lenders and securitizes them. A farmer applies through a lender. The UK’s AMC is a separate company that makes loans to farm businesses.
Related pages on our site
Further reading: community engagement in farming.
Farmonaut crop monitoring
See your own fields from space
Draw your fields once and Farmonaut shows satellite vegetation maps for them through the season, on web, Android or iOS.




Keep reading
Sources
- USDA FSA, November 2026 lending rates: fsa.usda.gov
- USDA FSA, October 2026 lending rates: fsa.usda.gov
- USDA FSA, September 2026 lending rates: fsa.usda.gov
- USDA FSA, August 2026 lending rates: fsa.usda.gov
- USDA FSA, July 2026 lending rates: fsa.usda.gov
- USDA FSA, June 2026 lending rates: fsa.usda.gov
- USDA FSA, May 2026 lending rates: fsa.usda.gov
- USDA FSA, April 2026 lending rates: fsa.usda.gov
- USDA FSA, March 2026 lending rates: fsa.usda.gov
- USDA FSA, current loan interest rates: fsa.usda.gov
- USDA FSA, farm ownership loans: fsa.usda.gov
- USDA FSA, guaranteed farm loans: fsa.usda.gov
- USDA FSA, loan guarantee fact sheet: fsa.usda.gov
- Federal Reserve Bank of Chicago, AgLetter, August 2026: chicagofed.org
- USDA NASS, Land Values 2026 Summary (July 2026): release.nass.usda.gov
- USDA ERS, Assets, Debt, and Wealth (3 September 2026): ers.usda.gov
- Farm Credit Administration, About: fca.gov
- Farm Credit Administration, About Farmer Mac: fca.gov
- 12 CFR 614.4200, Cornell LII: law.cornell.edu
- Farmer Mac, About: farmermac.com
- Farmer Mac release on FARM 2024-2, SEC filing (November 2024): sec.gov
- Lloyds Bank, AMC: lloydsbank.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Leher
 AgroRisk
 Oath Inc
 Reddane Farming
 Esri North East Africa
 Cresol
 Atur Kuliner
 MDCV UK
 Zerella Group
 Etech Consulting Madagascar
 Vestlandsforsking
 Agritein
 Delicio
 WB Dev
 Sama Premium
 Prochecker
 Tres Valles
 LACOS Geoinformation
 Magrifly
 LatConnect 60
 Blickwinkel
 Agricultural Credit Policy Council

 Exploration consultancy · South Africa · Gold
 Licence holder · Niger · Gold
 Licence holder · Nigeria · Gold + lithium
 Client · Tanzania · Gold










