

Farm finance · Texas rate guide
Land Loans Texas: Rates and Lender Options Compared
FSA direct farm ownership loans were 6.250% in October 2026 (USDA). Texas veterans’ land loans were 7.25% and bankers averaged 7.46% fixed (Dallas Fed). Compare seven ways to fund land and test your own payment.
Key takeaways
- FSA direct Farm Ownership Loans were 6.250% for October 2026, up from 6.000% in September (USDA FSA).
- The Dallas Fed’s Q3 2026 survey of ag bankers put the average fixed long-term farm real estate rate at 7.46% and variable at 7.54%.
- The Texas Veterans Land Board lends up to $200,000 at 7.25% (26 October 2026), typically with a minimum 5% down payment.
- Direct FSA loans go up to $600,000; guaranteed loans through a bank go up to $2,558,000, with FSA covering up to 95% of a loss.
- Rates change often: get a written quote and advice from the lender before you decide.
In this article
- Land loan rates in Texas right now
- How rates moved over the past year
- 7 ways to finance land in Texas
- Comparison table: Texas land loan options
- FSA monthly rates in detail
- Who qualifies for a Texas land loan
- Which option fits which buyer
- How to apply for a land loan in Texas
- Land loan payment calculator
- A worked example: what a 0.75-point rate gap costs
- What lenders look at beyond the rate
- Land prices and why lenders care
- What bankers said about credit and demand
- Texas regions: what the land costs and what that means for loans
For land loans in Texas, the best-known published rate is from the USDA Farm Service Agency (FSA): its direct Farm Ownership rate is 6.250% for October 2026 (USDA FSA, 1 October 2026). Texas veterans can borrow through the Veterans Land Board at 7.25% (Texas General Land Office, page read 26 October 2026), and ag bankers in the Dallas Fed district reported an average fixed rate of 7.46% on long-term farm real estate loans in the third quarter of 2026. Rates change, so ask the lender for a written quote before you decide.
This guide compares the seven main ways to finance farm and ranch land in Texas, shows the dated rates behind each one, and includes a payment calculator where you can test your own price, down payment and rate. It is general information, not financial advice: rates and rules change, so get advice from a lender, an accountant or an attorney before you sign.
Land loan rates in Texas right now
No single price list covers every Texas lender. Banks, Farm Credit associations and credit unions quote each borrower on credit, down payment, land type and term. Three published sources give you a fair yardstick. All three are averages or program rates, not offers to you.
| Benchmark | Rate | Date and basis | Source |
|---|---|---|---|
| FSA direct ownership | 6.250% | October 2026, set monthly by USDA | USDA FSA |
| FSA joint financing | 4.250% | October 2026, FSA share of a shared loan | USDA FSA |
| FSA down payment loan | 2.250% | October 2026, for the FSA share | USDA FSA |
| Texas VLB land loan | 7.25% | Posted by the General Land Office, 26 October 2026 | Texas GLO |
| Bank fixed, long-term | 7.46% | Average, Q3 2026, bankers in Texas, southern New Mexico and northern Louisiana | Dallas Fed |
| Bank variable, long-term | 7.54% | Same survey, Q3 2026 | Dallas Fed |
The Dallas Fed collected its third-quarter 2026 answers from 50 agricultural bankers between 1 and 9 September. It reported that interest rates ticked up for all loan types in the quarter and that credit standards tightened (Dallas Fed Agricultural Survey, Q3 2026). The survey covers the Eleventh District, so it is wider than Texas alone.
A bank that quotes you far above the survey average is not always wrong. A small down payment, raw land or a weak credit history can all raise the rate. But the gap is a good question to ask: what is driving it, and what would lower it?
Chart
Published FSA, VLB and bank rates compared
Percent; different bases, see labels. Not offers to any borrower
How rates moved over the past year
The Dallas Fed survey lets you see the direction as well as the level. Fixed long-term farm real estate rates fell from 7.84% in the third quarter of 2025 to 7.34% in the first quarter of 2026, then rose to 7.46% by the third quarter. Variable rates followed the same path. The chart shows both lines.
Monthly FSA rates also moved up this autumn. USDA raised the direct ownership rate from 6.000% in September 2026 to 6.250% in October 2026, and the other ownership rates each rose by 0.250 percentage points (USDA FSA, 1 September 2026). Because FSA resets its rates every month, check the current month on the FSA site before you apply.
Chart
Long-term farm real estate loan rates, Dallas Fed district
Average rate in percent, ag bankers in Texas, southern New Mexico and northern Louisiana
7 ways to finance land in Texas
Texas had 230,662 farms on 125.5 million acres in the 2022 Census of Agriculture, with an average farm size of 544 acres (USDA NASS, 2022 Census of Agriculture, Texas profile). That is a large market with many types of lender. Each of the seven below fits a different buyer. The order is not a ranking, because the best fit depends on your credit, your cash, your experience and the land.
1. Farm Credit System lenders
The Farm Credit System is a nationwide network of customer-owned cooperatives that supports more than 615,000 farmers, ranchers, co-ops and rural borrowers in all 50 states (Farm Credit). The Farm Credit Administration oversees it, with a mission to keep Farm Credit System institutions safe, sound and dependable (Farm Credit Administration). In Texas, associations such as Texas Farm Credit list rural real estate loans, ranch and recreational land loans, land refinancing and land improvement loans (Texas Farm Credit, land loans page).
Best for: buyers who want a lender that specialises in agriculture and rural land. Watch for: rates and down payments are quoted per borrower, so compare at least two written quotes.
2. FSA direct farm ownership loans
FSA lends directly to eligible farmers and ranchers. Direct farm ownership loans go up to $600,000, with repayment terms up to 40 years for real estate (USDA FSA, Farm Ownership Loans). Applicants must be U.S. citizens or permanent residents, have enough education, training or experience to manage a farm, and show they can repay.
Best for: beginning and family-size farmers with a plan but a thin credit or equity record. Watch for: the $600,000 cap can fall short of Texas land prices, so many buyers combine FSA with another lender (see joint financing below).
3. FSA down payment and joint financing
Two FSA options reduce the cash you need. The Down Payment Program is for beginning farmers and ranchers and asks for a 5% down payment, with FSA financing up to 45% of the purchase price or appraised value. Joint financing means FSA lends alongside another lender and covers up to 50% of the purchase cost (USDA FSA, Farm Ownership Loans). In October 2026 the FSA rates for these were 2.250% and 4.250% (USDA FSA, October 2026). Those rates apply to the FSA share only. The other lender prices its own share.
Best for: a first land purchase where cash is the limit. Watch for: eligibility rules for beginning farmers differ by program, so ask your local FSA office to confirm yours.
4. FSA guaranteed loans through a bank
With a guaranteed loan, a commercial lender makes the loan and FSA backs it. FSA will guarantee loans up to $2,558,000 and covers up to 95% of a possible loss of principal and interest (USDA FSA, Guaranteed Farm Loans). The lender sets the interest rate, so it is not the FSA rate in the table above.
Best for: larger purchases than the direct cap allows. Watch for: the lender, not FSA, is your point of contact and sets the rate and many of the terms.
5. Texas Veterans Land Board loans
Texas veterans and military members can borrow up to $200,000 to buy land, and the program typically asks for a minimum 5% down payment on tracts of one acre or more. The posted rate was 7.25% when we read the page on 26 October 2026. The land must have at least one acre, legal and usable access to a public road, and not have been owned by you or your spouse in the past three years. No value is given to improvements on the tract (Texas General Land Office, Land Loans). VLB rates and discounts can change at any time, and all loans need credit approval.
Best for: eligible veterans buying raw or lightly improved land in Texas. Watch for: the $200,000 cap and the no-value-for-improvements rule limit what you can buy with it.
6. Commercial banks, credit unions and ag co-ops
Local banks and credit unions know county land values and often finance ranch and farm tracts with their own terms. The Dallas Fed average of 7.46% fixed and 7.54% variable for long-term farm real estate (third quarter of 2026) is a fair reference for a bank quote. Credit unions and cooperatives set their own rates and membership rules, and no single standing price covers them for Texas.
Best for: buyers with good credit, a solid down payment and a relationship with a local bank. Watch for: loan-to-value limits can be lower on raw or unimproved land, so ask each lender for its limit in writing.
7. Seller financing and private loans
In seller financing, the owner acts as the lender and you pay the seller over time. Terms are negotiated, so there is no standard rate or down payment. Have an attorney read every clause, including what happens if you miss a payment, whether the loan balloons after a few years and how the title is held until the loan is paid.
Best for: buyers who do not fit bank rules yet and have a willing seller. Watch for: a balloon payment or a high rate can cost more than a bank loan over time.
Comparison table: Texas land loan options
This table puts the published facts side by side. Where a lender does not publish a number, the cell says so instead of guessing.
| Loan type | Rate | Size limit | Down payment | Who it fits |
|---|---|---|---|---|
| Farm Credit | Quoted per borrower | Set by association | Set by association | Farm, ranch and rural land buyers |
| FSA direct | 6.250% (Oct 2026) | Up to $600,000 | Down payment program: 5% | Beginning and family-size farmers |
| FSA joint financing | 4.250% FSA share (Oct 2026) | FSA up to 50% of cost | Set by partner lender | Buyers who need a second lender |
| FSA guaranteed | Set by the lender | Guarantee up to $2,558,000 | Set by the lender | Larger purchases |
| Texas VLB | 7.25% (26 Oct 2026) | Up to $200,000 | Typically 5% | Texas veterans and military members |
| Bank or credit union | Dallas Fed avg 7.46% fixed (Q3 2026) | Set by the lender | Set by the lender | Borrowers with credit and cash |
| Seller financing | Negotiated | Negotiated | Negotiated | Buyers outside bank rules |
Rates move, so treat every number here as a dated reference and not as a quote. Get advice from the lender before you rely on any of them.
FSA monthly rates in detail
USDA announces FSA farm loan rates at the start of each month. For October 2026, effective 1 October, the direct rates were: Farm Operating Loans 5.375%, Farm Ownership Loans 6.250%, Farm Ownership joint financing 4.250%, Farm Ownership down payment 2.250% and Emergency Loans 3.750%. Direct farm operating loans go up to $400,000 (USDA FSA, Farm Operating Loans). That product covers seed, feed, fuel, equipment and similar costs, not land.
The chart below compares September and October 2026. All four ownership and operating rates moved up by 0.125 to 0.250 percentage points in a single month. For a $400,000 loan, a quarter of a point is about $1,000 a year in interest at the start of the loan, so the month you apply can matter.
Chart
FSA direct loan rates rose in October
Percent, effective 1 September and 1 October 2026
Who qualifies for a Texas land loan
Each lender sets its own test, but the same questions come up again and again.
- FSA: U.S. citizen or permanent resident, enough farm education, training or experience, and the ability to repay. Eligibility also depends on the specific ownership loan type (USDA FSA, Farm Ownership Loans).
- Texas VLB: age 18 or older and a legal Texas resident on the date of application, and either an active duty member, a Texas National Guard member, a reserve member with 20 qualifying years, a veteran with at least 90 active duty days (unless discharged sooner for a service-connected disability) who was not discharged dishonorably, or the surviving spouse of a veteran who was missing in action or whose death was service connected.
- Farm Credit, banks and credit unions: each looks at income, debts, credit history, the down payment and the land itself. Co-ops and credit unions may also ask for membership.
- Hobby and recreational land: FSA programs are for farm operations. Farm Credit associations list ranch and recreational land loans, and banks make them too. Ask what the lender needs to see for non-farm use.
Which option fits which buyer
Use this short guide to decide where to ask first. It is a starting point, not a recommendation of any lender.
- First-time buyer with little cash: ask FSA about the Down Payment Program and joint financing, and ask a bank or Farm Credit association about the other share of the loan.
- Veteran buying a tract from one acre up: look at the Veterans Land Board first, then compare its 7.25% rate with one bank quote. The $200,000 cap may be enough for a small tract but not for a working ranch.
- Established operator buying a neighbor’s land: compare a Farm Credit association and a local bank. Both can lend more than the FSA direct cap.
- Buyer who needs more than $600,000 but has a thin equity record: ask a bank whether it uses FSA guaranteed loans, which cover up to 95% of a loss and go up to $2,558,000.
- Buyer who does not yet fit bank rules: consider seller financing, but only with a written contract reviewed by an attorney.
Whatever you pick, get at least two written quotes on the same date and the same loan amount. Only then can you compare them fairly.
How to apply for a land loan in Texas
- Check your numbers. Pull your credit report, tax returns, bank statements and a list of assets and debts. For the VLB, have recent pay stubs ready.
- Set a budget. Use the calculator below to see the payment at several rates and terms. Plan for closing costs, survey, title and insurance on top of the price.
- Ask for prequalification from two or three lender types. For example, one Farm Credit association, one local bank, and FSA if you are a beginning farmer.
- Find the land. Check access, water, surveys, minerals and zoning. VLB needs legal, usable road access, and most lenders will require an appraisal.
- Submit the full application. Include a land use plan: what you will grow or raise, expected income, and costs.
- Close. Review the final papers with an attorney or title company, pay your down payment and closing costs, and record the deed.
Complete files move faster. A missing tax return or an unclear plan is a common reason for delay.
Land loan payment calculator
Use the calculator below to test your own purchase price, down payment, rate and term. Add a second rate to see what a lower quote would save.
Try the numbers for your own farm below.
Calculator
What would my monthly land loan payment be?
Enter your own price, down payment, rate and term. Add a second rate to compare a different quote.
- Amount borrowed: $400,000
- Down payment in cash: $100,000
- Total interest over the term: $448,135
- Monthly payment at the second rate: $2,639
- Saving per year at the second rate: $2,261
Example values only, not a benchmark or a quote. Use today’s rate from your lender. Assumes a fixed rate, equal monthly payments of principal and interest, no fees, taxes or insurance. A balloon loan would differ. Get advice from a lender before you borrow.
A worked example: what a 0.75-point rate gap costs
Take a $500,000 tract with 20% down, so the loan is $400,000 over 25 years. At 7.00% the payment is about $2,827 a month, and you pay about $448,000 in interest over the full term. At 6.25% the payment is about $2,639 a month and total interest is about $392,000. The 0.75-point gap is worth about $188 a month, or $2,261 a year.
Term matters as much. The same $400,000 at 7.00% costs about $3,595 a month over 15 years (about $247,000 in interest), $3,101 over 20 years and $2,661 over 30 years (about $558,000 in interest). A longer term lowers the payment and raises the total cost. These are calculations from the formula for a fixed-rate loan, not quotes, and they exclude fees, taxes and insurance.
The same formula shows why the down payment matters. On a $500,000 purchase at 7.00% over 25 years, borrowing $300,000 instead of $400,000 lowers the payment from about $2,827 to about $2,120. Put your own figures into the calculator above to see your case.
What lenders look at beyond the rate
The rate is only one part of the cost. When you compare quotes, line up these items on one page.
- Down payment and loan-to-value: a bigger down payment lowers the loan and often the rate. Raw land can need more cash than improved land, but each lender sets its own limit.
- Fixed or variable rate: a fixed rate keeps the payment steady. A variable rate can start lower but may rise. The Dallas Fed survey shows both types within 0.1 point of each other in the third quarter of 2026.
- Term and balloon dates: a 30-year schedule with a balloon payment after 5 or 10 years is not the same as a loan that fully pays off.
- Fees: origination, appraisal, survey, title and prepayment fees add to the true cost.
- Land use plan: a clear plan for crops, livestock or recreation helps underwriting, and any improvements (fencing, water, clearing) should be budgeted apart from the price.
Ag bankers in the Dallas Fed district also pointed to land pressure from other uses. In the third-quarter 2026 survey one banker wrote that significant acreage is being converted to data centers and alternative energy. Check the zoning and any easements, leases or mineral rights before you borrow against a tract.
Land prices and why lenders care
Lenders lend against the value of the land, so local prices matter. The Dallas Fed survey put average Texas dryland cropland at $3,455 an acre and ranchland at $4,446 an acre in the third quarter of 2026, up 8.2% and 11.1% from a year earlier. Irrigated cropland averaged $3,269 an acre, down 3.5%. These are averages of banker reports. Individual regions vary widely, and some regions have only three bankers reporting, so use them as context and not as an appraisal.
The chart shows ranchland by region. Central Texas averaged $11,333 an acre while the High Plains regions were near $1,100 to $1,350. Bankers reported East Texas ranchland up 40.9% on the year from a small sample, so treat that single figure with care.
Nationally, land is the biggest part of farm debt. USDA’s Economic Research Service forecasts U.S. farm sector debt of $605.1 billion in 2026, and farm real estate debt of $399.0 billion, which is about two thirds of the total (USDA ERS, Assets, Debt, and Wealth).
Chart
Texas ranchland value by region, Q3 2026
Banker-reported averages; 3 to 6 banks per region, so read with care
What bankers said about credit and demand
Besides rates, the Dallas Fed survey tracks how lending feels from the banker’s side. In the third quarter of 2026, 8.3% of bankers reported more farm real estate loan volume than a year earlier, 75.0% reported the same and 16.7% reported less (Dallas Fed Agricultural Survey, Q3 2026). The credit standards index showed more tightening. One banker said demand for ag real estate loans was steady to lower because higher rates deter investment, and that inventory of land for sale had grown and stayed on the market longer, except for good pasture.
For a buyer, tighter standards mean a cleaner file wins. Bring tax returns, a clear plan and enough cash for the down payment and closing costs. Longer time on market can also give you room to negotiate on price, but local conditions vary, so ask a local broker or appraiser.
Texas regions: what the land costs and what that means for loans
Texas ranchland averages differ about tenfold between regions ($1,100 to $11,333 an acre), so the same loan limit buys very different tracts. In the Dallas Fed survey for the third quarter of 2026, Texas dryland cropland averaged $1,225 an acre in the Northern High Plains and $1,438 in the Southern High Plains, compared with $7,000 in Central Texas and $8,000 in North Central Texas. Irrigated cropland averaged $2,933 in the Northern High Plains and $6,250 in Central Texas. Only a few bankers answered in some regions, and the survey flags the regions where data are thin.
What this means for a loan: a $200,000 VLB loan or a $600,000 FSA direct loan covers far more acres in the High Plains than in Central Texas. Lenders also look at the type of land. Dryland, irrigated land and ranchland carry different income and risk, and appraisers value water rights, access and improvements separately. Land near Austin, Rockwall or the Hill Country is generally in the higher-priced part of the state, so check the regional averages above. Ask local lenders and appraisers for sales near your tract.
Showing a lender the land and the plan
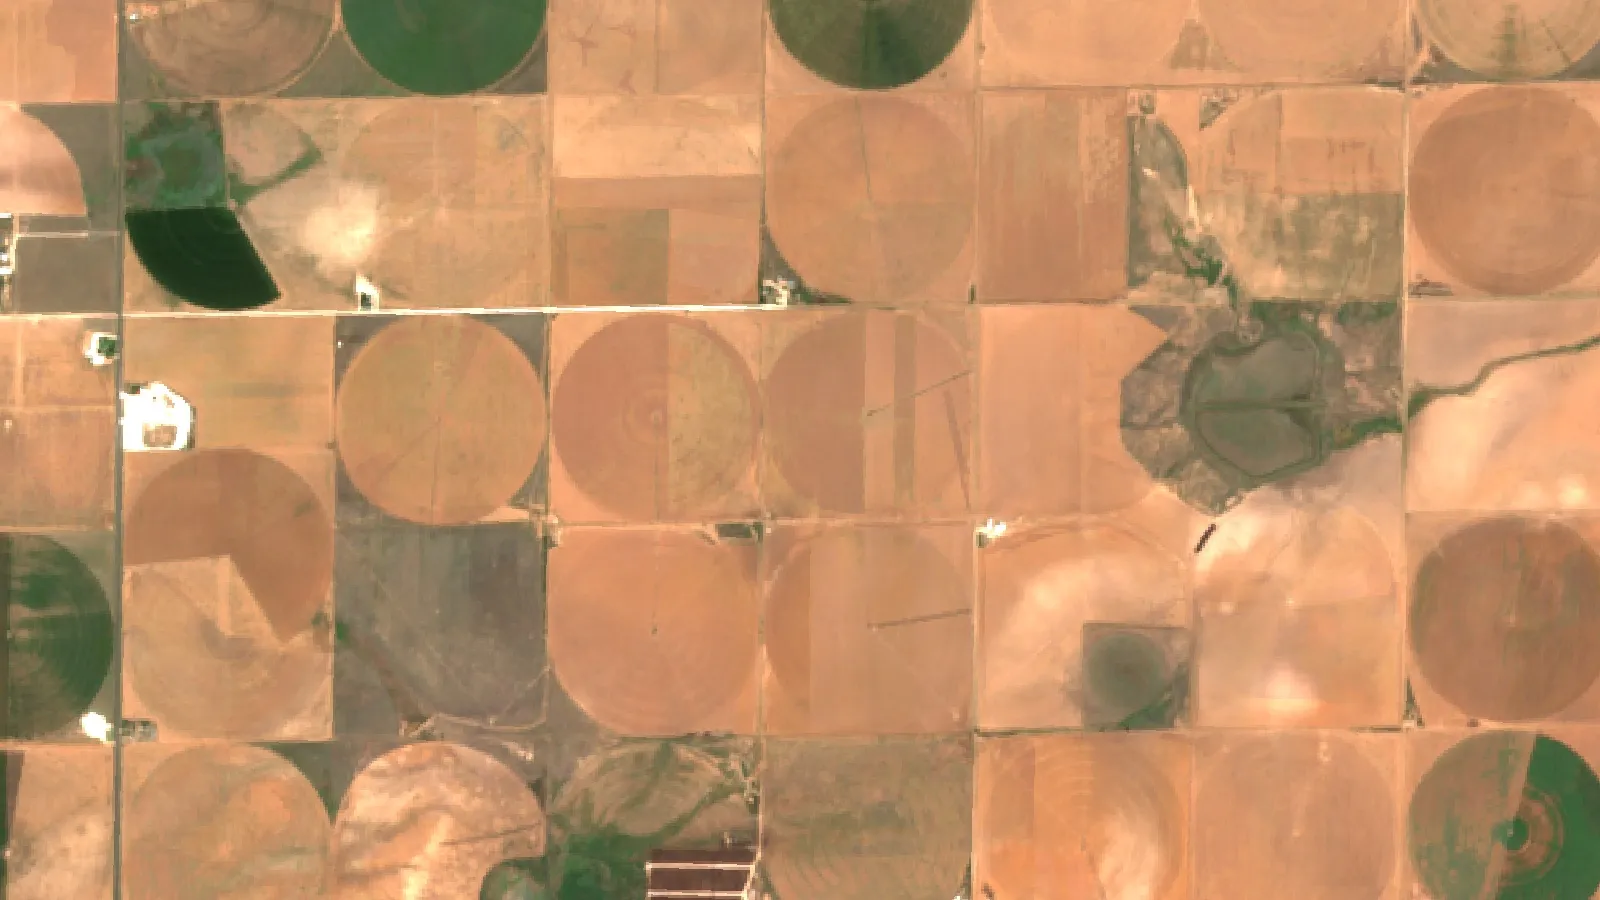
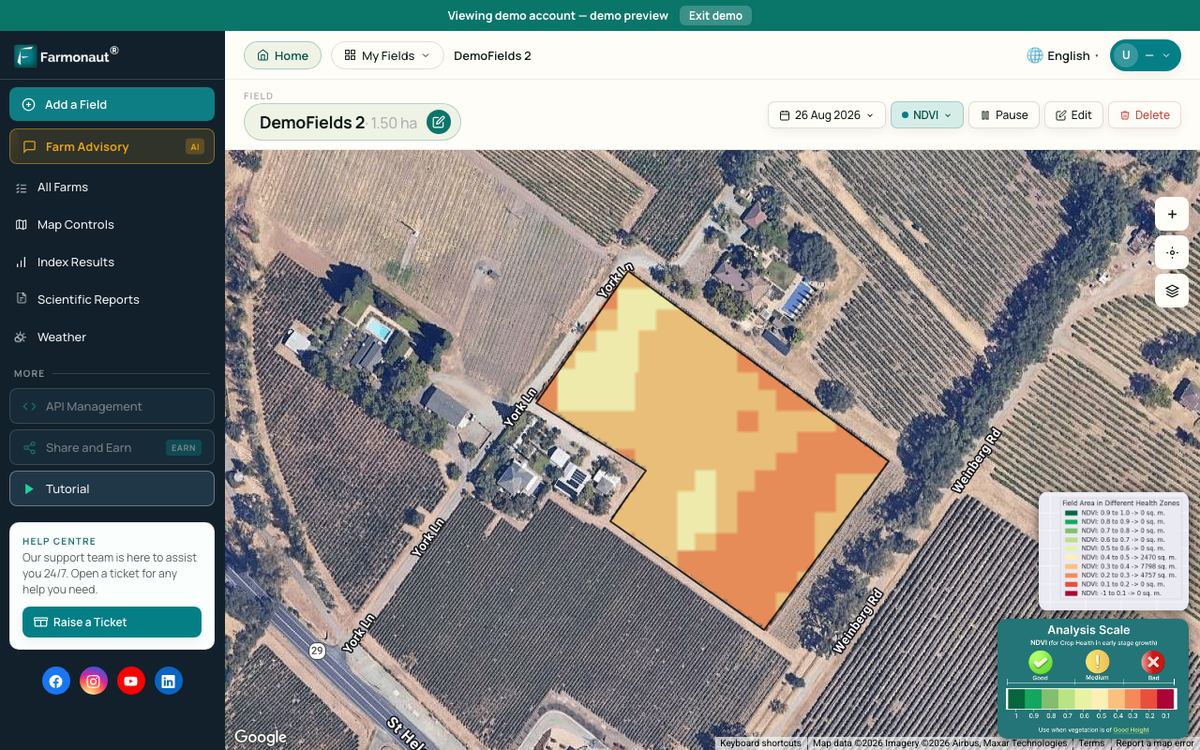
A lender wants proof that the land can earn enough to pay the loan. Maps, soil information, past yields and a crop plan all help. Satellite images show how vegetation on a tract changed across seasons, which can support a written plan, although they do not replace an appraisal or a soil test. Farmonaut Satellite + AI Farm Monitoring System is one tool that provides this kind of field imagery; the video below shows how to read it.
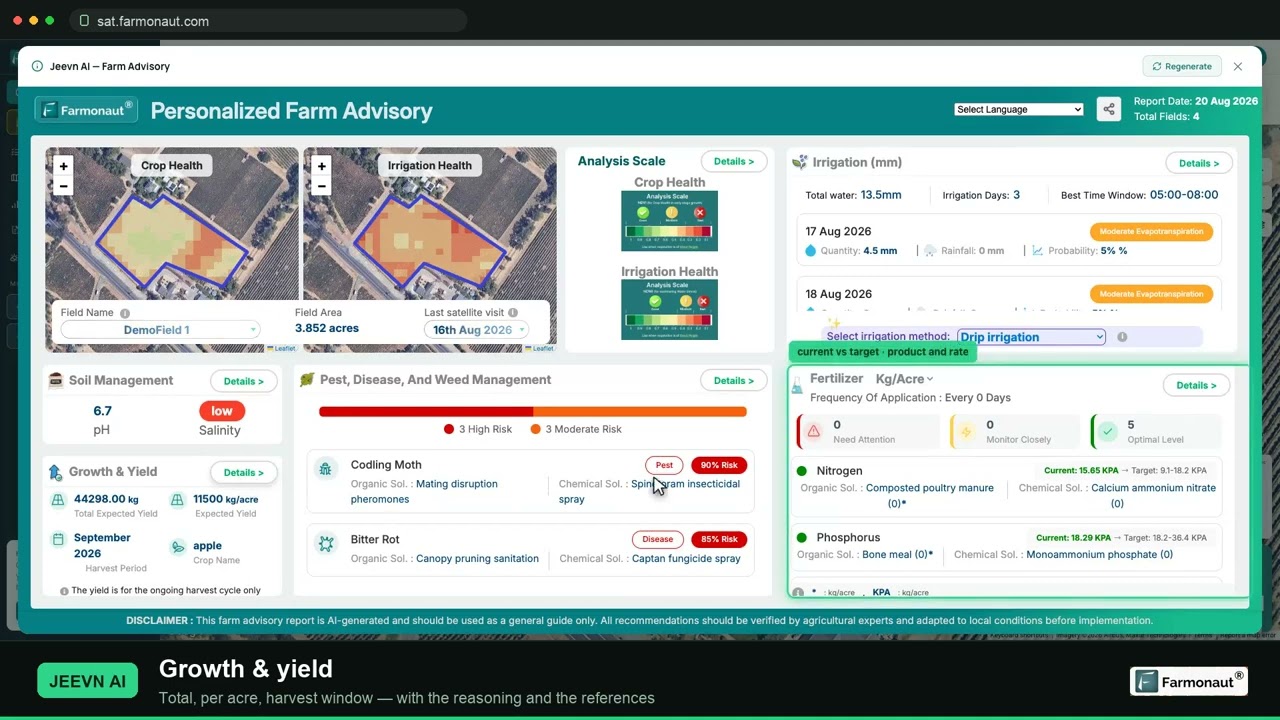
▶ A 20-minute walkthrough of satellite crop monitoring: reading NDVI and pulling a field report. · 19:36
Refinancing a Texas land loan
Many owners refinance to lower the rate, change from variable to fixed, pull out equity for improvements or combine loans. Farm Credit associations list land refinancing as a product (Texas Farm Credit, land loans page), and banks offer it too. Compare the total cost, not only the new rate: appraisal, title, legal and prepayment fees can cancel a small rate saving.
A quick test: add up the new fees and divide by the monthly saving. That tells you how many months it takes to break even. If you plan to sell the land before then, refinancing may not pay.
Mistakes to avoid
- Judging a loan by the headline rate and ignoring fees, balloon dates and prepayment terms.
- Comparing an FSA direct rate to a bank rate without noting the $600,000 cap and eligibility rules.
- Skipping a survey, title check or review of mineral and water rights.
- Borrowing to the limit. Dallas Fed bankers reported tighter credit standards and rising rates in the third quarter of 2026, and dry weather was hurting yields and pastures that quarter. Leave room for a bad year.
- Not asking for the quote in writing, with the date it expires.

▶ Farm land types and land cover classification: how land is classified from satellite data. · 8:53
Questions to ask every lender
- What is the rate today, is it fixed or variable, and how long is the quote good for?
- What is the longest term and is there a balloon payment?
- What is the maximum loan-to-value on this type of land (raw, improved, irrigated, ranch)?
- What fees apply at closing, and is there a prepayment penalty?
- Do you finance improvements such as fencing, water or clearing, and can they be added later?
- What documents do you need, and how long does underwriting usually take?
- If rates move before closing, can I lock the rate and what does that cost?
Write the answers down in one table so you can compare lenders side by side. Rates change, so get the lender’s advice for your own case.
FAQ
What is the minimum down payment for land loans in Texas?
It depends on the lender. The FSA Down Payment Program asks beginning farmers for 5%, and the Texas VLB typically asks veterans for a minimum 5% on tracts of one acre or more. Banks, credit unions and Farm Credit associations set their own limits, which can be higher for raw land. Ask each lender for its loan-to-value limit.
What are current farm and ranch land loan rates in Texas?
In October 2026, FSA direct Farm Ownership loans were 6.250%. The Texas VLB land loan rate was 7.25% on 26 October 2026. The Dallas Fed reported an average fixed rate of 7.46% on long-term farm real estate loans for the third quarter of 2026. Rates change often, so confirm with the lender.
Can I get a land loan in Texas with a low credit score?
FSA direct loans look at ability to repay, and eligibility rules vary by loan type. Credit unions, co-ops and seller financing may also be more flexible than a large bank. Each lender decides, so ask what it needs and how you can improve your file.
Do hobby farms or recreational land qualify?
FSA loans are for farm operations. Farm Credit associations in Texas list ranch and recreational land loans, and local banks also lend on non-farm rural land. Expect the lender to ask about the planned use and how you will repay.
Are there loans for new farmers in Texas?
Yes. FSA has a Down Payment Program and joint financing for beginning farmers, and FSA also offers operating loans for production costs. Farm Credit associations and banks may have their own beginning-farmer programs, so ask each one directly.
Can I refinance a Texas land loan?
Yes, if your lender or a new lender will make the loan. Farm Credit associations and banks offer refinancing. Compare fees and prepayment terms with the monthly saving before you decide.
Where to check the numbers yourself
These official pages are the source of the figures above. Rates and rules change, so go to them for the current version.
- USDA FSA monthly lending rates
- Texas General Land Office, Veterans Land Board land loans
- Dallas Fed Agricultural Survey
- Farmers.gov farm loans
More from Farmonaut: farm loans in Tennessee, farm operating loan guide, crop loan and insurance paperwork, farm management app, fleet management, carbon footprint tool, product traceability, urban farming article, satellite and weather API docs and API access.
Farmonaut crop monitoring
See your own fields from space
Farmonaut Satellite + AI Farm Monitoring System shows vegetation change across your fields through the season.
Sources
- USDA FSA, October 2026 lending rates: fsa.usda.gov
- USDA FSA, September 2026 lending rates: fsa.usda.gov
- Federal Reserve Bank of Dallas, Agricultural Survey Q3 2026: dallasfed.org
- USDA FSA, Farm Ownership Loans: fsa.usda.gov
- USDA FSA, Guaranteed Farm Loans: fsa.usda.gov
- USDA FSA, Farm Operating Loans: fsa.usda.gov
- Texas General Land Office, Land Loans (Veterans Land Board): glo.texas.gov
- Texas Farm Credit, land loans: texasfcs.com
- Farm Credit, about the network: farmcredit.com
- Farm Credit Administration, about: fca.gov
- USDA ERS, Assets, Debt, and Wealth: ers.usda.gov
- USDA NASS, 2022 Census of Agriculture, Texas profile: nass.usda.gov
- Farmers.gov, Farm Loans: farmers.gov
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Red August Group
 Farm Inc
 JJM Farms
 WeMe Global
 Pixxel
 Agrotoken
 Blue BearX
 Insignito
 Croptimum
 DnCubed
 Field Capacity
 Indosistim Teknologi
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC
 AgroGreen Dynamics
 AgroRisk
 Oath Inc
 Reddane Farming

 Licence holder · Niger · Gold










