

Farm finance · USDA loan and grant guide
USDA Farm Loans and Grants: Rates, Limits and How to Apply
From 1 October 2026, FSA direct farm loan rates run from 3.750% (emergency) to 6.250% (farm ownership). Direct limits are $400,000 for operating and $600,000 for ownership loans; higher limits in the 2026 farm bills are only proposed. Grants come mainly from NRCS (EQIP, CSP) and Rural Development (VAPG, REAP).
Key takeaways
- FSA direct rates from 1 October 2026: 5.375% operating, 6.250% farm ownership, 2.250% down payment, 4.250% joint financing, 3.750% emergency (FSA).
- Current limits: $400,000 direct operating, $600,000 direct ownership, $50,000 per microloan, $500,000 emergency, and $2,558,000 guaranteed for FY2027 (FSA handbook 1-FLP).
- The House and Senate 2026 farm bills would raise direct limits to $750,000 (operating) and $850,000 (ownership) and microloans to $100,000, but these are proposals, not law (CRS).
- EQIP has $2.655 billion of mandatory funding for FY2026 and CSP $1.3 billion under current law; FY2026 Value-Added Producer Grants paid up to $200,000 and need matching funds.
- FSA obligated $6.74 billion in 27,792 farm loans in FY2025; beginning farmers took about 56% of them (Farm Bureau review of FSA data).
In this article
- USDA farm loans and grants at a glance
- Current FSA loan interest rates
- USDA agriculture loans by type
- Loan limits now and what the farm bill would change
- Who is eligible for USDA farm loans
- Main USDA grants for farmers
- Rural Development and community grants
- How to apply for a USDA farm loan step by step
- How to apply for USDA grants
- Can your farm carry the loan payment?
- Loans or grants: which fits your plan
- How we checked the numbers
- FAQ
USDA farm loans and grants come from three main offices. The Farm Service Agency (FSA) lends money, the Natural Resources Conservation Service (NRCS) pays for conservation work, and Rural Development funds farm businesses and rural towns. From 1 October 2026 the direct FSA rates run from 3.750% for emergency loans to 6.250% for farm ownership loans, according to the FSA table of current loan interest rates.
The loan side is large. In fiscal year 2025, FSA obligated $6.74 billion across 27,792 farm loans, up 25% in dollars on the year before, as the American Farm Bureau Federation’s review of FSA lending reports. This guide covers each loan type with its current rate and limit, the farm bill changes that are only proposed so far, the main grants, who qualifies, and how to apply step by step. A payment calculator lets you test a loan against your own farm numbers.
USDA farm loans and grants at a glance
The table lists the programs farmers ask about most often. Rates are the direct rates effective 1 October 2026. Limits are per borrower and come from FSA’s own handbook and fact sheets. Grant amounts are for the latest round we could find.
| Program | What it pays for | Maximum | Rate or share | Where to apply |
|---|---|---|---|---|
| Direct operating loan | Seed, feed, fuel, livestock, equipment, family living costs | $400,000 | 5.375% (Oct 2026) | Local FSA office |
| Guaranteed operating loan | Same uses, through a bank or Farm Credit lender | $2,558,000 (FY2027) | Set by the lender, under an FSA cap | Your lender |
| Direct farm ownership loan | Buying land, buildings, soil and water work | $600,000 | 6.250% (Oct 2026) | Local FSA office |
| Down payment loan | Land purchase by a beginning or veteran farmer | 45% of price, up to $300,150 | 2.250% (Oct 2026) | Local FSA office |
| Microloan | Small operating or land needs | $50,000 each | 5.375% or 6.250% | Local FSA office |
| Emergency loan | Losses after a declared disaster | $500,000 | 3.750% (Oct 2026) | Local FSA office |
| EQIP | Conservation practices on working land | Set per practice and state | Payment rates by state | Local NRCS office |
| CSP | Keeping and adding conservation | Five-year contract | Annual payments | Local NRCS office |
| Value-Added Producer Grant | Planning or working capital for value-added products | $50,000 planning, $200,000 working capital | Matching funds needed | USDA Rural Development |
Loan rates change every month and limits change every fiscal year, so check the figures with your local office before you sign anything.
Current FSA loan interest rates
FSA sets its direct rates each month from the government’s own cost of borrowing. The table that took effect on 1 October 2026 lists 5.375% for direct operating loans and operating microloans, 6.250% for direct farm ownership loans and ownership microloans, 4.250% for joint financing, 2.250% for down payment loans, and 3.750% for emergency loans based on actual loss.
Chart
FSA direct loan interest rates by loan type
% per year, rates effective 1 October 2026
Rates move. In July 2026 the same table showed 5.125% for direct operating loans and 6.000% for direct farm ownership loans, according to the FSA July 2026 lending rates release. That is a rise of a quarter of a point in three months. Your rate is the one in force when the loan is approved or closed, so ask your office which date applies.
Guaranteed loan rates
Guaranteed loans are made by a commercial lender, so the lender sets the rate. FSA only caps it. For loans with rates that are variable or fixed for less than five years, the rate may not exceed the prior business day’s SOFR plus 6.75%. For loans fixed for five years or more, the cap is the five-year Treasury note rate plus 5.5%. Lenders may add 1% to each cap if SOFR is below 1.75%. These are ceilings, not the rate you will be offered. Compare quotes from more than one lender.
Special rates for beginning and veteran farmers
Two programs price below the standard rate. Down payment loans are set at the direct ownership rate minus 4%, with a floor of 1.5%. Joint financing, where another lender provides at least half of the money, is the direct ownership rate minus 2%, with a floor of 2.5%. The operating microloan rate is capped at 5% for beginning and veteran farmers, as the FSA farm loan information chart shows. With the October 2026 operating rate at 5.375%, that cap matters now.
USDA agriculture loans by type
FSA makes two kinds of loans. Direct loans come from FSA itself. Guaranteed loans come from a bank, Farm Credit association or other lender, and FSA promises to cover up to 95% of the lender’s loss if the borrower does not repay.
Direct operating loans
Operating loans pay for the running costs of a farm: livestock, feed, seed, fertilizer, fuel, farm equipment, minor repairs, family living costs and some debt refinancing. The limit is $400,000. Terms run from one to seven years, depending on what the money buys. Seed money for one season is repaid within the year, while a tractor might be spread over several years. The FSA farm operating loans page says applicants need a satisfactory credit history, the ability to repay, and no access to credit elsewhere at reasonable rates and terms.
Guaranteed operating loans
A guaranteed operating loan covers the same uses, but your own lender writes it. The limit is set for each fiscal year and rises with inflation. FSA’s handbook 1-FLP, amended on 21 September 2026, sets the guaranteed limit at $2,558,000 for FY2027, the year that began on 1 October 2026. The figure was $2,343,000 in FY2026. FSA charges a loan guarantee fee of 1.5%. For small requests, the EZ Guarantee covers loans of up to $100,000.
Farm ownership loans
Farm ownership loans buy land, build or repair buildings, pay closing costs and fund soil and water conservation. The direct limit is $600,000 and the term can reach 40 years. The FSA farm ownership loans page asks for enough education, training or experience in farm management and the ability to repay. A guaranteed farm ownership loan shares the $2,558,000 FY2027 guaranteed limit with guaranteed operating loans, and can also refinance debt.
The down payment loan helps beginning and veteran farmers buy land. The buyer puts down at least 5%. FSA lends the lesser of 45% of the purchase price, 45% of the appraised value, or 45% of $667,000, which works out to a maximum of $300,150. The term is 20 years. A commercial lender or the seller finances the rest.
Microloans
Microloans suit small, new, niche and urban farms. Operating microloans and ownership microloans each go up to $50,000. Operating microloans have terms of one to seven years, and ownership microloans can run up to 25 years. The FSA operating microloan page describes a simpler application with less paperwork than a standard loan, aimed at beginning farmers, veterans and specialty or non-traditional operations. You still need a farm business plan.
Emergency loans
Emergency loans help farms recover from physical or production losses in a declared disaster area. They can cover up to 100% of actual losses, up to $500,000, and can also pay essential family living costs and help reorganize the farm. The rate from 1 October 2026 is 3.750%. Terms are one to seven years for most purposes and up to 40 years for physical losses on real estate. There is a deadline after each declaration, so contact your office soon after a disaster.
Other FSA credit
FSA also offers conservation loan guarantees for practices in an NRCS-approved plan, land contract guarantees of up to $500,000 for owners who sell land to a beginning farmer, youth loans for 4-H and FFA projects, and farm storage facility loans for grain bins, cold storage and drying equipment. The farmers.gov loan assistance tool asks a few questions and points you to the loan types that fit.
▶ Ten small farm business ideas, from microgreens to hens and bees, the kind of start-up a microloan can fund. · 6:03
Loan limits now and what the farm bill would change
The direct limits have not changed since the 2018 farm bill set them at $600,000 for farm ownership and $400,000 for operating loans. Only the guaranteed limit rises each year with inflation, from a base of $1,750,000 in FY2019, as noted in the Farm Bureau review. Land and input prices have risen faster, and farm groups have asked Congress to raise the caps.
Chart
FSA guaranteed loan limit by fiscal year
maximum per borrower, $ thousands, selected fiscal years
Both 2026 farm bills would raise them, but neither is law yet. The Congressional Research Service comparison of the House and Senate bills says H.R. 7567 and the Senate bill would lift the direct ownership limit from $600,000 to $850,000 and the direct operating limit from $400,000 to $750,000. Guaranteed loans would rise to $3 million for operating loans and $3.5 million for ownership loans, and microloans would go from $50,000 to $100,000. The bills would also remove the separate cap on down payment loans.
The House passed its bill earlier in 2026. The Senate Agriculture Committee failed to advance its version on a 10 to 11 vote in August 2026, as Fertilizer Daily reported, and then passed it 12 to 11 at a second markup in September 2026, according to AgWeb. The full Senate still has to vote, and the two bills must be reconciled. When we checked in October 2026, the higher limits were proposals only. Plan with today’s limits.
What the budget reconciliation law did not change
The July 2025 budget reconciliation law (H.R. 1, often called the One Big Beautiful Bill Act) extended the main commodity programs, such as ARC, PLC and Dairy Margin Coverage, through 2031 and raised reference prices, the Farm Bureau summary of the final provisions explains. It did not change FSA loan limits, which is why those are still waiting on a farm bill.
Chart
FSA direct loan limits: current and proposed
maximum per borrower, $ thousands; proposed limits are in both the House (H.R. 7567) and Senate bills, not yet law
Who is eligible for USDA farm loans
Each loan has its own rules, but most FSA loans share a core set of tests. You will usually need to:
- Be a U.S. citizen, non-citizen national or qualified alien (permanent resident for ownership loans).
- Run, or plan to run, a family-size farm or ranch after the loan closes, as owner or tenant.
- Show a satisfactory credit history.
- Show you can repay from farm and other income, with a cash-flow plan.
- Be unable to get enough credit from a commercial lender at reasonable rates and terms (for direct loans).
- Have farm experience, training or education. Current law sets a three-year farm experience requirement for the loan program; the House bill would cut it to two years and let USDA accept other training.
Beginning farmers get extra help. FSA defines them as farmers and ranchers in their first ten years of operation, and Congress sets aside a share of loan funds for them each year, according to the FSA fact sheet for beginning farmers and ranchers. In FY2025, beginning farmers took 15,552 loans worth $3.53 billion, about 56% of all FSA farm loans by number. Veterans have the same access to down payment loans and the capped microloan rate.
Main USDA grants for farmers
Grants do not have to be repaid, but they come with rules. Most pay a share of a cost, pay after the work is done and inspected, or need you to match the money. They are also competitive: a good project can still miss out in a year with many applicants. The largest farm-level programs are the two NRCS working-lands programs, EQIP and CSP.
Chart
EQIP and CSP mandatory funding under current law
$ billion per fiscal year, FY2026 to FY2031
Environmental Quality Incentives Program (EQIP)
EQIP pays farmers, ranchers and forest landowners to put conservation practices on working land: cover crops, nutrient management, fencing and water for grazing, irrigation upgrades, high tunnels, manure storage and many more. An NRCS planner helps you choose practices. You sign a contract, do the work, and are paid the state’s rate once the work meets NRCS standards, according to the NRCS EQIP page. Some producers may also qualify for an advance payment.
Applications are taken all year, but each state has ranking dates. Apply before your state’s date to be considered in that funding round. Under current law, EQIP’s mandatory funding is $2.655 billion for FY2026, rising to $3.255 billion a year from FY2028, the CRS comparison shows.
Conservation Stewardship Program (CSP)
CSP is for farms that already do good conservation work and want to do more. Contracts last five years and pay each year for keeping existing practices and adding new ones. You can compete for a renewal if you meet the first contract and agree to new goals, the NRCS CSP page explains. Current law gives CSP $1.3 billion of mandatory funding for FY2026, rising to $1.375 billion a year by FY2029.
Value-Added Producer Grants (VAPG)
VAPG helps farmers turn a raw crop or animal product into something worth more: cheese from milk, packaged meat, jam, milled flour, or a local brand. The FY2026 national round had about $25 million, with a top award of $50,000 for planning grants and $200,000 for working capital grants, according to the USDA Rural Development VAPG briefing for FY2026. The window closed on 22 April 2026. At least 10% of funds were reserved for beginning, veteran and socially disadvantaged farmers and some other groups.
The rules are strict. You must produce and own more than half of the raw commodity used in the product, and you need matching funds at least equal to the grant. VAPG is not for research, farm training or buying land. Watch the Rural Development page for the FY2027 notice.
Sustainable Agriculture Research and Education (SARE)
SARE grants fund research and education on sustainable farming. Farmers and ranchers can apply, as can researchers, extension staff and graduate students, the SARE grants page says. A farmer grant usually pays for an on-farm trial, such as testing a cover crop mix or a grazing system. SARE grants cannot be used to start a farm or to buy land, equipment or animals beyond small project costs.
▶ Seven simple conservation practices, such as cover crops, that programs like EQIP and CSP help pay for. · 4:34
Rural Development and community grants
USDA Rural Development funds rural businesses, energy projects, housing and community facilities. Most of its money goes to towns, co-ops, nonprofits and businesses rather than to single farms, but some programs help farmers directly.
- Rural Energy for America Program (REAP): grants and loan guarantees for farmers and rural small businesses that add renewable energy or cut energy use, such as solar, efficient grain dryers or irrigation pumps. The grant share and limits are set in each notice and have changed in recent years, so read the current notice before you plan around a figure.
- Community Facilities loans and grants: for rural clinics, schools, fire stations and food banks. Applicants are public bodies, nonprofits and tribes.
- Farm Labor Housing loans and grants: for safe housing for farmworkers, through farm owners, nonprofits and local governments.
- Rural business grants: for small businesses and the groups that support them in rural towns.
Programs can stop. In March 2025 USDA cancelled about $1 billion of funding for the Local Food Purchase Assistance and Local Food for Schools programs, as DTN reported. Those programs had bought food from local farms for food banks and schools. Some other awards were ended early too. Read the terms, keep records, and avoid spending grant money before the agreement is signed.
Urban agriculture and greenhouse grants
USDA’s Office of Urban Agriculture and Innovative Production (OUAIP) has funded urban farms, community gardens, rooftop and indoor growing. In January 2025 it offered $2.5 million in new grants, on top of $53.7 million in grant projects since 2020, according to a USDA notice shared by Ohio State University Extension. In spring 2025 the office pulled its latest round of grant applications, and its director retired in April 2025, as Ambrook Research reported; and we found no new round announced as of October 2026. Greenhouse growers and nonprofits can still look at EQIP high tunnel contracts, VAPG for value-added products, microloans for small structures, and state programs. Our guide to grants aimed at beginning farmers lists more options for people starting out.
▶ How farm technology affects rural towns: money, jobs and internet access. · 3:50
How to apply for a USDA farm loan step by step
The process is similar for most FSA loans. Expect a few weeks for a microloan and longer for land purchases.
Infographic
Applying for an FSA loan in 6 steps
- 1Check what fitsUse the farmers.gov loan tool and call your county FSA office.
- 2Write a planMarkets, yields, prices and a one-year cash-flow budget.
- 3Gather recordsTax returns, balance sheet, debts, leases and experience.
- 4ApplyFSA forms for direct loans; your lender applies for guaranteed loans.
- 5Meet the officerFSA reviews credit, cash flow and collateral.
- 6Close and reportSign the documents and keep yearly records.
- Check what fits. Use the farmers.gov loan tool, then call your county FSA office. Ask which loan type, rate date and limit apply to you.
- Write a farm business plan. Show what you grow or raise, your markets, expected yields and prices, and a cash-flow budget for at least a year.
- Gather records. Tax returns, balance sheet, current debts, leases or land contracts, and proof of experience or training.
- Fill in the application. Direct loans use the FSA application forms; microloans use a shorter set. For a guaranteed loan, your lender applies to FSA for you.
- Meet the loan officer. FSA reviews your credit, cash flow and collateral and may visit the farm. Answer requests quickly; missing papers are a common cause of delay.
- Close and keep records. After approval you sign the loan and security documents. Keep yearly records, because FSA reviews your finances during the loan.
If your application is turned down, ask the office to explain why in writing and what you could change. You have the right to appeal an FSA decision.
How to apply for USDA grants
Grant steps differ by agency. NRCS programs are close to the loan process: you visit your service center, set up farm records, and an NRCS planner helps you build a conservation plan. Rural Development and NIFA grants are formal competitions.
- Register early. Many grants need an active SAM.gov registration and a Unique Entity ID before you submit. This can take weeks.
- Read the notice. Each round has a Notice of Funding Opportunity with the deadline, eligible costs, match rules and scoring.
- Plan the match. VAPG and many others need cash or in-kind matching funds you can document.
- Write to the scoring criteria. Reviewers score against the notice. Give clear goals, a budget and measurable results.
- Submit before the deadline through the portal named in the notice, then keep copies of everything.
State departments of agriculture run their own grants as well, such as specialty crop block grants, which USDA funds and states award. Your state agriculture department and county extension office can tell you what is open.
Can your farm carry the loan payment?
Before you apply, test whether the payment fits your cash flow. Lenders look at how much farm income is left to pay debts after operating costs and family living. The calculator below works out the payment for the amount, rate and term you enter, the total interest, and how many times your available income covers the payment. Enter your own numbers; the starting values are examples only, set near break-even.
This guide is general information, not financial, tax or legal advice. Loan terms depend on your situation. Talk to your FSA loan officer, lender or a farm financial advisor before you borrow, and check the current rate and rules with them.
Try the numbers for your own farm below.
Calculator
What will the loan cost each year, and can your income cover it?
Enter your own loan amount, rate, term and the income you have left for debt payments.
- Each payment: $8,896
- Total interest over the term: $77,925
- Coverage ratio (income / payment): 1.01
- Left after payments each year: $104
Example values only, not a quote, benchmark or forecast. The 6.25% example is the FSA direct farm ownership rate effective 1 October 2026 (FSA); your rate depends on the loan type and the date. The formula is a standard fixed-rate amortizing payment and ignores fees, insurance, taxes and rate changes. A coverage ratio below 1 means the income you entered does not cover the payment. This is general information, not financial advice: check the terms with your FSA loan officer, lender or a farm financial advisor.
Loans or grants: which fits your plan
Many farms use both. A loan buys what you need now and is repaid over time. A grant lowers the cost of a specific project but often pays only after the work is done, so you may need a loan or savings to carry the cost first.
| Question | FSA loan | USDA grant |
|---|---|---|
| Must you repay it? | Yes, with interest | No, if you meet the terms |
| What it covers | Land, inputs, livestock, equipment, refinancing | A named project or practice |
| When money arrives | At closing | Often after the work is inspected |
| Competition | Based on eligibility and funds | Scored against other applicants |
| Timing | Year-round | Ranking dates or yearly deadlines |
| Main risk | Payments in a bad year | Matching costs and paperwork |
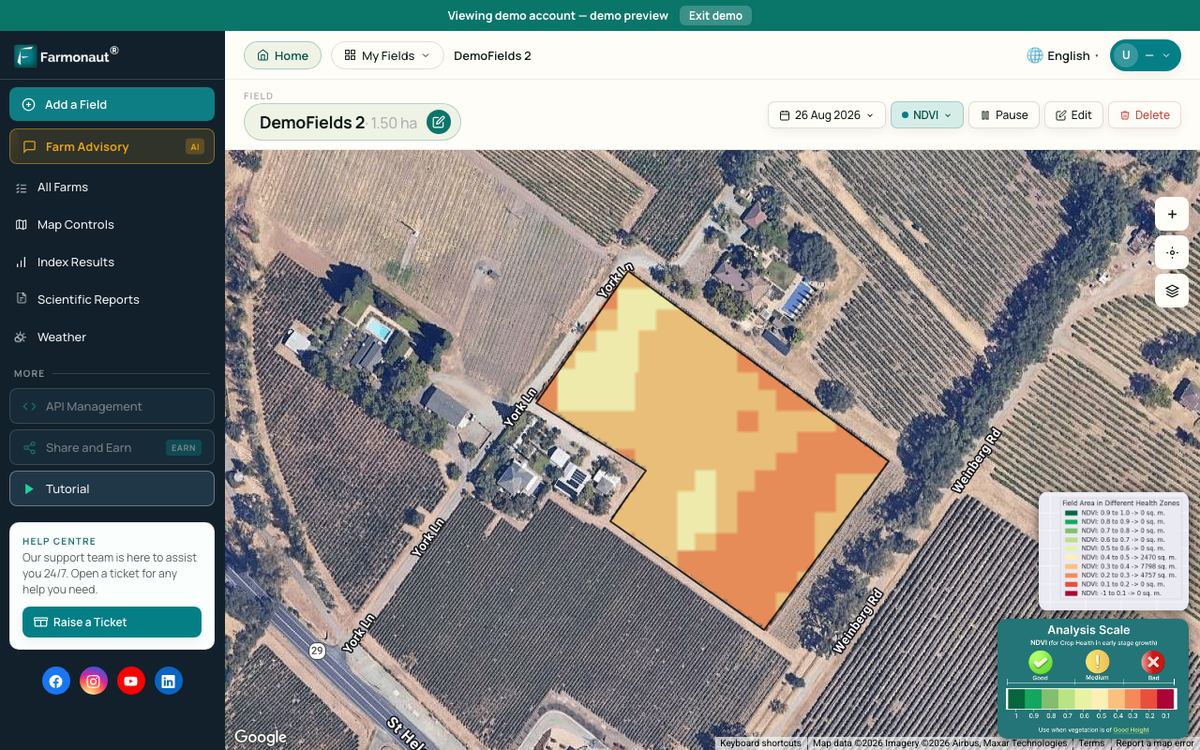
Good records help with both. Field maps, yields and practice records support a loan officer’s review and an NRCS or grant report. Some farms use satellite crop maps, for example from the Farmonaut Satellite + AI Farm Monitoring System, to keep a dated record of field condition through the season.
How we checked the numbers
We took loan rates from the FSA table effective 1 October 2026 and the July 2026 FSA release. Loan limits come from FSA handbook 1-FLP (amendment of 21 September 2026), the FSA loan information chart and FSA fact sheets. Proposed limits come from the Congressional Research Service report on the 2026 House and Senate bills. Grant figures come from NRCS program pages, the CRS report for EQIP and CSP funding under current law, and the USDA Rural Development VAPG briefing. Lending totals are from the American Farm Bureau Federation’s review of FSA data for FY2025. We removed funding figures from the older version of this page that we could not trace to a source.
FAQ
What is the interest rate on a USDA farm loan right now?
From 1 October 2026, FSA direct rates are 5.375% for operating loans, 6.250% for farm ownership loans, 2.250% for down payment loans, 4.250% for joint financing and 3.750% for emergency loans. Rates are reset monthly, and guaranteed loan rates are set by your lender under an FSA cap.
How much can I borrow from FSA?
Up to $400,000 on a direct operating loan, $600,000 on a direct farm ownership loan, $50,000 on each type of microloan and $500,000 on an emergency loan. Guaranteed loans go up to $2,558,000 in FY2027. Farm bills in Congress would raise these limits, but those changes are not law yet.
Can I get a USDA grant to buy a farm?
Not usually. USDA grants pay for projects such as conservation practices, value-added products or research, not for buying land. For land, look at FSA farm ownership loans, the down payment loan for beginning and veteran farmers, or ownership microloans.
Do I need farm experience for an FSA loan?
Yes, some experience, training or education is needed. Operating microloans are the most flexible on this. Current law sets a three-year experience requirement, and a House bill would cut it to two years. Ask your local office how it applies to you.
Are there USDA grants for greenhouses?
EQIP can pay part of the cost of a high tunnel on a farm, and VAPG can fund value-added projects. The urban agriculture grant program had no new round announced as of October 2026. State and nonprofit programs may also help.
Related pages on our site: satellite data for crop loans and insurance, product traceability, carbon footprinting, large-scale farm management app, fleet management, satellite and weather API docs and the Farmonaut web app.
Farmonaut crop monitoring
Keep a season-long record of your fields
Draw your fields once and Farmonaut shows satellite vegetation maps for them through the season, on web, Android or iOS.
Keep reading
 Farm guideAverage USDA Loan Interest Rate: Current USDA RD Rates Explained
 Farm guideAg Loan Requirements: 7 USDA RD Loan Criteria
 Farm guideRanch Loans & Beginning Rancher Loans: Ranch System Tips
Sources
- USDA Farm Service Agency, Current FSA Loan Interest Rates (effective 1 October 2026): fsa.usda.gov
- USDA FSA, USDA announces July 2026 lending rates for agricultural producers (July 2026): fsa.usda.gov
- USDA FSA, Handbook 1-FLP (Rev. 1) Amendment 309, loan limits for FY2027 (21 September 2026): fsa.usda.gov
- USDA FSA, Handbook 1-FLP, FY2026 loan limits (25 September 2025): fsa.usda.gov
- USDA FSA, Farm Loan Programs information chart (October 2025): fsa.usda.gov
- USDA FSA, Guaranteed loans fact sheet (October 2023): fsa.usda.gov
- USDA FSA, Farm Loans for Beginning Farmers and Ranchers fact sheet (2026): fsa.usda.gov
- USDA FSA, Farm Operating Loans: fsa.usda.gov
- USDA FSA, Farm Ownership Loans: fsa.usda.gov
- USDA FSA, Guaranteed Farm Loans: fsa.usda.gov
- USDA FSA, Operating Microloan: fsa.usda.gov
- farmers.gov, Loan Assistance Tool: farmers.gov
- Congressional Research Service, R48918, The 2026 Farm Bill: Comparison of the House and Senate Bills with Current Law (2026): everycrsreport.com
- American Farm Bureau Federation, Financing the Farm: A Look at USDA Farm Loan Programs (2026): fb.org
- American Farm Bureau Federation, One Big Beautiful Bill Act: final agricultural provisions (2025): fb.org
- Fertilizer Daily, Senate farm bill markup fails 10-11 in committee (15 September 2026): fertilizerdaily.com
- AgWeb, Farm Bill clears Senate Ag Committee with McConnell’s vote (2026): agweb.com
- USDA NRCS, Environmental Quality Incentives Program (EQIP): nrcs.usda.gov
- USDA NRCS, Conservation Stewardship Program (CSP): nrcs.usda.gov
- USDA Rural Development, Value-Added Producer Grant FY2026 briefing (farmers.gov, 2026): farmers.gov
- SARE, Grants: sare.org
- DTN, Cutting local food programs (17 March 2025): dtnpf.com
- Ohio State University Extension, USDA announces grants and technical assistance funding for urban agriculture (13 January 2025): urban-extension.cfaes.ohio-state.edu
- Ambrook Research, Urban agriculture in peril (2025): ambrook.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 ZOL Zimbabwe
 Innomick
 Juligerm
 AdBio
 MISE Maroc
 Drift-Sense
 NWNS
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 Croptimum
 DnCubed
 Field Capacity
 Indosistim Teknologi
 Liquify Digital

 Licence holder · Niger · Gold
 Licence holder · Nigeria · Gold + lithium










