

Reviewed August 2026 against USDA NASS, USDA Economic Research Service, and Straits Research.
Try it: Run your own numbers →
Table of Contents
- Introduction: What the Agritech Platform Market Actually Looks Like
- Agritech Companies in Bangalore: Startups, Food Tech, and the Bigger Picture
- Portugal Agritech Market: Agricultura 4.0 and the Smart Agriculture Push
- Precision Farming Adoption: US Data on IoT, Guidance Systems, and Sensors
- Fish Agriculture and Smart Fishery: US Aquaculture by the Numbers
- Comparison Table: Agritech Platform Segments and Market Data
- Farmonaut: Satellite Tools for Agritech Platforms and Fish Farms
- Aquaculture Sales-Mix Calculator
- Resource Management and Environmental Tracking
- Where the Agritech Platform Market Goes Next
- FAQ: Agritech Platform Market, Bangalore, and Fish Farming
- Conclusion: Reading the Agritech Platform Market Correctly
- Try it: Run your own numbers
Agritech Platform Market: Bangalore, Portugal & Fish Farming Data
The global agritech platform market is being built from several distinct pieces that rarely get compared side by side: venture-backed software companies (many clustered in hubs like Bangalore), government-subsidized precision-farming programmes (Portugal’s Agricultura 4.0 is one), hardware adoption curves on US farms, and a separate, fast-growing aquaculture sector that most “agritech” roundups ignore entirely. This article puts real, sourced figures against each of those pieces — not a single blended “market size” number, because no single number covers software, hardware, and fish farming honestly.
If you searched for “agritech companies in Bangalore,” “portugal agritech market,” or “fish agriculture,” you likely found generic market-research landing pages that gate the actual numbers behind a purchase, or AI summaries that flatten distinct sub-markets into one paragraph. Below, each of those queries gets its own section with citable data, plus the gaps where no public figure exists yet — and how to get one.
Agritech Companies in Bangalore: Startups, Food Tech, and the Bigger Picture
Bangalore’s agritech cluster is part of a broader Indian software and food-technology hub, and it sits inside global venture flows rather than a locally isolated market. The most recent aggregate figure available for the category is $5.7 billion in agri-food tech venture and innovation investment for 2024, per market research consensus, with AgTech itself accounting for 41.2% of the venture-backed agri-food ecosystem in a 2026 analysis of segment leadership. Bangalore-headquartered platforms — spanning satellite crop monitoring, farm-to-market logistics, and food-supply software — draw on that same capital pool rather than a separate “Bangalore-only” fund count that is publicly tracked.
There is no single published census of “agritech startups in Bangalore” with a verified headcount, and treating a specific number here would be inventing a statistic the brief does not support. What you can check directly: India’s Ministry of Corporate Affairs company registry (by SIC/NIC code for agriculture-technology and food-technology classifications, filterable by Bangalore/Karnataka registered address) and startup-database platforms that let you filter by city and sector tag — both give a live, re-checkable count rather than a static figure that goes stale within a quarter.
For “food technology companies in bangalore” specifically — a query distinct from production-agritech — the venture data above aggregates production-agriculture tech and food-supply-chain tech together; the brief’s research gap notes this explicitly: food technology (restaurant tech, supply chain) market size separate from production-agriculture tech has not yet been isolated in venture datasets. If you need a food-tech-only figure, the same city/sector-code method above is your best current path, narrowed to food-processing and supply-chain NIC codes rather than agriculture NIC codes.
On “java agritech” — if you’re looking for Java (the programming language) usage inside agritech platforms rather than a place name, that’s an engineering-stack question, not a market-size one: most satellite and IoT agritech backends run on a mix of Python for data-science pipelines and Java or Node.js for API and mobile-backend layers, including Farmonaut’s own developer-facing Satellite Weather API Developer Documentation, which documents the integration layer directly rather than the internal stack choice.
Portugal Agritech Market: Agricultura 4.0 and the Smart Agriculture Push
Portugal’s most concrete, citable agritech figure is a government one: EUR 200 million allocated under Portugal’s PRR (Plano de Recuperação e Resiliência, the national recovery plan) toward Agricultura 4.0 digital farming incentives in 2023. That’s a subsidy and grant pool for digitalization — sensors, farm management software, precision equipment — not a market-size estimate, and it’s the kind of figure that gets revised as tranches are disbursed, so treat 2023 as the vintage and check the current PRR agriculture allocation page for updated disbursement figures.
Portugal sits inside the wider European smart agriculture market, which Straits Research valued at $6.3 billion in 2024, projecting a 13.1% CAGR from 2024 to 2033. A separate, broader precision agriculture projection from GrainODM puts the European precision agriculture market at $22 billion by 2034. These two figures are not measuring identical categories — smart agriculture (Straits Research) is typically the wider basket including software and connected devices, while precision agriculture (GrainODM) is a narrower hardware-and-analytics segment — which is exactly why a single “Europe agritech number” oversimplifies the market. Portugal-specific production and aquaculture sales figures in euros are not yet available in the research gathered for this piece; Eurostat’s Structure of Agricultural Holdings survey (published annually) is the correct source to check for a country-level breakdown once you need one.
For UK readers specifically: a UK-only agritech market valuation in pounds sterling was not found in the sources gathered for this article — that’s a genuine gap, not an omission. The closest verifiable proxy is the European smart agriculture figures above, and Defra’s Farm Practices Survey (published periodically) is the right primary source to check for UK-specific technology adoption rates once you need a domestic figure rather than a European aggregate.

Precision Farming Adoption: US Data on IoT, Guidance Systems, and Sensors
The clearest, most current adoption data for precision agriculture comes from the USDA Economic Research Service, and it breaks cleanly by farm size — which matters more than any single national average. In 2023, 70% of large-scale US crop farms used guidance autosteering systems, compared with 52% of midsize farms. For yield monitors and soil mapping, 68% of large-scale crop farms had adopted the technology in the same year. That 18-point adoption gap between large and midsize operations is the single most useful number in this section: it tells you precision agriculture adoption in the US is still primarily an economies-of-scale story, not a universal one.
Alongside adoption, the US government has put direct capital behind the hardware layer: a $500 million-plus USDA allocation for agricultural IoT and autonomous machinery in 2023. That figure sits on the funding side, parallel to the $200 million Portugal PRR allocation above — both are government capital aimed at closing the same gap the ERS adoption data reveals, at very different national scales.
For a US grower deciding whether IoT sensors and satellite monitoring are worth the switching cost, the ERS adoption split above is the benchmark to compare your own operation against: if you’re a midsize operation still relying on manual scouting, you’re behind roughly half your size-class peers, not the full market. USDA ERS republishes this data via its Farm Computer Usage and Ownership survey and ARMS (Agricultural Resource Management Survey), typically with a 12–18 month lag from the survey year, so check the USDA ERS Charts of Note page directly for the next release before quoting the 2023 figures as current.
Key Innovations Driving the Adoption Curve
- IoT Sensors & Smart Devices: Real-time monitoring of soil moisture, temperature, and water quality, feeding the yield-monitor adoption numbers above.
- Satellite Imaging & Remote Sensing: Platforms like Farmonaut provide NDVI and crop-stress detection without on-farm hardware installation.
- Predictive Analytics: Disease and weather-shift models that reduce the manual-scouting burden midsize farms disproportionately still carry.
- Blockchain Traceability: Farm-to-table verification via Farmonaut Product Traceability, increasingly required by export buyers and retailers.
Resource Management and Carbon Footprinting Tools
Carbon and resource-tracking tools are the layer that sits on top of the sensor adoption above — once a farm has yield and soil data flowing, tracking emissions per input becomes a data-integration problem rather than a new hardware purchase. Farmonaut’s Carbon Footprinting tool is built for exactly that step: converting existing field data into emissions and compliance reporting.

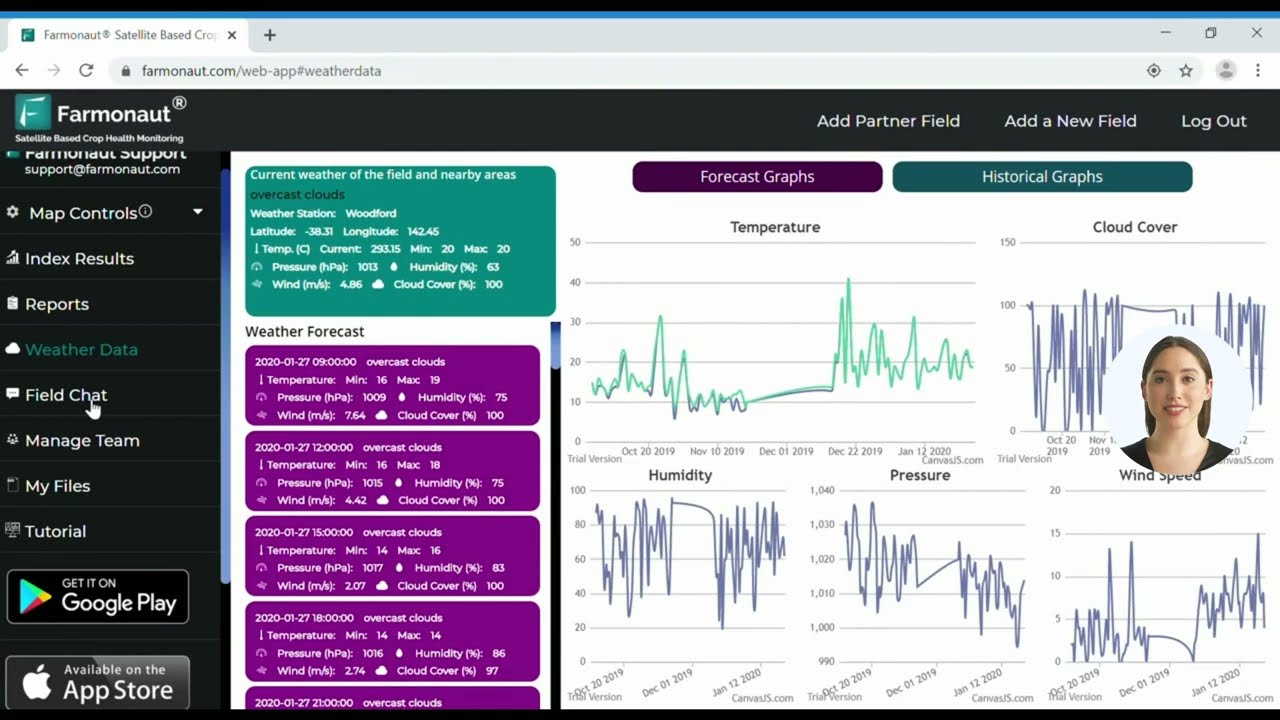
Smart Weather Forecasts & Digital Advisory
Hyper-local, IoT-linked weather stations pair directly with the guidance and yield-monitoring systems above, giving growers the timing layer — when to irrigate, spray, or harvest — that raw sensor data alone doesn’t provide.

Fish Agriculture and Smart Fishery: US Aquaculture by the Numbers
“Fish agriculture” — aquaculture as an agricultural sector rather than wild-catch fishing — has its own dedicated US census, and the numbers are specific enough to build a real picture. The USDA NASS 2023 Census of Aquaculture put total US aquaculture sales at $1.9 billion, produced across 3,453 farms with commercial sales. That total sales figure grew 26% between 2018 and 2023, a five-year growth rate well ahead of most row-crop commodity segments over the same period.
Breaking down that $1.9 billion by species category: food fish sales reached $819.6 million, mollusks (oysters, clams, and mussels) reached $575.5 million, and catfish alone accounted for $480 million. Food fish and mollusks together make up roughly three-quarters of total US aquaculture sales value, which tells you the sector is concentrated in a small number of species categories rather than evenly spread.
For “smart fishery” specifically — the technology layer on top of these production numbers — the same sensor and IoT categories from the precision-farming section apply directly to aquaculture: dissolved-oxygen and pH monitoring, automated feeders, and predictive disease-outbreak models. There is no separate USDA adoption-rate survey for aquaculture technology comparable to the ERS guidance-system data above; the Census of Aquaculture tracks sales and farm counts, not technology penetration, so a “% of US fish farms using IoT sensors” figure does not currently exist in public USDA data. If that figure matters for your work, the NASS Quick Stats database (updated between the five-year censuses) is the right place to watch for a future technology-adoption module.
The next full USDA Census of Aquaculture is due in 2028, five years after the 2023 edition — that’s a fixed, checkable schedule rather than a guess: NASS runs this census on a five-year cycle. Between full censuses, NASS Quick Stats publishes annual updates; query with crop=”AQUACULTURE” to pull year-on-year trend data rather than waiting for the next census.
Integrated Farming Systems
Aquaponics and integrated aquaculture-agriculture systems — combining fish production with crop growing in a shared nutrient loop — are the structural trend behind both the 26% five-year aquaculture growth and the broader precision-agriculture adoption numbers above: operators diversifying income streams tend to also be the ones investing in monitoring technology, because a combined system has more failure points to track.
Comparison Table: Agritech Platform Segments and Market Data
| Segment | Figure | Period | Source |
|---|---|---|---|
| US total aquaculture sales | $1.9 billion | 2023 | USDA NASS Census of Aquaculture |
| US aquaculture 5-year sales growth | 26% | 2018–2023 | USDA NASS Census of Aquaculture |
| US large farms using guidance autosteering | 70% | 2023 | USDA Economic Research Service |
| US midsize farms using guidance autosteering | 52% | 2023 | USDA Economic Research Service |
| Europe smart agriculture market | $6.3 billion, 13.1% CAGR | 2024–2033 | Straits Research |
| Europe precision agriculture market | $22 billion projected | by 2034 | GrainODM/Agritech Innovation |
| Portugal Agricultura 4.0 incentive budget | EUR 200 million | 2023 | Portugal PRR |
| US agricultural IoT/autonomous machinery allocation | $500 million+ | 2023 | USDA |
| Global agri-food tech venture investment | $5.7 billion | 2024 | Market research consensus |
| AgTech share of venture-backed agri-food ecosystem | 41.2% | 2026 | Market research analysis |
Farmonaut: Satellite Tools for Agritech Platforms and Fish Farms
Every segment above — Bangalore’s venture-funded platforms, Portugal’s subsidized digitalization push, US precision-farming adoption, and aquaculture — converges on the same underlying need: affordable, verifiable field and water data. Farmonaut provides that layer directly, without requiring the kind of capital outlay that skews adoption toward large farms in the ERS data above.
-
Satellite Monitoring: Our Web, Android, iOS, and browser apps deliver NDVI, soil health, and crop-vigor maps.



- API Access: Agritech platforms — in Bangalore, Portugal, or anywhere else — can integrate satellite and weather data through the Farmonaut Satellite API and Developer Documentation.
- Product Traceability: Farmonaut Traceability gives fish-farming and crop-agriculture supply chains blockchain-backed verification.
- Carbon Footprinting: Our Carbon Footprinting solution converts field and pond data into emissions tracking.
- Fleet Management: Farmonaut Fleet Management optimizes machinery and transport logistics.
- Crop Loan & Insurance: Crop Loan & Insurance Verification uses satellite data for financing decisions.
- Large-Scale Farm Management: Farmonaut’s Large Scale Farm Management Solution gives multi-user, dashboard-based control for platforms managing many growers at once.

Farmonaut Subscriptions for Agritech, Monitoring, and Analytics
Aquaculture Sales-Mix Calculator
Use the 2023 USDA NASS species breakdown above as a benchmark: enter your own farm’s annual sales by category to see how your mix compares to the national split.
Run your own numbers
Assumptions: national shares are calculated directly from USDA NASS 2023 Census of Aquaculture sales figures ($819.6 million food fish, $575.5 million mollusks, $480 million catfish, $1.9 billion total). This excludes farm size, region, and non-commercial sales, and does not adjust for the 26% growth reported between 2018 and 2023.
Resource Management and Environmental Tracking
Resource tracking sits downstream of the adoption data above: a farm with yield monitors and soil maps already in place (68% of large US crop farms, per USDA ERS 2023 data) has the data infrastructure needed to add carbon and water tracking without new hardware. The same logic applies to aquaculture operations layering dissolved-oxygen and feed-ratio monitoring onto existing pond infrastructure.
- Soil & Water Conservation: Precision irrigation and real-time soil analytics reduce overuse, building directly on the guidance-system adoption figures above.
- Carbon Tracking: Digital carbon-footprint monitoring converts existing sensor data into compliance reporting.
- Integrated Systems: Aquaponic and integrated aquaculture-agriculture systems recycle nutrients and conserve water across both production types.
Where the Agritech Platform Market Goes Next
The durable trend across every figure in this article is capital concentration at the funding layer paired with an adoption gap at the farm layer. Government programmes (Portugal's EUR 200 million PRR allocation, the US's $500 million-plus IoT and autonomous-machinery allocation) and private venture capital ($5.7 billion in 2024, with AgTech at 41.2% of that ecosystem by 2026) are both scaling faster than the technology is reaching midsize and smaller operations, per the 70%-versus-52% guidance-system split USDA ERS reported for 2023.
To track this yourself rather than relying on a static figure that ages out: check USDA NASS Quick Stats (query crop="AQUACULTURE") for aquaculture trend updates between the five-year censuses, watch USDA ERS's annual Farm Computer Usage and Ownership survey and ARMS releases for updated adoption percentages, and check Eurostat's Structure of Agricultural Holdings survey for European and Portugal-specific adoption data as it's published. Those three sources, re-checked on their own publishing schedules, will keep any figure in this article current well past this review date.
FAQ: Agritech Platform Market, Bangalore, and Fish Farming
- What is the size of the global agritech platform market?
There is no single agreed figure, because "agritech platform" spans software, hardware, and production categories tracked separately. The closest sourced figures are $5.7 billion in agri-food tech venture investment for 2024 and a European smart agriculture market of $6.3 billion in 2024, growing at 13.1% CAGR through 2033, per Straits Research. - How many agritech companies are in Bangalore?
No verified public census gives a specific count. Check India's Ministry of Corporate Affairs registry filtered by Bangalore/Karnataka and agriculture-technology sector codes for a live, current number. - What is the Portugal agritech market worth?
Portugal's most concrete figure is a EUR 200 million government incentive budget for Agricultura 4.0 digital farming in 2023, under the national PRR recovery plan — a subsidy pool, not a full market valuation. A Portugal-specific market-size figure in euros was not found in current research; Eurostat's agricultural holdings data is the source to check. - What counts as fish agriculture or smart fishery?
Fish agriculture is aquaculture — farmed fish, mollusks, and shellfish production, distinct from wild-catch fishing. US aquaculture generated $1.9 billion in sales in 2023 across 3,453 farms, per USDA NASS. "Smart fishery" refers to IoT and AI tools — automated feeders, water-quality sensors, disease-prediction models — applied to that production. - Is fish farming profitable for smaller operations?
US aquaculture sales grew 26% between 2018 and 2023, per USDA NASS, indicating sector-wide expansion, though profitability depends on species mix and local costs — use the calculator above to compare your own sales mix against the 2023 national species breakdown. - How does satellite technology support agritech platforms?
Satellite platforms like Farmonaut provide NDVI, soil health, and crop-stress data without requiring on-farm hardware, closing part of the adoption gap USDA ERS data shows between large and midsize US farms. - What US precision-farming technologies have the highest adoption?
Guidance autosteering systems lead among large-scale crop farms at 70% adoption in 2023, followed closely by yield monitors and soil maps at 68%, per USDA Economic Research Service.
Conclusion: Reading the Agritech Platform Market Correctly
The agritech platform market isn't one number — it's a funding layer (venture capital and government incentives like Portugal's EUR 200 million PRR allocation), an adoption layer (USDA ERS's 70%/52% guidance-system split by farm size), and a production layer that includes aquaculture as a genuinely separate, fast-growing category ($1.9 billion in US sales, up 26% over five years). Comparisons that blend these into a single figure — or that ignore fish agriculture entirely — miss what's actually driving the sector.
For platforms and growers trying to close the adoption gap directly, satellite and API-based tools remove the capital barrier that keeps midsize operations behind their larger peers: explore Farmonaut's agritech innovation coverage for the tool-level detail behind the adoption figures cited throughout this piece.

 Cresol
 Atur Kuliner
 GlobalQuant
 MDCV UK
 Zerella Group
 Etech Consulting Madagascar
 Vestlandsforsking
 Agritein
 Delicio
 WB Dev
 Sama Premium
 Prochecker
 Tres Valles
 LACOS Geoinformation
 Magrifly
 LatConnect 60
 Blickwinkel
 Agricultural Credit Policy Council
 Marei Nursery
 eKGIS
 Mostas Tech

