

Rare earths · Company comparison
Rare Earth Mining Investment: 8 Companies Compared
Rare earth mining investment means producers, developers or funds. China mined about 69% of 2025 supply (USGS). Compare 8 listed companies by stage and dated filings, then test a price floor.
Key takeaways
- China mined an estimated 270,000 of 390,000 tonnes of rare earth oxide in 2025, about 69% (USGS, February 2026).
- MP Materials has a US$110/kg NdPr price floor from the US government; Benchmark put ex-China NdPr at US$95/kg on 21 August 2026.
- Lynas reported A$288.9 million quarterly revenue in the June 2026 quarter, its highest since the June 2022 quarter, but NdPr output fell to 1,857 tonnes.
- Arafura and Iluka are building plants in Australia; Hastings and American Rare Earths are still at study stage.
- The IEA says refining and magnet capacity outside China lags mined supply, so projects need more than a deposit.
In this article
- Rare earth mining investment: what you can actually buy
- How we chose the companies in this guide
- Supply numbers behind the investment case
- Prices and price floors: what drives the revenue line
- Rare earth mining companies compared (facts from company filings)
- Rare earth funds and ETFs
- Policy and China's export controls
- Risks and due diligence checklist
- Where satellite data fits into project research
- Frequently asked questions
Rare earth mining investment: what you can actually buy
A rare earth mining investment is exposure to companies that dig, separate or turn rare earth elements (REEs) into magnets, or to a fund that holds several of them. In 2025 about 390,000 tonnes of rare earth oxide were mined worldwide, and China mined an estimated 270,000 tonnes of that, roughly 69% (USGS Mineral Commodity Summaries, February 2026). The investable question is who is building supply outside China, how that supply is paid for, and where the project risks sit. This page lays out those facts so you can read each company’s own filings with better questions.
This is a fact sheet, not a recommendation. It names no company to buy or sell, it gives no price targets, and every figure carries a date and a source.
Four ways to get exposure
- Producers already sell rare earth products, for example MP Materials in California and Lynas Rare Earths in Western Australia and Malaysia.
- Developers hold a defined deposit and are raising money or building, for example Arafura Rare Earths (Nolans, Northern Territory) and Hastings Technology Metals (Yangibana, Western Australia).
- Explorers hold ground and drill results but no study that proves a profit. They carry the highest failure rate.
- Funds spread the risk across a basket of miners, but their fees are higher than broad market funds and the baskets are often mixed with lithium and other metals.
If you are new to the elements themselves, start with our guides on what a rare earth metal is and the rare earth metal definition and critical minerals list. For a wider view of mining as an asset class, see our overview of mining investments by metal.
How we chose the companies in this guide
We included a company only if its own filing, a stock-exchange announcement or a regulator page from 2026 confirms the facts we quote. The test was simple:
- It is listed on a major exchange, and we give the exchange and ticker from the company’s own release.
- It has a named rare earth asset with a stated status: producing, under construction, or at study stage.
- The facts are about the business (output, capital, offtake, approvals), not about its share price.
The list is not every rare earth company. It leaves out many explorers and companies whose 2026 filings we did not read. For a US-only list, see our list of USA rare earth mining companies.
Supply numbers behind the investment case
Rare earths are not rare in the crust, but minable concentrations are less common than for most other mineral commodities (USGS, 2026). The USGS estimates 2025 world mine production at 390,000 tonnes of rare earth oxide equivalent and world reserves above 75 million tonnes, with China holding 44 million tonnes of that. The United States produced an estimated 51,000 tonnes of oxide in mineral concentrates, valued at US$240 million, almost all from one mine, Mountain Pass in California (USGS, 2026). Our guide to the Mountain Pass rare earth mine covers that deposit in more detail.
Chart
Mine production of rare earth oxide, 2025 (estimate)
Tonnes of rare earth oxide equivalent, selected producers, smaller producers not shown
Mining is only the first step. The same USGS summary reports that US net import reliance for rare earth compounds and metals was an estimated 67% of apparent consumption in 2025, and that US imports of compounds and metals rose 169% in 2025 while their value stayed near US$165 million. The mined rock still has to be split into separate oxides, turned into metal, alloyed and made into magnets, and much of that work is done in China.
The International Energy Agency (IEA) makes the same point from the project side. In its 2026 outlook it estimates that existing and announced rare earth refining capacity in diversified regions equals about two thirds of expected mined supply by 2035, while planned magnet production is only about one third. It also reports that capital costs for refining projects are 20% to over 150% higher outside the dominant supplier, and operating costs about 50% higher (IEA, Global Critical Minerals Outlook, 2026). For investors this explains why governments are paying for refining and magnets, not only for mines.
Prices and price floors: what drives the revenue line
Most of the value in a rare earth deposit sits in four magnet elements: neodymium, praseodymium, dysprosium and terbium. Neodymium and praseodymium are usually sold together as NdPr oxide. Our explainer on the neodymium rare earth element covers its uses, and the price page rare earth prices and NdPr metal price shifts follows the market.
Chart
US average price of NdPr and neodymium oxide
US$ per kilogram, annual average
The USGS average annual US price for NdPr oxide (99% minimum) was US$92 per kilogram in 2021, US$124 in 2022, US$75 in 2023, US$55 in 2024 and an estimated US$69 in 2025. That swing of more than 50% between years is why many developers look for long-term price protection before they raise construction money.
The US$110 per kilogram floor
In July 2025 the US Department of Defense (now styled the Department of War) agreed to a 10-year price floor of US$110 per kilogram for MP Materials’ NdPr products, and to buy US$400 million of newly issued preferred stock that gave it about a 15% stake, according to Argus Media. MP’s own results show the mechanism: it receives cash for the gap between US$110 per kilogram and a quarterly benchmark price on the NdPr it produces, and the arrangement started on 1 October 2025 (MP Materials, 26 February 2026).
The floor matters because the market price has been below it. Benchmark Mineral Intelligence reported on 21 August 2026 that NdPr oxide delivered to Europe and North America had fallen to US$95,000 per tonne (US$95 per kilogram), down 7.3% over 6 to 20 August, and that the Chinese domestic price was higher at RMB 721,500 per tonne (about US$107,500) (Benchmark, 21 August 2026).
In the second quarter of 2026, MP recorded US$17.6 million of income from the price protection agreement on top of US$108.5 million of revenue (MP Materials, 6 August 2026). The calculator below lets you test what a floor is worth under your own price and volume inputs.
Calculator
What is a price floor worth on your NdPr volume?
Enter your own volume, market price and floor to see the top-up and total revenue.
- Revenue at market price (US$): $190,000,000
- Revenue including floor top-up (US$): $220,000,000
Example values only, not a forecast. The US$110/kg floor is the level in the MP Materials agreement (MP Materials, 26 February 2026); change it to test other terms. Prices are inputs: use today’s price.
Rare earth mining companies compared (facts from company filings)
The table states what each company’s own documents say. It is ordered by stage, from producing to study, and it is not a ranking of quality or value.
Chart
Lynas average selling price, all rare earth products
A$ per kilogram, by quarter
| Company and listing | Main asset | Stage | Dated facts |
|---|---|---|---|
| MP Materials (NYSE: MP) | Mountain Pass, California; Independence magnet plant, Texas | Producing | 2025 NdPr oxide output 2,599 t; Q2 2026 NdPr output 840 t and sales 1,006 t (company results) |
| Lynas Rare Earths (ASX: LYC) | Mt Weld, Western Australia; Kalgoorlie; Kuantan, Malaysia | Producing | June 2026 quarter: revenue A$288.9 million, NdPr 1,857 t, average price A$98.2/kg (quarterly report, 22 July 2026) |
| Energy Fuels (NYSE American: UUUU; TSX: EFR) | White Mesa Mill, Utah; uranium and rare earths | Producing, expanding | Completed purchase of Australian Strategic Materials (28 August 2026); heavy rare earth plant under construction |
| Iluka Resources (ASX: ILU) | Eneabba refinery, Western Australia | Under construction | Commissioning planned for 2027; A$1.65 billion government loan; A$1,101 million spent to 30 June 2026 |
| Arafura Rare Earths (ASX: ARU) | Nolans, Northern Territory | Under construction | Investment decision May 2026; ground broken 8 October 2026 |
| Neo Performance Materials (TSX: NEO) | Magnet and materials plants; Narva, Estonia | Producing, expanding | Building a sintered magnet plant in Estonia (Q2 2026 filing) |
| Hastings Technology Metals (ASX: HAS) | Yangibana, Western Australia (40% interest) | Study, permitted | Updated feasibility study 13 July 2026: initial capex A$333.4 million, pre-tax NPV A$649 million (100% project basis; Hastings holds 40%) |
| American Rare Earths (ASX: ARR) | Halleck Creek, Wyoming | Scoping study | Scoping study 30 September 2026: about 2,500 t NdPr oxide a year planned, no ore reserves declared |
MP Materials (NYSE: MP)
Why it is listed: Reading how a government price floor changes a miner’s accounts. MP produced a record 2,599 tonnes of NdPr oxide in 2025, up 101% on 2024, and 50,692 tonnes of rare earth oxide in concentrate (MP Materials, 26 February 2026). In the second quarter of 2026 it produced 840 tonnes of NdPr, sold 1,006 tonnes, and reported a net loss of US$20.3 million, an improvement of US$10.6 million on a year earlier. In its February 2026 results it said it had been awarded a US$200 million incentive package for a second magnet plant (the 10X facility) in Northlake, Texas.
Supportive facts: a producing mine, a price floor and a defence customer. Facts to weigh: the company was still loss-making in the quarter, and the magnet business is at an early stage of qualification with customers.
Lynas Rare Earths (ASX: LYC)
Why it is listed: Reading how a producer outside China sells both light and heavy rare earths. In the June 2026 quarter Lynas reported gross sales revenue of A$288.9 million, a 70% rise on the same quarter a year earlier, total rare earth oxide output of 3,481 tonnes, and cash of A$1,209.1 million (Lynas quarterly report, 22 July 2026). NdPr output fell to 1,857 tonnes from 2,080 tonnes a year earlier because of water-recycling and concentrate-quality problems at Mt Weld. First samarium oxide came in March 2026.
On 1 October 2026 Lynas and Meteoric Resources signed a binding agreement for Lynas to buy Meteoric, owner of the Caldeira ionic clay project in Brazil, in a deal Lynas values at A$968 million (ASX announcement, 1 October 2026). It is a proposed scheme of arrangement and still needs approvals. Malaysia renewed the Lynas operating licence for 10 years in March 2026 (Reuters via Kitco, 2 March 2026).
Supportive facts: the highest quarterly revenue since 2022, a record average selling price and a large cash balance. Facts to weigh: NdPr output fell in the quarter, an interim chief executive was in place from 1 July 2026, and the heavy rare earth plant in Malaysia is now budgeted at about A$294 million, up from about A$180 million.
Energy Fuels (NYSE American: UUUU; TSX: EFR)
Why it is listed: Reading how a uranium miner is moving into rare earth metals and magnets. Energy Fuels completed its acquisition of Australian Strategic Materials on 28 August 2026, adding rare earth metal and alloy production (Investing News Network, 28 August 2026). In its second quarter report of 5 August 2026 it also said it had agreed to buy the magnet maker Vacuumschmelze (VAC) for about US$1.9 billion in cash and stock, and that construction of a heavy rare earth plant at its White Mesa Mill in Utah had begun (Energy Fuels, 5 August 2026).
Supportive facts: an existing mill, a uranium business and a move down the chain to magnets. Facts to weigh: large acquisitions add integration and funding risk, and the company reported a net loss for the quarter driven mainly by deal costs.
Iluka Resources (ASX: ILU)
Why it is listed: Reading a government-financed refinery build. Iluka is building the Eneabba refinery in Western Australia, which it describes as Australia’s first fully integrated refinery for separated rare earth oxides. Its half-year report shows A$1,101 million of capital spent by 30 June 2026, commissioning in 2027, access to the full A$1.65 billion non-recourse government loan, and an offtake agreement that starts in 2028 for an initial four years with minimum prices agreed between the parties (Iluka, 28 July 2026).
Supportive facts: funded construction and a feedstock base in its own mineral sands. Facts to weigh: no refinery revenue until commissioning, which Iluka plans for 2027.
Arafura Rare Earths (ASX: ARU)
Why it is listed: Reading a new mine, plant and offtake package in one project. Arafura made a final investment decision on Nolans in May 2026, and the Australian government agreed to buy up to 500 tonnes of product a year (ABC News, 21 May 2026). Ground was broken on 8 October 2026, and the company says the build will take about three years (Australian Resources & Investment, 9 October 2026).
Supportive facts: a funded decision and named customers. Facts to weigh: first production is years away, and the company’s managing director describes the build as taking place in one of the most remote parts of Australia.
Neo Performance Materials, Hastings and American Rare Earths
Neo (TSX: NEO) makes bonded magnets through Magnequench and is building a sintered magnet plant at Narva, Estonia (Neo, second quarter 2026 report). Hastings (ASX: HAS) holds 40% of the Yangibana joint venture, managed by Wyloo with 60%. Its July 2026 study shows initial capital of A$333.4 million (100% project basis, pre-tax NPV A$649 million at an 8% discount rate), a 19-year life on a 20.93 million tonne ore reserve at 0.90% total rare earth oxide, and approvals in hand, but it does not state a final investment decision (Hastings, 13 July 2026). American Rare Earths (ASX: ARR) published a scoping study for the Cowboy State Mine at Halleck Creek on 30 September 2026 with an after-tax NPV of about US$1.07 billion at an 8% real discount rate (US$764 million at 10%) and initial capital of about US$900 million. The company states that a scoping study is not a feasibility study and that no ore reserves are declared (ASX announcement, 30 September 2026).
Rare earth funds and ETFs
Funds hold many miners in one ticker. A June 2026 guide from Motley Fool lists three US-listed funds: the VanEck Rare Earth and Strategic Metals ETF (REMX), the Sprott Rare Earths Ex-China ETF (REXC) and the Global X Rare Earth & Critical Materials ETF (EART). It gives REXC assets of US$72 million, an expense ratio of 0.65%, and top holdings of MP Materials (20.44%) and Lynas (18.81%) (Motley Fool, updated 13 June 2026). The same article warns that these funds charge more than broad market funds, can be small enough to risk closure, and hold cyclical companies, some of which are not yet consistently profitable.
Read each fund’s index rules and current holdings on the issuer’s site. Some baskets include lithium and other metals, so they are not pure rare earth exposure.
Policy and China’s export controls
China introduced export controls on seven heavy rare earth elements in April 2025 and widened them in October 2025. The wider measures were suspended for one year, until November 2026, after US-China trade talks (IEA, 2026). A law firm summary of the announcement says China’s Ministry of Commerce suspended six export-control announcements of 9 October 2025 for one year (Pillsbury). A suspension is not a repeal, so the rules can return at the end of the period.
Western governments now back supply with money: the US price floor and equity stake for MP, the Australian loan for Iluka’s refinery, and an Australian offtake for Arafura. These supports reduce price risk for the named projects, but they bring political risk, because terms can change with governments.
Risks and due diligence checklist
- Stage of the project. A scoping study, a pre-feasibility study and a feasibility study carry different weight. A scoping study cannot support ore reserves, as American Rare Earths states in its own announcement.
- Processing, not only the mine. Ask where the ore will be separated, who owns the plant, and whether the process route has been proved at scale.
- Heavy versus light. Heavy rare earths (dysprosium and terbium) are scarcer than NdPr and can sell at a different price path.
- Offtake and price terms. Look for named customers, volumes, start dates, and whether a minimum price exists, as Iluka and MP describe.
- Funding. A project with an investment decision but no full funding may need new shares or debt.
- Permits and waste. Rare earth ores often contain natural radioactive elements such as thorium. Malaysia’s 2026 Lynas licence terms on residue show how rules can change.
- Land and access. Check title, native title or community agreements, and road, power and water access.
- Single-asset risk. Many developers depend on one deposit and one plant.
Cost lines also matter. Equipment supply and haulage costs can move a capital budget, and our guide to mining equipment and machinery lists the main categories. For traceability of material through a supply chain, see our page on product traceability.
▶ What satellite exploration cannot do, and why those limits matter in mining due diligence. · 2:08
Where satellite data fits into project research
Before a drill hole, satellite imagery can show alteration patterns, structures, vegetation cover and access, which helps rank targets inside a licence area. It does not replace drilling or a resource estimate. Farmonaut offers satellite-based mineral detection for exploration targets, and our guide to rare earth deposits and how exploration works explains what to look for.
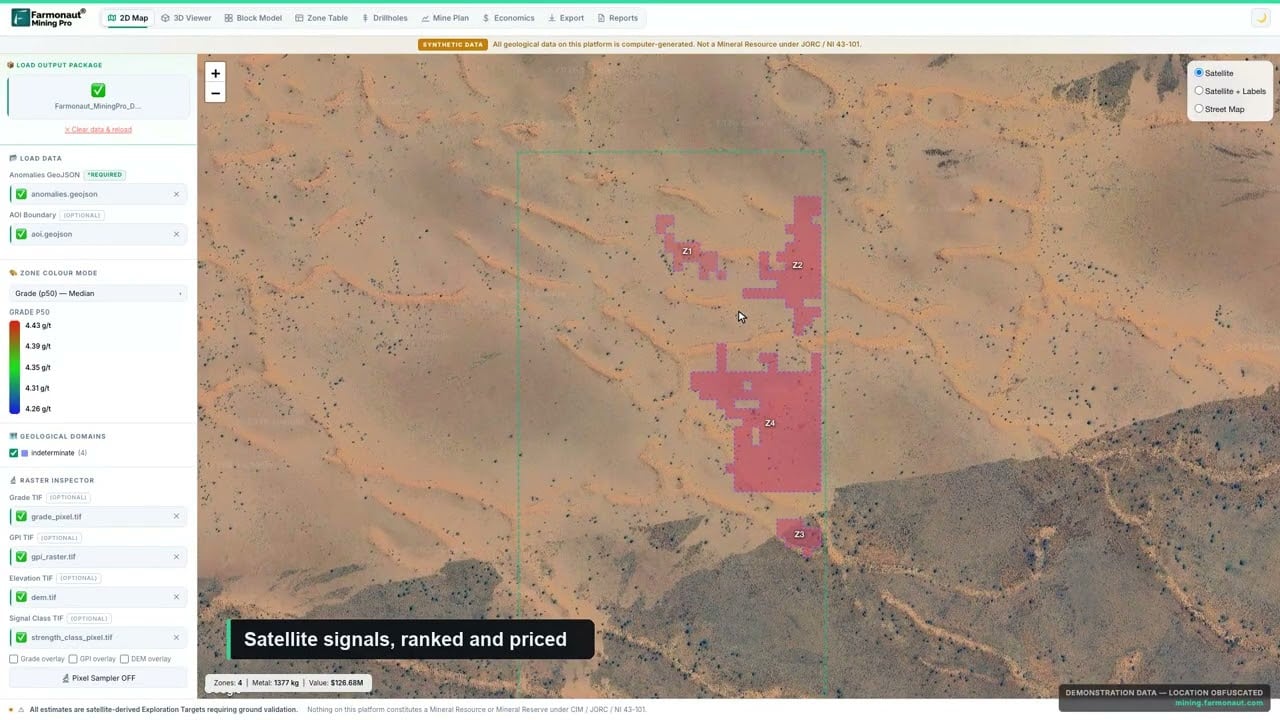
▶ A short look at Farmonaut Mining Pro, which turns a licence boundary into a geological and economic picture. · 4:56
If this topic matters to you, read Rare Earth Companies in Canada: 9 Compared by Stage next.
Frequently asked questions
What is the safest way to get exposure to rare earth miners?
No route is safe. Producers have operating and price risk, developers have funding and construction risk, and explorers have discovery risk. Funds spread the company risk but add fees and commodity swings. Match the choice to your own risk tolerance and take advice from a licensed adviser.
Which companies produce rare earths outside China?
MP Materials in the United States and Lynas in Australia and Malaysia are the two producers most often named, and Lynas describes itself as the only commercial producer of light and heavy rare earth oxides outside China in its October 2026 announcement. Energy Fuels also produces rare earth products at White Mesa Mill.
How much of the world’s rare earth supply comes from China?
The USGS estimates China mined 270,000 tonnes of the 390,000 tonnes of oxide produced worldwide in 2025, about 69%. The IEA estimates that refining capacity in diversified regions equals about two thirds of expected mined supply by 2035, and planned magnet production about one third.
What is an NdPr price floor?
It is a contract that guarantees a minimum price. In the MP Materials agreement the US government pays the gap between US$110 per kilogram and a benchmark price for NdPr products, for 10 years from October 2025.
Are rare earth ETFs a pure bet on rare earths?
Not always. Some funds hold lithium, cobalt and other strategic metals, and some hold Chinese companies. Read the index rules and the holdings list on the issuer’s site.
What is the difference between a scoping study and a feasibility study?
A scoping study is an early estimate with wide error margins. A feasibility study uses detailed engineering and can support an ore reserve. American Rare Earths states that its scoping study cannot support an ore reserve.
Why are heavy rare earths treated differently?
Dysprosium and terbium are used in high-temperature magnets and are less abundant than neodymium. Benchmark described heavy rare earths as genuinely scarce in August 2026, while NdPr outside China was oversupplied.
Do rare earth miners pay royalties?
Yes, in most jurisdictions. A royalty is a payment to the state or a private holder, set as a share of revenue or profit. Hastings reports its EBITDA after royalties, so rates matter for project economics.
Is rare earth mining radioactive?
Many ores contain thorium or uranium, so processing creates low-level radioactive residue that regulators control. Read the licence terms, such as the Malaysian conditions for Lynas.
How can I check a company’s claims?
Read the stock-exchange filings (ASX, SEC EDGAR, SEDAR+), check the study stage, and compare quoted figures with the USGS and IEA data used on this page. Not investment advice.
This page is for information only. It is not investment advice. It names no security to buy or sell. Check company filings and speak to a licensed adviser.
Farmonaut mining
Screen exploration ground from space
Farmonaut maps alteration and structure inside a licence area to help rank exploration targets before drilling.

Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026: Rare Earths (February 2026): pubs.usgs.gov
- IEA, Global Critical Minerals Outlook 2026, executive summary: iea.org
- Argus Media, US DoD to invest $400mn in MP Materials (July 2025): argusmedia.com
- MP Materials, fourth quarter and full year 2025 results (26 February 2026): mpmaterials.com
- Benchmark Mineral Intelligence, ex-China NdPr prices below the $110/kg floor (21 August 2026): source.benchmarkminerals.com
- MP Materials, second quarter 2026 results (6 August 2026): mpmaterials.com
- Lynas Rare Earths, quarterly report for the period ended 30 June 2026 (ASX, 22 July 2026): announcements.asx.com.au
- Lynas Rare Earths and Meteoric Resources, scheme announcement (ASX, 1 October 2026): announcements.asx.com.au
- Reuters via Kitco, Malaysia renews Lynas operating licence for 10 years (2 March 2026): kitco.com
- Investing News Network, Energy Fuels completes acquisition of Australian Strategic Materials (28 August 2026): investingnews.com
- Energy Fuels, Q2-2026 results (5 August 2026): investors.energyfuels.com
- Iluka Resources, half-year results and update (ASX, 28 July 2026): announcements.asx.com.au
- ABC News, Arafura Rare Earths mine green-lit (21 May 2026): abc.net.au
- Australian Resources & Investment, Nolans breaks ground (9 October 2026): australianresourcesandinvestment.com.au
- Neo Performance Materials, management’s discussion and analysis for Q2 2026: neomaterials.com
- Hastings Technology Metals, updated Yangibana Stage 1 DFS (ASX, 13 July 2026): bulletin.webull.com
- American Rare Earths, Cowboy State Mine scoping study (ASX, 30 September 2026): announcements.asx.com.au
- Motley Fool, rare earth ETFs (updated 13 June 2026): fool.com
- Pillsbury, China suspends export controls on certain critical minerals: pillsburylaw.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited











