

Reviewed August 2026 against USGS Mineral Commodity Summaries, Fastmarkets/Benchmark Mineral Intelligence spot price data, and Global X Funds ETF performance reporting.
Lithium Price 2025: Market Trends, ETFs & Mining Data
Lithium carbonate spot prices in North Asia stood at $8,259/tonne on June 23, 2025, before Fastmarkets recorded a further move to $13,003/tonne in China by November 26, 2025 — and Benchmark Mineral Intelligence has tracked battery-grade lithium carbonate near $25,000/tonne as of May 2026. That is roughly a threefold increase in under a year. If you searched for a single “lithium market price” figure, there isn’t one: price depends on grade, region, and delivery date, and it has moved fast enough that any number printed here needs a live source, which this article gives you throughout.
The headline trend for anyone tracking lithium ore mining or considering lithium-linked investments: prices bottomed in mid-2025 after a prolonged slide from 2022–2023 highs, then reversed sharply on tightening supply and EV demand. The Global X Lithium & Battery Tech ETF (LIT) returned 57% year-to-date in 2025, a scale of move that outpaced most single-commodity plays. This piece walks through the price data, the production numbers behind it, the ETF mechanics, and the mining fundamentals — with a calculator at the end so you can size a lithium tonnage estimate against current spot pricing yourself.
Lithium Market Price 2025: The Trend in Numbers
Three data points anchor the 2025–2026 lithium price story, all reported by Fastmarkets and Benchmark Mineral Intelligence:
- $8,259/tonne — lithium carbonate spot price, North Asia, June 23, 2025.
- $13,003/tonne — lithium carbonate spot price, China, November 26, 2025 (Fastmarkets).
- ~$25,000/tonne — battery-grade lithium carbonate, May 2026 (Benchmark Mineral Intelligence), with commentary cited in the same reporting suggesting prices could reach as high as $28,000/tonne by 2026 on strong demand forecasts.
That is a move from roughly $8,000 to roughly $25,000 per tonne in under twelve months — a price environment unlike the relatively flat 2023–2024 period that preceded it. For context on why this matters to search volume: queries like “lithium market price 2025” and “lithium market trends 2025” spike precisely because the number moves fast enough that last quarter’s figure is already wrong. There is no static answer to “what is the lithium price” — there is only a source you check regularly. Fastmarkets and Benchmark Mineral Intelligence publish lithium carbonate and hydroxide spot assessments on a daily-to-weekly cadence across North Asia and China; if you need today’s number, that is where to look rather than any fixed figure printed in an article.
Lithium carbonate (Li₂CO₃) and lithium hydroxide (LiOH) are quoted separately because battery chemistries use them differently — lithium iron phosphate (LFP) cells lean on carbonate, while nickel-rich cathodes (NCM, NCA) typically require hydroxide. The research brief for this article did not surface a hydroxide-specific price point or a breakdown of grade premiums by chemistry; if that distinction matters for your sourcing decision, Fastmarkets publishes both series separately and that is the correct place to pull a current, chemistry-specific number rather than relying on a single blended “lithium price.”
Lithium Price Comparison Table: Spot Prices Over Time
| Date | Market | Price (USD/tonne) | Source |
|---|---|---|---|
| June 23, 2025 | Lithium carbonate spot, North Asia | $8,259 | Fastmarkets / Benchmark Mineral Intelligence |
| November 26, 2025 | Lithium carbonate spot, China | $13,003 | Fastmarkets |
| May 2026 | Battery-grade lithium carbonate | ~$25,000 | Benchmark Mineral Intelligence |
These three points are not a smooth curve — there is a roughly five-month gap between the second and third readings, and prices in fast-moving commodity markets do not move in a straight line between two known points. Treat the direction (up, and sharply) as the reliable takeaway, and pull a fresh spot quote from Fastmarkets before making a purchasing or investment decision on the strength of any number in this table.
Lithium ETFs: How LIT Has Performed and What Drives It
For readers searching “lithium etfs,” the largest and most-referenced vehicle is the Global X Lithium & Battery Tech ETF (LIT), which holds a basket of lithium miners, refiners, and battery makers rather than the physical metal. LIT returned 57% year-to-date in 2025, according to Global X Funds’ own performance reporting — a move large enough that financial commentary compared it favorably to mega-cap technology stock performance over the same stretch.
That return tracks the same price recovery detailed above: as lithium carbonate spot prices rose from roughly $8,000/tonne in June 2025 toward $25,000/tonne by May 2026, the equities of companies that mine and process lithium re-rated accordingly, since miners’ margins are highly leveraged to the spot price above their production cost. This is the mechanical link between the mining data in this article and the ETF question a searcher is actually asking: an ETF holding lithium producers moves largely on the same carbonate and hydroxide price series covered above, plus company-specific factors (production costs, project timelines, balance sheets) that a single commodity price does not capture.
Before treating a 57% one-year return as a repeatable pattern, note two things a current AI summary won’t spell out for you: first, that return followed a multi-year price decline, so part of it is recovery from a depressed base rather than new highs; second, ETF performance is a trailing, backward-looking figure — for the current NAV, holdings, and expense ratio, Global X publishes fund-level detail on its own site rather than through secondary aggregators.
Global and US Lithium Production Data
Global lithium mine production was 240,000 tonnes in 2024, per USGS, and Fastmarkets estimated the figure to have risen to 290,000 tonnes in 2025 — a roughly 21% year-over-year increase in mined volume even as prices bottomed and then recovered. The United States is a minor producer by comparison: US lithium mine production was 4,000 tonnes in 2024, according to the USGS Mineral Commodity Summaries 2025, against measured and indicated US lithium resources of 19 million tonnes as of the same report. The US imported 3,800 tonnes of lithium for consumption in 2024 — nearly matching domestic mine output, which underscores how much of US lithium-chemical supply still comes from overseas processing even where raw resources exist domestically.
Put another way: the US holds roughly 4,750 times more lithium in the ground (19 million tonnes of resources) than it mined in a single year (4,000 tonnes), a gap that reflects permitting timelines, project financing, and processing capacity rather than geological scarcity. The USGS Mineral Commodity Summaries 2025 is the primary source for all four of these figures and is republished annually — check the current edition for updated tonnage before citing these numbers as this year’s data.
Lithium Ore Mining: Extraction Methods and Where It Happens
Lithium is extracted through two distinct paths, and the method used shapes both cost and environmental footprint:
- Hard-rock ore mining: extraction from spodumene and petalite-bearing deposits, dominant in Western Australia, followed by conventional crushing, flotation, and chemical conversion to lithium carbonate or hydroxide.
- Brine extraction: pumping lithium-rich brine from underground aquifers, then evaporating it in shallow ponds over months, concentrated in the Lithium Triangle spanning Chile, Argentina, and Bolivia.
Global demand for the metal in 2025 was estimated at $9.2 billion in market size, according to Market Research Future — a figure that captures the value of lithium chemicals sold into batteries, ceramics, glass, and lubricants combined, not the mined-ore value alone. For background on which companies dominate extraction volume, see our breakdown of the biggest lithium producers and the current state of world lithium supply.
Demand Drivers: EVs, Storage, and Strategic Stockpiling
The IEA forecast global electric vehicle sales at 20 million units for 2025 — the single largest driver of lithium chemical demand, since each EV battery pack requires several kilograms of lithium carbonate equivalent depending on pack size and chemistry. Three other demand channels compound this pull on supply:
- Grid-scale energy storage: utility and industrial battery installations paired with wind and solar capacity, which compete directly with EV manufacturers for the same battery-grade lithium hydroxide and carbonate supply.
- Consumer electronics: laptops, phones, and power tools maintain a steady baseline lithium-ion demand independent of the EV cycle.
- Government-backed processing investment: the US Department of Energy committed $3 billion in federal funding for lithium extraction and processing projects under the Bipartisan Infrastructure Law in 2024, aimed specifically at building domestic midstream capacity rather than just mining volume.
That $3 billion figure matters for anyone assessing US lithium supply security: it targets the gap identified above, where the US mines only 4,000 tonnes annually but sits on 19 million tonnes of resource — the constraint is processing and refining capacity, not the rock in the ground. The research brief for this article did not include specific project names, funding recipients, or production start dates for individual US lithium projects; the Department of Energy’s Loan Programs Office and the Bipartisan Infrastructure Law program pages are the correct places to check current award status and timelines, since those details change as projects clear permitting and financing milestones.
Supply Constraints and Why Prices Stay Volatile
Global mine production rose from 240,000 tonnes (2024) to an estimated 290,000 tonnes (2025) — a 21% increase — yet prices still roughly tripled over a similar window, from $8,259/tonne in June 2025 to near $25,000/tonne by May 2026. That combination (rising supply, rising price) signals that demand growth outpaced even a fairly large production increase. Several structural constraints explain why supply cannot simply expand to meet price signals within a single year:
- Permitting timelines: new hard-rock and brine projects commonly take multiple years from discovery to first production, regardless of price incentives, because environmental review and water-rights processes run on fixed regulatory schedules.
- Geographic concentration: high-grade reserves remain concentrated in a small number of jurisdictions — Australia, the Lithium Triangle nations, and China — so a permitting delay or policy shift in any one of them has outsized effect on global supply.
- Water and energy intensity: brine evaporation requires months of processing time that cannot be compressed regardless of price, and hard-rock conversion to battery-grade chemicals is itself energy- and capital-intensive.
- Processing bottlenecks: as the US data shows, mining capacity and chemical-conversion capacity do not scale together — the $3 billion DOE commitment exists specifically because midstream processing lagged upstream resource development.
This is the durable mechanism behind every lithium price spike and crash cycle: supply responds on a multi-year lag while demand (EV sales, storage buildouts) can shift within a single earnings cycle. Anyone modeling future lithium prices should treat the current $25,000/tonne level as a data point on that lag, not a floor or a ceiling — check Fastmarkets’ current assessment before assuming today’s number still holds.
Environmental and Social Considerations in Lithium Mining
Environmental Pressures
- Water use: brine operations in Chile’s Atacama Desert draw on aquifers shared with local agriculture and communities, making water allocation a recurring regulatory and social flashpoint in the Lithium Triangle.
- Energy intensity: converting spodumene concentrate to battery-grade lithium chemicals requires high-temperature roasting and acid leaching, both energy-intensive steps that operators are under increasing pressure to power with lower-carbon sources.
- Land and tailings: hard-rock mining generates tailings that require long-term containment and, in many jurisdictions, mandatory reclamation planning before permits are issued.
- Carbon accounting: Farmonaut’s carbon footprinting solutions give mining operators a way to measure and report emissions across extraction and processing in real time, which matters as buyers increasingly ask for chain-of-custody emissions data alongside the metal itself.
Social License and Supply Chain Trust
- Community engagement: brine and hard-rock projects alike increasingly require negotiated benefit-sharing agreements with indigenous and local communities before permits clear.
- Traceability: blockchain-backed tools such as Farmonaut Traceability let battery makers and automakers verify the provenance of lithium chemicals through the supply chain, which is becoming a procurement requirement rather than a marketing feature as regulators in the US and EU move toward mandatory supply-chain disclosure.
Regional Breakdown: Australia, the Lithium Triangle, China, US, EU
Australia: Volume Leader via Hard-Rock Ore
Australia’s spodumene deposits make it the largest single source of mined lithium volume globally, feeding directly into the 290,000-tonne 2025 global total estimated by Fastmarkets. See our full producer rankings in biggest lithium producers. Operators increasingly use satellite and fleet management platforms to track vehicles and monitor land disturbance across remote sites without physical site visits.
The Lithium Triangle: Chile, Argentina, Bolivia
Brine extraction in the Lithium Triangle remains among the lowest-cost production routes globally, but water allocation disputes and community relations continue to shape project timelines more than price alone. Satellite monitoring of evaporation ponds and surrounding water tables is increasingly used to provide independent, third-party evidence in these disputes.
China: Processing Dominance, Growing Mine Supply
China set the reference price point cited earlier — $13,003/tonne for lithium carbonate as of November 26, 2025, per Fastmarkets — reflecting its role as the largest single lithium-chemical market and processing hub, even as it simultaneously expands domestic and overseas mining investment to reduce reliance on imported spodumene. Our world lithium supply analysis covers how Chinese refining capacity shapes the price a US or European buyer ultimately pays.
United States: Small Mine Output, Large Resource Base
As detailed above, the US mined 4,000 tonnes of lithium in 2024 against 19 million tonnes of measured and indicated resources and imported 3,800 tonnes to cover demand the same year. The $3 billion DOE commitment to extraction and processing under the Bipartisan Infrastructure Law targets exactly this gap. For a look at which US-based companies are positioned to close it, see top US lithium producers.
European Union: Circular Economy Push
EU battery regulation continues to push toward mandatory recycled-content minimums and supply-chain due diligence for battery materials, which affects how European automakers and battery makers source lithium chemicals — favoring traceable, lower-carbon supply even at a price premium over untraced material.
Calculator: Lithium Carbonate Value Estimator
Use the tool below to estimate the market value of a given tonnage of lithium carbonate at a spot price you set yourself — useful for sizing a project, a stockpile, or comparing against the historical price points cited above.
Assumptions: this tool multiplies input tonnage by the spot price you enter and applies your recovery rate to approximate saleable output value. It does not include mining costs, conversion/refining costs, transport, royalties, or taxes, and it does not forecast future prices — enter a current spot price from Fastmarkets or Benchmark Mineral Intelligence for an up-to-date estimate.
Satellite and AI Technology in Lithium Mine Monitoring
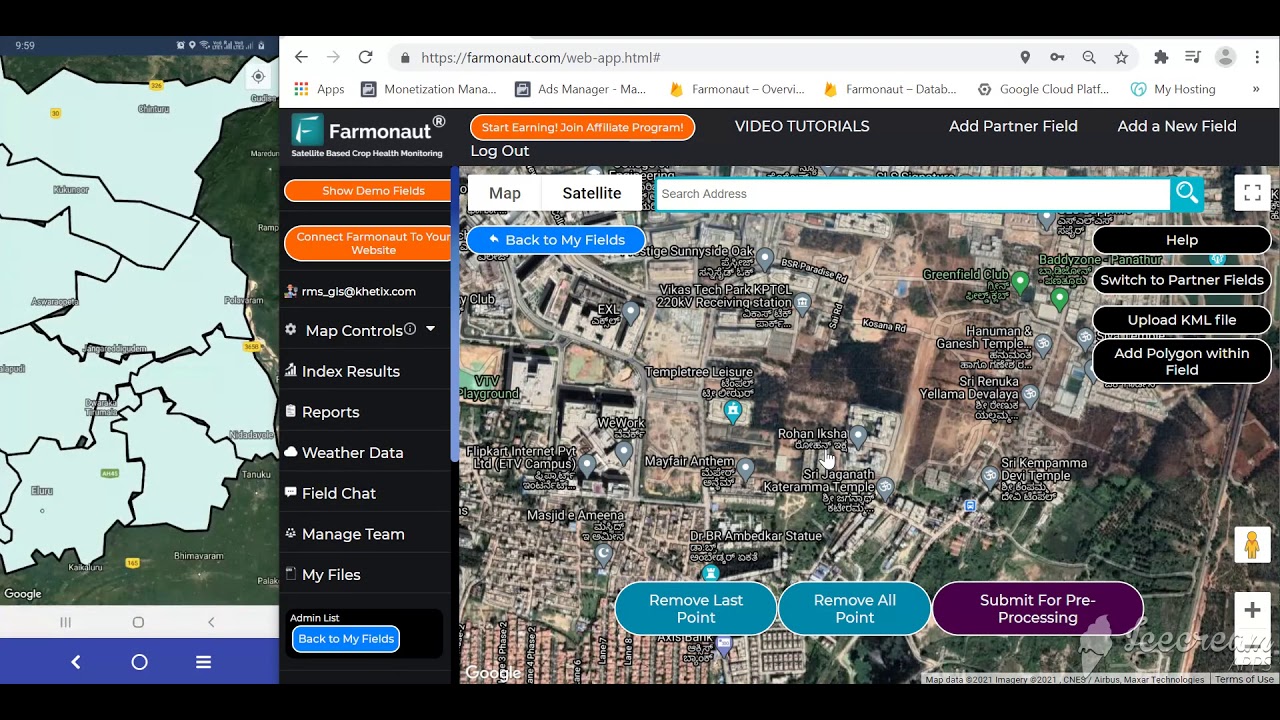
- Satellite-based monitoring: high-frequency multispectral imagery lets operators track evaporation pond levels, tailings extent, and land disturbance without repeated site visits. The Farmonaut Agro Admin App supports large-scale monitoring of landscapes and mining assets from a single dashboard.
- Predictive analytics: machine-learning models applied to satellite and sensor data support resource identification and equipment maintenance scheduling across both greenfield and brownfield lithium sites.
- Blockchain traceability: verified chain-of-custody records for mined lithium are increasingly requested by battery makers and automakers as a procurement condition, not just a sustainability add-on.
- Fleet management: fleet management tools reduce unnecessary fuel use and idle time across vehicle-heavy mining and haulage operations.


Farmonaut Solutions for Mining Operators
Tracking lithium mine sites, tailings, and infrastructure footprint against the kind of price volatility documented above requires monitoring that does not depend on physical site visits. Farmonaut provides a satellite-driven platform built for exactly this.
Key Offerings
-
Real-time satellite monitoring: our platform and apps (Web, iOS & Android) use high-resolution multispectral imagery to monitor extraction sites, tailings facilities, and infrastructure footprint, supporting early detection of environmental issues.



- Resource and fleet management: our fleet management solution tracks vehicles and heavy equipment across remote, vast sites to cut operational costs.
- AI advisory and traceability: our Jeevn AI system delivers site-specific sustainability recommendations, paired with blockchain-based traceability for tamper-proof supply chain reporting.
- API integration: integrate satellite-based weather, land, and environmental intelligence directly via our public API and developer documentation to automate mining site data collection and risk analytics.
- Scalable subscriptions: flexible tiers for individual users, mining companies, and government agencies of any operational scale.
- Large-scale project monitoring: our large-scale project monitoring tools oversee multi-site mining infrastructure, rehabilitation, and land restoration from one interface.
Subscription Options
Interested in advanced lithium mining insights?
Try the Farmonaut mining monitoring solution on web, iOS, or Android.



Where Lithium Fits in Diversified Metals and Mining Markets
Lithium is frequently grouped with other battery and industrial metals under “diversified metals and mining” coverage, but it behaves differently from base metals like copper or nickel in one key respect: its price history over 2025–2026 (roughly $8,000 to $25,000/tonne) reflects a narrower, faster-moving market than diversified metals indices typically capture, because lithium chemical demand is concentrated almost entirely in batteries rather than spread across construction, industrial, and consumer end-uses. For market price transparency specifically, that means lithium spot assessments from Fastmarkets and Benchmark Mineral Intelligence — not blended mining-sector indices — are the correct reference point if you are pricing lithium exposure rather than a diversified metals basket. If your interest is genuinely in the broader diversified metals and mining sector rather than lithium specifically, that comparison sits outside the scope of this article and is better served by sector-wide mining index coverage.
FAQs: Lithium Price, Mining, and ETFs
What is the lithium market price right now?
There is no single fixed number — lithium carbonate spot prices moved from $8,259/tonne in North Asia (June 23, 2025) to $13,003/tonne in China (November 26, 2025), and Benchmark Mineral Intelligence tracked battery-grade material near $25,000/tonne by May 2026. For the current figure, check Fastmarkets’ or Benchmark Mineral Intelligence’s live spot assessment, which is updated daily to weekly.
What are the lithium market trends driving this price movement?
Global mine production rose from 240,000 tonnes (2024) to an estimated 290,000 tonnes (2025), yet prices still roughly tripled over a similar window because EV demand (20 million units forecast for 2025 by the IEA) and grid storage buildouts outpaced supply growth. Permitting timelines and processing-capacity bottlenecks mean supply cannot expand as fast as demand within a single year.
What is the best lithium ETF and how has it performed?
The Global X Lithium & Battery Tech ETF (LIT) is the most widely referenced lithium-sector fund; it returned 57% year-to-date in 2025 per Global X Funds’ own reporting. It holds equities across mining, refining, and battery manufacturing rather than physical lithium metal, so its return reflects both commodity price moves and company-specific factors.
How much lithium does the United States produce and import?
The US mined 4,000 tonnes of lithium in 2024 and imported 3,800 tonnes for consumption the same year, against measured and indicated domestic resources of 19 million tonnes, per USGS Mineral Commodity Summaries 2025. See top US lithium producers for company-level detail.
Which regions lead global lithium mining?
Australia leads on mined hard-rock volume via spodumene deposits; Chile, Argentina, and Bolivia (the Lithium Triangle) lead on low-cost brine extraction; China leads on processing and chemical conversion. See our biggest lithium producers and world lithium supply coverage for the full breakdown.
What environmental concerns are tied to lithium mining?
Water use in brine extraction, energy intensity in chemical conversion, tailings management in hard-rock mining, and carbon emissions across both routes are the primary concerns. Read more in our dedicated piece on lithium mining environmental impacts in the Lithium Triangle.
How does Farmonaut support lithium mining operations?
Farmonaut provides real-time satellite monitoring, carbon footprint tracking, fleet and resource management, and blockchain traceability, accessible via our app (Web, iOS, Android) or through our API and developer documentation.

 Critica Metals Limited
 Congo Mining Solutions
 Mining SARL
 SenGold Invest SAS
 Sania Corporation
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading

