

Reviewed August 2026 against USDA Farm Service Agency lending rate announcements and the Federal Reserve Bank of Dallas Agricultural Survey.
Try it: Run your own numbers →
Texas farmers and ranchers currently have three main paths into agricultural financing: USDA Farm Service Agency direct loans, Farm Credit System lending, and commercial bank or credit union products, with the Texas Agricultural Finance Authority (TAFA) layered on top for state-specific projects. As of the USDA’s August 2026 announcement, FSA direct Farm Operating Loans carry a 5.25% interest rate and direct Farm Ownership Loans carry 6.00%, while the Federal Reserve Bank of Dallas reported Texas farm real estate loan rates running 6.8%–7.4% in its Q2 2026 Agricultural Survey. Below is the full comparison, the actual rate ranges, and a calculator to work out what a loan will cost you before you apply.
Summary: Agricultural Financing Solutions in Texas
Texas agriculture draws on a layered financing system rather than a single lender type. The USDA Farm Service Agency sets a national base rate that resets monthly; the Farm Credit System supplies the largest single pool of agricultural credit in the country; commercial banks and credit unions fill in equipment and short-term needs; and TAFA adds Texas-specific programs for modernization, rural business, and land expansion. Because FSA rates change on a monthly cycle and Farm Credit or bank rates track broader credit markets, the “right” answer to agricultural financing solutions Texas depends on which rate window you’re borrowing in, not on a single fixed number that holds all year.
This matters for search terms like agriculture financing, texas ag finance, and agricultural business loans texas because each maps to a different lender and a different qualification bar — federal direct loans for beginning or underserved producers, Farm Credit for larger creditworthy operations, and commercial equipment loans for shorter-term asset purchases. The comparison table below breaks out which is which.
The Texas Agricultural Finance Landscape
Agricultural financing solutions Texas cover a broad spectrum of needs, from single-season operating costs to multi-decade land mortgages. The core categories:
- Crop production loans finance seed, fertilizer, chemicals, and labor during planting and growing periods.
- Equipment loans fund tractors, harvesters, irrigation systems, and precision ag technology.
- Land acquisition loans (real estate loans) let producers expand acreage or secure long-term tenure — this is the category where the Dallas Fed’s 6.8%–7.4% Q2 2026 rate range applies.
- Lines of credit provide working capital flexibility during fluctuating market cycles.
Three institution types dominate the Texas market:
- Farm Credit System: A network of borrower-owned lending cooperatives that, system-wide, held $81.21 billion in outstanding non-real-estate agricultural loans and $187.95 billion in outstanding real estate farm loans at the end of 2024, per the Farm Credit System’s investor presentation. System-wide, Farm Credit held a 45.82% share of all U.S. agricultural debt in 2023 — making it the single largest source of farm credit nationally, and its Texas-based associations operate the same way, with dedicated ag divisions and terms tailored to local crop and livestock cycles.
- USDA Farm Service Agency (FSA): The direct lender of last resort for beginning and socially disadvantaged farmers, and the source of the rate figures in this article. FSA rates are published monthly, so the numbers below have a shelf life measured in weeks, not years — see the refresh method under the comparison table.
- Texas Agricultural Finance Authority (TAFA): A state agency offering targeted loans for modernization, rural agribusiness, conservation, and land expansion, structured as loan guarantees and interest rate reduction programs rather than direct USDA-style lending.

Why Texas’s Financing Mix Differs From Other States
Texas covers semi-arid West Texas, humid Gulf Coast prairies, and the High Plains cotton belt — three distinct risk profiles under one state finance system. That range is part of why Texas ranchland values rose 8% year-over-year as of the Dallas Fed’s Q2 2026 survey: land values in different sub-regions are responding to different pressures (drought exposure in the west, urban-adjacent demand near metro areas), and a single statewide rate doesn’t capture that spread. If you’re comparing “texas farm financing” against a specific county, ask your lender for the county-level appraisal comp, not just the statewide average.
Comparative Table: Texas Agricultural Financing Options
The table below lists rates and figures with a published source and date. Where no verified figure exists (loan amount caps, exact eligibility mechanics that vary by lender), that is marked explicitly rather than filled in.
| Financing Solution | Provider/Institution | Interest Rate | Rate Vintage | Typical Use | Source |
|---|---|---|---|---|---|
| Farm Operating Loan (direct) | USDA Farm Service Agency | 5.25% | August 2026 | Seed, fertilizer, labor, short-term operating costs | USDA FSA |
| Farm Ownership Loan (direct) | USDA Farm Service Agency | 6.00% | August 2026 | Land purchase, farm ownership transfer | USDA FSA |
| Commodity Loan (under 1 year) | USDA Farm Service Agency | 5.00% | August 2026 | Post-harvest marketing loans against stored crops | USDA FSA |
| Farm real estate loans (mortgages) | Texas commercial banks / Farm Credit associations | 6.8%–7.4% | Q2 2026 | Land acquisition, long-term real estate financing | Dallas Fed Ag Survey |
| Non-real-estate ag loans, system-wide | Farm Credit System | Rate not published per-loan; $81.21B outstanding | End of 2024 | Operating lines, equipment, livestock financing | Farm Credit System |
| Real estate farm loans, system-wide | Farm Credit System | Rate not published per-loan; $187.95B outstanding | End of 2024 | Land mortgages, long-term real estate credit | Farm Credit System |
| TAFA loan guarantee / rate reduction programs | Texas Agricultural Finance Authority | Not independently published; ask the administering lender | — | Modernization, rural ag business, conservation, land expansion | State agency; verify current terms directly with TAFA |
Refresh method: USDA FSA lending rates are republished monthly, typically the first Wednesday of the month, at fsa.usda.gov’s news section — search “announces…lending rates” for the current month’s figures rather than relying on the August 2026 numbers above once several months have passed. The Dallas Fed’s Agricultural Survey runs quarterly; the Q2 report covers April–June conditions, so a Q3 or Q4 edition will supersede the 6.8%–7.4% range and the 8% ranchland figure cited here.
Loan Repayment Calculator
Use the calculator below to estimate monthly and total payments on any of the loan types above — enter the actual rate for the product you’re evaluating rather than assuming one number fits every loan.
Run your own numbers
Assumes a fixed annual rate compounded monthly with equal payments (standard amortization) for ownership/real estate loans, and simple annual interest for operating loans repaid in one season. Excludes origination fees, closing costs, insurance premiums, and any rate adjustments tied to sustainability-linked or beginning-farmer discounts. Confirm actual amortization terms with your lender — FSA, Farm Credit, and commercial banks structure repayment differently.
Seasonal Farm Financing Options
Seasonal financing needs fall into two distinct windows: pre-planting operating credit and post-harvest marketing credit. USDA’s Commodity Loan program — priced at 5.00% for terms under one year as of August 2026 — is built specifically for the post-harvest window, letting producers borrow against stored grain or cotton rather than sell into a low market immediately after harvest. Pre-planting operating credit, by contrast, is what the 5.25% direct Farm Operating Loan rate applies to, and it is drawn down over the growing season rather than in a single disbursement.
This two-window structure is the practical answer to “seasonal farm financing options”: short-term commodity-secured loans for the marketing window, and operating lines or direct FSA loans for the production window. Producers commonly combine both — an operating loan to fund the crop, then a commodity loan against the harvested crop if market prices are unfavorable at harvest time.
Agriculture Financing in National Context
For readers comparing “agricultural finance companies” or “agricultural financial services” beyond Texas, it helps to see the scale of the national market Texas operations borrow within. The Farm Credit System alone held $81.21 billion in non-real-estate agricultural loans and $187.95 billion in real estate farm loans outstanding at the end of 2024 — a combined $269.16 billion — and represented 45.82% of all agricultural debt nationally in 2023. That means most agricultural debt in the U.S., Texas included, runs through Farm Credit associations rather than commercial banks or federal direct lending.
This scale matters for anyone searching “agri finance advisors”: an advisor’s first useful question isn’t which lender has the lowest advertised rate, but which lender’s balance sheet and risk appetite actually matches your loan size and collateral — a $50,000 microloan and a $3 million real estate purchase are rarely competing for the same lender’s attention.

Technology Trends Reshaping Agricultural Finance
Beyond published rates, the mechanics of how a Texas farm loan gets underwritten are changing:
-
Precision Agriculture Data in Underwriting:
Soil health data, yield history, and field-level weather records give lenders site-specific evidence instead of relying solely on the borrower’s balance sheet — improving terms for operations with strong data trails. -
Digital Application Platforms:
Automated underwriting reduces paperwork and accelerates approval timelines relative to paper-based FSA or bank applications. -
Sustainability-Linked and Green Loans:
Water conservation and soil health compliance are increasingly tied to rate discounts at select commercial lenders — though no state-published rate schedule exists for these; ask the specific lender for their current green-loan terms. -
Satellite-Verified Field Data:
Lenders and insurers are adopting remote field verification to confirm planted acreage and crop condition claims without an in-person visit.
For example, Farmonaut’s crop loan & insurance solutions give lenders and insurers satellite-based field verification and claim validation, reducing the lag between a weather event and a resolved claim.

Working Capital & Crop Insurance Financing
Texas operations face weather volatility, shifting commodity prices, and rising input costs, which makes working capital access and risk management products essential rather than optional.
- Working Capital Loans: Cover operating costs — seed, fertilizer, labor, transportation — typically issued by commercial banks, cooperatives, and Farm Credit associations rather than FSA direct lending.
- Crop Insurance Financing: Bundled with operating loans, federally subsidized or private crop insurance protects against yield losses from drought, flood, hail, pests, or disease. Lenders often adjust collateral requirements when coverage is documented and current.
Cotton, corn, sorghum, and cattle producers in Texas face the widest range of weather exposure in the country within one state, from High Plains hail risk to Gulf Coast hurricane exposure — which is part of why bundled loan-insurance products remain the standard structure rather than the exception.

Risk Management & Climate-Resilient Financing for Texas Agriculture
Texas agriculture’s risk profile is shaped by variable rainfall, drought, hurricane exposure along the Gulf Coast, and rising land values that change the collateral math on existing loans. The Dallas Fed’s Q2 2026 survey put Texas ranchland value growth at 8% year-over-year — a figure that directly affects how much equity a rancher can borrow against, since rising land values expand available collateral even when cash flow is flat.
- Disaster-Responsive Lending: USDA and state agencies activate low-interest disaster loans after federally declared events, streamlining access to capital for recovery.
- Climate-Linked Insurance: Policies based on weather data and historical yield trends stabilize cash flow. Farmonaut’s crop loan and insurance monitoring helps validate weather-impacted claims through satellite evidence.
- Water & Soil Conservation Incentives: Some lenders offer rate reductions or grants for conservation tillage or improved irrigation, though — as noted above — these are lender-specific and not centrally published.

What to Ask Before You Borrow Against Rising Land Values
A durable rule for any Texas producer evaluating a real estate loan: confirm whether the appraisal behind your offered rate reflects a recent county-level comp or a statewide average like the Dallas Fed’s 8% figure. Statewide growth masks sub-regional swings — West Texas drought-affected land and Gulf Coast urban-fringe land are not appreciating at the same rate, and a lender using a stale or mismatched comp can either overstate your available equity or underprice your collateral. Ask for the appraisal date and the comparable sales it’s based on before signing.
Sustainability-Linked Financing for Texas Farms
A growing share of Texas lenders reward measurable environmental performance rather than pricing every loan the same regardless of practice:
- Water-Saving Irrigation Projects: Some lenders offer reduced rates for drip or precision irrigation investments in drought-prone zones — confirm current terms directly with the lender, as no statewide rate schedule for these exists.
- Soil Health Improvements: Certain programs reward tracking of soil organic matter, nutrient stewardship, and erosion prevention.
- Carbon Farming and Regenerative Agriculture: Producers using cover crops, conservation tillage, or on-farm renewable energy may access green loan products tied to measurable impact. For verification and management, see Farmonaut’s carbon footprinting tools.
Financial providers are increasingly tailoring products for Texas agribusinesses that demonstrate climate-smart management and digital traceability. For trusted produce supply chains and market access, see:
Farmonaut’s blockchain-based traceability solution.
How Satellite Data Supports Agricultural Finance Applications
Digital verification is becoming central to how Texas lenders and insurers confirm loan and claim data:
-
Satellite-Based Monitoring:
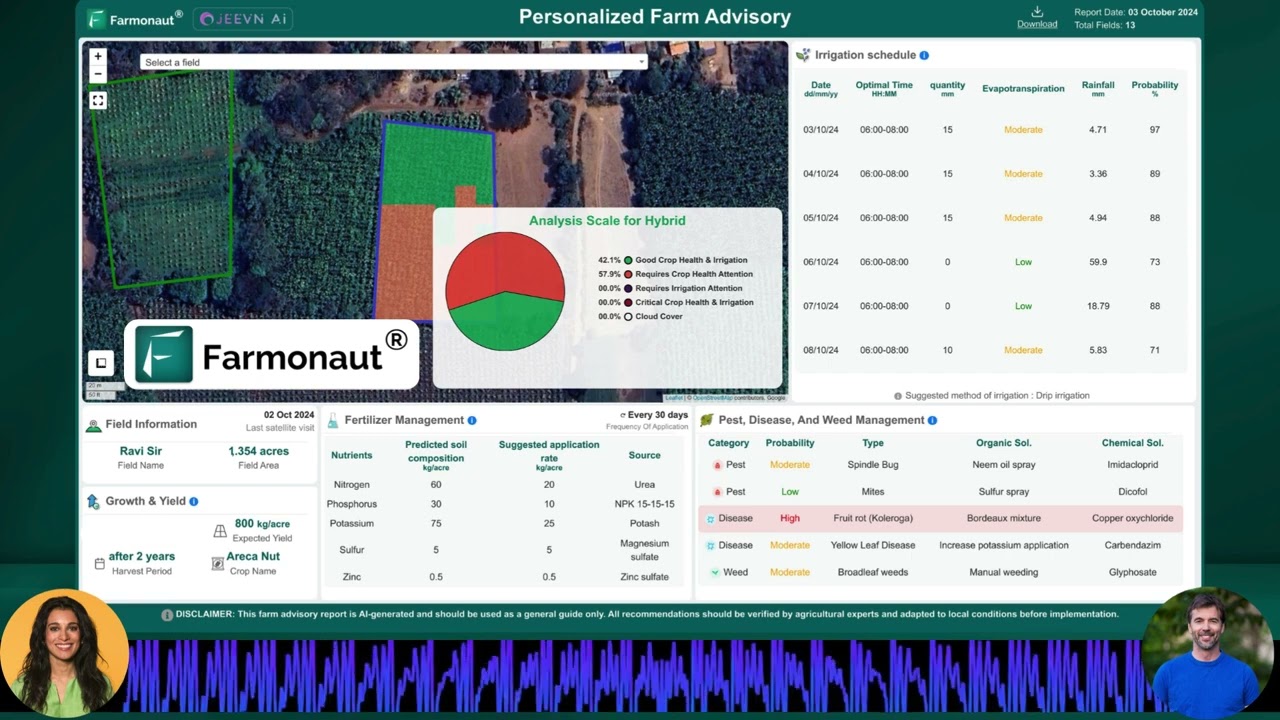
Farmonaut provides real-time crop and soil monitoring solutions through Android, iOS, and web apps, giving Texas producers field-level insight regardless of operation size. -
AI-Based Advisory & Custom Insights:
Farmonaut’s Jeevn AI system delivers tailored recommendations, weather forecasts, and risk alerts that inform financial decision-making across a crop season. -
Resource Management:
Farmonaut’s fleet management tools help track equipment and vehicle deployment, supporting the operational efficiency evidence lenders look for in loan applications. -
Satellite Verification for Financing:
Farmonaut supports financial institutions with API-based access to field data, enabling satellite-driven verification of loan or insurance claims. Developers can explore integration via the developer docs. -
Environmental Impact Tracking:
Farmonaut’s carbon footprinting solutions help Texas operations document sustainability-linked lending compliance and emissions reporting.
This platform is built for the full range of Texas operators: smallholder ranchers, row crop producers, agri-cooperatives, and large-scale agribusinesses.
Farmonaut Solutions & Product Links
-
Crop Loan & Insurance Monitoring: Satellite-based verification and claim validation for lenders and insurers. Reduces fraud, fast-tracks claims, and provides digital field history for credit analysis. -
Carbon Footprinting Tool: Track your operation’s carbon output for access to green financing and environmental certification. -
Product Traceability Platform: Blockchain-based authenticity for supply chains, supporting food safety and market access for Texas products. -
Fleet & Resource Management: Streamline logistics and demonstrate management efficiency in loan/insurance applications. -
Large-Scale Farm Management: Platform for operators managing multiple properties, diversified crops, or extensive fleets.
Get Started: Farmonaut Apps & Resources
Monitoring and analytics support financing applications across Texas. Farmonaut’s platforms are accessible via web app, Android, and iOS.



For enterprise or development integration, use the API and Developer Docs.
Farmonaut Subscription Packages for Agricultural Monitoring
Flexible packages for Texas producers and agribusinesses needing continuous satellite-driven monitoring — useful for building the documentation case behind agricultural financing, risk management, and sustainability-linked loans.
Frequently Asked Questions
What are the main agricultural financing solutions available to Texas farmers?
Texas farmers can access USDA FSA direct operating and ownership loans (5.25% and 6.00% respectively as of August 2026), Farm Credit System loans, commercial bank and credit union equipment financing, and TAFA-administered state programs for modernization and rural business projects. Check fsa.usda.gov’s monthly rate announcements for the current FSA figures before applying.
What is the current interest rate for a Texas farm loan?
It depends on the loan type. USDA FSA direct operating loans were 5.25% and ownership loans 6.00% as of the August 2026 announcement. The Dallas Fed’s Q2 2026 Agricultural Survey put commercial farm real estate loan rates in Texas at 6.8%–7.4%. Both figures update on a set schedule — FSA monthly, the Dallas Fed survey quarterly — so verify the current number at the source links in this article before locking in a rate.
What is agriculture financing and how does it differ from a standard business loan?
Agriculture financing refers to credit products designed around farm-specific cash flow cycles — seasonal operating loans tied to planting and harvest, commodity loans secured by stored crops, and land loans amortized over farm-appropriate terms. Standard commercial loans don’t typically account for a single annual harvest cycle the way FSA and Farm Credit products do.
Readers focused on land purchases can compare agricultural mortgage rates and USDA loan options nationally.
Are there seasonal farm financing options for pre-planting and post-harvest needs?
Yes. Operating loans (5.25% at USDA FSA as of August 2026) fund the pre-planting and growing season, while commodity loans (5.00% for terms under one year) let producers borrow against harvested, stored crops rather than selling immediately into potentially unfavorable market prices.
How does the Farm Credit System compare to USDA FSA loans?
The Farm Credit System is a much larger overall lender — holding a combined $269.16 billion in outstanding agricultural loans at the end of 2024 and 45.82% of national agricultural debt in 2023 — and generally serves creditworthy producers at commercial-market rates. USDA FSA direct loans are smaller in scale but carry lower, federally set rates and are targeted at beginning, small, or underserved farmers who may not qualify for Farm Credit or bank financing on standard terms.
How does Farmonaut support agricultural financing and insurance applications?
Farmonaut provides satellite-driven monitoring and verification for lenders, insurers, and producers — including crop health data, soil insights, and automated reporting — through an API and app-based platform that helps document loan eligibility and support insurance claim validation.
What documents are required for a Texas agricultural loan application?
Typical requirements include financial statements, production records, credit history, and a farm management plan. Increasingly, lenders also accept digital field evidence such as satellite imagery or yield analytics. Requirements are generally lighter for USDA microloans and beginning-farmer programs than for large Farm Credit real estate loans.





Conclusion
Agricultural financing in Texas runs through three parallel systems — federal direct lending via USDA FSA, cooperative lending via the Farm Credit System, and commercial bank or credit union products — with TAFA layered in for state-specific projects. The concrete numbers to anchor any comparison: 5.25% for FSA operating loans, 6.00% for FSA ownership loans, and 5.00% for commodity loans under a year, all as of August 2026; 6.8%–7.4% for Texas commercial real estate loans and 8% ranchland value growth, both from the Dallas Fed’s Q2 2026 survey; and a Farm Credit System holding $269.16 billion in combined outstanding agricultural debt at the end of 2024.
Because every one of those figures resets on a schedule — FSA monthly, the Dallas Fed quarterly, Farm Credit System data annually — the durable move is not to memorize this month’s numbers but to know where they live: the USDA FSA news page for lending rates, and the Dallas Fed’s Agricultural Survey series for Texas-specific credit conditions and land values. Use the calculator above with whatever current rate you find to model your actual repayment before signing.

 AgriBazaar
 Geno
 Hayleys Agriculture
 Linx Agritech
 Adinet
 Save Your Soils
 Grandstream Algérie
 XOS Realty
 Geospatial Lab Africa
 Agro La Gándara
 HIPSAC
 ZOL Zimbabwe
 Juligerm
 AdBio
 MISE Maroc
 NWNS
 Red August Group
 Farm Inc
 WeMe Global

