

Farm Bookkeeping and Accounting: A Complete System for US Farms
Reviewed August 2026 against IRS Publication 225 (Farmer’s Tax Guide) and USDA Economic Research Service farm income and balance sheet data.
Try it: Cash-to-Accrual Net Income Gap Calculator →
Farm bookkeeping is the daily recording of every sale, input purchase, loan payment, and asset change on your operation; farm accounting is the layer above it that turns those records into a profit and loss statement, a balance sheet, and a cash flow statement you can hand to a lender, the IRS, or your own year-end review. Get the first one wrong and the second one is worthless — a chart of accounts full of miscategorized fuel and repair costs cannot produce a trustworthy per-acre cost of production, no matter which software totals it. This guide sets up both halves in the order US row-crop, livestock, and specialty farms actually need them: which accounting method to pick, how to build a chart of accounts around IRS Schedule F, how long to keep what, and which reports your lender will ask for first.
Table of Contents
- What Is Farm Accounting? Farm Bookkeeping vs. Accounting
- Why Bookkeeping in Agriculture Works Differently
- Cash or Accrual? Choosing a Farm Accounting Method
- Building a Farm Chart of Accounts From Schedule F
- Consistent Record-Keeping for Farmers
- Reconciling Farm Accounts
- The Three Financial Reports Every Farm Needs
- Farm Accounting Software and Technology
- Farm Bookkeeping Best Practices
- When to Bring in a Professional Bookkeeper or Accountant
- Continuing Education in Agricultural Accounting
- Comparison Table: Farm Bookkeeping and Accounting Practices
- FAQ: Farm Bookkeeping and Accounting
- Conclusion
- Try it: Cash-to-Accrual Net Income Gap Calculator



What Is Farm Accounting? Farm Bookkeeping vs. Accounting Explained
Farm bookkeeping and farm accounting are two stages of the same job, not two names for one thing. Farm bookkeeping is the transaction-level task: entering each crop or livestock sale, each seed, feed, fertilizer, or fuel purchase, and each payment on a loan or lease, as it happens. Farm accounting takes those entries and classifies, summarizes, and reports on them — building a chart of accounts, applying a consistent accounting method, and producing the profit and loss statement, balance sheet, and cash flow statement that a lender, insurer, or the IRS will ask to see.
So what is farm record and accounting, in practice? A farm record is any document — an invoice, a scale ticket, a bank statement, a fuel receipt — that supports a bookkeeping entry. Accounting is the discipline of turning a shoebox of those records into numbers you can compare year over year: cost per acre, cost per head, net income by enterprise. The IRS’s own guidance on why farmers should keep records lists the same reasons every US Extension office repeats: it lets you monitor the progress of the business, it is what you use to prepare financial statements, and it is what backs up every deduction and every dollar of income on Schedule F (Form 1040) if you are ever asked to prove it (IRS Publication 225, Farmer’s Tax Guide).
None of this is unique to large operations. The USDA counted 1.88 million farms in the United States in 2024, averaging 466 acres and 876 million total acres in farms — most of them businesses small enough that one person does the bookkeeping, the accounting, and the fieldwork (USDA ERS, Charts of Note, published April 2025; NASS reissues farm-count estimates every February, so check that page for a newer figure before you cite one).
Why Bookkeeping in Agriculture Works Differently
Bookkeeping in agriculture carries complications a typical small-business ledger does not: income and major expenses often land in different tax years than the work that generated them (calves born in the fall are not sold until spring); a large share of net worth sits in assets that only get valued once a year — land, breeding stock, growing crops, machinery; and profitability swings by enterprise far more than in most industries. That last point is not a guess — it is the difference between the least and most profitable farm types in the same USDA forecast.
Average Net Cash Farm Income by Farm Type — 2026 Forecast (USD)$74.8kCattle/calves$159.9kPoultry$191.6kCorn$219.4kWheat$296.4kCotton$305.3kSpecialtycrops$369.1kHogs$514.6kDairySource: USDA ERS, Farm Business Income, updated May 2026 — 2026 forecast (F) by commodity specialization.
USDA’s Economic Research Service forecasts 2026 average net cash farm income at $50,300 for cattle and calves operations against $477,500 for dairy — a spread of more than 9 to 1 in the same year (USDA ERS, Farm Business Income, September 2026). A chart of accounts and a bookkeeping cadence built for a dairy’s daily milk-check cash flow will misrepresent a cow-calf operation’s seasonal, once- or twice-a-year sale pattern, and the reverse is just as true. This is the importance of farm accounting in one number: the same bookkeeping habits produce a useful report for one enterprise and a misleading one for another, so the setup has to match the enterprise, not a generic small-business template.
Cash or Accrual? Choosing a Farm Accounting Method
The IRS defines the two methods plainly: under the cash method, “income is reported when received, and expenses are deducted when paid”; under the accrual method, “income is reported when earned, and expenses are deducted when incurred,” regardless of when the cash moves (IRS Publication 225). Most US farms use the cash method because it is simpler to keep and it lets a farmer manage which tax year income and expenses land in — sell grain in January instead of December, or prepay next spring’s fertilizer in the current December, and the cash-method return reflects that timing choice directly.
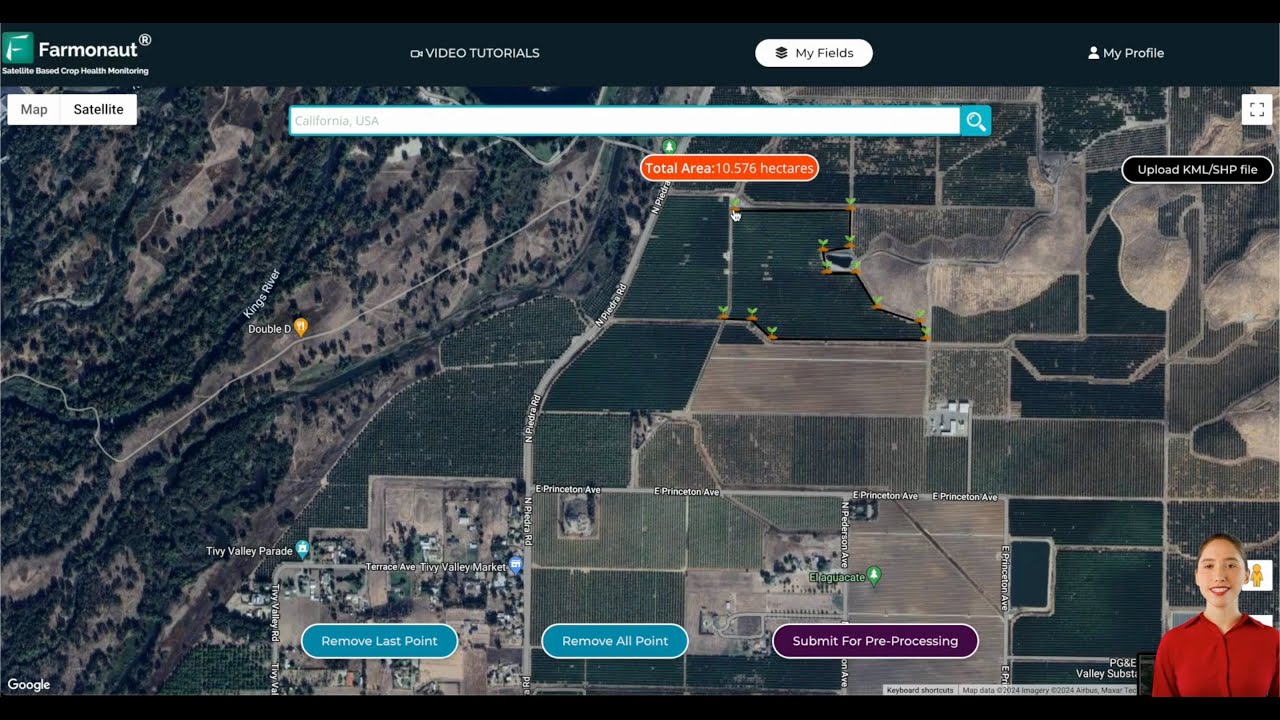
The trade-off is that a cash-basis return can make a good year look mediocre and a bad year look fine, because it says nothing about unsold grain sitting in the bin, calves not yet marketed, or unpaid input bills. Accrual accounting corrects for that by counting the change in inventory, receivables, and payables, which is why a lender reviewing a loan application commonly asks for an accrual-adjusted income statement even from a farm that files its taxes on the cash method. Farmonaut’s large-scale farm management tools and satellite crop-health tracking can supply the yield and input-timing data that feeds that adjustment, linking crop condition through the season to the harvest and expense figures your accountant reconciles at year-end.

Use the calculator below to see the size of that cash-to-accrual adjustment for your own operation before deciding how much weight to put on a cash-basis number alone.
Interactive
Cash-to-Accrual Net Income Gap Calculator
Whichever method you choose, the IRS wants consistency, not a preference — changing methods requires filing Form 3115 in most cases, so document the choice once and keep it unless your accountant recommends a formal change.
Building a Farm Chart of Accounts From Schedule F
A chart of accounts is the list of buckets every transaction gets sorted into. For a US farm, the fastest way to build one that survives tax season is to mirror the categories the IRS already uses on Schedule F (Form 1040), “Profit or Loss From Farming” — sales of livestock, produce, and grain; cooperative distributions; agricultural program payments; and crop insurance proceeds on the income side; car and truck, chemicals, feed, fertilizer, fuel, hired labor, insurance, interest, repairs, seeds, supplies, and utilities on the expense side. Schedule F’s exact line items are set by the IRS each year, so check the current-year form and instructions before finalizing your categories — a chart of accounts built to last gets reviewed against the live form annually, not copied once and forgotten.
Beyond Schedule F: Assets, Liabilities, and Equity
Schedule F only covers income and deductible expenses. A complete farm chart of accounts also needs asset accounts (land, buildings, machinery, breeding livestock, stored grain and feed inventory), liability accounts (operating loans, equipment loans, real estate mortgages, supplier credit), and an owner’s equity account — the three sections that feed the balance sheet rather than the tax return.
Consistent Record-Keeping for Farmers
Agricultural bookkeeping lives or dies on how consistently records get entered and stored, not on which software holds them. The habit that actually prevents year-end scrambling is simple: log income the day a check or deposit clears, and log an expense the day you have the receipt or invoice in hand — not at month-end from memory. For agricultural accounting on farms with employees or contract labor, that discipline extends to payroll and 1099 records, which carry their own IRS retention rule.
How long you keep each type of record is not a matter of preference: the IRS specifies a different period for each record type, not for each farm size or entity type.
How Long the IRS Says to Keep Farm RecordsGeneral return support3 yearsEmployment tax records4 yearsUnderreported income >25%6 yearsBad debt / worthless securities7 yearsProperty & asset recordsUntil disposed +limitations period (3–7 yrs)No return filed / fraudulent returnIndefiniteSource: IRS, “How long should I keep records?” (irs.gov), reviewed August 2026.
The general rule is 3 years from the date you file, matching the standard period of limitations for a claim or an audit. Employment tax records need at least 4 years. If you underreport income by more than 25% of what is on the return, the IRS’s own window extends to 6 years, and records supporting a bad-debt or worthless-securities deduction should be kept 7 years. Property and asset records — the basis for depreciation, the cost of that new grain bin or breeding herd — need to be kept for as long as you own the asset, plus the limitations period after you dispose of it, because that basis determines your gain or loss on sale (IRS, “How long should I keep records?”, reviewed August 2026).
For traceability that goes beyond what a spreadsheet can prove — verifying inputs, harvest dates, and chain of custody for a buyer or certifier — Farmonaut’s product traceability platform keeps a blockchain-backed record alongside your financial one.
Reconciling Farm Accounts
Reconciliation is the check that catches what entry alone misses: a bank fee you forgot to log, a duplicate invoice, a check that never cleared. Three accounts need it on a recurring basis:
- Bank reconciliation — match every line on the bank statement against your ledger monthly; outstanding checks and missing deposits are the two most common gaps.
- Inventory reconciliation — count grain in the bin, feed on hand, and finished livestock against what the books show, at harvest and again before year-end financials.
- Loan and credit reconciliation — verify principal, interest, and remaining balance on every operating loan, equipment note, and supplier credit line against the lender’s statement. Skipping this step is where “the books look fine” and “the books are right” stop meaning the same thing — and it is a common reason a lender’s numbers and a farmer’s numbers disagree at renewal time.
Where the bookkeeping system offers an accounting software API, bank and loan data can be pulled in on a schedule rather than keyed in by hand, which removes one of the more common sources of reconciliation error.
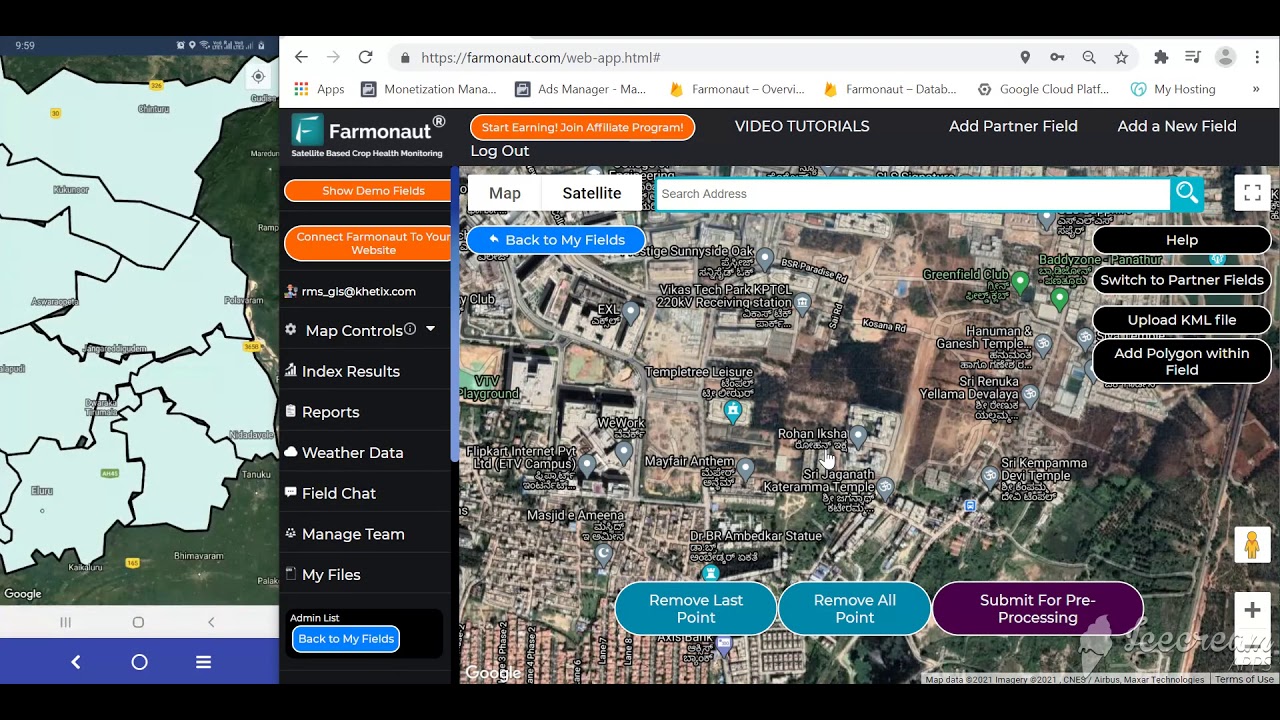
Satellite-verified field records can support that reconciliation from the production side — Farmonaut’s crop loan and insurance tools use field-level satellite verification so the acreage and condition data behind a loan or claim matches what your books say you planted and harvested.
A monthly bookkeeping routine for farmers
Most farm bookkeeping problems come from letting entries pile up until tax time. A fixed monthly routine, done in the same week every month, keeps the books usable for decisions, not just for Schedule F.
- Enter everything left over. Clear the pile of receipts, scale tickets, settlement sheets and invoices so the ledger is complete to month-end.
- Reconcile the bank and card accounts. Match every line on the statement to the ledger and chase outstanding checks and missing deposits.
- Check loan statements. Split each payment into principal and interest and confirm the balance matches the lender’s figure.
- Record payroll. Post wages and withholding for each pay period and file employment tax deposits on time.
- Update inventory in busy months. At harvest, weaning or sale time, record grain in the bin, feed on hand and livestock numbers.
- Run a quick profit and loss and cash flow. Compare them with the same month last year and with your budget, by enterprise if you can.
- Look ahead. Note input bills, loan payments and estimated tax dates coming in the next 60 days.
On a small operation this takes a few hours a month. If it regularly takes much longer, or the reconciliation never balances, that is usually the point where hiring a bookkeeper who knows farm accounts pays for itself.
The Three Financial Reports Every Farm Needs
Every US lender, and the IRS indirectly through Schedule F, expects the same three statements, built from the same chart of accounts:
- Profit and Loss Statement — revenue minus expenses over a period, the closest thing to “did the farm make money.”
- Balance Sheet — assets, liabilities, and owner’s equity at a single date; this is where land value, machinery, and debt live.
- Cash Flow Statement — actual cash in and out, which can diverge sharply from the P&L on a farm because of seasonal sales and large lump-sum input purchases.
The balance sheet is where accounting method and reconciliation habits show up most starkly at a sector level. USDA’s Economic Research Service forecasts US farm sector total assets at $4.47 trillion for 2026, up 3.0% from 2025, financed by $605.1 billion in debt (up 4.6%) and $3.86 trillion in equity (up 2.7%) — debt growing faster than assets, in nominal terms, in the same forecast. Real estate makes up 83% of that asset total (USDA ERS, Assets, Debt, and Wealth, updated September 2026).
US Farm Sector Balance Sheet Composition — 2026 ForecastDebt: $624.7B (13.8%)Equity: $3.92T (86.2%)Financed byReal estate: $3.77T (83%)Other assets: $0.77T (17%)Asset mixTotal farm sector assets: $4.54 trillion (+3.2% from 2025)Source: USDA ERS, Assets, Debt, and Wealth, updated May 2026 — 2026 forecast (F), nominal dollars.
That composition is exactly why an out-of-date asset ledger is more dangerous than an out-of-date expense ledger: land and real estate values move the balance sheet more than any single input cost, and USDA revises this forecast three times a year — February, late summer, and late fall — so treat the figures above as the current published forecast, not a fixed number, and pull the newest release from the link above before a loan application or year-end review.
Farm Accounting Software and Technology
General small-business accounting software — the QuickBooks or Xero class of tool — handles the ledger, invoicing, and tax-category mapping well, but it was not built for livestock tracking, grazing records, or crop-specific inventory, which is why many US operations pair it with a farm-specific management platform rather than replacing one with the other. What technology adds on top of correct bookkeeping is automated bank feeds, real-time inventory tied to purchase and usage, remote access from the field, and reminders ahead of loan or filing deadlines.
Farmonaut layers satellite-based crop health monitoring, carbon footprint tracking, fleet management, and blockchain traceability on top of that core, so the production data behind your numbers — actual field conditions, not just what a receipt says you bought — is available when you or your accountant need to explain a variance. For developers and agri-tech partners integrating that data into an existing accounting or ERP system, the Farmonaut satellite and weather API and its developer documentation cover the integration points directly. Farms managing multiple vehicles and implements can pull maintenance and fuel-cost data into the same ledger through Farmonaut Fleet Management, and operations reporting on environmental compliance can track that alongside the financials with carbon footprinting tools.
Farm Bookkeeping Best Practices
- Separate business and personal accounts. One bank account and one card for the farm, used for nothing else — this is the single change that most simplifies an IRS audit or a loan underwriting review.
- Code every transaction consistently. The same fuel purchase should hit the same account every time, or per-acre and per-head cost comparisons will be wrong without anyone noticing.
- Reconcile on a fixed schedule. Monthly for the bank, at minimum quarterly for inventory and loans — set the date on a calendar rather than “when there’s time.”
- Back up digital records off-site. Cloud storage or a second physical location protects years of records from one fire, flood, or failed drive.
- Train anyone else who enters data. A spouse, partner, or office employee who codes transactions needs the same chart-of-accounts rules you use, or the categories drift within a season.
The University of Wisconsin–Madison’s farm financial management guidance puts it bluntly: a net worth statement, income statement, cash flow statement, and statement of owner equity are only as good as the consistency of the entries behind them — “garbage in, garbage out” applies to a farm ledger exactly as it does to any other database (University of Wisconsin–Madison Extension).
When to Bring in a Professional Bookkeeper or Accountant
Bookkeeping for farmers of any size benefits from at least an annual review by a professional, even when day-to-day entry stays in-house — a second set of eyes on the accounting method, the depreciation schedule, and the Schedule F categorization catches errors that compound over years. Complexity is the real trigger for hiring help sooner: multiple enterprises, employees, an entity change (sole proprietor to LLC or partnership), or a large equipment or land purchase all raise the cost of a bookkeeping mistake past the cost of an hour with a professional.
An accountant or bookkeeper who works with agribusiness financial management specifically will also know the farm-specific provisions in Publication 225 that a general small-business accountant may not — income averaging, the different depreciation rules for agricultural equipment, and how to document crop insurance proceeds correctly.
Continuing Education in Agricultural Accounting
Agricultural accounting changes with every new farm bill, tax law update, and depreciation rule, so a chart of accounts and a set of habits built once need a periodic review, not a one-time setup. Land-grant university Extension offices — the same ones behind the FINBIN and FINPACK benchmarking tools at the University of Minnesota’s Center for Farm Financial Management — run workshops on farm financial record-keeping most winters, when fieldwork slows down; a state’s Cooperative Extension website is the fastest way to find the current schedule. Peer discussion groups, often organized through the same Extension offices or a farm credit lender, are the other consistent source of what is actually changing in practice, not just in the tax code.
Farmonaut’s Jeevn AI Advisory delivers ongoing crop management, weather, and resource guidance alongside the financial side — start at the Farmonaut app.
Comparison Table: Farm Bookkeeping and Accounting Practices
| Practice | What You Track | Recommended Frequency | IRS Retention Period | Feeds Into |
|---|---|---|---|---|
| Recording income & expenses | Every sale, input purchase, loan payment | Daily to weekly | 3 years (return support) | P&L, Schedule F |
| Choosing cash or accrual method | Timing of income/expense recognition | Set once; reviewed annually | 3 years | All three statements |
| Bank reconciliation | Bank statement vs. ledger | Monthly | 3 years | Balance sheet, cash flow |
| Inventory reconciliation | Grain, feed, livestock on hand | At harvest and year-end | 3 years | Balance sheet |
| Loan & credit reconciliation | Principal, interest, balance | Monthly or quarterly | 3 years after final payment | Balance sheet, cash flow |
| Payroll & employment tax records | Wages, withholding, contract labor | Every pay period | 4 years | P&L, compliance filings |
| Asset & depreciation records | Land, machinery, buildings, breeding stock | At purchase or sale | Until disposed + 3–7 years | Balance sheet, Schedule F depreciation |
| Bad debt / casualty documentation | Uncollectible accounts, disaster losses | As incurred | 7 years | Schedule F, insurance claims |
Farmonaut Precision Agriculture Subscriptions
FAQ: Farm Bookkeeping and Accounting
What is farm accounting?
Farm accounting is the process of classifying, summarizing, and reporting on farm bookkeeping entries — turning recorded transactions into a profit and loss statement, balance sheet, and cash flow statement that support tax filing, lending, and management decisions.
What is farm record and accounting?
A farm record is any document that supports a transaction — an invoice, receipt, or bank statement. Farm record and accounting together describe the full system: keeping those records, entering them consistently, and using them to produce the financial reports a farm needs.
Should I use cash or accrual accounting for my farm?
Most US farms file taxes on the cash method because it is simpler and allows some control over which tax year income and expenses land in. Larger or multi-enterprise operations, and any farm applying for financing, commonly also prepare an accrual-adjusted income statement, since it accounts for inventory, receivables, and payables that the cash method ignores (IRS Publication 225).
How often should I reconcile farm accounts?
Reconcile bank accounts monthly. Reconcile inventory at harvest and again before year-end financials. Reconcile loan and credit accounts monthly or quarterly, matching your lender’s statement cycle.
What financial reports does a farm need?
Three: a profit and loss statement, a balance sheet, and a cash flow statement. Lenders and the IRS, through Schedule F, expect all three to be derivable from the same chart of accounts.
How long should I keep farm financial records?
The IRS default is 3 years from filing. Employment tax records need 4 years. Records behind a bad-debt deduction need 7 years, and records for land, machinery, or breeding stock need to be kept for as long as you own the asset plus the applicable limitations period afterward.
Do I need a professional accountant for farm bookkeeping?
Not for day-to-day entry, but an annual review by someone familiar with agricultural accounting catches errors in method, depreciation, and Schedule F categorization that compound if left uncorrected — and becomes more valuable as soon as you add employees, enterprises, or a change in business entity.
What software should farmers use for bookkeeping?
General accounting software such as QuickBooks or Xero handles the ledger and tax categories; farm-specific platforms add livestock, crop, and inventory tracking those tools were not built for. Many US operations run both together rather than choosing one over the other.
Conclusion: A Bookkeeping System That Holds Up Under Review
Farm bookkeeping and farm accounting are not a once-a-year tax chore — they are the system that tells you, in real time, whether the operation is profitable, whether a lender will approve the next loan, and whether you can defend every number if the IRS asks. Build the chart of accounts around Schedule F, pick an accounting method and hold to it, reconcile on a fixed schedule, keep records for as long as the IRS actually requires, and pull a fresh USDA forecast before every major financial decision rather than relying on an old number.
Ready to connect the production data behind those numbers? Explore product traceability, carbon footprinting, and large-scale farm management, or download the app below.

 AgroGreen Dynamics
 Leher
 AgroRisk
 Oath Inc
 Reddane Farming
 Esri North East Africa
 Cresol
 Atur Kuliner
 MDCV UK
 Zerella Group
 Etech Consulting Madagascar
 Vestlandsforsking
 Agritein
 Delicio
 WB Dev
 Sama Premium
 Prochecker
 Tres Valles
 LACOS Geoinformation
 Magrifly
 LatConnect 60
 Blickwinkel
 Agricultural Credit Policy Council

