

Farm finance · Lease or buy guide
Ag Equipment Financing: Lease vs Buy With Real Rates
In simple dollars, a lease wins only below the break-even annual payment: the net cost of owning, divided by the years. FSA’s direct operating loan rate, for borrowers who cannot get credit elsewhere, was 5.625% effective 1 November 2026, and US bank prime was 7.00% on 4 November.
Key takeaways
- Compare any lease quote with the break-even annual payment for the same machine and term.
- FSA direct rates rose between August and November 2026: operating from 5.250% to 5.625%, ownership from 6.000% to 6.250%.
- US tractor sales fell 38.4% from 2021 to 2025, and combines fell 51.3% from 2023 to 2025 (AEM data, farmdoc daily).
- Section 179 reaches $2,560,000 for tax years beginning in 2026, but only on property you own; a $1 buyout may count as a purchase.
- Canada’s CALA program guarantees lenders 95% of a net loss on eligible loans, and loans for machinery can reach C$350,000.
In this article
- What ag equipment financing costs now
- Farm machinery lease vs loan, line by line
- What the machinery market means for your quote
- Used equipment financing and dealer stock
- The tax line to check before you choose
- Farm equipment financing in Canada
- Finding a farm equipment lender in your county
- Size the machine to the crop you actually harvest
- Eight checks before you sign an equipment lease or loan
- FAQ
- Where to go from here
Ag equipment financing comes down to one test: compare a lease quote with the break-even annual payment, which is the net cost of owning the same machine over the same term, divided by the years. A quote below that figure favors the lease. A quote above it favors buying with a loan. Public reference rates moved in the autumn: the USDA Farm Service Agency (FSA) direct operating loan rate rose from 5.250% in August 2026 to 5.625% effective 1 November 2026.
This guide gives dated rates, a line-by-line lease and loan comparison, a break-even calculator and market data you can use in a dealer negotiation. It is written for farm owners and the advisers who work with them in the US and Canada, with short notes for UK readers. Tax and lease terms depend on your own situation, so check them with your tax preparer, accountant or lender before you sign.
What ag equipment financing costs now
Start with the published government rates, because anyone can look them up in advance. FSA reissues them each month. The November 2026 list gives Farm Operating (Direct) at 5.625%, Farm Ownership (Direct) at 6.250%, Farm Ownership joint financing at 4.250%, the down payment program at 2.250% and Emergency loans (actual loss) at 3.750%. Farm Storage Facility loans ran from 4.875% for three years to 5.250% for twelve years. Compared with the August 2026 FSA announcement, every line listed here except the Emergency rate went up.
Chart
FSA loan rates: August vs November 2026
Percent, selected USDA Farm Service Agency programs, effective 1 August and 1 November 2026
Four points follow from those numbers.
- The direct rate is national. A borrower in Maine and a borrower in Illinois see the same FSA rate. A search for a local rate is really a search for a local office.
- Direct loans are capped and restricted. Applicants must show they cannot get credit elsewhere at reasonable rates and terms, so most buyers cannot simply choose this rate. FSA lists direct operating loans up to $400,000, and farm equipment is a listed use.
- Guaranteed loans are priced by the lender. FSA can guarantee operating loans up to $2,558,000, and the rate and terms are negotiated between lender and applicant, within FSA maximums.
- Commercial pricing starts elsewhere. The bank prime rate stood at 7.00% in the Federal Reserve H.15 release of 4 November 2026. Prime is a base rate for short-term business loans, not an equipment quote. Your rate depends on credit, term, machine age and lender.
Dealer and captive-finance offers are often quoted as a payment rather than a rate. Ask for the annual percentage rate in writing and convert every offer to that basis, or you cannot compare them. Our roundup of farm equipment loan terms and lender types covers the lender categories.
Farm machinery lease vs loan, line by line
Leasing and buying differ on more than the monthly number. Kansas State University’s Leasing vs. Buying Farm Machinery notes that a lessee still pays insurance, operating costs and repairs not covered by warranty, much as an owner does. The main differences are how the financing works and who holds title.
| Line | Lease | Buy with a loan |
|---|---|---|
| Cash at signing | First payment and fees, per the lease schedule | Down payment set by the lender, plus sales tax where it applies |
| Cost of money | Built into the lease rate and residual; ask for it as an APR in writing | Stated. FSA direct operating was 5.625% effective 1 Nov 2026; other lenders set their own |
| Value risk | Lessor carries it on a fair-market-value lease; you carry it on a $1 buyout | You carry it. Used tractor asking prices fell 5.85% in the year to Dec 2025 |
| Balance sheet | Leases over 12 months generally show as a right-of-use asset and a liability under FASB ASC 842 | Asset on one side, loan on the other |
| Tax | True lease: payments deducted as made. A disguised sale is treated as a purchase | Section 179 up to $2,560,000 for tax years beginning in 2026, plus bonus depreciation |
| Usage limits | Often annual hour or acre caps with overage charges; check your contract | None from the loan itself; lender terms still apply |
| Repairs | Yours unless the schedule or warranty covers them; return standards apply | Yours |
| Fit | Short replacement cycles, fast-changing technology, capacity needed for a few seasons | Core machines kept past the lease term; operations that can use the deduction |
The balance sheet line deserves a second look. Older guides say that leases stay off the books. For US GAAP reporters, ASC 842 changed that, and private companies now apply it. If your covenants use total liabilities or a debt-to-asset ratio, ask your accountant what a five-year lease does to those ratios before you assume that a lease protects your borrowing base. Farms that do not report on GAAP should ask their lender how it treats leases.
The method for settling the choice comes from the same Kansas State paper by Dhuyvetter, Williams and Dumler (October 2010): put both options on a common cash-flow footing over the same period and compare present values. The calculator below is a simpler version you can run at the dealer’s desk. Run the full present-value version with your adviser before a large deal.
Break-even lease payment calculator
Enter the purchase price, loan terms and expected trade value. The tool returns the annual lease payment at which owning and leasing cost the same in simple dollars. It then compares that figure with your quote.
Try the numbers for your own farm below.
Calculator
What annual lease payment breaks even with buying?
Enter your own price, loan and trade figures, then your lease quote.
- Quote minus break-even (above zero favors buying): $454
- Annual loan payment: $39,546
- Net cost of owning over the term: $117,732
- Total lease payments over the term: $120,000
Example values only, set near break-even; they are not a quote, a benchmark or a forecast. Assumes annual loan payments and simple dollars with no discounting. It leaves out section 179 and bonus depreciation, sales and property tax, insurance, repair differences, lease-end buyouts, overage charges and any return on the down payment. The rate is an example, use your lender’s quote.
What the machinery market means for your quote
Tractor sales have been falling for four years. US farm tractor sales went from 317,944 in 2021 to 195,857 in 2025 (preliminary), a drop of 38.4%. Combine sales went from a peak of 7,349 in 2023 to 3,579 in 2025, a drop of 51.3%. Both series are Association of Equipment Manufacturers data compiled in farmdoc daily (16):33, University of Illinois, 27 February 2026.
Chart
US self-propelled combine unit sales
Units per year, 2025 preliminary
Chart
US farm tractor unit sales
Units per year, 2025 preliminary
Deere expected more of the same in 2026. In its second-quarter release of 21 May 2026, Deere forecast large agriculture demand in the US and Canada down 15% to 20% for its fiscal year. A weak market may give a cash or loan buyer room to push on price, although USDA’s index of machinery prices paid by farmers was still up 0.8% in the year to December 2025, as the farmdoc article reports. A lessee can push too, but ask how the residual was set, because the residual moves the payment as much as the price does.
The dealer survey in the farmdoc report shows how the mood is shifting. Dealers expect fewer declines in 2026 than they reported in 2025, on both new and used equipment.
A forecast is not a price, and this is not a recovery signal: the farmdoc article itself concludes the factors suggest a prolonged downturn. Check current unit data before you time a purchase: the Association of Equipment Manufacturers publishes tractor and combine reports each month, and one month in a small category such as combines can swing a long way without marking a trend.
Chart
Dealers reporting or expecting sales declines
Share of surveyed dealers, declines of 2% or more
Used equipment financing and dealer stock
Used machines change the sums on both sides, since the same used values feed a lease residual and your own trade estimate. Sandhills data for December 2025, reported in the farmdoc article, shows tractors and combines moving differently.
| Used market, Dec 2025 | Tractors, year on year | Combines, year on year |
|---|---|---|
| Inventory | Down 15.5% | Down 9.5% |
| Asking prices | Down 5.85% | Down 0.37% |
| Auction values | Down 2.54% | Up 7.47% |
Two uses for that table. First, soft tractor values are a risk to any trade estimate you type into the calculator, so test a lower number. Second, firmer combine auction values give a combine lessee a reason to ask for a higher residual, which lowers the payment. These are December figures, so get current auction results for your exact class before relying on them.
Manufacturers also cut stock. Census Bureau data cited by farmdoc shows manufacturers’ total farm machinery and equipment inventories (seasonally adjusted value) going from about $7.23 billion in October 2022 to $5.72 billion in December 2025, down 20.84%, though the value had been rising in recent months. Tariffs add to manufacturers’ costs. Deere reported about $600 million of tariff cost in fiscal 2025 and projected about $1.2 billion for fiscal 2026, and AGCO expected up to $110 million in 2026 against $40 million in 2025. The Supreme Court’s February 2026 ruling against tariffs imposed under the International Emergency Economic Powers Act may ease that pressure, the same article notes, if manufacturers secure refunds and avoid future levies. The article also warns that a new 10% tariff under Section 122, potentially rising to 15%, has renewed the uncertainty.
Lenders may treat older machines differently on term and down payment, so ask for the used-equipment terms before you settle on a machine. Our note on used tillage equipment trends covers what to look at for that class. Readers outside North America can compare a different dealer market in our guide to farming equipment in South Africa.
The tax line to check before you choose
For tax years beginning in 2026, the most a taxpayer can elect to expense under section 179 is $2,560,000, and the limit phases down dollar for dollar once section 179 property placed in service exceeds $4,090,000. Both amounts are in IRS Revenue Procedure 2025-32. The 2025 tax law also permanently restored full bonus depreciation, according to the American Farm Bureau Federation’s summary.
Those deductions follow ownership. Under a true lease you deduct the payments as you make them. The catch is that the label on the contract does not decide this. IRS Publication 225 says that an agreement may be a conditional sales contract rather than a lease, based on intent and the facts. Warning signs it lists include:
- part of each payment builds an equity interest for you;
- you get title after a stated amount of payments;
- you pay much more than the fair rental value;
- you can buy the machine at a nominal price, such as a $1 buyout;
- part of the payments is named as interest or is easy to spot as interest.
If the contract is a conditional sale, the payments are not deductible as rent, and you treat the machine as purchased. IRS Publication 946 adds that you can depreciate leased property only if you keep the incidents of ownership. Ask your preparer which side of the line your contract falls on.
A large deduction is worth more in a high-income year, so timing matters. USDA forecast 2026 net farm income at $158.4 billion, down 2.6% from 2025 in nominal terms, and net cash farm income at $176.4 billion, up 0.4%, in the Economic Research Service forecast updated 3 September 2026. That is a sector average and it says little about your farm. Use your own expected income, and place the machine in service in the tax year you mean to claim it.
In the UK, the Annual Investment Allowance is £1 million, per GOV.UK guidance. The page says hire purchase items can be claimed for all payments from when you start using them, but not the interest. Check how a lease is treated with your accountant.
Farm equipment financing in Canada
One federal tool in Canada is a loan guarantee. Under the Canadian Agricultural Loans Act program, the government guarantees the lender repayment of 95% of a net loss on an eligible loan. The aggregate limit for one farm operation is C$500,000, with up to C$350,000 for purposes other than land and buildings, which includes machinery. The program’s own example: a C$300,000 tractor loan leaves room for a further C$200,000 for land or building work.
Your lender sets the rest of the terms, so get quotes from your bank or credit union, Farm Credit Canada and the dealer’s finance arm, and compare them as APRs. The calculator works in Canadian dollars too. The US tax limits above do not apply; ask your accountant about capital cost allowance and how your lease will be treated.
Finding a farm equipment lender in your county
Searches for financing in one town, such as Topsham, Maine or Champaign, Illinois, are really two lookups: which FSA office covers you and which Farm Credit association serves your county.
- FSA office. The USDA service center locator finds offices by state and county. For Topsham choose Maine and Sagadahoc County. For Champaign choose Illinois and Champaign County.
- Farm Credit association. The Farm Credit Administration directory and map, updated 13 March 2026, shows the system’s banks and the associations they fund across the CoBank, AgriBank, Farm Credit Bank of Texas and AgFirst districts.
Maine readers get the same FSA direct rate as a Kansas borrower. What differs is the commercial and Farm Credit pricing, so get at least two quotes and compare them as APRs.
Central Illinois readers have a benchmark to test payments against. The University of Illinois publishes Illinois crop budgets by region, with per-acre machinery lines. The handbook page is dated May 2026. The earlier 2026 budgets, published in August 2025, projected stable power costs, with small increases in machinery repairs and hire or lease offsetting lower economic depreciation per acre. Divide a proposed payment by your acres and compare it with the machinery lines for your productivity class. A payment well above them is a reason to ask whether you need that much machine. Machinery cost is only one part of the decision, so treat this as a check and not as a verdict.
Size the machine to the crop you actually harvest
Planted acres can overstate the work a harvester will do. If part of a field yields far below plan, a capacity estimate based on nameplate acres will overstate the tonnage, and you could end up paying for capacity you do not use. Check two or three seasons of yield maps and field records before choosing a machine size or an acre cap.
Leaf yellowing is one crop sign to read with care. Under nitrogen shortage, plants break down chloroplast proteins and chlorophyll and move the nitrogen to younger tissue, so older leaves tend to yellow first, as a 2022 review in Frontiers in Plant Science explains. Water stress, disease and normal end-of-season aging can also cause yellowing. Satellite vegetation indices show the change in the canopy but not its cause, so walk the field too.
Farmonaut offers satellite vegetation maps of your own fields, which you can read with your yield records when you estimate capacity. If you model machinery decisions in a spreadsheet, the satellite and weather API can feed field indices in, and the API developer docs cover the setup.
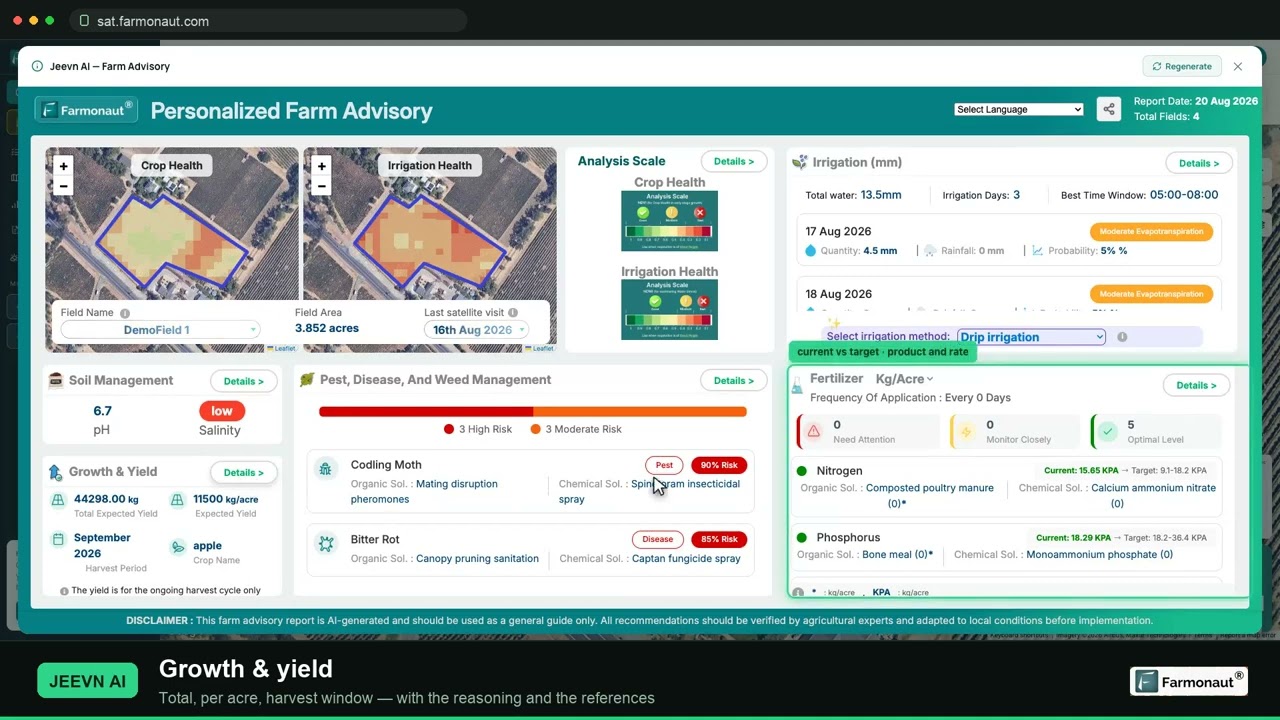
▶ A walkthrough of satellite crop monitoring and how to read NDVI maps for your own field. · 19:36
Eight checks before you sign an equipment lease or loan
Rates and unit counts go stale. This sequence does not.
- Convert every offer to an APR. Lease rate factors and monthly payments cannot be compared. Ask for the implicit rate in writing.
- Pull the current FSA rate. It is a public reference point, reissued monthly. Ask a lender to explain a large gap, while remembering that FSA has its own eligibility rules and limits.
- Work out the break-even annual payment. Use the calculator above or a spreadsheet, and test a lower trade value.
- Check used values for your machine class. Tractors and combines moved in opposite directions at auction in the year to December 2025.
- Read the usage schedule. Hour or acre caps and return standards can change the economics of a lease.
- Ask about covenants. Find out how your lender treats the lease in your ratios.
- Confirm the tax treatment. Ask your preparer about section 179, bonus depreciation and conditional-sale risk for the year the machine goes into service, not the year you order it.
- Size capacity to harvested yield. Use records from recent seasons, not just planted acres.
▶ Six plain steps to start precision agriculture without buying a robot. · 4:18
FAQ
Is farm equipment leasing cheaper than buying?
In simple dollars, only when the annual lease payment is below the break-even figure: the net cost of owning over the same term, divided by the years. Tax and the timing of payments can change the answer. That figure depends on the price, your loan rate and the trade value, so it is specific to the machine and to you.
What interest rate should I expect on ag equipment financing?
FSA direct rates effective 1 November 2026 were 5.625% for Farm Operating and 6.250% for Farm Ownership, but only for borrowers who cannot get credit elsewhere at reasonable rates and terms. Guaranteed, commercial and dealer loans are priced by the lender, and US bank prime was 7.00% on 4 November 2026. Get written quotes for your own machine and credit.
Does leasing keep equipment off my balance sheet?
Generally not for leases over 12 months if you report under US GAAP, because ASC 842 requires a right-of-use asset and a lease liability. Ask your accountant and lender how your own statements treat a lease.
Can I claim Section 179 on leased farm equipment?
Not on a true lease, since you do not own the machine; the payments are deducted instead. A contract treated as a conditional sale, as with some $1 buyouts, is handled as a purchase. Ask your preparer which one you are signing.
How do I find farm equipment financing near me?
Use the USDA service center locator for your FSA office and the Farm Credit Administration directory for the association serving your county. In Canada, ask a lender about the Canadian Agricultural Loans Act program.
Can I finance used farm equipment?
Yes. FSA lists farm equipment as a use of operating loans without limiting it to new machines, and commercial lenders and dealers also quote on used machines. Terms vary with age and condition, so ask for them before you commit to a machine.
Where to go from here
Work out the break-even payment from your own price, term and trade estimate. Pull this month’s FSA rate and the latest tractor and combine report, so you know the market you are negotiating in. Then size the machine to the yield your fields deliver, not the acres you plant.
Farmonaut crop monitoring
See your own fields from space
Draw your fields once and Farmonaut shows satellite vegetation maps for them through the season, on web, Android or iOS.




Keep reading
Sources
- USDA FSA, November 2026 lending rates: fsa.usda.gov
- USDA FSA, August 2026 lending rates: fsa.usda.gov
- USDA FSA, Farm Operating Loans: fsa.usda.gov
- USDA FSA, Guaranteed Farm Loans: fsa.usda.gov
- Federal Reserve, H.15 Selected Interest Rates (4 November 2026): federalreserve.gov
- Kansas State University, Leasing vs. Buying Farm Machinery, MF-2953 (2010): agmanager.info
- farmdoc daily (16):33, University of Illinois, US farm machinery market (February 2026): farmdocdaily.illinois.edu
- Deere and Company, second-quarter results (21 May 2026): prnewswire.com
- IRS, Revenue Procedure 2025-32: irs.gov
- American Farm Bureau Federation, One Big Beautiful Bill Act agricultural provisions (2025): fb.org
- IRS, Publication 225, Farmer’s Tax Guide: irs.gov
- IRS, Publication 946, How To Depreciate Property: irs.gov
- USDA ERS, Highlights from the Farm Income Forecast (3 September 2026): ers.usda.gov
- GOV.UK, Annual Investment Allowance: gov.uk
- Agriculture and Agri-Food Canada, Canadian Agricultural Loans Act program: agriculture.canada.ca
- USDA farmers.gov, service center locator: farmers.gov
- Farm Credit Administration, FCS directory and map (March 2026): fca.gov
- University of Illinois, farmdoc crop budgets by region: farmdoc.illinois.edu
- farmdoc daily, 2026 Illinois Crop Budgets (August 2025): farmdocdaily.illinois.edu
- Sakuraba, nitrogen starvation-induced leaf senescence, Frontiers in Plant Science (2022): frontiersin.org
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Zerella Group
 Agroes
 Etech Consulting Madagascar
 Vestlandsforsking
 Agritein
 Delicio
 WB Dev
 Sama Premium
 Prochecker
 Tres Valles
 LACOS Geoinformation
 Magrifly
 LatConnect 60
 WebsEdge
 Blickwinkel
 Agricultural Credit Policy Council
 Marei Nursery
 eKGIS
 Mostas Tech
 Andex

 Exploration consultancy · South Africa · Gold
 Licence holder · Niger · Gold
 Licence holder · Nigeria · Gold + lithium
 Client · Tanzania · Gold










