

Ag Loans & Farm Loans: Types, Rates, and How to Qualify
Reviewed September 2026 against USDA Farm Service Agency (FSA) and USDA National Agricultural Statistics Service (NASS) data.
Try it: Run your own numbers →
An ag loan is credit extended for farm operations, land purchase, or equipment, typically through USDA’s Farm Service Agency, Farm Credit System lenders, or commercial banks. In fiscal year 2025, USDA FSA alone issued 28,000 direct and guaranteed farm loans totaling $6.7 billion, with $3.53 billion of that going to beginning farmers. The right loan type depends on what you’re financing — land, seasonal operating costs, or equipment — and each carries a different rate, term, and collateral requirement, which this guide breaks down with current figures.
Contents
- What Counts as an “Ag Loan”
- USDA Farm Loans: Direct and Guaranteed
- Farm Land Loans
- Types of Agriculture Loans Compared
- Small Farm and Beginning Farmer Loans
- Sustainable and Conservation Ag Financing
- Regional Banks, Credit Unions, and Farm Credit System
- Farm Equipment Loans
- ANZ Farm Loans, FFA Loans, and Non-US Options
- Loan Repayment Calculator
- Strengthening a Loan Application with Farm Data
- Application Process
- FAQs
- Conclusion
What Counts as an “Ag Loan”
“Ag loan,” “agricultural loan,” and “farm loan” are used interchangeably to describe any credit product built specifically for agricultural producers — as distinct from a general small-business loan. That distinction matters because agricultural lenders underwrite against farm-specific realities: seasonal cash flow, land as the dominant collateral class, commodity price exposure, and weather risk. In the United States, three lender categories cover almost all agricultural financing options: USDA’s Farm Service Agency (direct lending and loan guarantees), the Farm Credit System (a network of cooperative lenders including entities that operate under names like Farm Credit Services or, in some regions, credit associations sometimes referenced informally as “ffa farm loans” by borrowers confusing the Farm Credit brand with FFA the youth organization — the two are unrelated), and commercial banks with dedicated ag lending desks.
Whichever lender you approach, agriculture financing options split along two axes: what the money is for (land, operating costs, equipment, conservation) and how long you need it (short-term operating lines versus long-term real estate mortgages). Get the axis wrong — for instance, using a 5-year operating loan to buy land — and either the lender will decline the mismatch or you’ll be refinancing sooner than planned.
USDA Farm Loans: Direct and Guaranteed
For US producers, USDA’s Farm Service Agency is the anchor of federal agricultural lending. FSA offers two structures: direct loans, where USDA itself is the lender, and guaranteed loans, where a commercial bank or Farm Credit lender originates the loan and USDA guarantees a portion against default, allowing the private lender to extend credit it otherwise wouldn’t.
As of the September 2026 lending-rate announcement, FSA direct loan rates stood at 5.25% for Farm Operating Loans and 6.00% for Farm Ownership Loans. Two blended-rate options bring costs down further for qualifying borrowers: the Joint Financing Farm Ownership Loan at 4.00%, and the Down Payment Farm Ownership Loan at 2.00%. These rates are set monthly — FSA publishes the update on the 1st of each month at its news page, so if you’re reading this more than a few weeks after September 2026, check FSA’s farm loan programs report for the current figure before you budget against the number above.
- Farm Ownership Loans: purchase, expand, or improve farmland and buildings.
- Farm Operating Loans: seed, fertilizer, equipment, livestock, and working capital for the season.
- Microloans: streamlined underwriting for small and niche operations, capped at $50,000.
- Farm Storage and Facility Loans: on-farm storage, drying, and handling infrastructure.
- Conservation Loans: fund practices tied to an approved conservation plan.
Scale matters here. FSA’s fiscal year 2025 totals show 15,552 loans — 56% of everything FSA issued — went to beginning farmers, worth $3.53 billion, and a further $141 million funded veteran farmers specifically. If you’re a first-generation or first-time operator, that 56% share is the clearest evidence that FSA’s beginning-farmer set-asides aren’t a token category; they’re the majority of the direct/guaranteed book. Rate context for these programs, updated whenever USDA revises them, is also tracked in Farmonaut’s USDA and RD interest rate guide, alongside the Farm Service Agency loan management guide and the USDA farm loan aid overview.

Lenders increasingly accept satellite-verified field records as supporting documentation for loan and insurance underwriting. Farmonaut’s crop loan and insurance solutions generate that kind of field-level evidence for both borrowers and the institutions evaluating them.
Farm Land Loans
A farm land loan finances the purchase, refinance, or expansion of agricultural real estate — separate from operating credit because land loans run far longer and use the land itself as collateral. USDA NASS’s 2026 land values summary puts the national average value of farm real estate (cropland and pasture combined) at $4,500 per acre. Split by land type, cropland averages $6,020 per acre and pastureland $2,000 per acre — a threefold gap that reflects productive capacity, not just location. For producers renting rather than buying, NASS also reports the average cropland rental rate at $160 per acre for the 2025–2026 period.
These are national averages; regional values vary well outside that band in both directions, and NASS updates them annually each July. To pull the current figure for your county rather than the national number, go to NASS QuickStats (data.nass.usda.gov), select “Agricultural Prices,” then “Farm Real Estate Values” and the “$/Acre” measure.
- Term structure: typically 10–30 years, fixed or variable rate, with the land as primary collateral.
- Common uses: new acreage purchase, refinancing existing land debt, renewable energy siting, or conservation easement funding.
- Underwriting emphasis: production history, a written business plan, and — increasingly — documented environmental stewardship, which some lenders price into the rate.
Documented sustainability practices can support a land loan application directly. Farmonaut’s carbon footprinting tools and product traceability solutions generate the kind of verifiable environmental record some lenders now factor into terms for conservation-linked land financing.
Types of Agriculture Loans Compared
The table below lines up the main types of agriculture loans available to US producers by rate, size, and term, so you can see how a USDA microloan stacks up against a conventional land mortgage or an equipment note before you talk to a lender.
| Loan Type | Typical Use | Repayment Term | Collateral | Where to Verify Current Rate |
|---|---|---|---|---|
| USDA Direct Farm Operating Loan | Seed, inputs, livestock, working capital | 1–7 years | Crops, chattel, or none for small amounts | FSA monthly rate notice |
| USDA Direct Farm Ownership Loan | Buy, expand, or improve farmland | Up to 40 years | Real estate | FSA monthly rate notice |
| USDA Guaranteed Farm Loan | Land or operating, via a private lender | 7–30 years | Real estate, equipment, or crops | Originating bank + FSA guarantee terms |
| USDA Microloan | Small or niche operations, up to $50,000 | 1–7 years | Minimal, streamlined underwriting | FSA monthly rate notice |
| Conventional Farm Land Loan | Land purchase or refinance | 10–30 years | The land itself | Originating bank or Farm Credit lender |
| Farm Equipment Loan | Tractors, irrigation, precision-ag tech | 2–7 years, matched to depreciation | The equipment financed | Manufacturer finance arm or regional bank |
| Farm Credit System Loan | Land, operating, or equipment | Varies by product | Varies by product | Local Farm Credit association |
Small Farm and Beginning Farmer Loans
Small farm loans and USDA microloans target operations that don’t need — or can’t yet qualify for — a full-size ownership loan. FSA caps microloans at $50,000 and uses simplified paperwork specifically to reach beginning, niche, and specialty-crop producers. The FY2025 numbers above bear this out at scale: beginning farmers received 15,552 of FSA’s loans, or 56% of the total, worth $3.53 billion.
- Typical borrowers: operations under 100 acres, specialty or value-added producers, urban agriculture projects.
- Support beyond capital: FSA and many Farm Credit associations pair microloans with financial education and farm management advisory services.
- Where to start: your local Farm Service Agency office, agricultural credit unions, and community development financial institutions serving your county.
Sustainable and Conservation Ag Financing
A growing share of agriculture financing is tied to a conservation plan rather than a general business plan — USDA’s Conservation Loan Program, state-level green-lending initiatives, and Farm Credit sustainability products all fall here. The underwriting differs mainly in what documentation you provide: soil health data, water-use records, or a carbon plan, in place of (or alongside) a standard production history.
- Funded activities: cover cropping, reduced tillage transitions, water management infrastructure, solar or wind installations, ecological restoration on marginal land.
- What lenders want to see: a written conservation or sustainability plan with measurable outcomes, not just an intent to farm sustainably.
Farmonaut’s carbon footprinting and product traceability tools produce the documented, field-level record that conservation-linked lenders are asking for — turning a verbal claim of sustainable practice into a dataset a loan officer can review.

Regional Banks, Credit Unions, and Farm Credit System
For producers searching “loans for farmers” near their own county, the Farm Credit System, community banks, and credit unions are usually the fastest route, precisely because they underwrite against local knowledge — crop patterns, soil types, and commodity exposure specific to the region — rather than a national template. The Farm Credit System’s loan book has held up well through recent volatility: Farm Credit Associations reported only 0.7% of their agricultural loan portfolio was 30 or more days past due as of September 2023, per Congressional Research Service data compiled by farmdocDaily — a useful benchmark for how conservatively this lender class underwrites relative to headlines about farm financial stress.
- Advantages: faster decisions, repayment schedules built around the harvest cycle, and underwriters who know local land values without a national data pull.
- Loan types offered: seasonal operating lines, farm land loans, small farm loans, and equipment financing, often all from one relationship manager.
- What to bring: production history, local references, and — for larger requests — a written business plan.
Farm Equipment Loans
Farm equipment loans finance tractors, irrigation systems, and precision-ag hardware, structured to track the equipment’s depreciation schedule rather than a standard amortization table. Terms of 2–7 years are typical, and the equipment itself is the collateral, which is why approval turnaround tends to be faster than for a land loan — there’s less to underwrite beyond the asset and a repayment source. Canadian producers comparing lenders can see current options in Farmonaut’s roundup of Canadian agriculture equipment lenders.
- Providers: regional ag banks, equipment manufacturers’ captive finance arms, and credit unions.
- Coverage: new purchases, leases, and retrofits on existing machinery.
Tracking utilization after purchase matters as much as securing the loan — Farmonaut’s fleet management solutions use satellite and AI-driven tracking to document how financed equipment is actually being used, which supports both loan renewal conversations and depreciation records.
ANZ Farm Loans, FFA Loans, and Non-US Options
Australian producers searching “anz farm loans” are typically looking for agribusiness lending from Australia and New Zealand Banking Group, one of Australia’s major agricultural lenders alongside the other big-four banks and regional rural lenders. ABARES (the Australian Bureau of Agricultural and Resource Economics and Sciences) tracks farm debt and lending conditions nationally, and is the authoritative starting point for current Australian ag lending benchmarks — rate and volume specifics for ANZ’s own farm loan products are set by the bank directly and should be confirmed with ANZ or an accredited agribusiness broker rather than assumed from US figures, since Australian and US agricultural lending markets run on different rate cycles, land tenure systems, and government support structures.
On “ffa farm loans”: FFA (the youth agricultural education organization, formerly Future Farmers of America) does not itself originate farm loans. Searchers using this term are almost always looking for one of two things: USDA/FSA lending (the actual federal farm loan programs covered above), or Farm Credit System financing, whose regional associations are sometimes shortened informally to sound similar to “FFA.” If you arrived here searching “ffa farm loans,” the FSA programs in the USDA section above and the Farm Credit System entry in the comparison table are the products you’re likely looking for.
For Canadian producers, equipment-specific financing comparisons are covered in Farmonaut’s Canadian agriculture equipment lender guide; broader farm lending benchmarks for Canada are published by Statistics Canada and Farm Credit Canada, and should be checked directly rather than assumed to mirror US USDA figures.
Loan Repayment Calculator
Estimate a monthly and total repayment figure for any of the loan types above by entering the amount, rate, and term yourself.
Run your own numbers
Assumes a standard fixed-rate amortizing loan with equal monthly payments; excludes origination fees, guarantee fees, insurance, and any balloon structure. USDA rates shown in the dropdown are FSA’s direct loan rates as of the September 2026 announcement — confirm the current rate at FSA before using this for a real application.
Strengthening a Loan Application with Farm Data
Lenders underwriting a farm loan are ultimately pricing risk against production evidence, and satellite and AI-based monitoring now supply a documented record that used to rely on self-reported figures.
- Satellite-based crop monitoring: multispectral imagery tracking vegetation health and field productivity — supporting material for a loan or insurance claim. See how satellite verification supports crop loans and insurance.
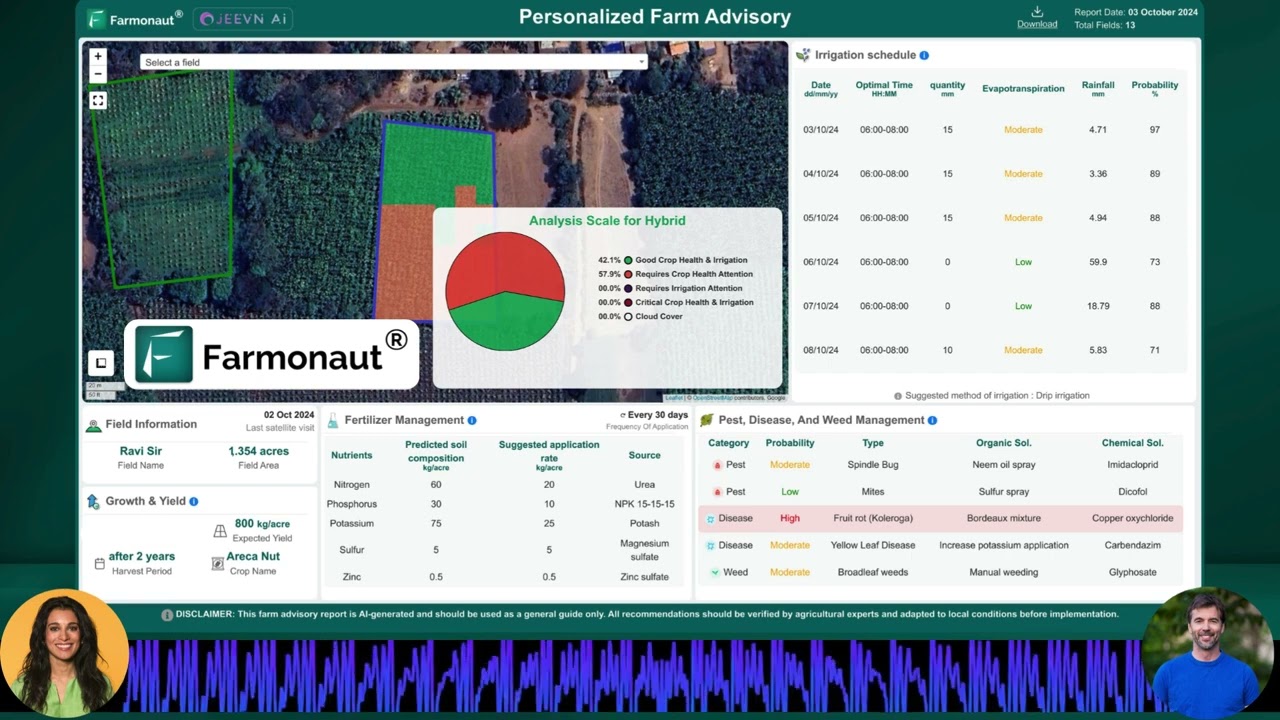
- AI advisory (Jeevn AI): data-driven recommendations on input planning and risk reduction that can support the “sound repayment plan” criterion lenders look for.
- Blockchain traceability: supply chain transparency that some sustainability-linked and traceability-linked financing products now require as documentation. Explore Farmonaut’s traceability solutions.
- Fleet and resource management: equipment utilization tracking that helps justify an equipment loan renewal or upgrade request. See fleet management capabilities.
- API and developer tools: for lenders or agribusinesses integrating field data directly, Farmonaut’s API delivers crop data programmatically; see the API developer docs for onboarding.

Application Process
- Identify the purpose: land, operating costs, equipment, conservation investment, or refinancing — each maps to a different product in the table above.
- Check eligibility: credit history, farming experience, entity structure, and — for USDA programs — citizenship or legal residency status.
- Gather documentation: tax returns (3+ years is standard), production and income records, a written business plan, collateral appraisals, and any conservation or sustainability plan relevant to the loan type.
- Compare lenders: USDA/FSA, Farm Credit System, regional banks, and credit unions — using the comparison table above as a starting checklist.
- Bring supporting field data: Farmonaut’s monitoring and reporting tools can generate documentation that speeds review, particularly for sustainability-linked terms.
- Submit and respond quickly: lenders will follow up on repayment source (typically crop or livestock income) and, increasingly, technology adoption.
- Close and manage: use a digital dashboard to track milestones and prepare renewal documentation ahead of the next cycle.
For producers investing in forestry, carbon farming, or regenerative practices specifically, the Farmonaut crop, plantation, and forest advisory platform helps document practices that qualify for climate-linked financing terms.
FAQs
- What’s the difference between an “ag loan” and an “agricultural loan”?
- None — they’re the same product category, referred to differently by lender, region, or borrower habit. Both cover USDA, Farm Credit, and commercial bank products built for farm operations.
- What are the types of agriculture loans available to a first-time borrower?
- USDA microloans (capped at $50,000) and Farm Operating Loans are the most accessible entry points; 56% of FSA’s FY2025 loan volume went to beginning farmers specifically, so these products are built to be used by new operators, not just available to them on paper.
- What is the current USDA farm loan interest rate?
- As of the September 2026 FSA announcement: 5.25% for direct Farm Operating Loans, 6.00% for direct Farm Ownership Loans, with blended rates of 4.00% and 2.00% for Joint Financing and Down Payment Ownership Loans respectively. These are reset monthly — check FSA’s rate notice directly for the current figure.
- Are “anz farm loans” the same as USDA farm loans?
- No. ANZ is an Australian bank offering agribusiness lending under its own terms, separate from the US federal USDA/FSA system. Australian producers should confirm current rates and products with ANZ or ABARES rather than referencing US figures.
- Does FFA offer farm loans?
- No — FFA is a youth agricultural education organization and does not originate loans. Searchers using this term are typically looking for USDA/FSA programs or Farm Credit System financing, both covered above.
- How do I find “loans for farmers” near me?
- Start with your local USDA Farm Service Agency office, then compare a regional Farm Credit association and a community bank or credit union with an ag lending desk — all three typically serve the same county with different underwriting styles.
- Can agriculture financing cover technology investments?
- Yes — equipment loans and some operating loans cover precision-ag hardware, remote monitoring systems, and farm management software.
- Will lenders accommodate seasonal, uneven income?
- Yes. Most agricultural operating loans are structured with repayment aligned to harvest timing rather than equal monthly installments.
Further reading:
Conclusion
Matching the loan to the purpose is the single decision that matters most: a USDA Farm Operating Loan for seasonal inputs, a Farm Ownership Loan or conventional land mortgage for real estate, an equipment loan tied to depreciation for machinery, and a Farm Credit System or regional bank relationship when local underwriting and speed matter more than the lowest posted rate. USDA’s FY2025 numbers — $6.7 billion across 28,000 loans, 56% of them to beginning farmers — show federal lending remains a real, heavily used channel rather than a marginal option, and the rate table above gives you the current benchmark to compare any other offer against.
- Compare at least two lender types (USDA/Farm Credit and a commercial bank) before committing.
- Match loan term to asset life — short for operating costs, long for land, matched-to-depreciation for equipment.
- Use documented field and sustainability data to strengthen conservation-linked or standard applications alike.
- Recheck FSA’s rate notice and NASS land values before finalizing any numbers — both update on a fixed published schedule, not annually at random.
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 WICO
 Gen Chayat
 Chimera Innovation
 Hiteshi Infotech
 Clubhouse OS
 SkyHarvest
 Polaris Digitech
 Teledarbas
 Wild Oak Farm
 SFX
 BACF Africa
 Doodlakine
 Exurbia Geospatial
 FieldZero
 Indico Company

 Licence holder · Niger · Gold










