

Reviewed August 2026 against the USDA Economic Research Service, the U.S. Government Accountability Office, and NASA/USGS Landsat program data.
Try it: Satellite Pass Estimator for Your Growing Season →
Big data in agriculture means fusing satellite imagery, machine telemetry, soil sensors, and weather records into decisions a farm can act on the same week. It is not a future promise: the U.S. Government Accountability Office found that 27% of U.S. farms had already adopted some form of precision agriculture as of mid-2023, and the technology stack behind that number — guidance systems, yield mapping, variable-rate inputs — is what most people mean when they search for big data analysis in agriculture. This piece lays out the adoption numbers, the data sources feeding them, and the specific companies selling the tools.
What “Big Data” Means in Agriculture Right Now
The phrase covers five overlapping streams: satellite and drone imagery, in-field IoT sensors (soil moisture, pH, temperature), machinery telemetry (planting rate, fuel use, tillage passes), weather station networks, and market or logistics records. What makes it “big” is not just volume — it’s that these streams update on different clocks (a soil sensor every few minutes, a satellite every 8–16 days, a USDA acreage report once a season) and have to be reconciled before a recommendation is useful.
The commercial side of this is growing at a measurable rate. According to The Business Research Company’s global market report, published in July 2026, the big data analytics in agriculture market was valued at $1.46 billion in 2025, grew to $1.65 billion in 2026 (a 13.0% year-over-year rate), and is projected to reach $2.56 billion by 2030 at an 11.5% compound annual growth rate. That is a market-research estimate, not a government figure — treat it as directional, and check the same report page for the current-year update since these estimates get revised as new data lands.
How Big Data Analysis in Agriculture Actually Works
Big data analysis in agriculture starts with a data-collection layer and ends with a recommendation engine, but the part farmers actually feel is the update cadence. Free public satellite data is the backbone: NASA’s Landsat program revisits the same ground location every 16 days with a single satellite, or every 8 days now that Landsat 8 and 9 fly together. NASA states that Landsat’s free, open data policy contributed an estimated $25.6 billion to the U.S. economy in 2023 alone, and USDA’s National Agricultural Statistics Service has drawn on Landsat imagery since 2009 to build its annual Cropland Data Layer — a once-a-season map of what was planted where.
That mismatch in cadence matters: a farmer chasing a fast-moving pest or nitrogen deficiency cannot wait out a 16-day satellite gap, which is why platforms blend satellite passes with in-field sensors (near-continuous) and drone flights (on demand, weather permitting) to fill the space between images. The chart below lines up the three cadences that most U.S. row-crop data pipelines still depend on.
Satellite Pass Estimator for Your Growing Season
Assumptions: this estimates theoretical Landsat overpasses only, not commercial constellations, drone flights, or radar (which sees through cloud cover). It does not account for orbital path overlap at your specific latitude, sensor outages, or partial cloud cover over part of a field. Use it to compare revisit strategies, not as an exact schedule.
Precision Agriculture Adoption, By the Numbers
Adoption is uneven, and the size of the farm is the single biggest predictor. The GAO’s January 2024 report put overall U.S. adoption of any precision agriculture practice at 27% of farms as of mid-2023, while USDA’s Economic Research Service, drawing on the 2023 Agricultural Resource Management Survey, found automated guidance or auto-steer systems on 70% of large-scale crop-producing farms and 52% of midsize farms. Yield monitors, yield maps, and soil maps together were in use on 68% of large-scale crop farms. Two decades earlier, guidance system adoption on these same farms was in the single digits, so this is a real technology transition, not a plateau.
Adoption also depends heavily on which crop and which technology you’re asking about. USDA’s February 2023 report “Precision Agriculture in the Digital Era” (using data through 2019) found automated guidance on well over half of the combined acreage planted to corn, cotton, rice, sorghum, soybeans, and winter wheat — but yield maps, soil maps, and variable-rate technology reached only 5% to 25% of total planted acreage for winter wheat, cotton, sorghum, and rice specifically. Guidance systems are the easy win; input-mapping technologies are the harder sell.
| Technology | Farm segment | Adoption rate | Source & date |
|---|---|---|---|
| Any precision-ag practice | All U.S. farms | 27% | GAO-24-105962, data as of mid-2023, published Jan. 2024 |
| Automated guidance / auto-steer | Large-scale crop farms | 70% | USDA ERS, 2023 ARMS chart of note |
| Yield monitors + yield maps + soil maps | Large-scale crop farms | 68% | USDA ERS, 2023 ARMS chart of note |
| Automated guidance / auto-steer | Midsize farms | 52% | USDA ERS, 2023 ARMS chart of note |
| Automated guidance | Combined acreage: corn, cotton, rice, sorghum, soybeans, winter wheat | Well over 50% of planted acres | USDA ERS EIB-248, Feb. 2023 (data through 2019) |
| Yield maps, soil maps, VRT | Winter wheat, cotton, sorghum, rice | 5%–25% of planted acres | USDA ERS EIB-248, Feb. 2023 (data through 2019) |

Fewer, Bigger Farms: Why the Data Stakes Keep Rising
Adoption skews toward large operations partly because the number of large operations keeps growing relative to the number of farms overall. The 2022 Census of Agriculture, released by USDA’s Economic Research Service in February 2024, counted 1,900,487 U.S. farms — down 7% from the 2,042,220 farms recorded in the 2017 Census — while total farmland fell a smaller 2.2%, to 880 million acres. The result: average farm size grew from 441 acres in 2017 to 463 acres in 2022, a 5% increase. Fewer, larger operations means each remaining farm manages more acres, more machines, and more data per decision-maker, which is exactly the condition that makes big data tools pay for themselves faster on bigger farms and slower on smaller ones.
Where the Data Pays Off: Inputs, Pests, Supply Chains, Climate
Resource Management and Cost Control
Soil sensors and moisture mapping feed the variable-rate irrigation and fertilizer schedules that the adoption numbers above are measuring. For large operations coordinating multiple fields and machines, that data extends naturally into fleet management — tracking which machine covered which acres, and when, against the same field-level records used for input planning.
Pest and Disease Control
Satellite and drone imagery, layered with the sensor data above, is what lets an operation flag a stressed zone within a field before it’s visible from the road. The value of catching an outbreak early is well documented in agronomy literature at the field-trial level; what’s harder to find is a single reliable national percentage for “pest losses avoided,” so treat any such figure you see elsewhere with a source check, and rely instead on your own field records year over year.
Supply Chain and Traceability
Big data’s role in the supply chain is provenance and routing: linking a harvested lot back to the field it came from, and using live logistics data to route it. Blockchain-based traceability tools exist specifically to make that chain-of-custody record tamper-resistant, which matters more as buyers and export markets ask for documented origin rather than a supplier’s word.

Sustainability and Climate Resilience
Environmental monitoring and emissions accounting are the newest big-data workload in agriculture, driven by buyer sustainability requirements and voluntary carbon markets rather than by yield alone. Carbon footprinting tools use the same satellite and field-record inputs described above to estimate emissions per acre and track change over time, which is the baseline a farm needs before it can document a reduction to a buyer or a carbon program.
Agriculture Big Data Companies: Who Provides What
“Agriculture big data companies” is not one market — it splits into machinery-tethered platforms, seed-agnostic overlay platforms, and satellite-first platforms that need no hardware purchase at all. The table below names the major players in each lane. Where a company doesn’t publish a verifiable aggregate figure, we say so rather than guess — check the company’s own newsroom or investor relations page for the current number.
| Company / platform | Data lane | Verified scale figure | Best fit |
|---|---|---|---|
| Deere & Company — Operations Center | Machinery telemetry + agronomic records | No single public aggregate acreage figure found; ask a dealer for regional numbers | Row-crop farms already running Deere equipment |
| Bayer — Climate FieldView | Satellite + weather + as-planted/as-harvested data fusion | “Hundreds of millions of acres, across dozens of countries,” per Climate Corporation’s own account, 2024; the underlying Climate Corporation was acquired by Monsanto in 2014 for $1 billion | Seed-agnostic overlay analytics across brands of equipment |
| Trimble — Ag software and GPS hardware | Guidance + variable-rate hardware integration | No public aggregate acreage figure found | Farms centered on guidance and VRT hardware |
| Corteva — Granular | Farm financial and agronomic record-keeping | No public aggregate acreage figure found | Financial and agronomic record-keeping in one system |
| Farmonaut | Satellite crop health, AI advisory, traceability, carbon accounting | API-accessible per-acre monitoring; no proprietary hardware required | Operations wanting hardware-free entry, from smallholder to enterprise scale |
For the API-first end of that table: Farmonaut exposes its satellite and weather layers directly through a developer API, documented at the API developer docs, so a distributor or agribusiness can pull live satellite data into its own systems rather than adopting a whole new platform. Larger operations managing full crop-production cycles across many fields can do the same work inside the Agro Admin App.
Verified field-level data also underpins crop loan and insurance products: a lender or insurer can underwrite against a documented yield and health history instead of a self-reported one, which is one of the more concrete financial payoffs of keeping consistent records in the first place.
How to Evaluate Any Big Data Agriculture Platform
Adoption numbers and market-size figures will change every time USDA or a market-research firm publishes a new edition. What doesn’t expire is the checklist for judging whether a given platform is worth adopting on your own operation:
- Data portability. Can you export your own field boundaries, yield history, and machine data in a standard format, or is it locked to one vendor’s app? The AgGateway ADAPT standard, built from nearly a decade of industry framework development and partly funded through USDA’s National Agricultural Producers Data Cooperative, exists specifically so equipment from different manufacturers can exchange field and machine data without a proprietary translator in between. Ask any vendor whether they support it.
- Revisit frequency and resolution. Know whether the imagery behind your recommendations updates every few days or once a season, and whether the pixel size matches the decision you’re making — a whole-field average is not the same input as a management-zone map.
- Who owns the data, and can you delete it. Get the data-ownership clause in writing before you sign, not after a dispute.
- Cost per acre, stated plainly. A platform that won’t quote a per-acre or per-subscription price upfront is a platform you can’t budget against.
- Works without new hardware. Confirm whether the platform requires you to buy a specific brand of equipment or sensor, or whether it runs on imagery and records you already have.
Run any vendor pitch through those five points and the marketing language mostly falls away.
Try It: Farmonaut’s Satellite Tools
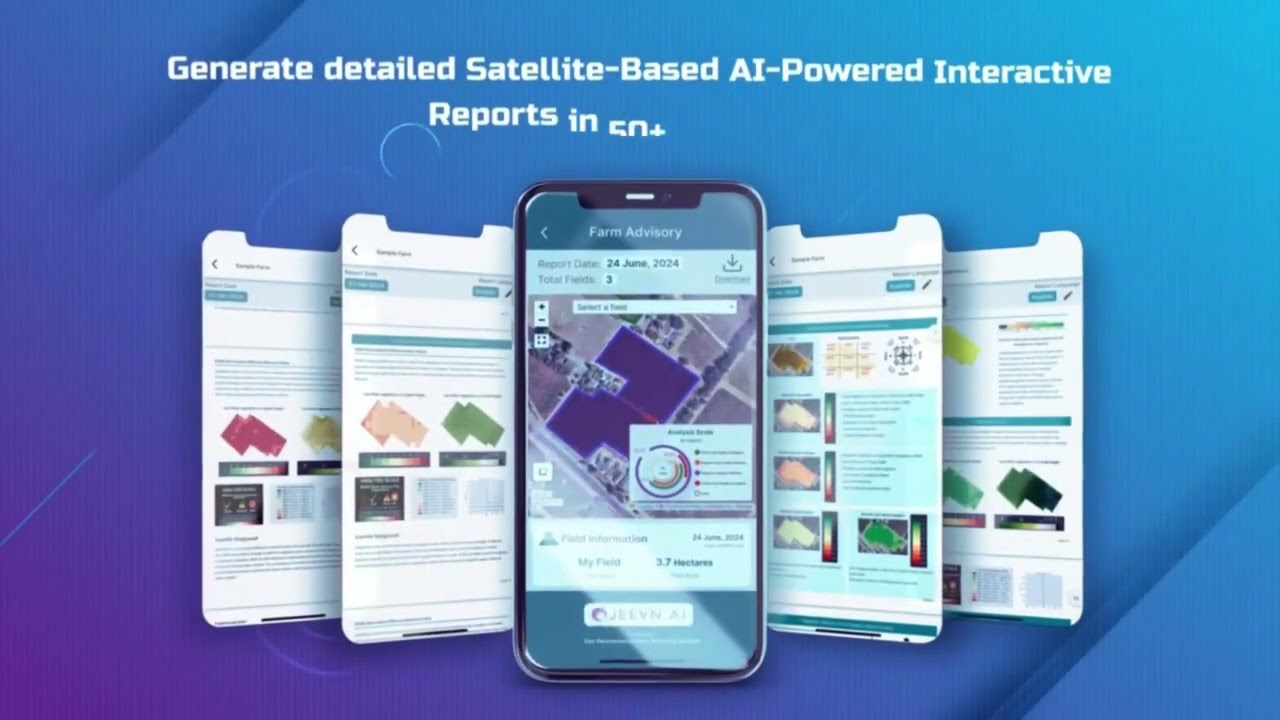
Farmonaut’s own tools follow the hardware-free model described above — satellite crop health monitoring, AI-based advisory (JEEVN AI), and record-keeping accessible from a phone, without requiring new field hardware. The web and mobile app is the fastest way to see a field’s current health index against your own records.



Frequently Asked Questions
What is big data in agriculture?
It is the collection and analysis of large, varied datasets — satellite and drone imagery, IoT soil and weather sensors, machinery telemetry, and market records — to drive field-level and farm-level decisions. See the data-streams section above for how the pieces fit together.
What does big data analysis in agriculture actually involve?
Reconciling data sources that update on different clocks (sensors near-continuously, satellites every 8–16 days, USDA acreage layers annually) into a single recommendation, using machine learning models trained on historical yield, weather, and imagery data.
How many U.S. farms actually use these tools?
27% of U.S. farms had adopted some precision agriculture practice as of mid-2023, per the GAO’s January 2024 report, with adoption rates far higher — 68% to 70% — among large-scale crop-producing farms specifically.
Which companies lead in agriculture big data?
Machinery-tethered platforms (Deere’s Operations Center, Trimble), seed-agnostic overlay platforms (Bayer’s Climate FieldView, Corteva’s Granular), and satellite-first, hardware-free platforms (Farmonaut) cover the three main lanes — see the companies table above for what each does and does not publicly disclose about scale.
Is this only useful for large farms?
Adoption is concentrated on large operations because the payoff scales with acres managed per decision-maker, but hardware-free, API- and app-based tools remove the biggest cost barrier for smaller operations — see Farmonaut’s app for an entry point that doesn’t require new equipment.
Where can I get the source data myself instead of relying on someone else’s summary?
USDA ERS publishes its precision-agriculture adoption chart updates on its Charts of Note page, the Census of Agriculture runs every five years from USDA NASS, and Landsat imagery itself is free through NASA/USGS.

Conclusion
The honest state of big data in agriculture, as of the sources cited above, is this: adoption is real but concentrated, at 27% of all U.S. farms and 68–70% of large-scale crop farms; the underlying data infrastructure — Landsat’s 8-to-16-day satellite revisit, annual USDA cropland layers, near-continuous field sensors — is public and largely free; and the vendor landscape splits cleanly into machinery-tethered, seed-agnostic, and hardware-free lanes. None of those numbers will stay fixed, which is exactly why each one above is tied to its source and its date rather than presented as a permanent fact. Check the linked USDA, GAO, and NASA pages directly the next time these figures matter for a real decision.
Explore Farmonaut’s satellite API and developer documentation to pull the same kind of data described in this article directly into your own systems.

 Godrej Agrovet
 Hayleys Agriculture
 Linx Agritech
 Adinet
 Save Your Soils
 GalaxEye Space
 Grandstream Algérie
 XOS Realty
 Geospatial Lab Africa
 Agro La Gándara
 HIPSAC
 ZOL Zimbabwe
 Juligerm
 AdBio
 MISE Maroc
 NWNS
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 DnCubed
 Indosistim Teknologi
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC
 AgroRisk
 Oath Inc
 Esri North East Africa
 MDCV UK
 Etech Consulting Madagascar
 Vestlandsforsking
 WB Dev
 Sama Premium
 Tres Valles
 Blickwinkel
 Agricultural Credit Policy Council
 eKGIS
 Mostas Tech
 Andex
 Deluxe Conseil
 WICO
 Chimera Innovation
 SkyHarvest
 Teledarbas
 Exurbia Geospatial
 FieldZero

