

Gold equities · Company list
Best Junior Gold Mining Stocks Ranked by Project Stage
Nine North American-listed gold companies ranked from producer to explorer, each with ticker, main asset, stage and a dated source. Includes capital-cost and gold-price charts and a value-per-ounce calculator. Facts only.
Key takeaways
- The list runs from West Red Lake Gold, producing at Madsen, to Altamira Gold, still exploring Cajueiro in Brazil; each entry carries a ticker, asset and dated source.
- Gold averaged $3,442 per ounce in 2025 against $2,388 in 2024 (World Bank, September 2026); Kitco quoted $4,123.60 on 20 October 2026.
- Capital cost estimates range from $394 million to $2,576 million across four projects, on different bases and dates, so financing is a main catalyst for builders (company filings, 2026).
- West Red Lake cut its 2026 Madsen guidance to 27,000 to 32,000 ounces on 27 October 2026, a reminder that producers carry execution risk too.
- Facts from filings and releases, not advice: the page does not say which share to buy, hold or sell. Not investment advice.
In this article
- Best junior gold mining stocks ranked by project stage
- How we chose these nine companies
- Company profiles from producer to explorer
- Next catalysts for each company
- Gold price context for junior valuations
- What it costs to build a mine: capital estimates compared
- A producing junior in practice: Madsen output and guidance
- How do you value junior gold stocks?
- Which gold explorers sit near existing infrastructure?
- What should retail investors know before buying gold juniors?
- What events make investors review a position in gold juniors?
- Junior ETFs and lists: where GDXJ fits
- Takeovers and consolidation
- How satellite screening fits
Best junior gold mining stocks ranked by project stage
The best junior gold mining stocks to research are the ones whose project stage, funding and next milestone you can check in a filing, so this page lists nine companies by how close each is to producing gold, from a mine already pouring ounces to a pure drill programme. Kitco showed spot gold at $4,123.60 per troy ounce on 20 October 2026 (Kitco quote, 20 October 2026), and the World Bank put the 2025 average at $3,442, up from $2,388 in 2024 (World Bank Pink Sheet, September 2026 update).
Every company below is described with facts only: name, ticker, exchange, main asset, stage and a dated source. This is a fact list, not a recommendation. It does not say which share to buy, hold or sell. Prices in this article are in US dollars unless a line says C$.
| Rank by stage | Company | Ticker (exchange) | Main asset | Stage at the source date |
|---|---|---|---|---|
| 1 | West Red Lake Gold Mines | WRLG (TSXV) | Madsen mine, Ontario | Producing; pre-feasibility study due (27 Oct 2026) |
| 2 | Montage Gold | MAU (TSX) | Koné, Côte d’Ivoire | First gold poured 26 Sep 2026; commercial production targeted Q4 (27 Sep 2026) |
| 3 | Skeena Resources | SKE (TSX, NYSE) | Eskay Creek, British Columbia | Construction, over 70% complete (31 Aug 2026, company site) |
| 4 | Perpetua Resources | PPTA (Nasdaq, TSX) | Stibnite, Idaho | Early works; full construction awaits financing (28 Sep 2026) |
| 5 | U.S. Gold Corp. | USAU (Nasdaq) | CK Gold, Wyoming | Permitted; financing under discussion (Aug 2026) |
| 6 | Liberty Gold | LGD (TSX) | Black Pine, Idaho | Feasibility study published (8 Sep 2026); permitting next |
| 7 | Dakota Gold | DC (NYSE American) | Richmond Hill, South Dakota | Pre-feasibility study Q4 (Aug 2026) |
| 8 | Snowline Gold | SGD (TSX) | Valley deposit, Yukon | Preliminary economic assessment (23 Jun 2025); pre-feasibility study due by Q1 2027 |
| 9 | Altamira Gold | ALTA (TSXV) | Cajueiro, Brazil | Exploration with a resource (21 Sep 2026) |
Stage is not quality. A producer can miss guidance, as the Madsen section below shows, and an explorer can find a deposit that a major wants. The table only tells you which risks apply: operating risk for producers, construction and financing risk for developers, geological risk for explorers.
How we chose these nine companies
We wanted names that readers search for and that publish enough to check. A company had to meet four tests.
- Gold is the main project. Companies whose value rests on another metal were left out, which is why copper names are ranked on a separate page (junior copper mining companies).
- A named asset with a dated disclosure. Each has a press release, filing or fact sheet from 2025 or 2026 that states the stage.
- Listed in North America. Each trades on the TSX, TSX Venture, Nasdaq, NYSE or NYSE American, so reporting follows Canadian or US rules.
- Spread across stages. One producer, one mine that has poured its first gold, two builders, two developers with a completed feasibility study, two at the pre-feasibility or economic-assessment stage and one explorer, so the list shows how risk changes along the path to a mine.
The list is a sample, not a complete ranking of the sector. Larger names such as Alamos, Equinox and Endeavour dominate junior-miner funds; the VanEck fund held 160 positions on 14 October 2026 with those three among its five largest (GDXJ holdings, StockAnalysis, 14 October 2026). For a view of the biggest producers, see our top 20 gold mining companies by output. For a plain explanation of the business model, see what junior miners are and how they are financed.
Company profiles from producer to explorer
1. West Red Lake Gold Mines (TSXV: WRLG)
West Red Lake Gold owns the Madsen mine in the Red Lake district of Ontario, which declared commercial production effective 1 January 2026 (West Red Lake Gold release, 12 January 2026). Its release of 27 October 2026 reports 7,859 ounces of gold in the third quarter and 22,102 ounces for the nine months to 30 September, with September the best month since the restart at 3,320 ounces. The company cut its 2026 output guidance to 27,000 to 32,000 ounces from 35,000 to 45,000, citing industry-wide labour problems, and said an integrated Madsen and Rowan pre-feasibility study would come in the following weeks (West Red Lake Gold release, 27 October 2026). The land package is 47 square kilometres, and the Rowan property adds three past-producing mines.
2. Montage Gold (TSX: MAU)
Montage has built the Koné mine in Côte d’Ivoire and is bringing it into production. Its 11 August 2026 update put measured and indicated resources at 6.3 million ounces at 0.80 g/t and inferred resources at 2.0 million ounces at 0.68 g/t (15 June 2026 update). Capital cost is estimated at $885.0 million, with $714.4 million committed by 11 August. Dry commissioning of the oxide circuit began in July. The company poured its first gold on 26 September 2026, about 1,140 ounces, ahead of schedule (Montage Gold release, 27 September 2026). It expects commercial production from the oxide circuit in the fourth quarter of 2026, and the hard-rock circuit is scheduled for the second quarter of 2027. Cash was $154.4 million at 30 June 2026 (Montage Gold Q2 2026 activities, 11 August 2026). The shares also trade over the counter as MAUTF.
3. Skeena Resources (TSX and NYSE: SKE)
Skeena is rebuilding the Eskay Creek mine in British Columbia. On 31 March 2026 it reported the project 49% complete at 28 February, with 66% of project costs committed. The construction cost estimate rose to $659 million from $560 million in the 2023 definitive feasibility study, and leasing the water treatment plant, high-voltage power and camp cut upfront cost by about $94 million. Initial production is targeted for the second quarter of 2027 (Skeena release filed with the SEC, 31 March 2026).
4. Perpetua Resources (Nasdaq and TSX: PPTA)
Perpetua is redeveloping the Stibnite gold-antimony-silver site in central Idaho. Its 28 September 2026 update says federal approvals were secured in 2025, early works and critical-path construction continue, and a 10,000-metre drill programme was passed in August and expanded (Perpetua update, 28 September 2026). The quarterly filing for 31 March 2026 gives direct capital cost at $2,576 million, a proposed export-credit loan of about $2.7 billion that had not yet had a final board vote at that date (the U.S. EXIM board approved a $2.9 billion loan on 21 May 2026, per the company release), and cash of $669.5 million. The company says it will not start full construction until full financing is in place (Perpetua Form 10-Q, 31 March 2026).
5. U.S. Gold Corp. (Nasdaq: USAU)
U.S. Gold Corp. holds CK Gold, a gold-copper project in southeast Wyoming. Its August 2026 update cites a March 2026 feasibility study with an after-tax NPV at a 5% discount rate of $632 million and a 27% IRR at $3,250 per ounce gold, $4.50 per pound copper and $40 per ounce silver; an 11-year mine life; about 85,000 gold-equivalent ounces a year; and initial capital of about $394 million. The company reports cash of about $31 million at 30 April 2026, roughly 16.5 million shares, and first production as soon as late 2028 if financing closes (U.S. Gold Corp. CEO update, August 2026). The study prices are the company’s base case, not today’s market.
6. Liberty Gold (TSX: LGD)
Liberty Gold owns 100% of the Black Pine oxide project in Idaho. The resource update of 10 February 2026, effective 31 January 2026, shows 502.7 million tonnes indicated at 0.30 g/t for about 4.88 million ounces and 157.1 million tonnes inferred at 0.21 g/t for about 1.05 million ounces, at a 0.10 g/t cut-off. The feasibility study followed on 8 September 2026: initial capital of US$411.4 million, a probable reserve of 4.04 million ounces at 0.29 g/t, a 16-year mine life and an after-tax NPV at a 5% discount rate of US$2.397 billion at $3,250 per ounce gold (Liberty Gold release, 8 September 2026). Permitting and a construction decision are still ahead. The resource figures above come from (Liberty Gold release, 10 February 2026). At 0.30 g/t the grade is low, so cost per tonne of ore matters more here than at a high-grade vein.
7. Dakota Gold (NYSE American: DC)
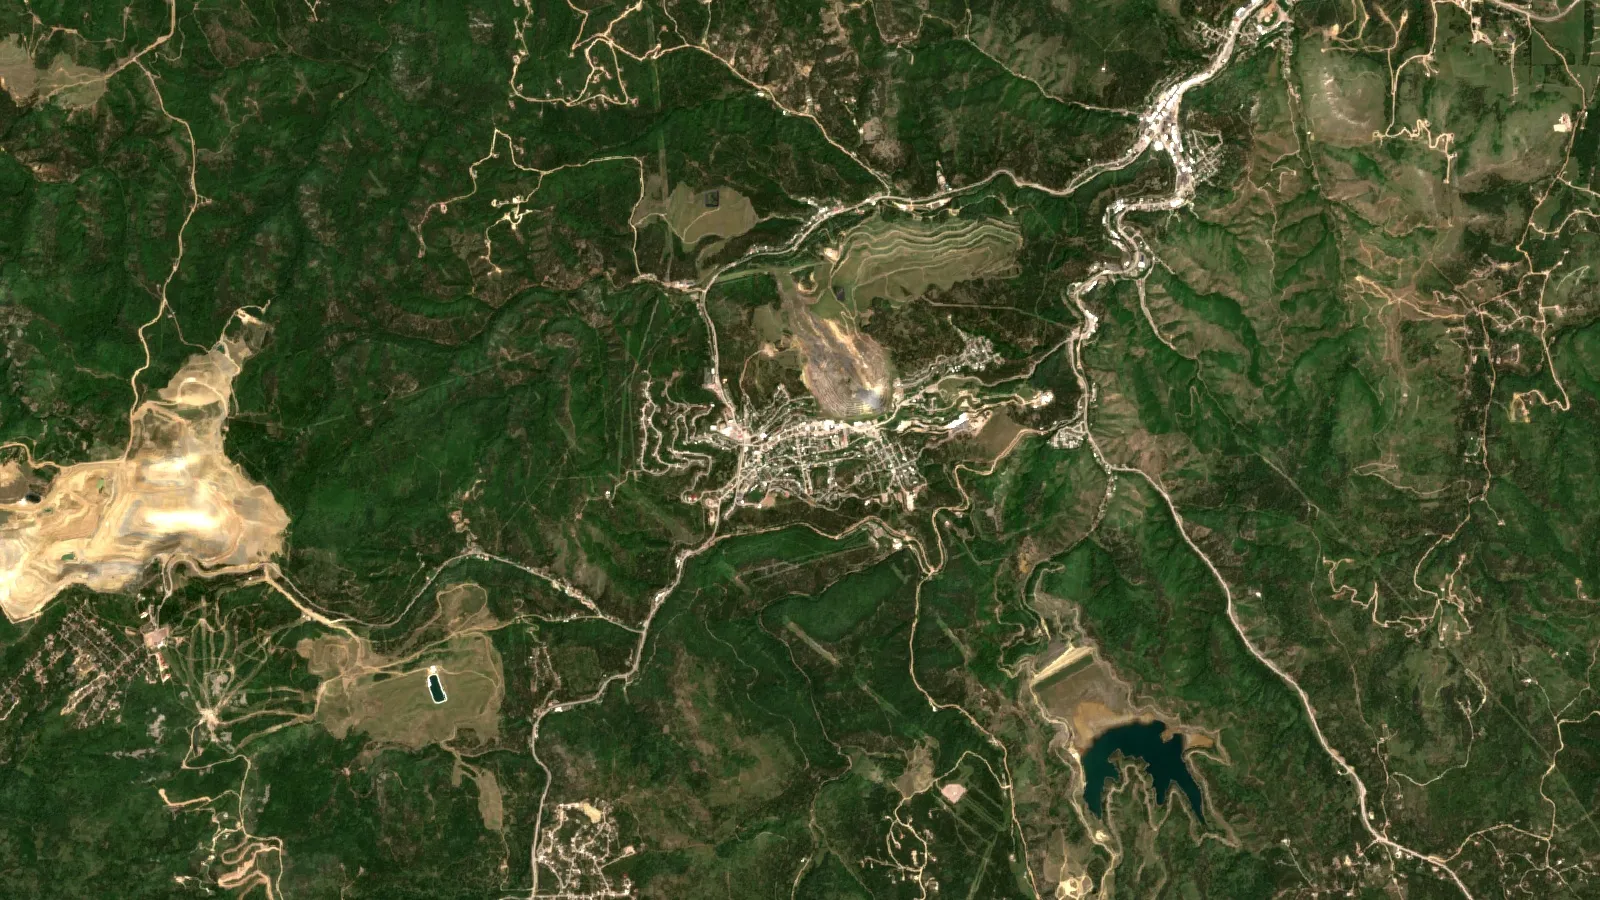
Dakota Gold is advancing Richmond Hill in the historic Homestake district of South Dakota, on private land with state and county permitting. Its August 2026 fact sheet lists a pre-feasibility study in Q4 2026, a feasibility study in the first half of 2027, a maiden resource at the Maitland target in the first half of 2027, production as soon as 2029, and $99 million of cash at 30 June 2026 (Dakota Gold fact sheet, August 2026). A Kitco report of 19 October 2026 gives about 18 months for permitting, with permits targeted by the end of 2028 (Kitco, 19 October 2026).
8. Snowline Gold (TSX: SGD)
Snowline’s main asset is the Valley gold deposit in Yukon. Its preliminary economic assessment, announced on 23 June 2025, described a 20-year open-pit operation averaging 544,000 ounces a year over the first five years, with a post-tax NPV of C$3.37 billion at a gold price of $2,150 per ounce (Snowline PEA release, 23 June 2025). A pre-feasibility study is on track for delivery by the first quarter of 2027 (Snowline release, 9 September 2026). A preliminary economic assessment is an early study type that can include inferred resources, so treat its numbers as conceptual. The company’s website listed the shares as TSX: SGD and OTCQB: SNWGF on 28 October 2026 (Snowline Gold).
9. Altamira Gold (TSXV: ALTA)
Altamira is exploring the Cajueiro project in the Juruena gold belt of western central Brazil, on a land package of more than 90,000 hectares. Its resource for the Maria Bonita deposit was updated on 21 September 2026 to 25 million tonnes at 0.50 g/t gold indicated (403,877 ounces) and 70 million tonnes at 0.41 g/t gold inferred (908,477 ounces), at a 0.24 g/t cut-off; Cajueiro Central is a second deposit with its own resource (Altamira Gold release, 21 September 2026). The shares also trade as EQTRF over the counter and T6UP in Frankfurt. This is the earliest stage on the list: the next steps are drilling and economic studies, not construction.
Next catalysts for each company
A catalyst is a dated event that can change how the market values a company. These are the next ones each company itself has stated. Dates are the companies’ targets, and targets move.
| Company | Next stated milestone | Source date |
|---|---|---|
| West Red Lake Gold | Madsen and Rowan pre-feasibility study; ramp-up toward 27,000 to 32,000 oz in 2026 | 27 Oct 2026 |
| Montage Gold | Commercial production from the oxide circuit in Q4 2026; hard-rock circuit Q2 2027; updated mine plan and reserves at year-end | 27 Sep 2026 |
| Skeena Resources | Initial production in Q2 2027 | 31 Mar 2026 |
| Perpetua Resources | Closing of the $2.9 billion U.S. EXIM loan (approved 21 May 2026), then a final construction decision; further drill assays | 21 May 2026 |
| U.S. Gold Corp. | Financing announcement and possible construction start as soon as late 2026 | Aug 2026 |
| Liberty Gold | Permitting and a construction decision after the feasibility study | 8 Sep 2026 |
| Dakota Gold | Pre-feasibility study in Q4 2026; feasibility study in H1 2027 | Aug 2026 |
| Snowline Gold | Pre-feasibility study, on track for Q1 2027; project description submission for permitting | 9 Sep 2026 |
| Altamira Gold | Step-out drilling at Maria Bonita, open to the west, south and at depth | 21 Sep 2026 |
Four kinds of event repeat across the sector. Drill results move explorers most, because a single long, high-grade intercept can re-rate a project. Economic studies move developers, so check the gold price each study assumes: U.S. Gold’s base case uses $3,250 per ounce while Snowline’s 2025 study used $2,150. Financing decisions move builders, because a placement at a discount dilutes holders. Production reports move producers, because a guidance cut is read as a signal about costs and management.
Gold price context for junior valuations
Juniors are used to the gold price in a plain sense: a small change in the price changes the value of an undeveloped deposit by a larger percentage, because mining costs are fixed in dollars. The World Bank’s annual averages show how large the recent move has been: $1,392 per ounce in 2019, $2,388 in 2024 and $3,442 in 2025 (World Bank Pink Sheet, annual prices, updated 2 September 2026).
Chart
Gold annual average price, 2019 to 2025
US$ per troy ounce, nominal
Supply has not kept pace. The USGS estimates world mine production at 3,300 tonnes in 2025 against 3,280 tonnes in 2024, and US mine output at 160 tonnes in 2025 against 187 tonnes in 2021 (USGS Mineral Commodity Summaries 2026: Gold). A flat supply with a higher price is the backdrop that makes small, permitted deposits worth studying.
What it costs to build a mine: capital estimates compared
Capital cost decides how much new equity or debt a developer needs. The four projects with a published figure in the profiles above range from $394 million to $2,576 million, a ratio of about 6.5. The bases differ: Perpetua’s is direct capital at 31 December 2025, U.S. Gold’s excludes owners’ costs, Skeena’s includes contingency, and Montage’s is mostly spent. Financing is why capital cost matters for the builders and developers.
Chart
Capital cost estimates for four projects
US$ million, latest company figure; bases and dates differ
A producing junior in practice: Madsen output and guidance
West Red Lake is useful because it shows what a producer looks like in its first year. Output in the second quarter was 8,576 ounces and in the third quarter 7,859, and the release table lists the first quarter at 5,667 ounces, which makes the 22,102-ounce nine-month total. The guidance range was then cut. A cut is not a verdict on the ore body; the company blamed labour supply. It does show that production guidance for a young mine carries execution risk that a feasibility study cannot remove.
Chart
Madsen quarterly gold output, 2026
Ounces, from the release table
Chart
Madsen 2026 output guidance, before and after the cut
Ounces of gold, low and high end of the range
How do you value junior gold stocks?
Analysts use a few standard tools, and each answers a different question.
- Enterprise value per resource ounce. Market capitalisation plus debt minus cash, divided by the ounces in the resource. It is quick and lets you compare two explorers, but it ignores grade, depth, metallurgy and jurisdiction, and categories differ: inferred ounces are less certain than indicated ones.
- Price to net asset value (P/NAV). The share price divided by the discounted cash flow value per share from a study. It needs the study’s gold price, discount rate and capital cost, and the same study can look very different at another price. U.S. Gold’s own figures show the effect: its March 2026 base case at $3,250 per ounce gave an NPV of $632 million, and the company’s estimate at about $4,500 per ounce was about $1.37 billion (U.S. Gold Corp. update, August 2026).
- Cash runway. Cash divided by quarterly spending. For an explorer with no revenue this matters more than any ratio, because a company short of cash raises money at whatever price the market gives.
- Cash flow multiples. These apply only to producers such as West Red Lake once a full year of output exists. Cash flow multiples only work for companies that already generate cash flow.
Resource and reserve numbers must follow a recognised code. In Canada that is National Instrument 43-101, and for US registrants the SEC’s S-K 1300 rules (17 CFR 229.1300, eCFR). Skip any figure that does not name the code, the cut-off grade and the effective date.
The calculator below applies the first and third methods to your own inputs. Use the latest share count, cash and debt from the quarterly filing, and a resource that names its category.
Calculator
What is a junior worth per resource ounce, and how long does its cash last?
Enter figures from the latest quarterly filing. Everything is in US$ millions unless stated.
- Market capitalisation (US$ million): $300
- Enterprise value (US$ million): $260
- Cash runway (quarters): 8.0
- Shares added by a raise of one runway year at this price (million): 13.3
Example values only, not a benchmark or a company result. Share price is an example, use today’s price. Resource ounces should name one category (indicated or inferred). Enterprise value is market capitalisation plus debt minus cash; it ignores warrants, options, royalties and streams. Runway assumes spending stays constant.
Which gold explorers sit near existing infrastructure?
Distance from roads, power and a mill lowers capital cost and permitting risk, so it is a fair question to ask of any project. Among the nine names, the filings point to three kinds of advantage. Dakota Gold describes Richmond Hill as in the historic Homestake district with existing infrastructure (Dakota Gold fact sheet, August 2026). West Red Lake feeds Rowan and other targets into the existing Madsen mill, which it calls the central processing hub. Montage connected Koné to the grid in 2026, which allowed dry commissioning to begin. At the other end, Perpetua is building an access road, worker housing and a powerline as part of early works at Stibnite, which is what a remote site costs. Skeena cut about $94 million from upfront cost by leasing the water treatment plant, power infrastructure and camp.
When you compare two projects, ask four things: the distance to a grid connection, whether a mill with spare capacity already exists nearby, whether the site has road access in winter, and whether land is private or federal, since private land in South Dakota follows state and county permitting while federal land adds national review.
▶ How gold is mined and refined, step by step, from rock to bar. · 5:27
What should retail investors know before buying gold juniors?
Six facts apply to almost every junior.
- Most have no revenue. They fund themselves by selling shares, so each raise can dilute holders. Check the share count over several years.
- A single project carries the company. A permit delay or a weak drill hole at one site can move the whole share price.
- Study numbers depend on the gold price used. A study at $2,150 per ounce and one at $3,250 are not comparable.
- Liquidity is thin. Small caps can gap on little volume, and over-the-counter listings can be harder to trade than the main exchange.
- Currency and tax differ. Canadian-listed shares trade in C$, some US filers report in US$, and cross-border holders face withholding and reporting rules that vary by country.
- Company materials are promotional. Fact sheets and presentations stress the upside. The risk factors in the annual report and the technical report show the rest.
If you only want broad exposure, a fund holds many companies and removes single-project risk, though not gold-price risk (see the VanEck Junior Gold Miners ETF breakdown). Funds at the junior end of the sector also hold mid-sized producers, as the GDXJ list above shows.
What events make investors review a position in gold juniors?
No filing tells a reader when to sell, and this page does not. What investors commonly do is write down, before they hold a share, the facts that would change their view, then check them after each company release. Typical items are these.
- A missed milestone date, such as a study that slips by two quarters.
- A financing at a large discount to the previous raise, which shows what the market will pay.
- A downgraded resource or a study that moves capital cost sharply, as Skeena’s rose from $560 million to $659 million.
- A guidance cut at a producer, as at Madsen.
- A takeover offer. Majors replace depleting reserves by buying developers, so a bid for a neighbour can re-rate peers, and a bid for the company itself sets a price that holders can compare with their own view.
A tax adviser can say how a sale is treated where you live.
Junior ETFs and lists: where GDXJ fits
People who search for a list of junior gold miners often find the holdings of a fund. VanEck’s GDXJ held 160 positions on 14 October 2026, with Alamos Gold at 6.54%, Coeur Mining at 6.32%, Equinox Gold at 5.90%, Endeavour Mining at 5.55% and IAMGOLD at 5.18% (GDXJ holdings, StockAnalysis, 14 October 2026). Those are producing mid-sized companies, so a junior fund is not the same thing as a basket of explorers. None of the nine companies in this article is in the fund’s top five. Fees, structure and index rules are covered on our GDXJ page.
Takeovers and consolidation
Developers with a permitted, drilled-out deposit are the usual targets when a major wants to replace the ounces it mines each year. The profile of the target matters more than the share price trend: a large resource, a stable jurisdiction, a study that is complete or close and a route to permits. Among the names above, U.S. Gold Corp. disclosed in August 2026 that a special committee was assessing merger and acquisition interest. That is a statement about the process, not a forecast of a deal. For the economics a buyer will compare, see margins and all-in sustaining costs by metal, and for the largest US operations see active gold mines in the USA.
How satellite screening fits
For a company, a licence or a claim block, satellite imagery can show alteration minerals, structures and surface changes before a drill is booked. Investors can use the same idea to check whether a target was chosen from data or from a story. Farmonaut’s satellite-based mineral detection maps a licence area from a boundary file; a quote form is on the mining query page. Satellite results are exploration targets that sit ahead of a resource estimate and are not a substitute for drilling.
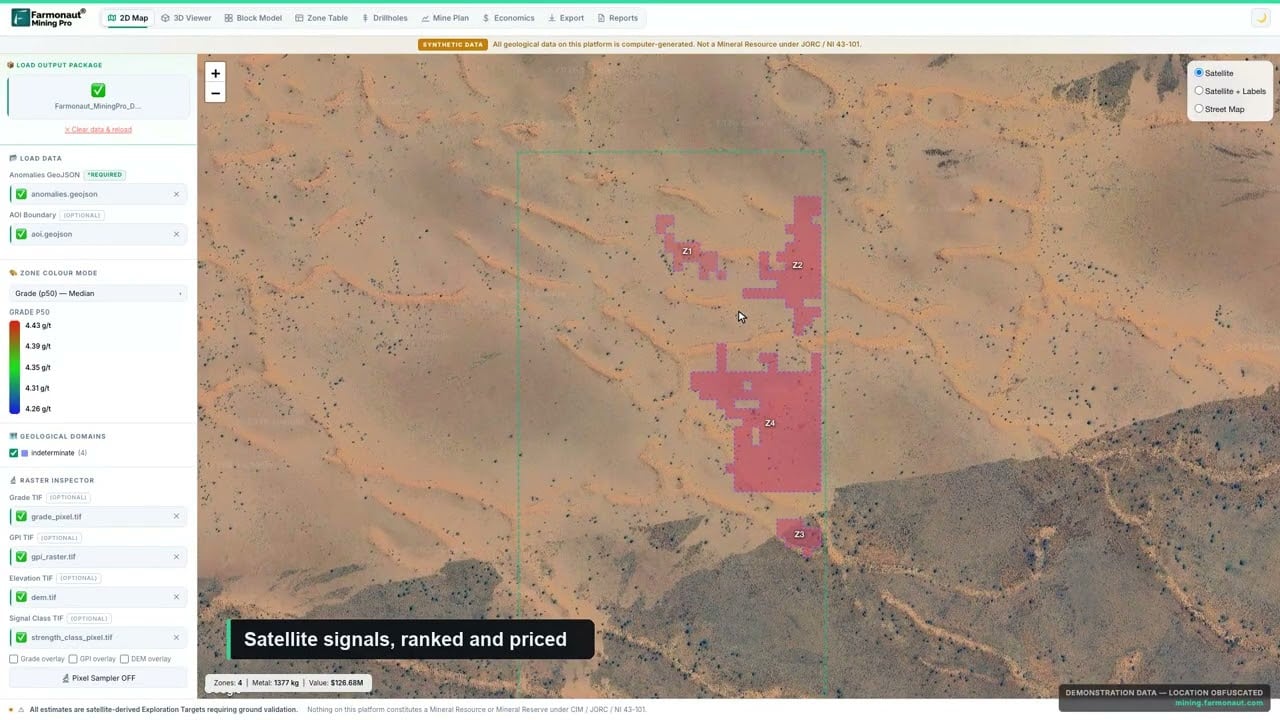
▶ A short look at Farmonaut Mining Pro, which turns a licence boundary into a geological and economic picture. · 4:56
Frequently asked questions
What are the best junior gold mining stocks?
There is no single answer, because the best fit depends on the stage and risk you accept. This page profiles nine North American-listed companies from a producer to an explorer, with dated facts for each. It does not rate them.
What is a junior gold mining stock?
It is a share in a small company that explores for or develops gold deposits, or runs a young mine, and has little or no diversified cash flow. Seniors such as the largest producers operate several mines at once.
How do you value junior gold stocks?
Common tools are enterprise value per resource ounce, price to net asset value from a study, and cash runway for explorers. Each depends on assumptions, so compare the gold price, discount rate and resource category behind every figure.
What catalysts should I watch for when investing in a junior gold explorer?
Drill results, resource updates, economic studies, permits, financings and takeover interest. List each company’s next dated milestone and check that its cash reaches that date without a raise.
What should retail investors know before buying gold juniors?
Most juniors have no revenue, rely on equity raises, depend on one project and trade thinly. Read the risk factors and the technical report, not just the presentation.
How do rising gold prices affect exploration-stage companies?
Higher prices raise the value of an undeveloped deposit and make financing easier, usually by a larger percentage than the move in the metal. They also raise costs and can raise expectations. The World Bank annual average rose from $2,388 in 2024 to $3,442 in 2025.
Which gold exploration companies are positioned near existing infrastructure?
Among the nine profiled, Dakota Gold cites existing infrastructure in the Homestake district, West Red Lake uses the existing Madsen mill, and Montage has connected its site to the grid. Check each company’s technical report for distances and capacity.
How do I compare two gold exploration companies?
Use the same checklist for both: stage, resource category and grade, cash and quarterly spending, share count, jurisdiction, infrastructure and next dated milestone. Then enter both into the calculator on this page.
Which listed gold miners offer both production and exploration upside?
West Red Lake Gold produces from Madsen and is also advancing Rowan and other targets in the Red Lake district. Larger producers in the GDXJ list also explore, but check each company’s own disclosures.
What does a company mean by a 43-101 resource?
It means the resource was reported under Canada’s National Instrument 43-101 by a qualified person, with category, cut-off grade and effective date. Reserves are a stricter class: they need at least a pre-feasibility study showing the material can be mined at a profit.
Are Altamira Gold, Snowline Gold or Dakota Gold producers?
No. Altamira is exploring, Snowline has a 2025 economic assessment and is preparing a pre-feasibility study, and Dakota is also preparing a pre-feasibility study. None reports gold sales.
Are there other companies and tickers not on this list?
Yes, many. The list is a sample from each stage. Use the checklist above with any other ticker you find, and read the company’s latest filing before relying on a third-party list.
This page is for information only. It is not investment advice. It names companies for illustration and does not recommend that anyone buy, hold or sell any security.
This page is for information only. It is not investment advice. It rates no company and names no security to buy or sell. Check company filings and speak to a licensed adviser.
Farmonaut mining
Screen a project area from space
Farmonaut maps alteration and structure inside a licence boundary so exploration targets can be ranked before drilling.

Mining Pro sample view, synthetic data
Keep reading
Sources
- World Bank, Commodity Markets: Pink Sheet annual prices (updated 2 September 2026): worldbank.org
- USGS, Mineral Commodity Summaries 2026: Gold: pubs.usgs.gov
- Kitco gold quote, 20 October 2026 (via Depor): depor.com
- West Red Lake Gold, Q3 2026 production release (27 October 2026): bnnbloomberg.ca
- Montage Gold, Q2 2026 activities (11 August 2026): bnnbloomberg.ca
- Skeena Resources, Eskay Creek update (31 March 2026): sec.gov
- Perpetua Resources, construction and exploration update (28 September 2026): finviz.com
- Perpetua Resources, Form 10-Q for 31 March 2026: sec.gov
- U.S. Gold Corp., CEO update (August 2026): finviz.com
- Liberty Gold, updated Black Pine resource (10 February 2026): finanznachrichten.de
- Dakota Gold, fact sheet (August 2026): dakotagoldcorp.com
- Kitco, Dakota Gold and Richmond Hill (19 October 2026): kitco.com
- Snowline Gold, company website (28 October 2026): snowlinegold.com
- StockAnalysis, GDXJ holdings (14 October 2026): stockanalysis.com
- eCFR, 17 CFR 229.1300 (S-K 1300): ecfr.gov
- Snowline Gold, Valley preliminary economic assessment (23 June 2025): snowlinegold.com
- Montage Gold, first gold pour at Koné (27 September 2026): globenewswire.com
- Liberty Gold, Black Pine feasibility study (8 September 2026): bnnbloomberg.ca
- Altamira Gold, Maria Bonita resource increase (21 September 2026): investingnews.com
- Perpetua Resources, EXIM loan approval (21 May 2026): prnewswire.com
- West Red Lake Gold, commercial production at Madsen (12 January 2026): globenewswire.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Sahel Shipping SA
 Sania Corporation
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd











