

Diamond industry · Ranked list
Biggest Diamond Company in the World: Ranked by Carats
Alrosa mined 29.8 million carats in 2025, De Beers 21.7 million. Here is every company with a published figure of 1 million carats or more, the country totals behind them, and what each carat sells for.
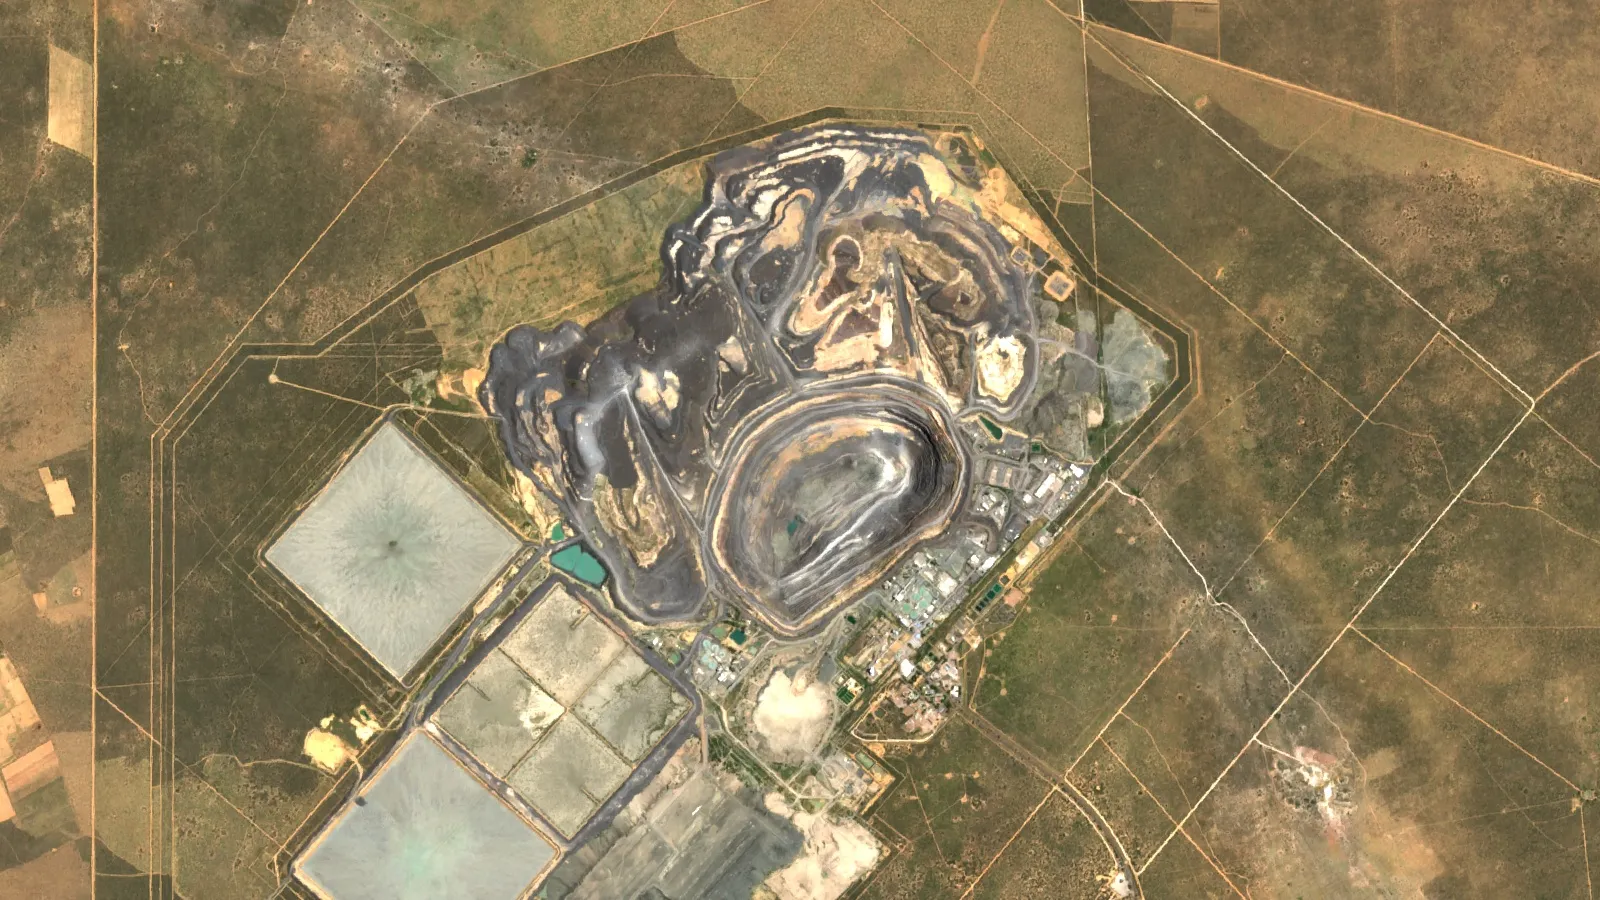
Key takeaways
- Alrosa reported 29.8 million carats for 2025, about 30% of the 98.8 million carats counted worldwide (Alrosa; Kimberley Process).
- De Beers recovered 21.7 million carats in 2025, down 12%, and Anglo American is selling its 85% stake (De Beers, February 2026; Miningmx, July 2026).
- Rio Tinto’s Diavik made 4.4 million carats in 2025 and closed on 26 March 2026 after more than 150 million carats (Rio Tinto).
- Russia made 31.5 million carats in 2025, Botswana 15.5, Angola 15.2 and Canada 14.1 (Kimberley Process).
- Gem Diamonds’ Letšeng averaged US$1,105 per carat in 2025 against US$142 for De Beers (company reports).
In this article
- Biggest diamond companies ranked by carats produced
- Method: how the ranking was built
- Alrosa leads on volume
- De Beers: the best-known diamond company and second by carats
- Rio Tinto, Petra, Mountain Province and Burgundy in detail
- Big producers that do not publish company-level carats
- Biggest diamond company by value per carat
- Why the biggest diamond companies are producing less
- What guidance says about the next ranking
- How to read any list of the biggest diamond companies
- Can a small company join the list of diamond producers?
- Check a diamond licence from space before you drill
- Work out what a producer's carats are worth
- Frequently asked questions
By carats mined, the biggest diamond company in the world is Alrosa of Russia. It reported 29.8 million carats for 2025, about 30% of the 98.8 million carats counted worldwide that year. De Beers is second with 21.7 million carats, so the two together made roughly half the world’s rough diamonds. The ranking changes if you rank by price per carat, by country or by profit, and each of those is covered below with the source and year next to every number.
A carat is 0.2 grams, the unit all diamond output is counted in. “Rough” means uncut stones straight from the mine. The tables below use company reports first and the Kimberley Process, the government and industry scheme that counts rough diamonds crossing borders, for country totals. Sections follow a simple order: the ranked list, how it was built, each leader, the producers that do not publish company numbers, then value, outlook and calculator.
Biggest diamond companies ranked by carats produced
Metric: rough diamonds recovered in calendar 2025, in million carats (Mct), as reported by each company. Where a company reports a different year or a share, the last column says so. The list holds every company we found that published a 2025 figure of 1 Mct or more.
Chart
Rough diamond output by company, 2025
Million carats; ZCDC is a CEO statement, Petra the year to June 2026, Mountain Province its 49% share
| Rank | Company | Main mines | Rough output | Basis and note |
|---|---|---|---|---|
| 1 | Alrosa (Moscow Exchange: ALRS) | Yakutia and Arkhangelsk, Russia | 29.8 Mct | Whole-company 2025 production, per Alrosa, July 2026 |
| 2 | De Beers (Anglo American) | Jwaneng and Orapa in Botswana, Debmarine and Namdeb in Namibia, Venetia in South Africa, Gahcho Kué in Canada | 21.7 Mct | 100% basis, except Gahcho Kué at De Beers’ 51% share (De Beers, 5 February 2026) |
| 3 | Rio Tinto | Diavik, Northwest Territories, Canada | 4.4 Mct | Diavik at 100%; the mine closed on 26 March 2026 (Rio Tinto Q4 review) |
| 4 | Zimbabwe Consolidated Diamond Company (ZCDC, state-owned) | Marange fields, Zimbabwe | 3.8 Mct | 2025 output as stated by its chief executive in May 2026, not an audited report (FSX Business, May 2026) |
| 5 | Burgundy Diamond Mines (ASX: BDM) | Ekati, Northwest Territories, Canada | 2.7 Mct | Sum of four quarterly reports: Q1 0.77, Q2 0.81, Q3 0.61, Q4 0.54 (June 2025, December 2025, March 2026 reports) |
| 6 | Petra Diamonds (LSE: PDL) | Cullinan and Finsch, South Africa | 2.3 Mct | Twelve months to 30 June 2026, not calendar 2025 (Petra, 28 July 2026) |
| 7 | Mountain Province Diamonds (TSX: MPVD) | 49% of Gahcho Kué, Canada | 2.1 Mct | Its 49% share of 4.33 Mct (Mountain Province, March 2026) |
The Gahcho Kué joint operation appears twice because the two partners report different shares: De Beers counts its 51% inside its 21.7 Mct, and Mountain Province reports the other 49%. Do not add rows 2 and 7 without removing the overlap. ZCDC’s figure is a chief executive’s statement, not an audited report, and Petra’s is a different year, so treat ranks 4 to 7 as approximate. Catoca in Angola is reported at about 6 to 7 Mct a year but has no official 2025 company figure, so it is not ranked.
Method: how the ranking was built
We used volume because it is the one measure every producer reports in the same unit. Revenue is harder to compare: Alrosa’s reported revenue covers its whole group, De Beers’ sales are split between Sights (its regular selling events) and other channels, and several miners report only quarterly sales. Share price and market value were not used, because they say little about the size of the mining operation.
Three rules kept the list consistent. First, the year is calendar 2025 unless a row says otherwise. Second, 100% of a mine is credited to its operator, with joint operations shown as noted. Third, a company needed a published figure of at least 1 Mct. Producers below that line, such as Lucara and Gem Diamonds, are covered in the value section because they matter for price rather than volume. Rankings can move quickly: Alrosa itself guides to 25 to 26 Mct for 2026 (Reuters via Kitco, August 2026).
Alrosa leads on volume
Alrosa describes itself as the world’s leading producer of natural diamonds by volume, and the Kimberley Process data agree with the scale: Russia produced 31.5 Mct in 2025 (Kimberley Process, 2025 global summary), and Alrosa’s 29.8 Mct is about 95% of that by our arithmetic. Output fell 10% from 2024 as the company temporarily shut low-margin assets (Reuters via Kitco, December 2025).
Alrosa has been under Western sanctions since 2022, and it reported a net loss of 9.5 billion roubles for the first half of 2026, against a profit of 40.6 billion roubles a year earlier (Reuters via Kitco, 27 August 2026). It expects output to fall to 25 to 26 Mct in 2026 and to recover to 29 to 30 Mct once the market stabilises, so the gap with De Beers may narrow.
De Beers: the best-known diamond company and second by carats
De Beers recovered 21,656 thousand carats in 2025, down 12% from 24,712 thousand in 2024. Botswana provided 15,134 thousand of that, Namibia 2,082, South Africa 2,230 and Canada 2,210 (De Beers production report, 5 February 2026). Within Botswana, Orapa recovered 7.9 Mct and Jwaneng 7.3 Mct. Jwaneng was offline for the whole of the fourth quarter for planned maintenance, and Orapa had a shorter shutdown in October; De Beers gave these as the main reasons Q4 output fell 35%.
Chart
De Beers rough output by country, 2025
Million carats; Gahcho Kué at the 51% share
De Beers’ full-year consolidated average realised price fell 7% to US$142 per carat in 2025, and the group guided 2026 output to 21 to 26 Mct, cut from 26 to 29 Mct (same report). It is also a company in transition. Anglo American owns an 85% stake and is running a sale; its chief executive said on 30 July 2026 that Anglo was not exclusive with any bidder and hoped to conclude in the second half of the year (Miningmx, 30 July 2026). For what a change of owner could mean for mines, workers and supply, see our look at the De Beers and Anglo American takeover. De Beers also said in May 2025 that it would close Lightbox, its lab-grown jewellery brand, to focus on natural diamonds (De Beers, 8 May 2025).
Rio Tinto, Petra, Mountain Province and Burgundy in detail
Rio Tinto’s Diavik recovered 4,429 thousand carats in 2025, up from 2,759 thousand in 2024, as ore processed rose from 1.27 million to 1.91 million tonnes while the mine neared the end of its economic reserves (Rio Tinto, Q4 operations review). Its last day of production was 26 March 2026, after 23 years and more than 150 million carats (Rio Tinto, 26 March 2026). Diavik was one of several mines on the Lac de Gras diamond field; the coordinates of that field and six other sites are in our guide to diamond coordinates.
Petra Diamonds recovered 2.34 Mct in the year to June 2026, down 4%. Its Cullinan mine in South Africa made 1.40 Mct and sold at an average US$106 per carat, but Finsch, which made 0.94 Mct, was placed into business rescue (South Africa’s court-supervised restructuring process) in the fourth quarter and operations were suspended on 10 June 2026. Petra’s guidance remains suspended (Petra, 28 July 2026).
Gahcho Kué recovered 4,333,792 carats at 100%, 7% below 2024, with 43% of the year’s carats arriving in the fourth quarter. Mountain Province’s 49% share was 2,123,558 carats (Mountain Province, March 2026). Burgundy Diamond Mines owns Ekati; it recovered 0.54 Mct in the December 2025 quarter and 0.38 Mct in the March 2026 quarter (Burgundy, 30 April 2026). For the drilling side of Canadian diamond projects, see diamond drilling companies in Canada.
Big producers that do not publish company-level carats
Some of the largest diamond operations are state-linked or artisanal, so no comparable audited company figure exists and a company ranking would understate them. The Kimberley Process country totals show where they sit. Angola made 15.2 Mct in 2025 (US$1.81 billion) and Luele and Catoca are its two largest projects, supplying most of the national output, according to Expansão, February 2026. The Democratic Republic of the Congo made 8.9 Mct at an average of only US$5 per carat, and Zimbabwe made 4.2 Mct at US$24 per carat, of which the state-owned ZCDC said it produced 3.8 Mct.
| Country | Rough output | Value | Average per carat |
|---|---|---|---|
| Russia | 31.5 Mct | US$2.72 billion | US$86 |
| Botswana | 15.5 Mct | US$1.98 billion | US$128 |
| Angola | 15.2 Mct | US$1.81 billion | US$119 |
| Canada | 14.1 Mct | US$0.89 billion | US$63 |
| DR Congo | 8.9 Mct | US$0.04 billion | US$5 |
| South Africa | 5.6 Mct | US$0.60 billion | US$107 |
| Zimbabwe | 4.2 Mct | US$0.10 billion | US$24 |
| Namibia | 2.1 Mct | US$0.72 billion | US$344 |
Source for the table: Kimberley Process, Annual Global Summary 2025, rounded. World production was 98.8 Mct worth US$9.23 billion, an average of US$93 per carat. That is down from 107.9 Mct and US$9.53 billion in 2024. Smaller producers also appear in the 2025 data, for example Tanzania at 0.37 Mct, Ghana at 0.20 Mct and Sierra Leone at 0.12 Mct.
Biggest diamond company by value per carat
Volume and value rank very differently. Gem Diamonds recovered only 90,354 carats at Letšeng in Lesotho in 2025 but averaged US$1,105 per carat, and its group revenue was US$98.4 million (Gem Diamonds, full-year 2025 results). Lucara sold 353,302 carats from Karowe in Botswana for US$159.7 million (Lucara, 3 March 2026), which works out to about US$452 of revenue per carat sold; that revenue includes the Seriti stone (1,094 carats, initial polished value US$12.0 million), so it is not a pure rough price. Neither reaches 1 Mct, yet each earns more per carat than De Beers (US$142) or Cullinan (US$106).
Chart
Average rough price per carat
US$ per carat; De Beers and Letšeng 2025, Cullinan year to June 2026, Karowe revenue per carat sold, Russia all producers
The reason is the size and quality of the stones. Lucara recovered three stones above 1,000 carats in 2025. Large, clean, colourless stones sell for far more per carat than the small stones that make up most of Russian, Canadian and Congolese output, and Petra points to a structural change in the price of smaller stones. Petra said Finsch’s large share of smaller goods, together with a strong rand, made the mine untenable (Petra, July 2026).
Why the biggest diamond companies are producing less
World output fell 8% in 2025 and most of the big names cut or paused production. De Beers said rough trading remained difficult amid industry, geopolitical and tariff uncertainty, and that its average rough price index fell 12% during the year. Alrosa temporarily shut low-margin assets. Burgundy suspended its Point Lake pit in the September 2025 quarter. Diavik is closed because its reserves ran out, not because of the market.
Chart
Change in rough output, one year apart
Million carats; Petra compares years to June 2025 and June 2026, the rest 2024 and 2025
Lab-grown stones are part of the story but the data need care. The USGS reports that natural diamond is less than 1% of all industrial diamond produced, with synthetic diamond making up the rest; that statement covers industrial grit and stones, not jewellery (USGS Mineral Commodity Summaries 2026). For gems, De Beers’ choice to close Lightbox shows how it wants to position natural stones against lab-grown ones. If you also follow the metals that mining groups sell, the same market logic appears in our guides to the largest silver and diamond mining companies and the top silver mining companies.
What guidance says about the next ranking
The two leaders both plan to mine less. Alrosa guides to 25 to 26 Mct, down from 29.8 Mct. De Beers guides to 21 to 26 Mct (100% basis, with Gahcho Kué at 51%), against 21.7 Mct recovered in 2025. The two ranges overlap: Alrosa at 25 Mct and De Beers at 26 Mct would put De Beers ahead by 1 Mct, while the opposite ends would put Alrosa ahead by 5 Mct. De Beers reported negative EBITDA (earnings before interest, tax, depreciation and amortisation) of US$113 million for the first six months of 2026, an improvement on a US$189 million loss a year earlier (Miningmx, 30 July 2026).
At the mid-size end, the change is bigger. Diavik stopped on 26 March 2026, so Rio Tinto’s 2026 total will include only its first quarter. Finsch made 0.94 of Petra’s 2.34 Mct, about 40%, and is now suspended. Gahcho Kué reached new ore from its latest cut in the fourth quarter of 2025, which lifted De Beers’ Canadian output. Check each company’s next quarterly report; these figures will be superseded.
How to read any list of the biggest diamond companies
Three checks avoid most errors. First, ask whether the figure is production or sales: a company can sell stock built in earlier years, as Burgundy did when it sold 0.68 Mct in the December 2025 quarter while recovering 0.54 Mct. Second, look at the basis. A joint venture such as Gahcho Kué is reported at 100% by Mountain Province’s release and at 51% by De Beers. Third, check the year end. Petra reports to 30 June, so its latest year is not comparable to a December year.
Also be wary of rankings that mix companies with countries or with sales channels, because a mine’s output can then be counted twice.
Can a small company join the list of diamond producers?
Not at the top. The seven companies in the ranked table run mines that treat millions of tonnes of ore a year, and Petra’s Cullinan alone treated 4.6 million tonnes in the year to June 2026. Smaller operators do appear in the Kimberley Process data, such as Tanzania, Ghana and Sierra Leone, and licence rules differ by country. The short video below looks at whether a foreigner can get a small-scale mining licence in Africa.
▶ Explains whether a foreigner can get a small-scale mining licence in Africa. · 5:16
Check a diamond licence from space before you drill
Kimberlite pipes are small, and some sit under soil or lake sediment. Satellite imagery cannot see diamonds. It can show vegetation, soil colour and drainage patterns around known pipes and help a geologist decide where to sample first, ahead of drilling and a resource estimate. Farmonaut offers satellite screening of licence areas for this purpose. The two-minute video below explains the instrument types.
▶ Explains in plain words how remote sensing measures the ground from a distance. · 2:01
Work out what a producer’s carats are worth
The calculator below turns any producer’s annual carats and an average rough price into gross sales, and compares it with the 2025 world totals from the Kimberley Process.
Calculator
What are a producer’s carats worth?
Enter a producer’s annual carats and an average price per carat.
- Share of world carats: 2.0%
- Share of world value: 2.2%
- Your price against the 2025 world average: 1.07 x
Example values only, not any company’s figures. The price is an input: example, use today’s price or a quoted parcel value in US$ per carat. World totals are the Kimberley Process 2025 figures (98.8 Mct, US$9.23 billion). The result is gross sales value before mining cost, tax and royalties.
Frequently asked questions
What is the biggest diamond company in the world?
By rough carats produced, Alrosa, with 29.8 million carats in 2025 according to its own report. De Beers is second at 21.7 million carats.
Is De Beers bigger than Alrosa?
Not by volume: Alrosa mined about 8 million more carats in 2025. De Beers averaged US$142 per carat; Russia’s national average was US$86 per carat (Kimberley Process).
Who owns De Beers?
Anglo American owns an 85% stake and is selling it. As of 30 July 2026 its chief executive said no exclusive agreement had been reached with any bidder.
Which country produces the most diamonds?
Russia, with 31.5 million carats in 2025, followed by Botswana at 15.5 million, Angola at 15.2 million and Canada at 14.1 million (Kimberley Process).
How many diamonds does the world produce each year?
The Kimberley Process counted 98.8 million carats of rough diamonds worth US$9.23 billion in 2025, down from 107.9 million carats worth US$9.53 billion in 2024.
Which is the biggest diamond mine by output?
Among the mines in the company reports cited here, Orapa in Botswana recovered the most in 2025 at 7.9 million carats, ahead of Jwaneng at 7.3 million. We found no verified 2025 carat figure for Angola’s Catoca or Luele.
What happened to the Diavik diamond mine?
Rio Tinto’s Diavik, in Canada’s Northwest Territories, delivered its final production on 26 March 2026 after 23 years and more than 150 million carats.
Who owns the Ekati diamond mine?
Burgundy Diamond Mines (ASX: BDM) owns and operates Ekati in the Northwest Territories. It recovered 0.38 million carats in the March 2026 quarter.
Are lab-grown diamonds replacing natural diamond companies?
Lab-grown stones have taken a large share of industrial use, where natural diamond is under 1% according to the USGS. In jewellery the picture is mixed: De Beers announced in 2025 that it would close its lab-grown Lightbox business to focus on natural stones.
Which diamond company has the most valuable stones?
By average price per carat, small high-value mines lead: Gem Diamonds’ Letšeng averaged US$1,105 per carat in 2025, and Lucara’s Karowe earned about US$452 of revenue per carat sold, compared with De Beers at US$142.
Can satellites find new diamond mines?
Satellites do not detect diamonds directly. They help screen a licence area for the landforms, vegetation and soil patterns around kimberlite pipes, so that ground sampling can start in the right places.
Not investment advice. Production figures are company-reported and may be restated; check the latest quarterly report before relying on a number.
This page is for information only. It is not investment advice. Production figures are company-reported and may be restated.
Farmonaut mining
Screen your own licence area from space
Licence owners and mining consultants can request a quote for a satellite screening of a licence area, to help choose where to sample first, ahead of ground work and a resource estimate.

Mining Pro sample view, synthetic data
Keep reading
Sources
- Kimberley Process, Annual Global Summary 2025: kimberleyprocessstatistics.org
- Kimberley Process, Annual Global Summary 2024: kimberleyprocessstatistics.org
- De Beers, Production Report for the Fourth Quarter of 2025 (5 February 2026): debeersgroup.com
- De Beers, intention to close Lightbox (8 May 2025): debeersgroup.com
- Alrosa, carbon neutrality for 2025 (16 July 2026): alrosa.ru
- Reuters via Kitco, Alrosa flags smaller decline (23 December 2025): kitco.com
- Reuters via Kitco, Alrosa posts H1 loss (27 August 2026): kitco.com
- Rio Tinto, Fourth quarter 2025 operations review (SEC 6-K): sec.gov
- Rio Tinto, Diavik delivers its final production (26 March 2026): riotinto.com
- Petra Diamonds, Q4 and FY 2026 Operating and Business Update (28 July 2026): investegate.co.uk
- Mountain Province Diamonds, full year and fourth quarter 2025 results: tools.prnewswire.com
- Burgundy Diamond Mines, Quarterly Activities Report to 30 June 2025: burgundydiamonds.com
- Burgundy Diamond Mines, Quarterly Activities Report to 31 March 2026: bulletin.webull.com
- Gem Diamonds, Full Year 2025 Results: gemdiamonds.com
- Lucara Diamond, Year End 2025 Results (3 March 2026): lucaradiamond.mediaroom.com
- Miningmx, Anglo not exclusive with any buyer for De Beers (30 July 2026): miningmx.com
- Expansão, Angola diamond production 2025 (9 February 2026): expansao.co.ao
- USGS, Mineral Commodity Summaries 2026: Diamond (industrial): pubs.usgs.gov
- Burgundy Diamond Mines, Quarterly Activities Report to 31 December 2025: bulletin.webull.com
- FSX Business, Zimbabwe diamond output target rises (May 2026): fsxbusiness.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Comfix & Engineering Limited
 Congo Mining Solutions
 Mining SARL
 SenGold Invest SAS
 Sania Corporation
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group











