

US mining companies · Comparison
7 Copper and Gold Mining Companies in the USA Compared
Freeport-McMoRan, Asarco, Hudbay, Barrick, Newmont, Kinross and Coeur compared on US mines, output and the technical change at each, from company filings and USGS data.
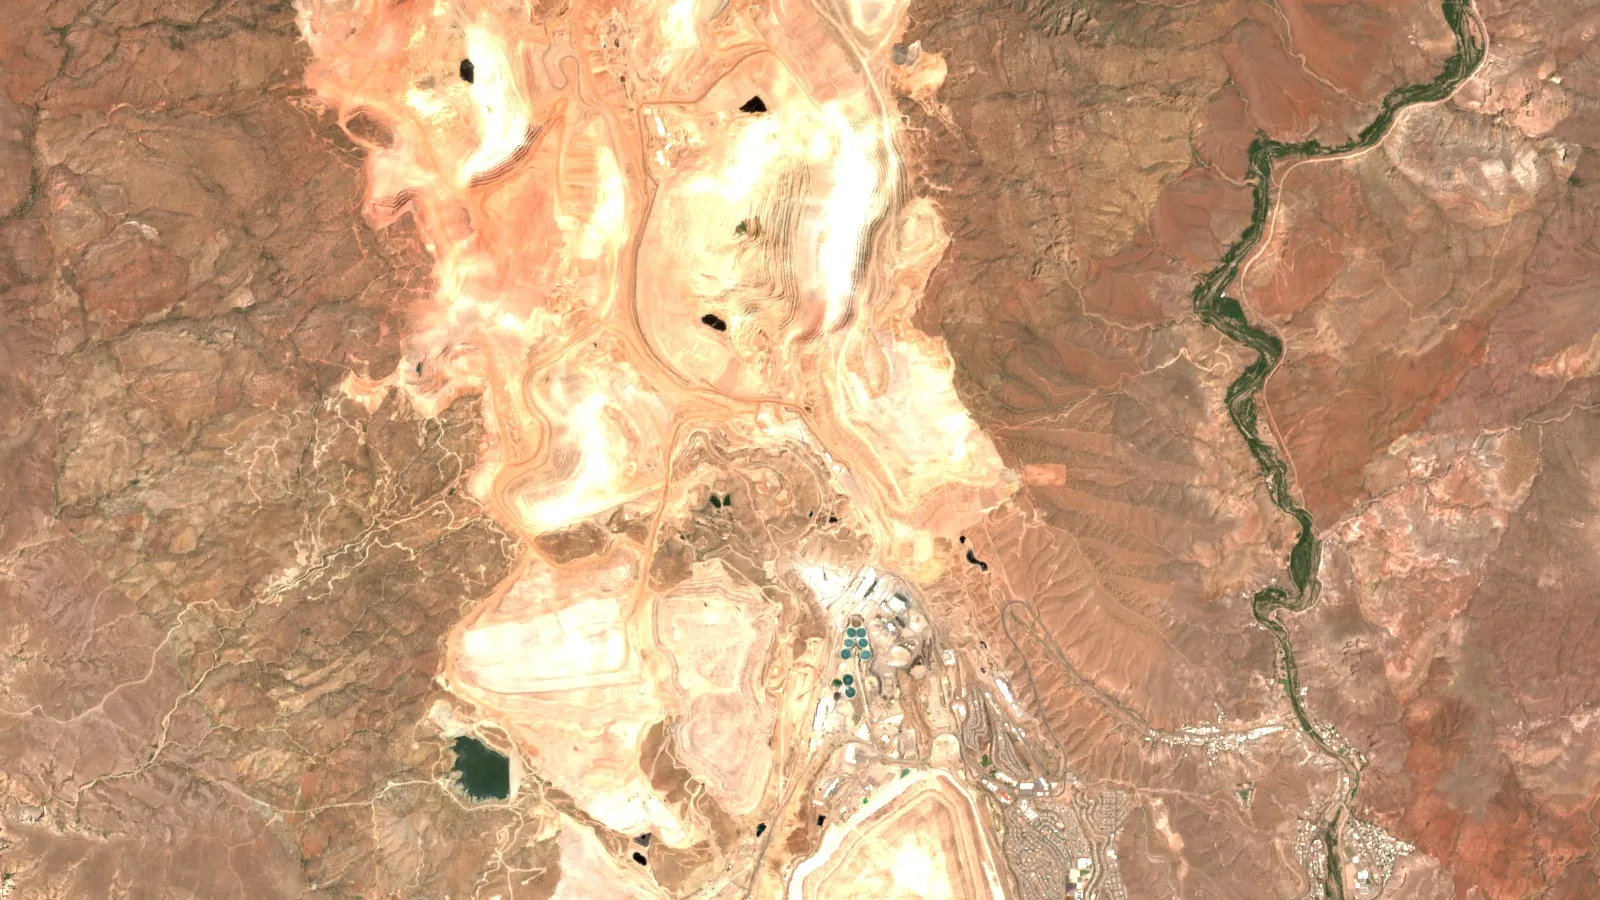
Key takeaways
- Arizona produced about 70% of US mine copper in 2025, and Nevada about 64% of US gold (USGS, 2026).
- Freeport’s seven US copper operations produced 641 million lb in the first half of 2026 (company release, July 2026).
- Barrick (61.5%) and Newmont (38.5%) share Nevada Gold Mines; Newmont reports 999,000 attributable oz for 2025.
- Hudbay and Mitsubishi approved Copper World in October 2026, with first production targeted for 2029.
- Kinross and Barrick are moving toward higher-grade underground rock in Nevada, while Freeport targets more copper from leaching.
In this article
- The 7 companies at a glance
- How we chose these copper and gold miners
- US copper output and why these companies matter
- Copper mining companies in the USA
- 1. Freeport-McMoRan: copper from leaching
- 2. Asarco: three Arizona mines and an idle smelter
- 3. Hudbay Minerals: a new Arizona mine approved for construction
- Gold mining companies in the USA
- 4. Barrick Mining: Nevada Gold Mines and Fourmile
- 5. Newmont: a smaller, joint-venture US position
- 6. Kinross Gold: from open pit to underground
- 7. Coeur Mining: gold and silver with a bigger crusher
- Other US copper and gold companies to know
- What the innovations have in common
The main copper and gold mining companies in the USA are Freeport-McMoRan, Asarco and Hudbay on the copper side, and Barrick, Newmont, Kinross and Coeur on the gold side. This page compares those seven on what they actually operate in the United States, how much they produce there, and the one technical change at each that is worth watching. Figures come mainly from company filings, results releases and the US Geological Survey, with dates.
The national picture sets the scale. US mines produced an estimated 1.0 million tons of recoverable copper in 2025, with Arizona at about 70% of output, and an estimated 160 tons of gold, with Nevada at about 64% and Alaska at about 22%. A short list of operators therefore accounts for much of the output, which is why these names come up so often.
The 7 companies at a glance
This is a comparison, not a ranking. Figures use different bases because the companies report differently, so the last column says what each number measures. Tickers are as stated in each company’s own 2026 releases or filings.
| Company | Metal | Listing | Main US assets | US output figure | Technical change to watch |
|---|---|---|---|---|---|
| Freeport-McMoRan | Copper | NYSE: FCX | Morenci, Bagdad, Safford, Sierrita, Miami (AZ); Chino, Tyrone (NM) | 641 million lb, first half of 2026 | Leaching new copper from old material |
| Asarco | Copper | Part of Grupo Mexico; not separately listed | Ray, Mission, Silver Bell (AZ) | No output figure in its 2025 interview | Solvent extraction and electrowinning at Silver Bell |
| Hudbay Minerals | Copper | TSX, NYSE: HBM | Copper World (AZ, in development) | None yet; first production targeted for 2029 | In-pit conveying and filtered tailings |
| Barrick Mining | Gold, copper | NYSE: B; TSX: ABX | 61.5% of Nevada Gold Mines; Fourmile (NV) | About 1.6 million oz, 2025, implied from the joint venture split | Thiosulphate recovery; Fourmile high-grade discovery |
| Newmont | Gold | NYSE: NEM | 38.5% of Nevada Gold Mines | 999,000 oz attributable, 2025 | A narrower US footprint after selling its Colorado mine |
| Kinross Gold | Gold | TSX: K; NYSE: KGC | Fort Knox (AK); Round Mountain, Bald Mountain (NV); Curlew (WA) | About 733,000 gold-equivalent oz, 2025, with Manh Choh at 100% | Moving from open pit to higher-grade underground |
| Coeur Mining | Gold, silver | NYSE, TSX: CDE | Rochester (NV), Kensington (AK), Wharf (SD) | About 264,000 oz gold, 2025 | Crushing rates at the expanded Rochester mine |
How we chose these copper and gold miners
We kept the seven companies this page has always covered, and we checked each one against its latest reports. To stay on the list, a company needs a producing mine or an approved construction project in the United States. We then looked for one technical change that the company itself describes in a filing or release, with a number or a date attached.
This is not every qualifying company. Rio Tinto, Capstone Copper and SSR Mining also matter, and they are covered in a section further down. For a wider view of American miners beyond copper and gold, see our guide to mining companies in US and the map of active US mines by state.
US copper output and why these companies matter
US mine output of copper fell from 1,230 thousand tons in 2021 to an estimated 1,000 thousand tons in 2025, according to USGS. Net import reliance rose to 57% of apparent consumption in the same estimate. That gap helps explain why new American projects draw attention. USGS counts 26 copper mines, of which 17 produced more than 99% of mine output, so a few operators shape the national total.
Chart
US mine copper output has slipped since 2021
Recoverable copper, thousand metric tons; 2025 is an estimate
If you want the geology behind these districts, our guide on where copper is found explains the main deposit types. Most large Arizona mines work porphyry deposits, which are huge, low-grade bodies of rock formed around old magma intrusions. Grade means the share of metal in the rock, and in copper it is given as a percentage.
Copper mining companies in the USA
1. Freeport-McMoRan: copper from leaching
Best known for: the largest group of US copper operations on this list. Freeport manages seven US copper operations: Morenci, Bagdad, Safford (including Lone Star), Sierrita and Miami in Arizona, and Chino and Tyrone in New Mexico. It holds 72% of Morenci. It also runs a smelter and rod mill in Miami, Arizona, and a refinery and rod mill in El Paso, Texas. Its share of US mine output was 641 million pounds of copper in the first half of 2026, against 637 million a year earlier.
The innovation: leaching dissolves copper out of rock with a solution, then recovers it from that liquid. Freeport is adding new technology and data analytics to these circuits across the US and South America. The initiatives gave 101 million pounds of extra copper in the first half of 2026, and the company is targeting a run rate of 300 million pounds a year by the end of 2026.
What to check: whether the run-rate target was met, and the decision on more than doubling Bagdad’s concentrator capacity, which the July 2026 release placed in the second half of 2026. A concentrator is the plant that separates copper minerals from waste rock.
2. Asarco: three Arizona mines and an idle smelter
Best known for: a very long US history, dating from its 1899 start as American Smelting and Refining Company. In a Western USA Mining 2025 interview, its chief executive said Asarco produces at Ray, Mission and Silver Bell in Arizona. He also said the Hayden concentrator and smelter would stay inactive while the company assessed how to resume, and that the Amarillo refinery would restart once the smelter does.
The innovation: not new, but useful to understand. The company history records a solvent extraction and electrowinning plant at Silver Bell, started in 1997. This route makes finished copper cathode at the mine, so that copper does not need a smelter. The same interview says Silver Bell produces cathode, while concentrate from Mission and Ray is trucked to Guaymas while Hayden is idle.
What to check: any restart news for Hayden. The interview put investment at around US$1 billion in 2023 and close to US$1.1 billion budgeted for 2024.
3. Hudbay Minerals: a new Arizona mine approved for construction
Best known for: Copper World, about 50 km (31 miles) southeast of Tucson. On 21 October 2026, Hudbay and Mitsubishi approved construction, with first production targeted for 2029. Hudbay owns 70% and Mitsubishi 30%, after a US$600 million investment. The feasibility study outlines 102,000 tonnes of copper a year over the first 10 years. In March 2026 Hudbay also announced a deal for Arizona Sonoran, owner of the Cactus project.
The innovation: in-pit crushing and conveying from year four, which moves ore by belt and needs fewer haul trucks. The plan also converts about one-third of tailings to filtered tailings, meaning waste with much of the water removed. Tailings are the fine waste left after processing. A permitted concentrate leach plant that could make cathode on site is treated as a future option, not part of the base plan.
What to check: these are study numbers, not results. The mine has not been built, so costs and dates can move.
Gold mining companies in the USA
US gold output has drifted down, from 187 tons in 2021 to an estimated 160 tons in 2025 (USGS). USGS says more than 40 lode mines in 12 states produce gold, and the top 25 operations yield about 94% of the total. A lode mine works gold in solid rock, as opposed to a placer mine, which works loose gravel. About 7% of US gold comes as a by-product of other ores, mainly copper. For a state-by-state view of sites, see our list of active gold mines in the USA.
Chart
US gold mine production
Metric tons; 2025 is an estimate
4. Barrick Mining: Nevada Gold Mines and Fourmile
Best known for: operating Nevada Gold Mines (NGM), its joint venture with Newmont. Newmont’s annual filing gives the split as Barrick 61.5% and Newmont 38.5%, with Barrick operating. NGM includes Carlin, Cortez, Turquoise Ridge and Phoenix. Newmont’s 999,000 attributable ounces imply about 1.6 million ounces for Barrick’s share in 2025; that is our arithmetic from the split, not a company figure.
The innovation: two stand out. First, Barrick was reported by Canadian Mining Journal in 2015 as the first producer to commercialize thiosulphate gold recovery, in Nevada, which replaces cyanide in that process. Second, at its wholly owned Fourmile project, Barrick’s February 2026 results report 2.6 million ounces of indicated resources at 17.59 g/t and 13 million ounces of inferred resources at 16.9 g/t. The unit g/t means grams of gold per tonne of rock. Inferred resources carry the least geological confidence and are not reserves.
What to check: the planned initial public offering of a new company holding its North American gold assets, which the February 2026 release expected by late 2026. Also check how Fourmile is treated, as Barrick says it may be contributed to NGM at fair market value if certain criteria are met.
5. Newmont: a smaller, joint-venture US position
Best known for: being a very large global gold producer, though its US production now comes through one holding. Newmont’s 2025 operating statistics show 999,000 attributable ounces from NGM, against 1,039,000 in 2024. Newmont does not directly manage these mines.
The change: this one is about portfolio, not technology. Newmont completed the sale of the Cripple Creek & Victor mine in Colorado to SSR Mining on 28 February 2025, according to its filing.
What to check: anyone comparing Newmont’s global totals with US mining should separate the two. Most of its output is outside the United States.
6. Kinross Gold: from open pit to underground
Best known for: three producing US mines. Its 2025 results list Fort Knox in Alaska at 410,822 gold-equivalent ounces, Bald Mountain in Nevada at 179,169 and Round Mountain in Nevada at 143,402. Fort Knox rose on a full year of higher-grade ore from Manh Choh. Round Mountain’s fall reflects planned mine sequencing.
Chart
Kinross US mines, 2024 to 2025
Thousand gold-equivalent ounces
The innovation: in January 2026, Kinross announced construction decisions on Round Mountain Phase X, Curlew and Bald Mountain Redbird 2. Together they are expected to contribute 3 million ounces and extend Nevada mine lives well into the 2030s. At Round Mountain, higher-margin underground reserves at 3.2 g/t replaced lower-margin open-pit reserves at 0.8 g/t. The change extends mine life by eight years to 2038.
What to check: progress updates. The second-quarter 2026 release said development at Phase X was slightly ahead of schedule and development at Curlew ahead of schedule.
7. Coeur Mining: gold and silver with a bigger crusher
Best known for: a mix of gold and silver across Nevada, Alaska and South Dakota. Its 2025 results show gold production of 106,068 ounces at Kensington, 97,327 at Wharf and 60,178 at Rochester. Coeur also has mines outside the United States, and its acquisition of New Gold closed in late March 2026, adding two Canadian mines.
The innovation: the Rochester heap-leach mine, where crushed ore is stacked on lined pads and leached. In the fourth quarter of 2025 it set records for tonnes crushed (6.4 million) and tonnes placed (9.3 million). Coeur also reported record crusher performance there in the second quarter of 2026. The company also said Wharf’s mine life nearly doubled to twelve years after its reserve update.
What to check: silver grades. Coeur reported lower grades at Rochester in the second quarter of 2026, which partly offset the crushing gains.
▶ How gold moves from rock to refined metal, step by step · 5:27
Other US copper and gold companies to know
- Rio Tinto (Kennecott, Utah): runs the Bingham Canyon operation. KUTV reported a US$1.5 billion investment in December 2019 to extend operations until 2032.
- Capstone Copper (Pinto Valley, Arizona): 100% owned open pit with 60,000 tonnes per day of milling capacity and a stated mine life to 2039.
- SSR Mining (Marigold, Nevada; Cripple Creek & Victor, Colorado): Nasdaq and TSX listed under SSRM, and now the owner of the Colorado mine that Newmont sold.
Alaska has its own group of operators and explorers, covered in our guide to Alaska mining companies. For a global comparison, see the largest copper producers, the top 20 gold and copper companies worldwide and our look at American copper mining stocks. For a metal beyond these two, see our note on tungsten for stainless steel in Canada.
What the innovations have in common
Strip away the press language and the real changes fall into four groups.
Chart
US gold output of four companies, 2025
Thousand ounces; bases differ, Kinross is gold-equivalent with Manh Choh at 100%, Barrick is implied
- More metal from existing rock: Freeport’s leaching work aims to recover more copper from material already mined, without opening new ground.
- Going underground for grade: Kinross at Round Mountain and Barrick at Fourmile target higher-grade rock, where each tonne holds far more gold.
- Moving less by truck: Hudbay’s planned in-pit conveying replaces part of the haul fleet. Coeur’s crushing gains increase the tonnage placed on its leach pads.
- Handling water and waste: Hudbay’s filtered tailings plan lets the concentrator expand with no additional water supply, and thiosulphate recovery replaces cyanide in the process where it is used.
Copper and gold prices behind these decisions
COMEX copper was shown at US$6.42 per pound on 5 November 2026 (MetalCharts), and gold at about US$4,141 per ounce on 4 November 2026 (PriceGold.net). USGS estimates a 2025 average of 480 cents per pound for COMEX copper and US$3,300 per ounce for gold. Hudbay’s Copper World study quotes value at both US$5.00 and US$6.00 per pound long-term copper, which shows how much the price assumption matters.
Prices move daily, so treat these as dated snapshots and use today’s price in the calculator below.
Calculator
What is the recoverable metal in a deposit worth?
Enter your own tonnage, grades, recoveries and prices in US$.
- Recoverable copper, lb: 8,818,480
- Recoverable gold, oz: 25,721
- Copper value, US$: $44,092,400
- Gold value, US$: $102,882,312
Example values only, not a benchmark or a valuation. Prices are inputs: example, use today’s price. Gross value before mining, processing, royalties and tax. Conversions: 31.1035 g per troy ounce and 2,204.62 lb per tonne.
How to compare a copper or gold company yourself
- Split US and global output. Newmont, Barrick and Hudbay all have large assets abroad, or no US output yet.
- Check the ownership basis. A 100% figure and an attributable figure can differ widely, as NGM shows.
- Check who operates. Newmont holds 38.5% of NGM, but Barrick runs it.
- Separate reserves, resources and study numbers. Reserves are the economically mineable part; inferred resources are the least certain; a study is a forecast.
- Read the mine’s stage. A permitted project, an approved build and a producing mine carry different risks.
- Check water and permits. Arizona and Nevada projects depend on water rights and state permits.
Licence and claim owners can use the same logic on smaller ground. Satellite imagery can screen a property for surface alteration and structure before money goes into drilling, and it produces exploration targets, not a resource estimate. Farmonaut offers satellite-based mineral detection for this step, and you can request a tailored quote or contact us with your boundary.
▶ How satellites map the rock around gold systems · 4:25
Groundwater and mining: how to read public well data
Water supply is a common question near any mine or proposed project, and US public records can answer part of it. The Safe Drinking Water Act required states and utilities to assess their source water, and some resulting state documents list details such as well depth and aquifer type for public water systems. If you need a worked example for one Illinois town, including what aquifer code 0101 means, see what Farmer City’s SWAP factsheet shows. That page now holds the topic, so this one stays on mining companies.
▶ The seven environmental impacts of mining, including effects on water · 2:31
Frequently asked questions
What is the largest copper mining company in the USA?
Among the companies compared here, Freeport-McMoRan reports the largest group of US copper operations, with seven sites and 641 million pounds in the first half of 2026. USGS estimates total US mine output at 1.0 million tons in 2025.
Which companies mine the most gold in the USA?
Nevada Gold Mines, owned by Barrick and Newmont, is the largest holding on this list. Newmont reports 999,000 attributable ounces for 2025, and Kinross reports about 733,000 gold-equivalent ounces from three US mines.
Which state produces the most copper?
Arizona, at about 70% of US output in 2025, according to USGS. Copper is also mined in Alaska, Michigan, Missouri, Montana, Nevada, New Mexico and Utah.
Which state produces the most gold?
Nevada, at about 64% of US output in 2025, followed by Alaska at about 22% (USGS).
Who owns Nevada Gold Mines?
Barrick holds 61.5% and operates it. Newmont holds 38.5%, according to Newmont’s 2025 annual filing.
Are Barrick and Kinross American companies?
Both report from Toronto, and both have large US mines. Barrick is listed as NYSE: B and TSX: ABX, and Kinross as TSX: K and NYSE: KGC.
When will Copper World start producing?
Hudbay and Mitsubishi approved construction in October 2026 and target first production in 2029. Treat that date as a plan until the mine is built.
Does Newmont still own US mines directly?
Its US production now comes through its 38.5% interest in Nevada Gold Mines. It sold Cripple Creek & Victor in Colorado to SSR Mining in February 2025.
What is thiosulphate gold recovery?
It is a process that recovers gold with a thiosulphate solution in place of cyanide. Canadian Mining Journal reported in 2015 that Barrick was the first producer to commercialize it, in Nevada.
What is the difference between a resource and a reserve?
A resource is mineralized rock with reasonable prospects of extraction. A reserve is the part shown to be economically mineable. Inferred resources have the lowest confidence.
This page is for information only. It is not investment advice.
Farmonaut mining
Map your own project area from space
Request a quote for satellite screening of your own licence or claim area.

Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026: Copper: pubs.usgs.gov
- USGS, Mineral Commodity Summaries 2026: Gold: pubs.usgs.gov
- Freeport, second-quarter 2026 results (July 2026): s22.q4cdn.com
- Asarco, company history: asarco.com
- GBR, Western USA Mining 2025: Asarco and Hudbay interviews: projects.gbreports.com
- Hudbay, Copper World construction approval (October 2026): s23.q4cdn.com
- Hudbay, closing of Mitsubishi investment (2026): s23.q4cdn.com
- Hudbay, Arizona Sonoran acquisition (March 2026): s23.q4cdn.com
- Newmont, 2025 Form 10-K: s24.q4cdn.com
- Newmont, Q4 2025 operating statistics: s24.q4cdn.com
- Barrick, full-year and Q4 2025 results (February 2026): finviz.com
- Canadian Mining Journal, Barrick cyanide-free gold recovery (May 2015): canadianminingjournal.com
- Kinross, Q4 and full-year 2025 results (February 2026): finviz.com
- Kinross, Q2 2026 results: s204.q4cdn.com
- Coeur, Q4 and full-year 2025 results: s201.q4cdn.com
- Coeur, Q2 2026 results (August 2026): nasdaq.com
- KUTV, Kennecott US$1.5 billion investment: kutv.com
- Capstone Copper, Pinto Valley: capstonecopper.com
- SSR Mining, 2025 results (February 2026): ssrmining.com
- US EPA, basic information about source water protection: epa.gov
- MetalCharts, COMEX copper price (5 November 2026): metalcharts.org
- PriceGold.net, gold price (4 November 2026): pricegold.net
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited

 Client · Tanzania · Gold










