

Dysprosium · Mines and price guide
Dysprosium Mines Worldwide: List and Price Chart
Dysprosium is a by-product of rare earth mining. China and Burma supply over 90% of heavy rare earth mine output; Lynas reported 19 tonnes of dysprosium and terbium in the June 2026 quarter. Fastmarkets assessed oxide outside China at US$2,500 to 3,500 per kg on 1 October 2026.
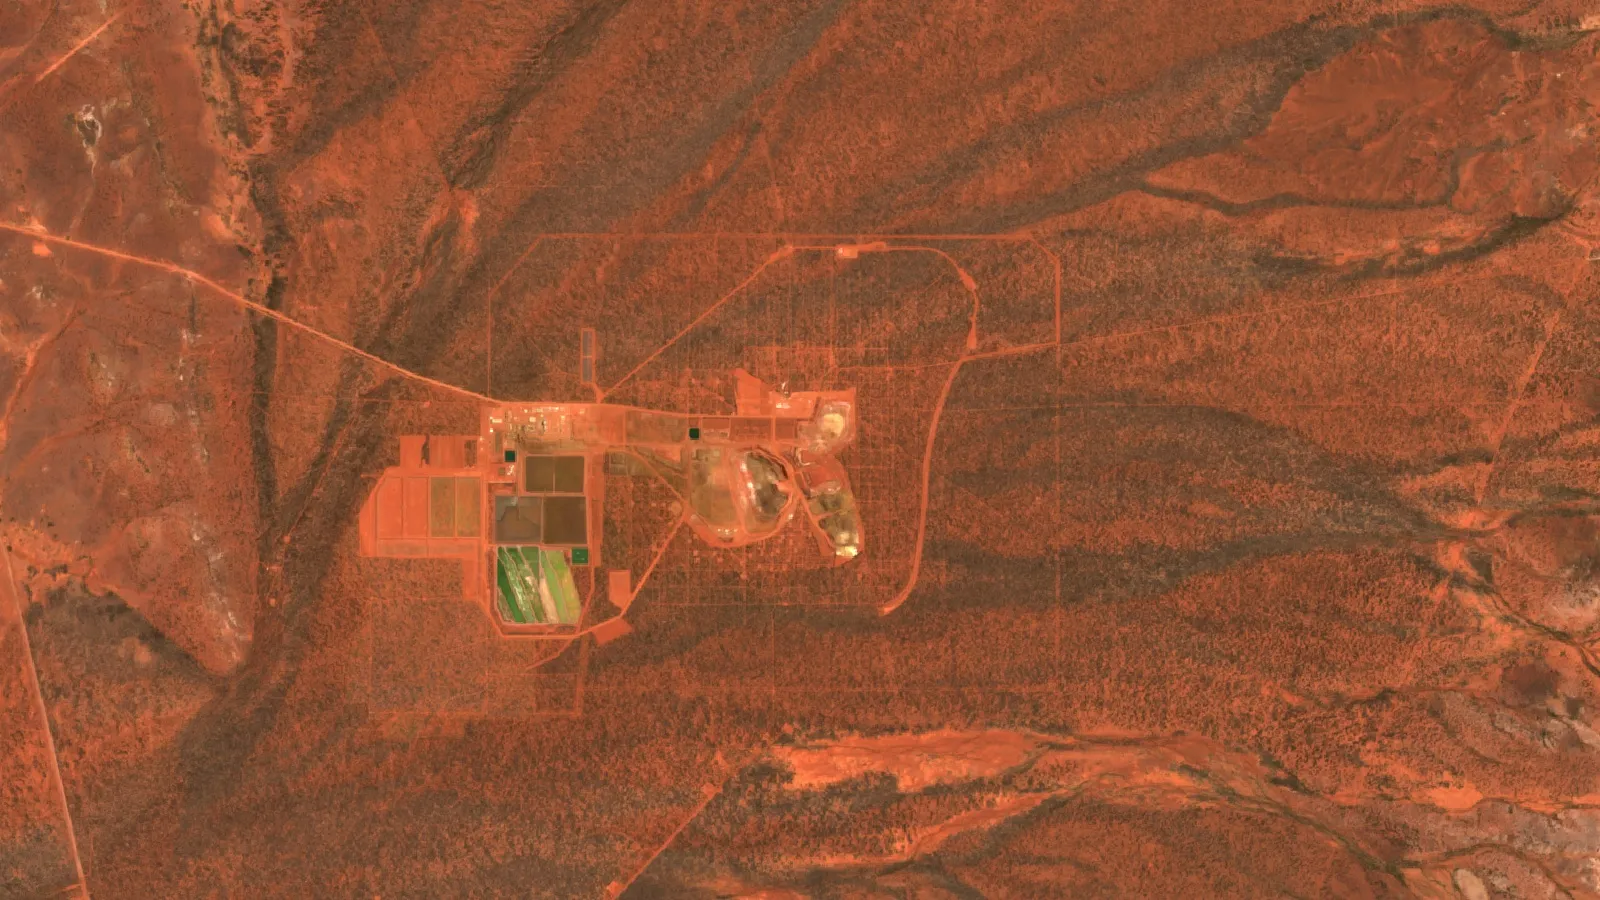
Key takeaways
- China and Burma account for more than 90% of world heavy rare earth mine production (CRU, quoted by Northern Minerals, July 2026); the USGS puts China at about 69% of all rare earth oxide mined in 2025.
- Outside China, Lynas reported 19 tonnes of dysprosium plus terbium in the June 2026 quarter, after 8 tonnes in the March quarter (Lynas, Kalkine).
- Dysprosium oxide 99.5%, CIP global, was assessed at US$2,500 to 3,500 per kg on 1 October 2026 (Fastmarkets); the USGS 2025 US average was US$239 per kg.
- China’s April 2025 dysprosium export licences remain; a wider October 2025 package is suspended until 10 November 2026, and we found no rare earth-specific extension notice by 15 October 2026, though a wider trade truce was reported extended to 10 January 2027.
- Browns Range plans Dy, Tb and Y at about 78% of basket value but had no confirmed final investment decision by 15 October 2026; Caldeira’s study target is 127 tonnes a year of dysprosium and terbium.
In this article
- Which mines produce dysprosium, and how much?
- Dysprosium mines and projects compared
- How we chose these projects
- Dysprosium price: dated figures and what moves them
- China's dysprosium export rules: what is suspended and what is not
- What it costs to build a dysprosium supply chain
- Estimate the dysprosium in a rare earth deposit
- How explorers find heavy REE deposits
- What satellite screening can and cannot tell you
- Recycling, thrifting and substitutes
- What to check before you plan around a dysprosium price
- Frequently asked questions
Dysprosium (Dy, atomic number 66) is not mined on its own. It comes out of rare earth ores, and most of it comes from ion-adsorption clay mines in southern China and Burma, which CRU data quoted in a July 2026 Northern Minerals investor presentation put at more than 90% of world heavy rare earth mine output. Outside that belt, output is still measured in tonnes per quarter: Lynas reported 19 tonnes of dysprosium and terbium oxide in the June 2026 quarter.
The price depends on which side of China’s export licences you buy. The USGS puts the 2025 average dysprosium oxide price in its US table at US$239 per kilogram, while Fastmarkets assessed 99.5% dysprosium oxide delivered outside China at US$2,500 to 3,500 per kilogram on 1 October 2026. The two numbers are not like for like, and the gap between them is the story of this market.
This page lists the mines and projects that matter for dysprosium, with their status as of 15 October 2026, dated price points with the basis stated, where China’s export rules stand, what plants cost to build, and a calculator for the dysprosium inside a deposit. If you are new to the family of elements, our list of heavy and light rare earth elements gives the groupings, and our guide to rare earth separation and hydrometallurgy explains how dysprosium is split from its neighbours.
Which mines produce dysprosium, and how much?
No agency publishes dysprosium mine output by country. The USGS reports total rare earth oxide (REO), which adds every rare earth element together as oxides, so the chart below shows where rare earth mining happens, not dysprosium tonnes. In the USGS estimates for 2025, China produced 270,000 tonnes of REO out of a rounded world total of 390,000 tonnes, about 69%, followed by the United States at 51,000 tonnes and Australia at 29,000 tonnes (USGS, Mineral Commodity Summaries, February 2026). Burma was fourth at 22,000 tonnes, down from 27,000 tonnes in 2024.
Chart
Rare earth mining among selected producers, estimated 2025
Mine production, selected countries, tonnes of total rare earth oxide (all elements, not dysprosium alone)
Dysprosium is a small part of that tonnage. The USGS fact sheet on rare earth elements lists an average of 5.2 parts per million in the Earth’s crust, and notes that ion-adsorption clay deposits in southern China are the world’s primary source of heavy rare earths. These clays hold only about 0.04% to 0.25% total rare earth oxide, yet they pay because the elements come off the clay with weak acids and are rich in the valuable heavy elements. Canada’s resource agency says China and Burma remain almost the sole producers of heavy REEs (Natural Resources Canada).
That is why a mine count is the wrong measure. A hard-rock carbonatite such as Mount Weld in Western Australia produces mostly light rare earths, and its dysprosium is a small by-product that has to be separated downstream. Ion-adsorption clays are often enriched in the heavy elements, and Browns Range’s xenotime is rich in dysprosium, which is why projects of those types get most of the attention in the next section.
Dysprosium mines and projects compared
The table groups the main sources by what they are and where they stand. Several are processing plants or development projects rather than mines, and the status column says so. Tonnes are of oxide unless stated.
| Project | Country | Type | Status (15 October 2026) | Dysprosium fact |
|---|---|---|---|---|
| Southern China and Burma clays | China, Burma | Ion-adsorption clay mines | Operating | More than 90% of world heavy rare earth mine output (CRU, via Northern Minerals) |
| Mount Weld mine and Lynas Malaysia plant | Australia, Malaysia | Carbonatite mine, separation plant | Operating; heavy rare earth expansion under way | 19 t Dy and Tb in the June 2026 quarter |
| Mountain Pass | United States | Bastnaesite mine | First heavy REE separation circuit completed; Dy and Tb output expected later in 2026 | US$150 million Department of War loan (USGS) |
| White Mesa Mill | United States | Processing mill | Operating; heavy rare earth plant under construction | Commercial NdPr oxide; Dy in pilot phase, Tb in lab phase (Energy Fuels) |
| Serra Verde (Pela Ema) | Brazil | Ion-adsorption clay mine | Ramping up; sold to USA Rare Earth | An unnamed Brazilian clay mine makes mixed Tb and Dy concentrate (USGS) |
| Caldeira | Brazil | Ion-adsorption clay project | Feasibility study done; Lynas takeover agreed, awaiting approvals | 127 t a year of Dy and Tb in the study |
| Browns Range | Australia | Xenotime hard-rock project | Engineering stage; funding not confirmed (non-binding EXIM and Export Finance Australia support only) | Dy, Tb and Y are about 78% of planned basket value |
| Eneabba refinery (Iluka) | Australia | Refinery | Under construction | Designed to make Nd, Pr, Dy and Tb oxides |
Mount Weld and Lynas Malaysia
Best for: seeing one of the few dysprosium and terbium oxide producers outside China. Lynas mines Mount Weld, ships concentrate to Malaysia and reported ready-for-sale dysprosium plus terbium of 9 tonnes in the September 2025 quarter, 26 tonnes in the December quarter and 8 tonnes in the March 2026 quarter (Lynas quarterly report); the June 2026 quarter was 19 tonnes. Watch: Lynas says concentrate quality problems at Mount Weld cut finished product in the June quarter, and the cost of its expanded heavy rare earth plant rose from about A$180 million to A$294 million (Lynas annual results).
Mountain Pass, California
Best for: following US domestic supply. Mountain Pass mines bastnaesite for light rare earths, and the USGS reports, without naming the company, a US$150 million Department of War loan to a producer at Mountain Pass to build a heavy REE separation facility there in 2025 (USGS, heavy rare earths chapter). Watch: the USGS says that in 2025 no US company produced sustained commercial-scale quantities of heavy rare earth compounds. MP Materials said in its second-quarter 2026 results (6 August 2026) that its first heavy REE separation circuit was complete and that terbium and dysprosium output is expected later in 2026 (MP Materials). We found no report of first dysprosium output by 15 October 2026.
White Mesa Mill, Utah
Best for: a US processing route where dysprosium is still at pilot scale. Energy Fuels completed its purchase of Australian Strategic Materials on 28 August 2026 and describes White Mesa Mill as part of its oxide supply chain. Energy Fuels’ own mill page says the mill makes commercial neodymium-praseodymium oxide, with dysprosium in pilot phase and terbium in lab phase, and a commercial-scale heavy rare earth expansion began construction on 29 July 2026 (Energy Fuels; ColoradoBiz report). Watch: it is a mill that processes feed, not a mine, and the report gives no dysprosium tonnage.
Serra Verde, Brazil
Best for: a clay mine already producing mixed concentrate outside China. The USGS describes an unnamed Brazilian mine, which it does not identify as Serra Verde, producing mixed concentrate from ionic clays with elevated terbium and dysprosium, and a US$465 million loan approved in November 2025 by the US International Development Finance Corporation (USGS). A trade report of 22 September 2026 says USA Rare Earth has completed its acquisition of the Pela Ema project for up to US$2.8 billion and that the project is ramping up toward 6,400 tonnes of rare earth oxides a year (SMM report). Watch: that report gives no separate dysprosium capacity.
Caldeira, Brazil
Best for: a large clay resource outside China. Lynas announced on 1 October 2026 an agreed all-share takeover of Meteoric Resources by scheme of arrangement, valued at A$968 million and unanimously supported by the Meteoric board. Meteoric’s resources include 41,000 tonnes of dysprosium and terbium oxide, and the feasibility study target averages about 127 tonnes a year of the two over the mine life (Lynas ASX announcement). Watch: the deal needs shareholder and court approval, and a scheme booklet is expected in December 2026. Caldeira is a study-stage project, not a producer.
Browns Range, Western Australia
Best for: a hard-rock source rich in dysprosium. Northern Minerals reports 7.3 million tonnes at 0.96% total rare earth oxide in resource and 5.2 million tonnes at 0.88% in reserve, with xenotime as the host mineral and dysprosium, terbium and yttrium together making up about 78% of planned basket value (investor presentation, 23 July 2026). Watch: the company targeted a final investment decision in the third quarter of 2026 subject to funding, and we found no announcement of one by 15 October 2026.
Eneabba refinery, Western Australia
Best for: the Australian processing link. Per the same presentation, quoting Iluka’s disclosures, the refinery costs about A$1.7 to 1.8 billion, is more than half built, targets commissioning in mid-2027 and will make separated neodymium, praseodymium, dysprosium and terbium oxides. Watch: it depends on feed from mines such as Browns Range, which has not yet been financed.
How we chose these projects
A project is on the list if a company filing, an exchange announcement or a government report names dysprosium for it and we could open that document. We checked status against the most recent filing we could find, and wrote “not confirmed” where we found none. We did not rank projects by quality or value, and we left out projects whose filings give no dysprosium figure. Nothing here is a recommendation to buy or sell any share, and the notes on export rules and licences are not legal advice.
Chart
Lynas dysprosium plus terbium, ready for sale
Tonnes of oxide per quarter
Dysprosium price: dated figures and what moves them
Prices below come from different assessments, so read the basis before comparing. FOB means the seller loads the goods onto the ship at the exporting port. CIP global means carriage and insurance paid to a delivery point outside China. Oxide is the usual traded form, at 99.5% purity for dysprosium.
Chart
US average dysprosium oxide price, 2021 to 2025
US dollars per kilogram, 99.5% minimum, FOB basis
| Date | What was measured | Price | Source |
|---|---|---|---|
| 2021 to 2025 | US average, dysprosium oxide 99.5%, FOB | US$410 falling to US$239 per kg | USGS, Mineral Commodity Summaries 2026 |
| May 2026 | Outside China, dysprosium oxide | About US$1,450 per kg | Argus data cited by Reuters, via The Oregon Group (10 June 2026) |
| 9 July 2026 | China domestic, Baotou exchange, 99.5% | About 1,419 yuan per kg | SunSirs, quoting the exchange; about three months old |
| 24 September 2026 | CIP global, dysprosium oxide 99.5% | US$1,910 to 2,500 per kg | Fastmarkets (6 October 2026) |
| 1 October 2026 | CIP global, dysprosium oxide 99.5% | US$2,500 to 3,500 per kg | Fastmarkets (6 October 2026) |
The USGS series shows a market that was falling until 2025. Then China’s April 2025 export licences split it in two. The Oregon Group, citing Argus data, reports that dysprosium oxide outside China rose to about US$1,450 per kilogram by May 2026, four to five times its level before the controls, while shipments of yttrium, dysprosium and terbium from China were still down about 50% against the 12 months before April 2025. An Argus market paper of 11 August 2026 describes a two-tier heavy rare earth market that separates licensed from non-licensed buyers.
On 1 October 2026 the low end of the Fastmarkets range was more than ten times the 2025 USGS average, although the two series use different bases and periods. The price jump that week was tied to US demand ahead of rules that bar the Pentagon from buying magnets containing Chinese-processed material from January 2027 (Fastmarkets). Fastmarkets also quotes Lynas saying the market for heavy REEs outside China is only about 400 tonnes a year, so small orders move the price. For ongoing figures on other elements, see our page on rare earth metal prices.
- Export licences: they restrict who can buy Chinese material and how much.
- Defence sourcing rules: US buyers pay more than European buyers for non-Chinese material, per Fastmarkets.
- Thrifting: magnet makers keep cutting dysprosium per magnet, which slows demand growth.
- New supply: Lynas, Serra Verde and others add tonnes, but still only dozens a year.
China’s dysprosium export rules: what is suspended and what is not
As of 15 October 2026, China’s April 2025 licensing rules for dysprosium are still in force, and a wider October 2025 package is suspended until 10 November 2026. We found no official notice extending or ending that suspension. Reports say a 28 September 2026 Ministry of Commerce statement extended the wider US-China trade truce to 10 January 2027, but it does not explicitly mention the rare earth controls and the legal notice still reads 10 November 2026, so treat the date as unsettled.
Chart
Heavy rare earth price ranges outside China, 1 October 2026
US dollars per kilogram, CIP global: low and high of each assessment
- April 2025: China’s commerce ministry added samarium, gadolinium, terbium, dysprosium, lutetium, scandium and yttrium, with their metals, oxides, alloys, compounds and magnet materials, to its export control list, so each shipment needs a licence (Pillsbury legal alert).
- October 2025: a second package added more elements, equipment, technology and a foreign-product rule, then was suspended for one year in November 2025. The USGS notes that as of December 2025 the April controls remained, although China began issuing general licences to selected exporters (USGS).
- Expiry: the suspension is set to end on 10 November 2026, and analysts list extension, selective reinstatement and full reimposition as the possible outcomes (Mining Technology analysis, April 2026).
- Trade flows: Fastmarkets reports that China has exported no dysprosium oxide or terbium oxide directly to Japan this year, according to Chinese customs data.
So dysprosium is licensed, not banned. Check the commerce ministry’s announcements before you sign a contract that depends on Chinese supply, because the position can change within days.
What it costs to build a dysprosium supply chain
Buyers pay the oxide price, but developers pay to build. Capex means capital spending before production starts, and opex is the operating cost per unit. TREO means total rare earth oxide, the combined oxide content of all rare earths in a concentrate. Published figures give a sense of scale:
- Browns Range feasibility study: A$592 million capex (real, fourth-quarter 2024 base, before working capital and financing) and operating cost of A$31.25 per kilogram of TREO, with a pre-tax net present value of A$187 million in the base case and A$705 million in the divergence case (Northern Minerals).
- Lynas Malaysia heavy rare earth expansion: about A$294 million including contingency, up from about A$180 million, because of extra equipment for customer purity specifications, dearer equipment sourced outside China and cost escalation (Lynas).
- Eneabba refinery: about A$1.7 to 1.8 billion, with an A$1.65 billion Australian government loan (per Iluka disclosures summarised by Northern Minerals).
- US government loans: US$150 million for a heavy rare earth plant at Mountain Pass and US$465 million for a Brazilian clay mine (USGS).
Two points follow. First, much of the spend is in separation, not mining, which is why a plant outside China can cost more than its mine. Second, the Browns Range study sets the divergence case, which assumes prices outside China stay apart from Chinese prices, against a base case; the net present value is almost four times higher in the divergence case. Any dysprosium project is a bet on the price gap as well as on the rock.
Estimate the dysprosium in a rare earth deposit
The calculator turns ore tonnes, grade and recovery into kilograms of dysprosium oxide and a revenue figure. Grade is the percentage of total rare earth oxide in the ore. The dysprosium share is the portion of that oxide that is dysprosium, which your assay or the company’s resource table gives. Recovery is the share that survives mining, concentrating and separation. Treat the output as a first screen, not a resource estimate.
Calculator
How much dysprosium oxide could a deposit hold?
Enter your own ore tonnes, grade and recovery.
- Dysprosium oxide per tonne of ore (kg): 0.27
- Dysprosium oxide per year (tonnes): 27.0
- Revenue at your price (US$ per year): $27,000,000
Example values only, not a benchmark or a resource estimate. The 0.9% grade is a round figure near the Browns Range reserve grade (Northern Minerals, 2026); the dysprosium share, recovery and price are placeholders. Price is an input: example, use today’s price. Money is in US$.
How explorers find heavy REE deposits
The USGS names four settings where rare earths reach economic grades: carbonatites, alkaline igneous systems, ion-adsorption clays and placers that carry monazite and xenotime (USGS fact sheet). Of more than 500 known carbonatites, only 6 were mined for rare earths when the fact sheet was written in 2014. Alkaline igneous bodies are sought because they are often enriched in the heavy elements, and the fact sheet cites grades of 0.3% to 2.6% total rare earth oxide for advanced projects.

▶ Farmonaut video on rare earth exploration in Canada, using geochemistry, satellite mapping and soil surveys. · 2:25
A typical programme starts with geological maps and surface sampling, then drilling. Because rare earth minerals often sit with thorium and uranium, many explorers also run radiometric surveys. Weathering and clay formation matter for ion-adsorption deposits, because the elements are leached from granite and held on the clay, as the USGS describes. A single sample cannot show how the heavy fraction behaves in processing, so test work on the dysprosium share is as important as the headline grade.
What satellite screening can and cannot tell you
Satellite imagery can map rock types, alteration and weathered clay cover over a licence before any crew goes out. It cannot measure dysprosium directly, and it is not a resource estimate. Farmonaut offers satellite mineral screening that includes rare earth elements, delivered in 5 to 20 business days from a boundary file, and its results are exploration targets to be tested by sampling and drilling.
▶ Farmonaut explainer on remote sensing for mining, in plain words. · 2:01
Recycling, thrifting and substitutes
Recycling is small so far. The USGS says small quantities of heavy rare earths were recovered from permanent magnets in 2025, and that the Department of War lent US$80 million to a recycler in Indiana and awarded US$5.1 million to another in Texas (USGS). On substitutes, the USGS says they exist for some uses but are generally less effective, and light rare earths can replace heavy ones in several applications. Fastmarkets quotes industry participants saying dysprosium use per magnet has fallen for years through grain boundary diffusion and changes to grain size and alloy, while the metal stays critical for high-performance magnets. For wider demand drivers, see our summary of rare earth demand trends.
What to check before you plan around a dysprosium price
- Which assessment is quoted: FOB China, CIP global or a contract price, and for which purity.
- Whether a price is a range or an average, and its date. Prices in this market moved by tens of percent within one week in October 2026.
- Whether a project’s dysprosium figure is a resource, a reserve or a production target, and whether it is Measured, Indicated or Inferred.
- Where separation will happen, and who holds the licence to export the intermediate.
- Whether the offtake is fixed price, market-linked or has a floor. Browns Range reports both fixed and market-linked mechanisms in its Iluka agreement.
- The date of China’s suspension decision, 10 November 2026, and any change to licensing.
Frequently asked questions
Which country mines the most dysprosium?
China, with Burma. Northern Minerals, quoting CRU, says China and Burma account for more than 90% of world heavy rare earth mine production, and the USGS shows China at about 69% of all rare earth oxide mined in 2025. Exact dysprosium tonnes by country are not published.
Is there a dysprosium mine in the United States?
Not a dysprosium mine as such. Mountain Pass mines bastnaesite, which is rich in light rare earths, and a heavy REE separation circuit has been completed there, with dysprosium and terbium output expected later in 2026 according to MP Materials. White Mesa Mill in Utah, which is a processing plant, is piloting dysprosium oxide, according to Energy Fuels, with a commercial-scale heavy rare earth expansion under construction. The USGS says no US company yet produced sustained commercial-scale heavy rare earth compounds in 2025.
How much does dysprosium oxide cost per kilogram?
It depends on the basis and date. The USGS gives a 2025 US average of US$239 per kilogram. Fastmarkets assessed dysprosium oxide 99.5%, CIP global, at US$2,500 to 3,500 per kilogram on 1 October 2026, and Baotou exchange data via SunSirs showed about 1,419 yuan per kilogram in China on 9 July 2026.
Why is dysprosium so expensive outside China?
China requires licences for dysprosium exports since April 2025, and the ex-China market is small, about 400 tonnes a year of heavy REE demand according to Lynas. Buyers who cannot get Chinese material compete for limited supply, and US defence sourcing rules due in January 2027 add demand.
Did China ban dysprosium exports?
No. It added dysprosium to its export control list in April 2025, which means shipments need a licence. A wider package from October 2025 was suspended for a year, to 10 November 2026. Exports to some destinations have fallen sharply, for example none of the oxide went directly to Japan this year, according to Fastmarkets.
What is dysprosium used for?
Mainly in neodymium-iron-boron permanent magnets, where small additions improve heat resistance. Fastmarkets lists electric vehicles, wind turbines and defence systems among the uses. Magnet makers are reducing the amount per magnet.
How rare is dysprosium?
The USGS lists 5.2 parts per million in average crust. That is more common than many metals people think of as rare, but economic concentrations are uncommon, and heavy rare earths are less abundant than light ones.
Is dysprosium recycled?
A little. The USGS reports small quantities recovered from magnets in 2025 and government loans to two recyclers. Capacity is not yet large enough to change the supply picture.
Can anything replace dysprosium in magnets?
Partly. The USGS says substitutes are available for some applications but generally less effective, and light rare earths can replace heavy ones in several uses. Industry sources quoted by Fastmarkets say grain boundary diffusion lowers dysprosium per magnet, but it stays important for high-performance uses.
When will non-Chinese dysprosium supply grow?
In steps. Lynas is already separating dysprosium, Mountain Pass and Eneabba are in construction or commissioning, and Browns Range and Caldeira are not yet producing. Caldeira’s study target of 127 tonnes a year of dysprosium and terbium is about a third of the roughly 400 tonnes a year that Lynas puts outside-China demand at, and it would only start after financing, approvals and construction.
How do I find out if my licence area could host rare earths?
Start with geology: carbonatites, alkaline intrusions, deeply weathered granite and xenotime-bearing rocks are the settings the USGS lists. Satellite screening can help rank ground before sampling, and a quote request to Farmonaut covers that first step.
This page is for information only. It is not investment advice. Prices change quickly; confirm current assessments and the status of China’s export rules before any decision.
Farmonaut mining
Get a quote to screen your licence area from space
Send your boundary file and target mineral, including rare earth elements, and we return a satellite screening report in 5 to 20 business days.

Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026, rare earths (2026): pubs.usgs.gov
- USGS, Mineral Commodity Summaries 2026, rare earths (heavy) (2026): pubs.usgs.gov
- USGS, Fact Sheet 2014-3078, Rare earth elements: critical resources (2014): pubs.usgs.gov
- Natural Resources Canada, Rare earth elements facts: natural-resources.canada.ca
- Northern Minerals, investor presentation, ASX announcement of 23 July 2026: bulletin.webull.com
- Lynas Rare Earths, quarterly report to 31 March 2026 (ASX, 21 April 2026): announcements.asx.com.au
- Lynas Rare Earths, Appendix 4E and annual results (ASX, 26 August 2026): announcements.asx.com.au
- Lynas Rare Earths, acquisition of Meteoric Resources (ASX, 1 October 2026): announcements.asx.com.au
- Kalkine Media, Lynas June 2026 quarter: kalkinemedia.com
- Fastmarkets, US demand drives sharp increases in CIP global terbium, dysprosium prices (6 October 2026): fastmarkets.com
- The Oregon Group, Rare Earth prices surge as China keeps export restrictions (10 June 2026): theoregongroup.com
- Argus Media, Export controls split the heavy rare earths market (11 August 2026): argusmedia.com
- Pillsbury, China suspends export controls on certain critical minerals (13 November 2025): pillsburylaw.com
- Mining Technology via Yahoo Finance, China rare earth export pause nears expiry (27 April 2026): finance.yahoo.com
- ColoradoBiz, Energy Fuels completes acquisition of Australian Strategic Materials (31 August 2026): coloradobiz.com
- SMM, USA Rare Earth acquires Serra Verde (22 September 2026): news.metal.com
- SunSirs, dysprosium oxide price, Baotou Rare Earth Products Exchange (9 July 2026): sunsirs.com
- MP Materials, second quarter 2026 results (6 August 2026): mpmaterials.com
- Energy Fuels, White Mesa Mill: energyfuels.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Mining SARL
 SenGold Invest SAS
 Sania Corporation
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.











