

Evolution Mining · Business model
Is Evolution Mining B2B or B2C? Who Buys Its Gold
B2B. Evolution Mining sells gold doré, gold credits and copper concentrate to refiners, smelters, traders and one streaming company, and five single customers gave about 94% of its gross revenue in the year to 30 June 2026 (FY26 annual report).
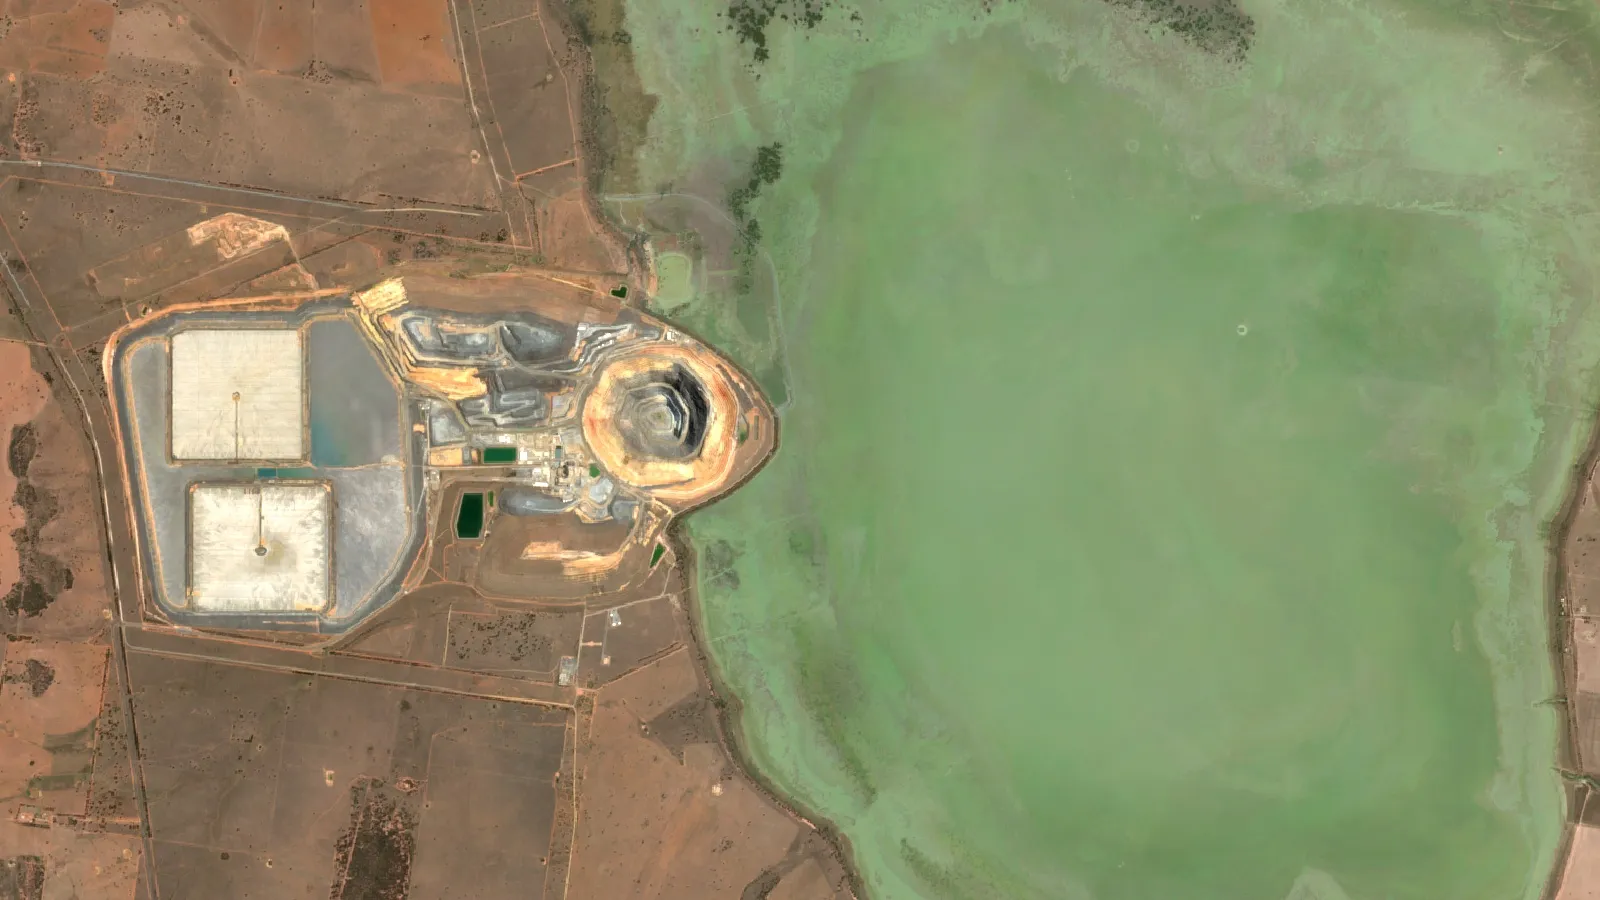
Key takeaways
- Evolution Mining has no consumer sales: five single external customers provided about A$5.27 billion of A$5.60 billion gross revenue in FY26 (annual report, August 2026).
- Gold is sold at spot; copper concentrate is priced provisionally and settled one to four months after shipment.
- FY26 output was 714,728 oz of gold and 65,636 t of copper at an AISC of A$1,717/oz, against an achieved gold price of A$6,023/oz.
- Statutory net profit hit a record A$1,475 million and the balance sheet moved to A$19 million net cash at 30 June 2026.
- FY27 guidance is 660,000-730,000 oz of gold at an AISC of A$1,795-1,995/oz (August 2026).
In this article
- Is Evolution Mining B2B or B2C? The short answer
- Who buys Evolution Mining's gold and copper
- How a sale works: from mine to refiner
- The six mines behind the sales
- How the money flows: price, cost and margin
- Evolution Mining compared with Newmont
- What the model means for licence owners, consultants and investors
- Guidance and what to check next
- Frequently asked questions
Evolution Mining is a B2B (business-to-business) company. It mines gold and copper in Australia and Canada and sells gold doré, gold credits and copper concentrate to a handful of refiners, smelters and metal traders. It has no shop and no consumer product. Its annual financial report for the year to 30 June 2026 shows that about 94% of gross revenue (A$5.27 billion of A$5.60 billion) came from just five single external customers, one for each main mine group.
That one fact settles the question, but it raises better ones: who those buyers are, how the price is set, why a miner with only a few customers can still earn record profits, and what the model means for smaller mine owners and investors. This page answers each with figures from the company’s own filings, three charts and a margin calculator you can run with your own prices.
Two terms first. B2B means the company sells to other businesses. B2C (business-to-consumer) means it sells to the public, the way a jeweller or a bullion dealer does. Evolution sits at the very start of the gold chain, well before any product reaches a consumer.
Is Evolution Mining B2B or B2C? The short answer
B2B, with no B2C channel at all. Four tests work for any mining company, and Evolution passes each one on the business side:
- Who signs the sales contract? At Evolution it is a refiner, smelter or trader. The annual report names each mine’s main buyer only as “a single external customer”, which is normal for commodity sales.
- Who sets the price? The market does. Gold is sold at spot (the live market price), and copper concentrate is priced against average monthly market prices after shipment. Evolution cannot set a retail price list.
- What is the product? Doré bars (an unrefined gold-silver alloy) and concentrate (crushed, upgraded ore). Neither is something a consumer can use.
- Is there a storefront? No. The website evolutionmining.com.au is an investor and corporate site with results, reserves and sustainability reports. You cannot buy metal on it.
People often search for “evolutionmining.com business model” after landing on that site and finding no plain explanation of who the customers are. The rest of this page fills that gap.
Who buys Evolution Mining’s gold and copper
The annual report for the year to 30 June 2026 (Evolution’s financial year 2026, or FY26) lists revenue by mine and flags every customer that buys a large share. The picture is a very concentrated customer base:
Chart
Evolution Mining gross revenue by buyer, FY26
A$ million, year to 30 June 2026; each named mine group sold mainly to one customer
| Mine group | What is sold | Gross revenue from one customer, FY26 | FY25 |
|---|---|---|---|
| Cowal and Mt Rawdon | Gold and silver | A$1,987.3 million | A$1,617.2 million |
| Ernest Henry | Copper, gold and silver in concentrate | A$1,022.0 million | A$1,030.6 million |
| Mungari | Gold and silver | A$847.9 million | A$313.6 million |
| Red Lake | Gold and silver | A$780.2 million | A$487.8 million |
| Northparkes | Copper, gold and silver in concentrate | A$628.6 million | A$530.6 million |
Those five buyers add up to about A$5,266 million, against gross revenue of A$5,599.7 million in FY26. The rest is mostly metal delivered under a streaming deal and smaller sales. A consumer brand would have millions of customers; Evolution, in effect, has five large ones plus a stream holder.
Who are these customers? The company does not name them in the report. For gold, the usual buyers are refiners on the LBMA Good Delivery list (the London Bullion Market Association’s list of refiners whose bars can trade on the global wholesale market) and the banks that hold metal accounts with them. For copper concentrate, buyers are smelters and metal traders. That is the standard pattern for gold miners: Newmont’s own annual report on Form 10-K says its doré goes to refiners and the refined gold credited to its account is typically sold to banks or refiners.
Why so few customers is not a weakness here
For most businesses, five customers bringing in 94% of sales would be a serious risk. For a gold miner it is much less so, because gold is a global commodity with a deep market. If one refiner stopped buying, the metal could be sold to another at close to the same spot price. The real risk sits elsewhere: in the gold price itself, in costs, and in each mine’s output. Copper concentrate is a little different, since smelter terms (treatment and refining charges) are negotiated, and Evolution deducted A$41.0 million of concentrate treatment, refining and freight costs from revenue in FY26, down from A$74.5 million in FY25.
How a sale works: from mine to refiner
Evolution’s accounting notes describe the sale steps in plain terms. Revenue is booked when the buyer takes control of the metal, and the timing differs by product:
- Gold doré: recorded as sold when the doré leaves the gold room at the mine for the buyer, or when gold credits are moved into the customer’s metal account.
- Concentrate from Red Lake and Northparkes: generally recorded when it is loaded onto the ship. (Red Lake is a gold mine, so its concentrate carries gold, not copper.)
- Ernest Henry concentrate: recorded when the customer takes control of it.
- Provisional pricing: concentrate is invoiced at a provisional price, then settled against average market prices in a later “quotation period”, usually one to four months after shipment.
Shipping of some concentrate is treated as a separate service and booked over time. In FY26 only A$15.8 million of the A$5,558.8 million net revenue was recognised over time; the rest was recognised at a single point, the moment of delivery.
The streaming deal: a different kind of B2B buyer
One buyer is not a refiner at all. At Northparkes, Evolution delivers part of its gold and silver to Triple Flag, a streaming company. A stream is a contract where a financier pays a large sum up front in exchange for the right to buy a share of future metal at a low fixed price. Under the deal, Triple Flag pays cash equal to 10% of the spot price for each ounce delivered. In FY26 Evolution delivered 17,151 ounces of gold and 245,776 ounces of silver under the stream, and it agreed amended terms that include a A$120 million payment to Evolution in December 2026, according to the FY26 results announcement. Triple Flag’s own third-quarter update calls Northparkes its flagship asset. This is still B2B: a finance company buying metal from a mining company.
▶ How gold moves from rock to refined bar, step by step · 5:27
The six mines behind the sales
Evolution runs six operations: five wholly owned mines (Cowal in New South Wales, Ernest Henry and Mt Rawdon in Queensland, Mungari in Western Australia and Red Lake in Ontario, Canada) and an 80% share of Northparkes in New South Wales. Group output in FY26 was 714,728 ounces of gold, 65,636 tonnes of copper and 765,694 ounces of silver.
Chart
Gold produced by mine, FY26
Thousand ounces, year to 30 June 2026 (Northparkes at 80% share)
Production is uneven across the portfolio. Cowal alone made 297,029 ounces, about 42% of the group’s gold. The expanded 4.2 million-tonne-a-year mill at Mungari lifted that mine to a record 186,115 ounces. Ernest Henry lost about 12,000 ounces of gold and 8,000 tonnes of copper after around 300 mm of rain fell in 24 hours in late December 2025. Mt Rawdon is in its last phase, processing low-grade stockpiles that the company scheduled to finish in the September 2026 quarter.
For context, the USGS Mineral Commodity Summaries 2026 estimate Australia’s gold mine output at about 280 tonnes in 2025 (roughly 9 million ounces) and Canada’s at about 200 tonnes. Evolution’s FY26 gold is about 22 tonnes, so it is a mid-sized producer on a world scale. For the wider field, see our list of the top 20 gold mining companies and our map of gold mines in New South Wales, home to Cowal and Northparkes.
Copper’s role in a gold company
Ernest Henry and Northparkes are copper-gold mines. Their copper is not just a side product: copper sales were A$1,209.2 million in FY26, about 22% of gross revenue. That copper also lowers the reported cost of gold, because copper sales are counted as a credit against costs. Both mines reported negative all-in sustaining costs per ounce of gold in FY26 (minus A$2,975 at Ernest Henry and minus A$8,314 at Northparkes), meaning copper and by-product revenue more than covered the sustaining cost of producing their gold. For a closer look at copper miners, see our guide to the largest copper producers.
How the money flows: price, cost and margin
Because Evolution cannot set its own price, profit comes down to the gap between the market price it achieves and what each ounce costs. The industry measure for that cost is AISC (all-in sustaining cost): the cash cost of mining and processing plus royalties, sustaining capital and corporate overheads, per ounce sold. The World Gold Council guidance note sets out how miners should calculate it, including how to credit by-product metals such as copper and silver.
Chart
Price rose faster than cost
A$ per ounce of gold, FY25 vs FY26
In FY26 Evolution’s figures were:
- Achieved gold price: A$6,023 per ounce, up 40% from A$4,300 in FY25.
- Achieved copper price: A$18,051 per tonne, up 25% from A$14,470.
- AISC: A$1,717 per ounce, up 9% from A$1,572.
- All-in cost (AISC plus growth spending): A$3,048 per ounce, against A$2,856 in FY25.
The price rose much faster than the cost, so the margin widened. Statutory net profit reached a record A$1,475 million (up 59%), underlying EBITDA (earnings before interest, tax, depreciation and amortisation) reached A$3,171 million with a 57% margin, and group cash flow was a record A$1,389 million. The balance sheet moved from net debt of A$849 million at 30 June 2025 to a small net cash position of A$19 million a year later.
The company also moved to an unhedged position at the end of FY26 after the last delivery into its gold hedge book. In FY26, 50,000 ounces were still delivered into hedges at an average A$3,234 per ounce, well below the spot sales average. From FY27 all gold is exposed to the spot price, which raises both the upside and the risk.
Where the cash goes
The business model has a clear order for using cash: sustaining capital to keep mines running (A$239.4 million in FY26), major projects that extend mine life (A$849.8 million, including the Northparkes E22 block cave, the Mungari mill expansion, the Cowal open pit continuation and the Bert development at Ernest Henry), then dividends. In August 2026 the board raised the target dividend payout to about 60% of group cash flow, from about 50%, and declared a full-year dividend of 41 cents a share, about A$833 million in total. For more on what separates high-margin miners from the rest, see our guide to mining profitability.
Calculator
What is the AISC margin at your gold price?
Enter ounces sold, a gold price and an AISC to see the margin per ounce and in total.
- Margin per ounce (A$): $4,283
- Margin as share of price: 71.4%
- Revenue at that price (A$): $4,200,000,000
Default AISC is Evolution Mining’s FY26 figure (A$1,717/oz, ASX, August 2026); ounces are a round example near its FY26 sales of 709,541 oz. The gold price is an input: example, use today’s price. AISC margin is before tax, interest and growth capital.
Evolution Mining compared with Newmont
Readers in the United States often compare Evolution with Newmont, the Denver-based, NYSE-listed producer. The model is the same: both are B2B miners selling doré and concentrate into commodity markets. The scale is not. Newmont’s full-year 2025 results reported 5.9 million attributable gold ounces, plus 28 million ounces of silver and 135,000 tonnes of copper, at a gold by-product AISC of US$1,358 per ounce.
| Measure | Evolution Mining (FY26, year to 30 June 2026) | Newmont (calendar 2025) |
|---|---|---|
| Listing | ASX: EVN | NYSE: NEM |
| Gold produced | 714,728 oz | 5.9 million oz attributable |
| Copper produced | 65,636 t | 135,000 t |
| AISC | A$1,717/oz | US$1,358/oz (by-product) |
| Main buyers | Refiners, smelters, traders, one stream holder | Refiners, banks and concentrate buyers |
The two AISC figures are in different currencies and cover different 12-month periods, so they should not be compared directly. The useful comparison is the structure: the same B2B sales route, the same cost metric and the same need to replace ounces as mines run down.
What the model means for licence owners, consultants and investors
Evolution’s model is a template for how value moves in gold and copper mining. A few practical points follow from it:
- Licence and claim owners: your buyer is rarely a consumer. Small producers sell doré or concentrate to a refiner, a trader or an aggregator, at a market-linked price minus charges. Mid-tier producers like Evolution also buy projects and companies: in July 2026 it agreed to acquire Carnaby Resources for about A$213 million by scheme of arrangement to add copper near Ernest Henry, and in August 2026 it took a 9.9% stake in Arizona Gold & Silver, an explorer in Arizona’s Oatman district.
- Consultants: the numbers buyers look at are grade, recovery, AISC, sustaining capital and mine life. A project pitch that cannot show these will struggle, whatever the geology.
- Investors: the share is a bet on metal price minus cost, times ounces, plus how well capital is spent. Customer concentration matters far less than for a consumer business. Watch AISC guidance, reserve replacement and hedging policy.
Before money is spent on drilling, many explorers now screen ground with satellite data to rank targets. Farmonaut offers satellite-based mineral detection for licence areas, which gives early exploration targets ahead of any drilling or resource estimate.
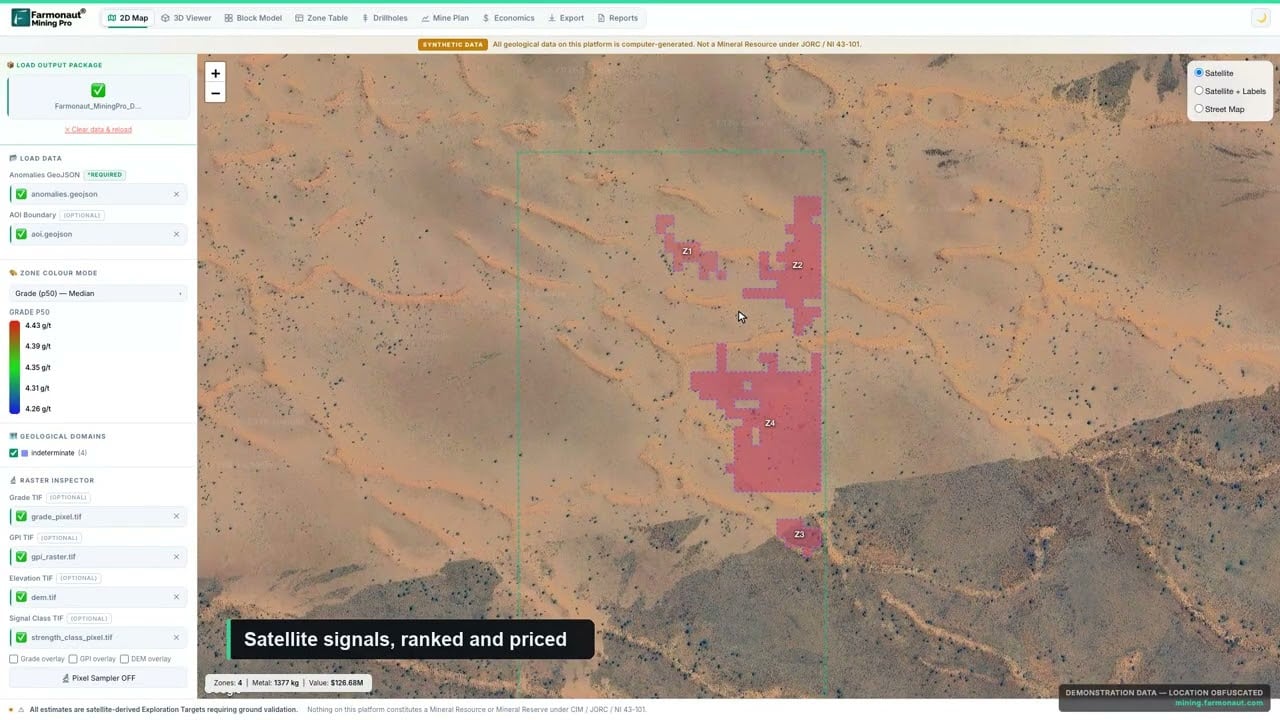
▶ How satellite screening turns a licence boundary into exploration targets · 4:56
Guidance and what to check next
Evolution’s FY27 guidance, published with the August 2026 results, is 660,000 to 730,000 ounces of gold and 63,000 to 70,000 tonnes of copper at an AISC of A$1,795 to A$1,995 per ounce. That guidance assumes a gold price of A$5,700 per ounce and a copper price of A$18,000 per tonne.
The company reports quarterly to the ASX, with half-year results each February and full-year results each August. Things worth checking in each report:
- Achieved gold and copper prices against AISC: is the margin per ounce holding?
- Cowal’s output and cost, since it carries about 42% of group gold.
- Recovery at Ernest Henry after the flood, and progress on the Bert project.
- Northparkes E22 block cave and mill expansion timing, which drive future copper.
- Whether the Carnaby deal closed and how the company treats hedging now that it is unhedged.
Every figure on this page comes from the company’s filings for the year to 30 June 2026 unless stated. Check the ASX announcements page for anything newer. For a quote on mapping your own licence area, use our mining enquiry form.
Frequently asked questions
Is Evolution Mining B2B or B2C?
B2B. It sells gold doré, gold credits and copper concentrate to refiners, smelters, traders and one streaming company. It sells nothing to consumers.
What is Evolution Mining’s business model?
It owns and runs gold and copper mines, sells the metal at market-linked prices, keeps costs per ounce low, reinvests in mine life and pays out about 60% of group cash flow as dividends under the policy set in August 2026.
Who are Evolution Mining’s customers?
The annual report does not name them. It says five single external customers, one per main mine group, provided about A$5.27 billion of FY26 gross revenue. Gold buyers in this market are usually accredited refiners and bullion banks; copper concentrate goes to smelters and traders.
Can I buy gold directly from Evolution Mining?
No. The company has no retail sales. Gold reaches the public only after refining, through dealers, mints and jewellers.
What does evolutionmining.com.au sell?
Nothing. It is the company’s corporate and investor website, with results, reserve statements and sustainability reports.
How many mines does Evolution Mining operate?
Six: Cowal, Ernest Henry, Mt Rawdon, Mungari, Red Lake and an 80% share of Northparkes. Mt Rawdon was processing its last low-grade stockpiles in the September 2026 quarter.
How much gold did Evolution Mining produce last financial year?
714,728 ounces of gold and 65,636 tonnes of copper in the year to 30 June 2026, at an AISC of A$1,717 per ounce.
Why are copper mines part of a gold company?
Ernest Henry and Northparkes produce both metals. Copper brought in A$1,209.2 million in FY26 and lowers the reported cost of each gold ounce, because copper sales are credited against costs.
Is Evolution Mining listed in the United States?
Its primary listing is on the Australian Securities Exchange under the code EVN. Check with your broker for any other trading lines.
Does Evolution Mining hedge its gold?
It delivered its last gold hedges in FY26 and moved to an unhedged position at 30 June 2026, so its gold is now sold at spot.
More from Farmonaut: contact us, critical minerals powering sustainable agriculture in 2025.
This page is for information only. It is not investment advice.
Farmonaut mining
Map your own project area from space
Send us your licence boundary for a quote on a satellite screen of exploration targets before you drill.

Mining Pro sample view, synthetic data
Keep reading
Sources
- Evolution Mining, Annual Financial Report for the year ended 30 June 2026 (ASX, August 2026): announcements.asx.com.au
- Evolution Mining, FY26 Full Year Financial Results and Final Dividend (ASX, 19 August 2026): announcements.asx.com.au
- Evolution Mining, corporate website: evolutionmining.com.au
- World Gold Council, Guidance note on non-GAAP metrics: AISC and AIC: gold.org
- World Gold Council, Gold all-in sustaining costs: gold.org
- LBMA, Good Delivery List: gold refiners: lbma.org.uk
- USGS, Mineral Commodity Summaries 2026: Gold: pubs.usgs.gov
- Newmont, fourth quarter and full year 2025 results (February 2026): seekingalpha.com
- Newmont, Annual Report on Form 10-K for 2025: s24.q4cdn.com
- Triple Flag, Q3 2026 revenue and Ravenswood deliveries (October 2026): bnnbloomberg.ca
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Southbridge & Wess PDC Ltd
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited

 Client · Oregon, USA · Gold










