

Lithium · Australia ranking
Spodumene Producers in Australia: 9 Mines Ranked
Greenbushes led Australian spodumene output in the year to June 2026 at 1.41 million tonnes, ahead of Pilgangoora (879.5 kt), Mt Holland (about 418 kt, our estimate) and Kathleen Valley (392 kdmt). This page ranks nine mines on company-reported figures from the June 2026 quarter.
Key takeaways
- Greenbushes produced 1,410 kt of spodumene in FY26 (100% basis), IGO’s report to 30 June 2026 shows.
- PLS Group (formerly Pilbara Minerals) made 879.5 kt at Pilgangoora and guides FY27 to 1,030-1,100 kt.
- Reported FY26 unit costs run from A$415 per tonne at Greenbushes to A$987 per tonne sold at Kathleen Valley; the definitions differ.
- Bald Hill and Finniss are restarting; Mt Cattlin is still on care and maintenance (Rio Tinto, 14 October 2026).
- Australia mined 92,000 t of lithium in 2025, about a third of the world total (USGS, 2026).
In this article
- How we chose and ranked the nine mines
- Terms used in this list
- Spodumene producers in Australia compared
- Ranked: Australia's nine hard-rock lithium mines
- How spodumene ore becomes concentrate
- Which mines operate at the lowest cost per tonne
- What the producers guide for FY27
- Australia's share of world hard-rock lithium supply
- How satellites help find lithium targets
- Related reading on hard-rock lithium
- Margin per tonne of spodumene concentrate
- Frequently asked questions
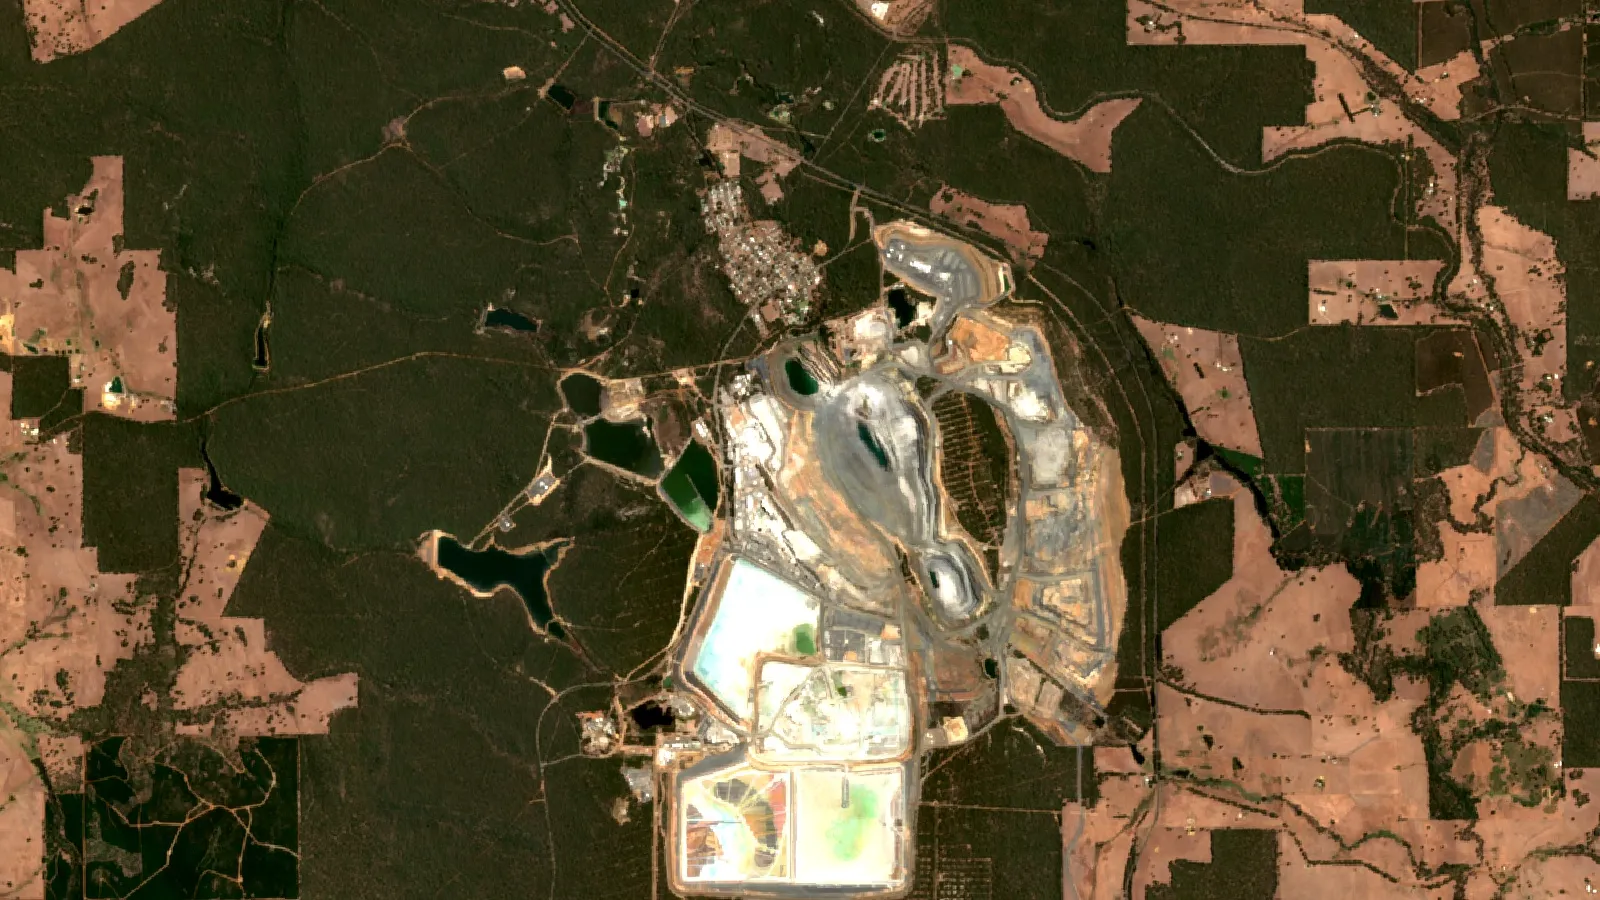
Nine Australian mines matter for anyone tracking hard-rock lithium supply: six are producing spodumene concentrate, two are restarting after a price-driven shutdown and one is idle. By reported output for the year to 30 June 2026, Greenbushes leads with 1.41 million tonnes, followed by Pilgangoora with 879.5 thousand tonnes, Mt Holland with about 418 thousand (our estimate from Wesfarmers’ share), Kathleen Valley with 392 thousand and Wodgina and Mt Marion with 317 and 242 thousand. This page ranks the nine, explains how the ranking was built and gives each mine a plain “best for”, pros, cons and 2026 status.
Spodumene is the lithium-bearing mineral found in pegmatite, a coarse-grained igneous rock. Miners crush the rock and concentrate it into a powder-like product that is shipped to chemical plants. Australia is the largest source: the USGS Mineral Commodity Summaries 2026 gives Australian mine production in 2025 as 92,000 tonnes of contained lithium, about a third of the world total of roughly 290,000 tonnes. If you want the geology of pegmatite and brine deposits first, read our guide to lithium deposits; for equipment and process flow, see the page on Australian hard-rock extraction methods.
How we chose and ranked the nine mines
The list is built for mining business owners, consultants and investors who need to know who actually ships spodumene from Australia, at what scale and in what condition. We used four rules.
- Hard-rock spodumene only. Brine projects, lithium chemical plants and exploration-stage projects are left out. Refineries are mentioned only where they change a mine’s economics.
- Company reports only. Every volume, cost and status line comes from a company’s own filing for the June 2026 quarter, published 28 to 30 July 2026, or from a dated company announcement. Where a figure comes from a news report, we say so.
- Ranked by reported output for the year to 30 June 2026 (FY26). The mines report on different bases, so read the numbers as reported, not as a perfect like-for-like. Greenbushes is a 100% figure for production; Wodgina and Mt Marion are project-basis sales as reported by Mineral Resources; Kathleen Valley is production in dry metric tonnes (dmt) at roughly 5% lithium oxide. Mt Holland is Wesfarmers’ reported 50% share (209 kt, at grade) doubled to about 418 kt for the whole mine, which is our arithmetic, so its rank is the least certain.
- Status uses one vocabulary: operating, ramping up, restarting, or care and maintenance. Care and maintenance means the mine is switched off but kept in a condition to restart.
The ranking measures size and reported condition. It does not say which company is the better business, and nothing here is a recommendation to buy or sell any share.
Terms used in this list
- Spodumene concentrate: the saleable product, made by crushing and separating ore. It is not yet battery chemical.
- SC6 and SC5.2: concentrate grades of 6% and 5.2% lithium oxide (Li2O). Companies convert volumes to SC6 to compare. A lower-grade tonne sells for less.
- dmt: dry metric tonnes, meaning moisture is excluded.
- FOB and CIF: FOB is the price or cost at the Australian port, with the cargo loaded on the ship; CIF adds freight and insurance to the buyer’s port.
- Recovery: the share of the lithium in the ore that ends up in concentrate. Low recovery means more rock for each saleable tonne.
- FY26: the Australian financial year from 1 July 2025 to 30 June 2026.
Spodumene producers in Australia compared
| Rank | Mine (state) | Operator and owners | Status, 30 Jul 2026 | Latest reported output |
|---|---|---|---|---|
| 1 | Greenbushes (WA) | Talison, owned by Windfield (Tianqi-IGO venture 51%, Albemarle 49%) | Operating, fire at one plant | 1,410 kt FY26 (100%) |
| 2 | Pilgangoora (WA) | PLS Group (ASX: PLS) | Operating, second plant restarting | 879.5 kt FY26 |
| 3 | Mt Holland (WA) | Covalent Lithium: Wesfarmers 50% / SQM 50% | Operating above nameplate | About 418 kt FY26 at grade (our doubling of Wesfarmers’ 209 kt share) |
| 4 | Kathleen Valley (WA) | Liontown (ASX: LTR) | Ramping up underground | 392 kdmt FY26 |
| 5 | Wodgina (WA) | MinRes 50% / Albemarle 50% | Operating, three trains | 317 kdmt SC6 sold FY26 (project basis) |
| 6 | Mt Marion (WA) | MinRes operates; 50% Ganfeng | Operating, expansion approved | 242 kdmt SC6 sold FY26 (project basis) |
| 7 | Bald Hill (WA) | MinRes 100% | Restarting | First concentrate June 2026 |
| 8 | Finniss (NT) | Core Lithium (ASX: CXO) | Restarting | First new shipment due Dec quarter 2026 |
| 9 | Mt Cattlin (WA) | Rio Tinto 100% | Care and maintenance (Rio Tinto, 14 Oct 2026) | None reported |
Chart
Reported FY26 spodumene volume by mine
Thousand tonnes, year to 30 June 2026; mixed bases (see caption)
The chart below plots the five mines with a published FY26 volume. The bars do not share one basis, so use them for scale, not for exact differences.
Ranked: Australia’s nine hard-rock lithium mines
1. Greenbushes: the largest hard-rock lithium mine
Best for: readers who want the biggest, lowest-cost source of spodumene in Australia.
Greenbushes is in the south-west of Western Australia, about 250 km south of Perth, and is described by Mining.com as the world’s biggest hard-rock lithium mine. Talison operates it. IGO’s June 2026 quarterly report shows production of 1,410 kt in FY26 (100% basis) and 387 kt in the June quarter, against 351 kt in the March quarter. The cash cost was A$415 per tonne for the year, the realised price averaged US$1,443 per tonne and the mine earned a 73% EBITDA margin (80% in the June quarter).
Ownership runs through Windfield Holdings, which owns Talison. IGO’s report says Windfield is 51% held by Tianqi Lithium Energy Australia and 49% by Albemarle. IGO holds 49% of that Tianqi venture and reports a 24.99% indirect interest in Greenbushes. Albemarle says the site has four concentrate plants with a capacity of 1.5 million tonnes a year.
- Pros: the largest volume, the lowest reported unit cost in this list, and an 80% margin in the June 2026 quarter.
- Cons: a fire at Chemical Grade Plant 3 (CGP3) stopped that plant for about seven weeks from June; and recovery was lower than planned in the quarter.
2026 status: operating. IGO said on 28 July 2026 that CGP3 production was expected to restart in the coming days. FY27 guidance is 1,550 to 1,750 kt at a cash cost of A$380 to 440 per tonne.
2. Pilgangoora: the second-largest producer, run by PLS Group
Best for: readers who want a stand-alone lithium producer with a capacity expansion under study.
Pilgangoora is in the Pilbara of Western Australia and is run by PLS Group Limited (ASX: PLS), the company formerly known as Pilbara Minerals. Its June 2026 quarterly report records FY26 production of 879.5 kt, up 17% on FY25’s 754.6 kt, with lithium recovery of 76.8% in the June quarter. The FOB unit cost (excluding freight and royalties) was A$569 per tonne for the year. The realised price rose from US$1,488 per tonne for FY26 to US$2,107 per tonne in the June quarter on a CIF China basis at about SC5.2.
The company restarted its Ngungaju plant on 1 July 2026 and expects target capacity within the first four months of FY27. A feasibility study for a larger P2000 expansion continues, with a possible final investment decision (FID) in the December 2026 quarter and about A$175 million of pre-FID spending approved. PLS also reports the Colina project in Brazil.
- Pros: A$2,290 million of cash at 30 June 2026, the second-largest output in Australia and a plant that has already restarted.
- Cons: the unit cost is guided up to A$575 to 625 per tonne in FY27 because the restarted plant costs more to run; the September 2026 quarter output is expected to be lower while the plant ramps up; P2000 is not yet approved.
2026 status: operating, with a second plant ramping up. FY27 guidance is 1,030 to 1,100 kt.
3. Mt Holland: the integrated mine and refinery
Best for: readers who want a mine tied directly to a hydroxide refinery.
Mt Holland is operated by Covalent Lithium, a 50/50 venture of Wesfarmers and the Chilean company SQM. Wesfarmers’ FY26 results report spodumene production of 209 kt for FY26 (145 kt in FY25) in the table for its chemicals and energy division, at grade, and say production was above guidance and above nameplate. Wesfarmers’ own outlook describes a 50% share of about 190 kt against a 100% nameplate of about 380 kt, so 209 kt is Wesfarmers’ share and the mine total is about 418 kt on our doubling (an estimate, not a company-reported figure, and at grade rather than converted to SC6). Wesfarmers’ share of lithium earnings was A$40 million, against a loss of A$59 million the year before. In July 2026 the partners approved an expansion that doubles nameplate capacity to about 760 kt a year, with a second concentrator due to start construction in the second half of calendar 2027 and first expanded output in 2030, according to International Mining.
- Pros: produced above nameplate in FY26 and has an approved expansion; the Kwinana refinery gives a route to lithium hydroxide.
- Cons: Wesfarmers says the refinery ramp-up was slowed by odour issues, and conversion of concentrate to hydroxide is expected to stay below the design rate through FY27.
2026 status: operating. Wesfarmers expects production in line with nameplate in FY27 and plans to sell about half of its share as concentrate.
4. Kathleen Valley: the underground ramp-up
Best for: readers following a single-asset mine that is moving from open pit to underground.
Liontown Resources (ASX: LTR) owns Kathleen Valley in Western Australia. Its June 2026 quarterly report shows 103,111 dmt of concentrate produced in the quarter and 391,992 dmt in FY26, with 108,489 dmt sold at an average of 5.0% Li2O. Lithium recovery averaged about 63% in the quarter, and about 70% when the plant was fed clean underground ore. Cash was A$561 million. The mine also sold tantalite, a tantalum by-product, with FY26 production of 925 dmt.
- Pros: strong cash build, a record 3,316 metres of underground development in the quarter and a by-product credit.
- Cons: the reported FY26 unit operating cost of A$987 per tonne sold (FOB) is the highest of the producers with published figures, recovery is below the other large plants, and the target of 2.8 million tonnes a year of ore mined is not due until the end of FY27.
2026 status: ramping up. FY27 guidance is 390 to 440 SC6 kdmt of concentrate at A$1,050 to 1,250 per tonne FOB. An expansion decision was due around the end of September 2026; we did not find the outcome in the sources we opened.
5. Wodgina: three trains, 750 kt of nameplate
Best for: readers who want to watch capacity that is still being filled.
Wodgina is in the Pilbara, 1,525 km north of Perth, and is a joint venture between MinRes (50%) and Albemarle (50%). Albemarle gives a nameplate of 750,000 dry tonnes of SC6 a year across three processing trains. In MinRes’s June 2026 quarterly report, FY26 sales were 317 kdmt SC6 against upgraded guidance of 270 to 290 kdmt, at an FOB cost of A$738 per tonne SC6. June-quarter production was 94 kdmt and the realised price was US$2,450 per tonne CIF.
- Pros: a low unit cost in this group, a large resource and a partner with a chemicals business.
- Cons: sales are well below the 750 kt nameplate, and recovery fell to 68% as the plant moved fully onto Stage 3 ore.
2026 status: operating. All three trains run from the first quarter of FY27, and pre-stripping of Stage 4 starts in that quarter.
6. Mt Marion: expansion with a new flotation plant
Best for: readers who want a mature mine moving underground.
Mt Marion is about 70 km south of Kalgoorlie and 590 km east of Perth. MinRes operates it under a 50-50 joint venture with Ganfeng Lithium. FY26 sales were 242 kdmt SC6 (upgraded guidance 210 to 230 kdmt) at A$847 per tonne FOB, and June-quarter production was 82 kdmt at a recovery of 59%. In May 2026 the venture approved A$490 million (100% basis) over FY27 and FY28 for a flotation plant and underground mining, with Macmahon as the mining contractor.
- Pros: record sales, a funded expansion and ore sorting that can treat lower-grade stockpiles.
- Cons: recovery of 59% is the lowest in this list, unit cost is the second highest, and the underground build adds execution risk.
2026 status: operating, with early works under way.
7. Bald Hill: a restart from care and maintenance
Best for: readers tracking how fast idled capacity returns.
MinRes put Bald Hill, 50 km south-east of Kambalda, on care and maintenance in November 2024 and announced the restart on 19 May 2026. It owns 100% of the mine, which has a capacity of about 165,000 dmt a year of 5.1% concentrate, equal to 140,000 dmt of SC6, and a resource of 58.1 million tonnes at 0.9% Li2O.
- Pros: a quick restart using existing inventory and equipment, and about 370 jobs.
- Cons: still small, with no full year of output; MinRes is studying plant expansion options.
2026 status: restarting. First concentrate was made in June 2026, the first shipment left in July and full capacity is expected in the December 2026 quarter.
8. Finniss: a restart in the Northern Territory
Best for: readers who want a small, cash-constrained restart.
Core Lithium (ASX: CXO) took an FID on the Finniss restart on 18 March 2026. In its June 2026 quarterly report, mining had started at the Grants open pit under contractor NRW, underground decline work had begun at BP33, and about 45 kt of lithium fines from the old stockpile were sold to Glencore. Cash was A$181.8 million. The Grants pit design holds about 784 kt of ore, expected to give about 134 kt of SC5 product in total.
- Pros: a stockpile sale brings early cash; the product ships through Darwin Port.
- Cons: Grants is small, so the longer-term plan rests on BP33; the restart is recent, so early ramp-up risk remains.
2026 status: restarting. Ore is processed in the September quarter and the first shipment of newly produced concentrate is targeted for the December 2026 quarter.
9. Mt Cattlin: idle, owned by Rio Tinto
Best for: readers who want to know which mine is still switched off.
Mt Cattlin, near Ravensthorpe in Western Australia, was held by Arcadium Lithium before Rio Tinto bought that company in March 2025. Rio Tinto’s December 2025 resource statement says the mine is 100% Rio Tinto and was placed on care and maintenance on 1 July 2025 because of market conditions, with underground mining studies under way. Rio Tinto’s third-quarter 2026 operations review (14 October 2026) still describes it as in care and maintenance and dates the shutdown to the end of March 2025 for production purposes, so the exact date differs between Rio’s documents. Its resource, exclusive of reserves, is 11.3 million tonnes at 1.35% Li2O.
- Pros: the plant and site are kept ready to restart, and an underground option is being studied.
- Cons: no restart decision appears in the sources we opened, and it adds nothing to supply today.
2026 status: care and maintenance, per Rio Tinto’s operations review of 14 October 2026; no restart is announced there.
How spodumene ore becomes concentrate
The mines in this list share a basic flow, and the differences explain much of the recovery and cost gap. Ore is mined from open pit or, increasingly, underground; Kathleen Valley, Mt Marion and Finniss (at BP33) are all building underground mines. The rock is crushed, and ore sorters can reject barren rock before the plant: PLS credits better ore sorter performance for its latest recovery gain, Mt Marion uses sorting on lower-grade stockpiles and Mt Holland’s expansion includes a sorting facility for stockpiled material. A dense media separation (DMS) circuit then floats the heavy spodumene apart from lighter rock, and flotation recovers the finer particles. Mt Marion’s A$490 million plan adds a flotation plant (recovery was 59% in the June 2026 quarter).
Infographic
From pit to concentrate in 5 steps
- 1MineOpen pit or underground mining of pegmatite ore.
- 2Crush and sortCrushing, then ore sorters reject barren rock.
- 3Dense mediaA DMS circuit separates heavy spodumene from lighter rock.
- 4FlotationFlotation recovers finer spodumene.
- 5ShipConcentrate goes by port to a converter, such as Kwinana.
The concentrate is not yet battery material. It goes to a converter such as the Kwinana hydroxide refinery that IGO and Tianqi own a share of, or to plants overseas. Kwinana produced 897 t of lithium hydroxide in the June 2026 quarter, down from 3,047 t in the March quarter because of a planned shutdown, IGO reports. These steps are why a tonne of ore at 1.4% lithium oxide, as at Kathleen Valley’s underground, ends up as a small share of a tonne of concentrate. Several of the technologies named in older write-ups, such as waterless flotation and direct extraction from ore, are not described in any of the June 2026 company reports we read, so we do not list them as deployed.
Which mines operate at the lowest cost per tonne
Cost is where the list separates. Greenbushes reports a cash cost of A$415 per tonne; PLS reports A$569 FOB before freight and royalties; Wodgina A$738 and Mt Marion A$847 per tonne of SC6; and Liontown A$987 per tonne sold. The definitions differ, so the chart is a guide to order, not a precise league table.
Chart
Reported FY26 unit cost per tonne
A$ per tonne; definitions differ by company
That gap matters when prices move. Trading Economics showed lithium carbonate in China at CNY 104,400 per tonne on 15 October 2026, down 21% over the month but 43% above a year earlier. Mining.com reported on 22 July 2026 that the Guangzhou futures contract had given back nearly 30% from its May high as restarts raised expectations of oversupply in 2027. Higher-cost mines lose margin first when prices fall, which is why Bald Hill went onto care and maintenance in 2024 and was restarted only after the rally.
What the producers guide for FY27
Quarter by quarter, the picture was mixed in mid-2026. Greenbushes and Kathleen Valley produced more in the June quarter than in the March quarter, while Pilgangoora produced less after an exceptionally strong March quarter.
Chart
Quarterly production, March vs June 2026
Thousand tonnes of concentrate as reported (Kathleen Valley in dmt)
For the full year to June 2027, Greenbushes guides to 1,550 to 1,750 kt, Pilgangoora to 1,030 to 1,100 kt and Liontown to 390 to 440 SC6 kdmt. Mineral Resources gave no numeric lithium guidance in the report we read, but said all three Wodgina trains will run, Bald Hill will reach full capacity in the December quarter and Mt Marion will treat lower-grade stockpiles. If the guidance holds, Pilgangoora’s output would rise by roughly 17 to 25% and Greenbushes’s by roughly 10 to 24% on FY26. These are company targets, not forecasts from us.
Australia’s share of world hard-rock lithium supply
The USGS gives 2025 mine production as 92,000 tonnes of lithium content in Australia, 62,000 in China, 56,000 in Chile and 28,000 in Zimbabwe. Chile’s output comes from brine, not hard rock. Australian reserves are 8.4 million tonnes of lithium out of 37 million worldwide. The same USGS summary says spodumene prices (6% Li2O, FOB Australia) rose from about US$800 a tonne in January 2025 to about US$970 a tonne in November, well below the US$2,000-plus realised prices that producers reported for the June 2026 quarter.
Chart
Lithium mine production by country, 2025
Tonnes of contained lithium; Chile is brine, Australia is mainly hard rock
Geoscience Australia’s 2026 preliminary resource tables note that its lithium production figures are estimated from spodumene output assuming 6% lithium oxide, so national totals depend on that grade assumption. The USGS also says world mine production outside the United States grew 31% in 2025. Zimbabwe, which supplied about a tenth of world output, plans a ban on lithium concentrate exports from 1 January 2027, according to Mining.com. That ban could redirect buyers toward Australian supply.
How satellites help find lithium targets
Every mine above began as a pegmatite target. Satellite data can help screen a licence for the iron-oxide, clay and structural clues that guide where to sample first, though only drilling proves lithium grade. Farmonaut offers satellite-based mineral screening for licence areas; the results are exploration targets and not a resource estimate.
▶ Explains remote sensing for mining in three minutes. · 2:01
Our own video on a satellite lithium exploration case study in Nigeria shows how that screening step is run on a real area. Operating sites that need to track emissions or vehicles can also look at Farmonaut’s carbon footprinting and fleet management tools.

▶ A satellite-based lithium exploration case study in Nigeria. · 10:49
Related reading on hard-rock lithium
For neighbouring topics, see our pages on spodumene deposits and exploration targets in Australia, and see where lithium is mined worldwide.
Margin per tonne of spodumene concentrate
The calculator below turns a sale price and a cost into a margin per tonne and a break-even price. Type your own numbers: it ships with round examples, not a quote. Use the SC6 price and cost on the same basis, and check the royalty rate that applies to your tenement with the regulator.
Calculator
What margin does a tonne of concentrate leave?
Enter your own price, exchange rate and cost.
- Revenue (A$): $230,769,231
- Royalty (A$): $11,538,462
- Operating cost (A$): $75,000,000
- Margin (A$): $144,230,769
- Break-even price (US$/t): 513 US$/t
Example values only, not a quote or forecast. Price is an input: example, use today’s price (US$ per tonne of concentrate, same grade basis as your cost). Revenue = tonnes x price / exchange rate. The royalty is an input; confirm the rate with the state regulator. Excludes freight, sustaining capital, tax and financing.
Frequently asked questions
Who are the largest spodumene producers in Australia?
By reported output for the year to 30 June 2026, Greenbushes led with 1,410 kt (100% basis), then Pilgangoora with 879.5 kt, Mt Holland with about 418 kt (our doubling of Wesfarmers’ 209 kt share, at grade) and Kathleen Valley with 392 kdmt. Wodgina and Mt Marion sold 317 and 242 kdmt of SC6 respectively on a project basis.
Which companies own Greenbushes?
Talison Lithium operates it and is owned by Windfield Holdings. Windfield is 51% held by Tianqi Lithium Energy Australia and 49% by Albemarle, and IGO owns 49% of the Tianqi venture, according to IGO’s June 2026 report.
Is Pilbara Minerals still listed?
The company now trades as PLS Group Limited on the ASX under the code PLS. Mining.com calls it the former Pilbara Minerals. Allkem, named for Mt Cattlin in older lists, no longer appears: Rio Tinto’s filing shows Mt Cattlin as 100% Rio Tinto.
Which Australian lithium mines are shut?
As last reported, Mt Cattlin has been on care and maintenance since 2025 (Rio Tinto, October 2026). Bald Hill went onto care and maintenance in November 2024 and Finniss is recommencing mining in 2026; PLS restarted its Ngungaju plant on 1 July 2026.
What is the difference between SC6 and SC5.2?
They are concentrate grades of 6% and 5.2% lithium oxide. Companies convert to SC6 to compare volumes, and a 5.2% tonne sells for less than a 6% tonne.
How much lithium does Australia produce?
The USGS Mineral Commodity Summaries 2026 lists 92,000 tonnes of contained lithium from Australian mines in 2025, up from 82,700 in 2024. World production was about 290,000 tonnes.
What does a lithium mine cost to run per tonne?
Reported FOB unit costs in FY26 ranged from A$415 per tonne at Greenbushes to A$987 per tonne sold at Kathleen Valley. Each company defines costs differently, and none of these figures include royalties, tax or all capital spending.
Is lithium mining in Australia profitable at today’s prices?
The producers reported positive margins for the June 2026 quarter, for example 80% EBITDA at Greenbushes and A$579 million of cash margin at PLS. Prices have since fallen: lithium carbonate in China was CNY 104,400 per tonne on 15 October 2026, down 21% in a month.
Why were some Australian lithium mines closed and?
Spodumene prices fell sharply, and higher-cost mines stopped to save cash. Bald Hill went on care and maintenance in November 2024 and Mt Cattlin in 2025. Restarts follow when prices cover cost.
Where can I check a mine’s current status?
Read the company’s quarterly activities report on the ASX announcements platform, and the Western Australian regulator’s public tenement records for licence status. The sources behind this page are listed at the end.
Are Australian lithium mines owned by Chinese companies?
Some have Chinese partners: Tianqi holds a stake in Greenbushes and Ganfeng holds half of Mt Marion. Others, such as Pilgangoora and Kathleen Valley, are held by Australian-listed companies.
This page is for information only. It is not investment advice, and it does not recommend buying or selling any company’s shares. It is not legal advice: check tenement and licence rules with the regulator. Prospecting and site visits carry safety risks, so follow local law and get permission before you enter land. Company figures are as reported on the dates shown and use different bases.
Farmonaut mining
Get a quote for satellite screening of your licence
Send your licence boundary and request a quote for satellite-based mineral screening that ranks exploration targets to test before you drill.
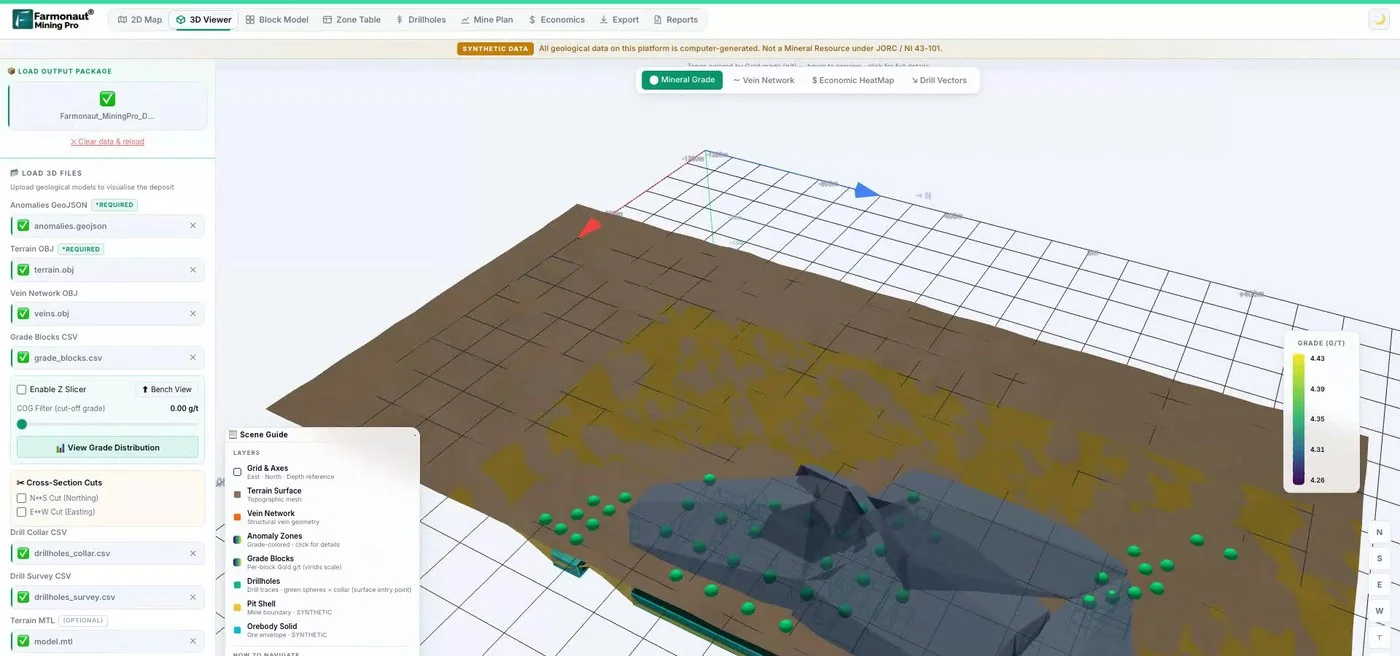
Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026: Lithium: pubs.usgs.gov
- IGO, Quarterly Report for the period ended 30 June 2026 (ASX, 28 Jul 2026): announcements.asx.com.au
- PLS Group, June 2026 Quarterly Activities Report (ASX, 30 Jul 2026): announcements.asx.com.au
- Liontown Resources, Quarterly Activities Report June 2026 (29 Jul 2026): investorpa.com
- Mineral Resources, Q4 FY26 Quarterly Activity Report (29 Jul 2026): mineralresources.com.au
- Mineral Resources, MinRes to restart Bald Hill lithium mine (19 May 2026): mineralresources.com.au
- Mineral Resources, Wodgina: mineralresources.com.au
- Mineral Resources, Mt Marion: mineralresources.com.au
- Albemarle, Mining interests: albemarle.com
- Core Lithium, June Quarterly Activities Report (ASX, 15 Jul 2026): bulletin.webull.com
- Rio Tinto, Mineral Resources and Ore Reserves statement incl. Mt Cattlin (4 Dec 2025): bulletin.webull.com
- Wesfarmers, FY26 full-year results (ASX, 27 Aug 2026): announcements.asx.com.au
- International Mining, Covalent Lithium to double spodumene output from Mt Holland (22 Jul 2026): im-mining.com
- Mining.com, Lithium price sinks to five-month low (22 Jul 2026): mining.com
- Trading Economics, Lithium carbonate price (15 Oct 2026): tradingeconomics.com
- Geoscience Australia, Australia’s Identified Mineral Resources 2026 preliminary tables: ga.gov.au
- Rio Tinto, Third quarter 2026 operations review (SEC 6-K, 14 Oct 2026): sec.gov
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS

