

Copper stocks · Screening guide
Undervalued Copper Mining Stocks: How to Screen Them
Undervalued copper mining stocks are screened on P/NAV, costs and balance sheet. Use the steps and the two-company calculator below to compare explorers on jurisdiction, runway and value per pound.
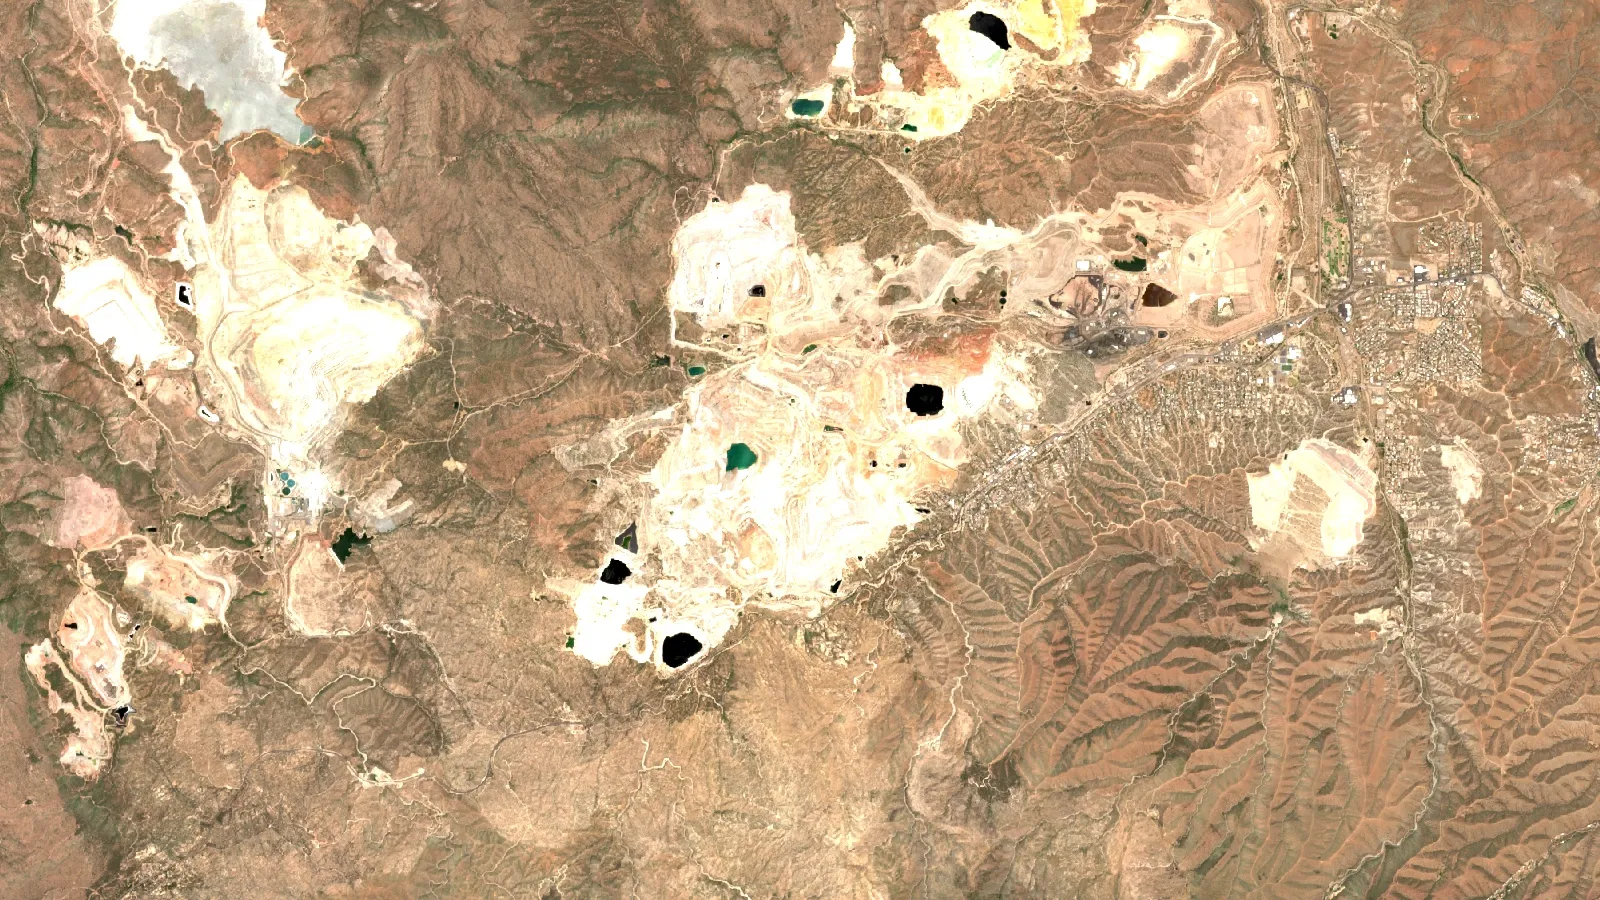
Key takeaways
- P/NAV, all-in sustaining cost and free cash flow are the screens for copper producers; explorers need runway and value per pound in the ground.
- Fraser Institute’s index weights mineral potential about 60% and policy about 40%; use it with each company’s own permit filings (Fraser Institute, 2025 survey).
- Chile (5.3 million t) leads mine output, followed by the DRC (3.2 million t) and Peru (2.7 million t); the US made about 1.0 million t (USGS, 2025 estimates).
- Compare two explorers on enterprise value per pound of copper and months of cash, using the same date and copper price.
- For information only; not investment advice.
In this article
- What "Undervalued" Means for a Copper Mining Stock
- The Supply-Demand Backdrop Driving Valuations
- Undervalued Producers vs. Undervalued Exploration Stocks
- A Practical Screen: 8 Factors That Separate Cheap From Value-Trapped
- Seven Producers Commonly Screened as Undervalued
- Where Satellite Exploration Data Fits Into Due Diligence
- Common Screening Mistakes
- Exploration & Market Videos
- Frequently Asked Questions
- Building a Repeatable Screen, Not a Static List
- Next Steps: Map Your Mining Site & Connect with Farmonaut
A copper mining stock is undervalued when its price sits below the discounted value of the copper (and by-product metal) still in the ground—measured by Price-to-Net-Asset-Value (P/NAV). That single ratio—market cap divided by the net present value of proven and probable reserves—is the difference between “cheap because the market missed it” and “cheap because the market is right to be worried.”
This page exists because the underlying supply-demand math for copper has shifted harder than most retail screens account for. The International Copper Study Group and S&P Global now project a refined copper supply deficit of 150,000 to 330,000 tonnes in 2026, narrowing only slightly to roughly 150,000 tonnes in 2027, before demand pressure from AI data centers and defense spending pushes the shortfall toward 10 million tonnes by 2040 against projected demand of 42 million tonnes (S&P Global). Below, we walk through what “undervalued” actually means for copper miners and explorers, how to screen for it yourself, and where satellite exploration data fits into due diligence before capital moves.
What “Undervalued” Means for a Copper Mining Stock
“Undervalued” is not a vibe—it’s a ratio. The standard tool is Price-to-Net-Asset-Value (P/NAV): take a company’s enterprise value and divide it by the discounted cash-flow value of everything it owns in the ground (reserves, resources, processing infrastructure), typically discounted at 8% for producers. Trade below net asset value and the market is pricing the stock at a discount to its own assets; trade meaningfully above it and you are paying a premium for growth, management, or jurisdiction safety.
That distinction matters more than the headline number: a stock trading cheap because of a fixable, temporary issue (a permitting delay, an oversold sector rotation) is a different opportunity than one trading cheap because its reserve base or jurisdiction genuinely carries more risk than peers. Screening on P/NAV alone conflates the two; you still have to read the “why.”
When spot trades above the price assumption baked into a valuation model, the “undervalued” case gets stronger—the NAV calculation was arguably too conservative to begin with. When spot falls back below that assumption, re-run the math before buying the dip.
LME copper closing prices are published daily at lme.com/metals/non-ferrous/lme-copper, and the St. Louis Federal Reserve (FRED) publishes monthly and quarterly global copper price series (tickers PCOPPUSDM and PCOPPUSDQ) that update with each release.
The Supply-Demand Backdrop Driving Valuations
Three separate data points explain why copper equities are being re-rated as a group rather than one at a time.
First, US domestic supply is a smaller share of the world than many investors assume. USGS Mineral Commodity Summaries 2026 estimates 1.0 million tonnes of US mine production (recoverable copper content) for 2025 (2024: 1.05 million tonnes)—useful context when comparing US-domiciled producers like Freeport-McMoRan against globally diversified peers (USGS Mineral Commodity Summaries 2025). The same edition puts US copper reserves at 47 million tonnes.
Second, the deficit is structural, not cyclical. ICSG and S&P Global’s January 2026 study puts the 2026 refined copper deficit at 150,000 to 330,000 tonnes, narrowing to roughly 150,000 tonnes in 2027—but that near-term narrowing masks a much larger long-run gap. By 2040, S&P Global projects global copper demand reaching 42 million tonnes against supply that falls 10 million tonnes (25%) short, driven substantially by data center capacity expected to hit 550 gigawatts globally by 2040 and by rising defense-sector copper intensity (S&P Global). ICSG republishes quarterly market reports with revised full-year estimates at icsg.org—check there for the current-quarter deficit figure rather than treating the 2026 range above as fixed.
Third, price and valuation aren’t always moving together, which is exactly the gap a stock screen is supposed to find. Whether a producer looks cheap depends on the copper price assumed in its NAV model. That’s the setup search traffic for “undervalued copper mining stocks” is really asking about: is the equity market pricing in the deficit, or still pricing copper at last cycle’s average?
Undervalued Producers vs. Undervalued Exploration Stocks
“Undervalued copper mining stocks” and “undervalued copper exploration stocks” are two different screens, and conflating them is the fastest way to misprice risk.
- Producers (Freeport-McMoRan, Southern Copper, Lundin Mining, and similar) generate current cash flow, so P/NAV, free cash flow yield, and All-In Sustaining Cost (AISC) are the right lenses. A discount here usually reflects jurisdiction risk, temporary operational issues, or sector-wide sentiment—things you can research today.
- Exploration and development-stage companies have no production revenue yet; their entire value is the market’s estimate of what’s still in the ground, discounted for the chance the deposit never gets built. A “cheap” junior explorer is really a bet that its resource estimate is right and that permitting, financing, and construction all clear—each of which can independently kill the thesis. For a broader view of how junior miners are ranked across commodities heading into 2026, see Farmonaut’s long-term junior mining stocks guide.
Geography matters differently for each group too. Investors comparing jurisdiction risk sometimes look past North and South America entirely—Farmonaut’s review of undervalued Australian mining stocks covers a market with a very different regulatory and currency profile, and the European supply side (relevant to KGHM specifically) is covered in Farmonaut’s breakdown of Europe’s main copper mines excluding Russia.
On extraction cost specifically: per-tonne AISC varies by deposit type, ore grade, strip ratio, and processing route, and we could not source a single verified cross-company AISC table for this review. Company 10-K and annual reports disclose AISC per pound or per tonne directly—for the seven producers listed below, that figure sits in each company’s most recent quarterly earnings release, and it is the single most important number to check before assuming a low share price means a cheap asset.
A stock trading below P/NAV because of a permitting delay is a different risk than one trading below P/NAV because its ore body is genuinely lower-grade than peers. Read the “why” behind the discount before treating it as an opportunity.
A Practical Screen: 8 Factors That Separate Cheap From Value-Trapped
This is the durable part of this page—the checklist below doesn’t expire when copper prices move. Run any candidate copper stock through it before treating a low P/E or low P/NAV as a buy signal:
Chart
Copper mine output, selected countries
Thousand tonnes of recoverable copper, 2025 estimates
- P/NAV relative to the sector benchmark. Compare each stock with its peers on the same NAV basis, then find out why the company sits where it does.
- AISC trend, not just AISC level. A producer with rising AISC quarter-over-quarter is getting less undervalued even if the share price hasn’t moved.
- Free cash flow yield at current spot, not at the consensus price. Re-run the math at both the model’s long-term copper price and the live spot price—the gap between the two tells you how much of the current valuation is already pricing in higher copper.
- Reserve life and grade trend. A shrinking reserve life or declining head grade erodes NAV even if the P/NAV ratio looks static.
- By-product credits (molybdenum, nickel, precious metals) that reduce net cash cost per tonne and buffer margins when copper alone dips.
- Jurisdiction and permitting status, checked against the company’s own regulatory filings, not general country risk indices.
- Balance sheet and hedging position. Debt maturities and any price hedges below current spot both cap upside during a deficit-driven rally.
- Capital discipline. Expansion plans funded from free cash flow are a different risk profile than a single mega-project funded by new debt.
Screening on P/E or share-price momentum alone. Two producers with identical P/E ratios can carry very different NAV discounts if their reserve life, AISC, or jurisdiction risk diverge—P/NAV is the metric built to catch that; P/E isn’t.
How to compare two copper exploration companies side by side
Start with the same four numbers for both companies, taken from each one’s latest quarterly report and technical report: enterprise value (market cap minus cash), contained copper in the resource, cash on hand and the yearly cash burn. Divide enterprise value by contained copper to get a price per pound in the ground. Divide cash by burn to get months of runway. Two explorers with similar market caps can look very different on these two ratios, and the gap is usually what should tip the decision.
Then ask what each number is made of. A resource that is mostly inferred is a weaker base than one that is mostly measured and indicated. A resource at 0.3% copper needs a very large, low-cost open pit; a resource at 1% or more can carry higher costs. In Canada, resources are reported under NI 43-101, so read the technical report, not the press release (the rule was proposed for replacement by the Canadian Securities Administrators in June 2025; CSA notice).
How to compare the jurisdiction risk of copper exploration companies
Rank the places where each company holds its main project, not where its head office sits. The Fraser Institute Annual Survey of Mining Companies is the usual starting point: its Investment Attractiveness Index weights mineral potential at roughly 60% and policy factors at about 40%, and the 2025 survey put Nevada, Ontario and Saskatchewan at the top (Fraser Institute, 2025 survey; summarised by The AU Report). Use it as one input, then check four things in each company’s own filings: who owns the licence, how long the permit stage has run, what royalty and tax regime applies, and whether any export or ownership rule changed recently.
North America against South America is a question about permits, taxes and community agreements as much as geology. Chile is the world’s largest copper miner and Peru the third largest, after the Democratic Republic of the Congo, so they offer real infrastructure and a long mining record, while the United States produces much less and relies on imports (USGS Mineral Commodity Summaries, 2026). Neither region is safer in every case. Judge each project on its own permit status and timeline.
Balance sheet, dilution and lowest-cost projects
An explorer without a producing mine pays for drilling by selling shares. Check the cash runway (the calculator below), the number of warrants and options outstanding, and whether a financing is planned within twelve months. A company with 24 months of cash can wait for a better share price; one with six months usually cannot. For a project, the figures that point to low cost are high grade, shallow ore, existing roads and power, and by-product credits. A study for an exploration project is an estimate only, so compare studies prepared on the same copper price and the same date.
Analyst ratings on small TSX Venture names are thin and often come from one or two firms. Read the rating’s date and price target basis, and treat it as a lead for your own check. This page gives facts for screening only. It is not investment advice.
Where satellite screening helps the comparison
Before you size a position in an explorer, a satellite alteration and structure map of its licence can show whether the claimed target sits on a plausible mineral system. That is a screening layer that comes before drilling, not a resource estimate.
Calculator
Which of two copper explorers is cheaper per pound?
Enter each company’s own figures from its latest report. Company A first, then B.
- Company B value per pound (US$/lb): 0.04
- Company A months of cash: 16.0
- Company B months of cash: 30.0
Example values only, not benchmarks. Take market cap, cash, burn and contained copper from each company’s filings of the same date. All money in US$ millions; resource in million pounds of copper.
Seven Producers Commonly Screened as Undervalued
These are the names that most frequently surface in P/NAV-based copper screens, listed for reference alongside what to verify before acting on any of them. This is not a ranked recommendation—current share price, P/E, and P/NAV move daily and require a live quote, which this review does not have access to.
- Freeport-McMoRan Inc. (FCX) — Largest US-domiciled copper producer; check its most recent 10-Q for current AISC and US production share against the 1.0 million tonne national total (USGS, 2025 estimate).
- First Quantum Minerals Ltd. (FM) — Check its P/NAV against peers and what jurisdictional risk the market is pricing in.
- Lundin Mining Corporation (LUN) — Diversified low-AISC producer with Europe and Americas exposure; cross-check reserve life in its latest annual report.
- Southern Copper Corporation (SCCO) — Major Latin American producer; note its P/E and margin profile are historically higher than peers, which affects where it sits on P/NAV versus peers.
- KGHM Polska Miedź S.A. — Central European producer; see Farmonaut’s dedicated breakdown of Europe’s main copper mines excluding Russia for regional production context.
- Hudbay Minerals Inc. (HBM) — Canada/Peru-focused producer; check current hedging disclosures given its smaller balance sheet relative to the majors above.
- Capstone Copper Corp. (CS) — Americas-focused producer noted for water-reclamation and tailings investment; verify current AISC trend against its expansion capex schedule.
None of the figures above are current share prices, P/E ratios, or market caps—live data for September 2026 was not available in the research used for this review. Pull current quotes from your brokerage or a live market data terminal before comparing any of these names against the P/NAV benchmarks discussed above.
Where Satellite Exploration Data Fits Into Due Diligence
Equity screening tells you what the market thinks a deposit is worth. It does not tell you whether the resource estimate behind that NAV is well-supported by ground truth, or whether a nearby exploration target could extend mine life beyond what’s currently priced in. That’s a separate, geological question—and it’s where Farmonaut’s work sits.
Farmonaut’s satellite-based mineral detection platform has been used across 18+ countries and 13+ mineral types to screen prospective ground before a field team is mobilized. For an investor or exploration company evaluating whether a company’s stated resource is likely to hold up—or whether adjacent claims carry unrecognized potential—satellite-derived prospectivity mapping compresses a process that traditionally takes months into days, at a reported 80-85% cost reduction versus conventional early-stage exploration methods, and without ground disturbance.
- 🚀 Faster screening: Prospectivity mapping in days rather than months, ahead of any drill program.
- 🌍 Cross-terrain applicability: Deployed across porphyry, sediment-hosted, and skarn copper settings on multiple continents.
- 💸 Lower upfront cost: Up to 80-85% cost reduction in early-stage exploration versus ground-based survey methods alone.
- 🌱 Non-invasive: No ground disturbance before a company commits capital to drilling.
- 🗺️ GIS-ready output: Prospectivity heatmaps and high-resolution maps compatible with standard mining GIS software.
For a technical look at how remote sensing is applied specifically to copper targets, see Farmonaut’s remote sensing applications in copper prospecting guide, and for a worked example of 3D output, review this satellite-driven 3D mineral prospectivity map.
For an active exploration company or a fund doing pre-drill diligence on a junior copper name, Farmonaut’s Premium and Premium+ mineral intelligence reports provide the geospatial layer that a P/NAV screen alone cannot: independent evidence of whether a resource claim is geologically plausible, before capital is committed to drilling or a position is sized.
🌟 Satellite analytics screen large regions before any field activity, saving time and capital on new mining prospects.
Map Your Mining Site Here
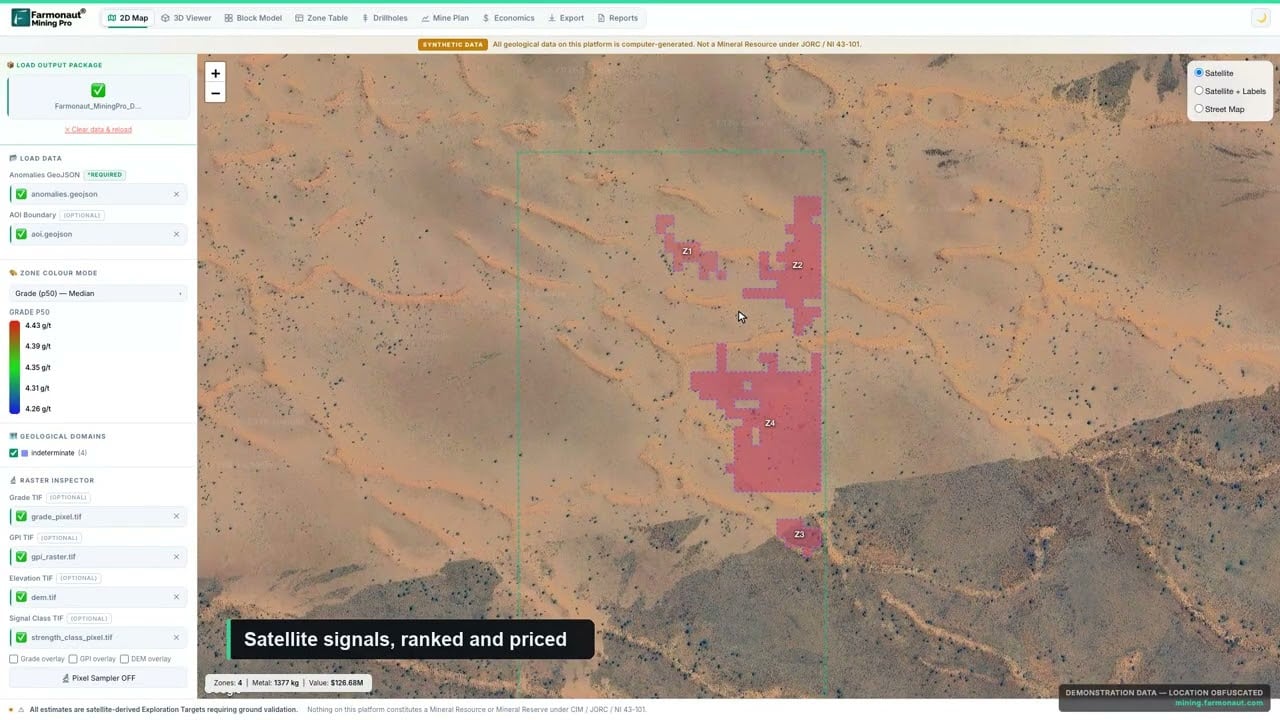
▶ Introduces Farmonaut Mining Pro, which turns a licence boundary into a geological and economic picture. · 4:56
Common Screening Mistakes
🌍 A stock’s P/NAV discount only means something once you know the assumed copper price behind the NAV. Two “cheap” stocks can be pricing in very different copper assumptions.
📈 Re-run any NAV model at the live spot price rather than accepting a NAV built on last year’s consensus. If a “discount” only exists because the model used a stale $10,000/tonne assumption, it isn’t a real discount.
🛑 Treating exploration-stage juniors and cash-flowing producers as the same screen. A junior’s “NAV” is an unproven resource estimate; a producer’s NAV is backed by current output. Confusing the two overstates how “undervalued” an explorer really is.
✅ Compare P/NAV across peers;
✅ Check AISC trend over the last four quarters, not a single data point;
✅ Confirm the copper price assumption behind any published NAV;
✅ Read the jurisdiction-risk disclosure in the company’s own filings.
💼 For broader copper price context and how futures markets have moved through 2026, see Farmonaut’s copper price analysis and futures records piece.
Exploration & Market Videos
The videos throughout this page cover copper-relevant exploration methods and regional market context, from Arizona porphyry systems to African production and satellite detection case studies.
▶ Explains the three jobs an AI mining app does and who builds one. · 3:52
Frequently Asked Questions
Undervaluation is measured against Price-to-NAV, not share price alone. A stock trading meaningfully below its peers on P/NAV may be worth investigating, provided the reason for the discount is temporary rather than structural.
S&P Global’s January 2026 study attributes accelerating demand growth to AI data center buildout (projected at 550 gigawatts of global capacity by 2040) and rising defense-sector consumption, pushing total demand to 42 million tonnes by 2040 against a projected 10 million tonne shortfall.
Yes. ICSG and S&P Global project a 150,000 to 330,000 tonne refined copper deficit for 2026, narrowing to about 150,000 tonnes in 2027. Check icsg.org for the current-quarter revised estimate, since ICSG updates this figure quarterly.
Mining stocks (producers) generate current revenue and are screened on P/NAV, AISC, and free cash flow yield. Exploration stocks have no production revenue—their value is entirely the market’s confidence in an unproven or partially proven resource, which makes them higher-risk and harder to benchmark with the same ratios.
Farmonaut provides satellite-based mineral detection and 3D prospectivity mapping that screen large regions before field mobilization, at a reported 80-85% cost reduction in early exploration versus conventional methods—useful context for investors validating a junior miner’s resource claims before sizing a position.
LME publishes daily closing prices at lme.com/metals/non-ferrous/lme-copper. FRED (St. Louis Federal Reserve) publishes monthly and quarterly series (PCOPPUSDM, PCOPPUSDQ). Kitco’s live base-metals page updates intraday. This page’s September 2026 figures will be out of date by the time you read this—pull a current quote from one of those three sources.
Building a Repeatable Screen, Not a Static List
The seven producers named above will not stay “undervalued” indefinitely—copper prices, P/NAV ratios, and company-specific catalysts move constantly. What doesn’t expire is the method: compare P/NAV against the sector benchmark, check whether the discount is temporary or structural, verify the copper price assumption behind any NAV model, and confirm AISC trend and jurisdiction risk directly from company filings.
The structural case for copper—an ICSG-projected refined deficit through 2027 and a widening gap toward 2040 as AI infrastructure and defense spending pull on the same supply—gives the sector a tailwind that most retail screens still underprice. Pair that macro read with a disciplined P/NAV screen, verify resource claims with independent geospatial evidence where it matters, and re-run every number in this article against a live source before acting on it.
Next Steps: Map Your Mining Site & Connect with Farmonaut
- Evaluating a copper asset or exploration target? Get a quote here for Farmonaut’s Premium exploration insight.
- Questions about integrating satellite intelligence into your copper prospecting? Contact Us and our experts will guide you.
- To explore prospects immediately: Map Your Mining Site Here
Copper’s supply-demand structure will keep shifting as data center and defense demand build through 2040. Check the sources linked throughout this page—ICSG, S&P Global and USGS—directly for the current numbers before making an investment decision.
This page is for information only. It is not investment advice.
Farmonaut mining
Screen a copper licence from space
Request a quote for satellite mapping of a copper licence area before drilling.

Mining Pro sample view, synthetic data
Keep reading
Sources
- Fraser Institute, Annual Survey of Mining Companies 2025: fraserinstitute.org
- The AU Report, ranking of mining jurisdictions (Fraser 2025 survey): theaureport.com
- USGS, Mineral Commodity Summaries 2026, Copper: pubs.usgs.gov
- Canadian Securities Administrators, NI 43-101 notice (2025): osc.ca
- Skillings Mining Review, Nevada tops Fraser survey: skillings.net
- BNN Bloomberg, Ontario mining investment study: bnnbloomberg.ca
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Swati Minerals
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS

 Exploration consultancy · South Africa · Gold










