

Tin · Deposits and mining guide
Cassiterite Mining: Tin Deposits, Top Mines and Methods
Cassiterite (SnO2) is the main ore of tin, symbol Sn. Mines produced about 290,000 t of tin in 2025, led by China, Indonesia, Peru, Brazil and Congo; about 80% of identified resources are placers and 20% granite-related lodes (USGS).
Key takeaways
- World mine output was an estimated 290,000 t of tin in 2025, and the top five countries (China, Indonesia, Peru, Brazil, Congo) made about three-quarters of it (USGS, Mineral Commodity Summaries 2026).
- About 80% of identified tin resources are placers and about 20% are hard-rock lodes tied to granite (USGS Professional Paper 1802-S, 2017).
- Reported grades vary widely: Bisie mill feed was 3.2% Sn (Sn is the symbol for tin) in the September 2026 quarter, San Rafael’s head grade 2.88% Sn in the second quarter of 2026, and the Renison resource 1.38% Sn (Alphamin, Shanghai Metals Market, Metals X).
- The LME cash settlement for tin was US$51,300 per tonne on 27 October 2026, against a 2025 average of about US$33,000 (Westmetall; USGS).
- The United States has not mined tin since 1993 and relied on imports for 77% of its refined tin in 2025 (USGS).
In this article
- Cassiterite mining at a glance
- What cassiterite is and how to recognise it
- Where tin deposits are found
- Top tin-producing countries ranked by mine output
- Which countries gained or lost tin output
- Tin mines and projects worth knowing
- How cassiterite is mined and processed
- How much tin is left in the ground
- Tin prices and mining costs
- What tin is used for
- How to screen ground for tin before you buy or stake
- Frequently asked questions
Cassiterite mining at a glance
Cassiterite (tin oxide, SnO2) is the main ore of tin, and the world’s mines produced an estimated 290,000 tonnes of tin in 2025, led by China (71,000 t), Indonesia (61,000 t), Peru (33,000 t), Brazil (28,000 t) and the Democratic Republic of Congo (27,000 t) (USGS Mineral Commodity Summaries 2026). About 80% of identified tin resources are loose placer deposits in rivers, valleys and on the sea floor, and about 20% are hard-rock veins and lodes tied to granite (USGS Professional Paper 1802-S, 2017). The LME cash settlement price for tin was US$51,300 per tonne on 27 October 2026 (Westmetall, LME cash-settlement prices).
This guide is written for licence and claim owners, consultants and investors. It explains how cassiterite forms and where tin deposits sit, ranks the producing countries, profiles working mines with their latest published numbers, walks through mining and processing, and ends with a worked calculator and a due-diligence checklist. Tin is not mined in the United States: the last mine closed in 1993 and the last smelter in 1989 (USGS).
What cassiterite is and how to recognise it
Cassiterite is a very dense, hard mineral. USGS gives it a specific gravity of 6.8 to 7.1 (meaning it is almost seven times heavier than water) and a Mohs hardness of 6 to 7. Its colour ranges from black and brown to yellow, red or white, with a greasy, diamond-like shine (USGS Professional Paper 1802-S). Pure cassiterite is roughly 79% tin by weight, which is the ratio of tin’s atomic mass (118.7) to that of SnO2 (150.7).
The density is the key to mining it. Running water carries lighter rock away and leaves cassiterite behind, which is why tin collects in stream beds. The same property lets a plant separate it from waste rock with gravity methods such as jigs and shaking tables. Cassiterite is also easy to confuse with other dark heavy minerals in a pan, so assays decide what a sample really holds.
Where tin deposits are found
Almost every tin deposit is linked to granite. USGS describes the hydrothermal (hot-fluid) tin deposits as a close family tied to highly evolved granite intrusions, which form pegmatites, disseminated ore, sheeted veins bordered by greisen (granite altered to quartz and mica), skarns and limestone replacements (USGS, 2017). Placer deposits form when weathering releases the cassiterite and streams or the sea concentrate it, so placers sit downstream of the same granites.
| Deposit type | How it forms | Where it is mined | Usual mining method |
|---|---|---|---|
| Alluvial and offshore placer | Weathering releases cassiterite; water concentrates it in gravels | Indonesia (Bangka, Belitung), Malaysia, Thailand, Brazil | Open pit, gravel pump or dredge |
| Eluvial and saprolite | Weathered granite keeps the heavy cassiterite in place | Pitinga, Brazil (tin from saprolite on albite granite) | Open pit |
| Greisen and sheeted veins | Hot fluids alter the roof of a granite | Cornwall (UK), Gejiu (China), Pitinga (Brazil) | Underground, some open pit |
| Skarn and carbonate replacement | Fluids replace limestone or dolomite near a granite | Renison, Tasmania; Gejiu, China | Underground |
| Granite-related lodes | Cassiterite in lodes linked to a granite intrusion | San Rafael, Peru (Bolivian tin belt) | Underground |
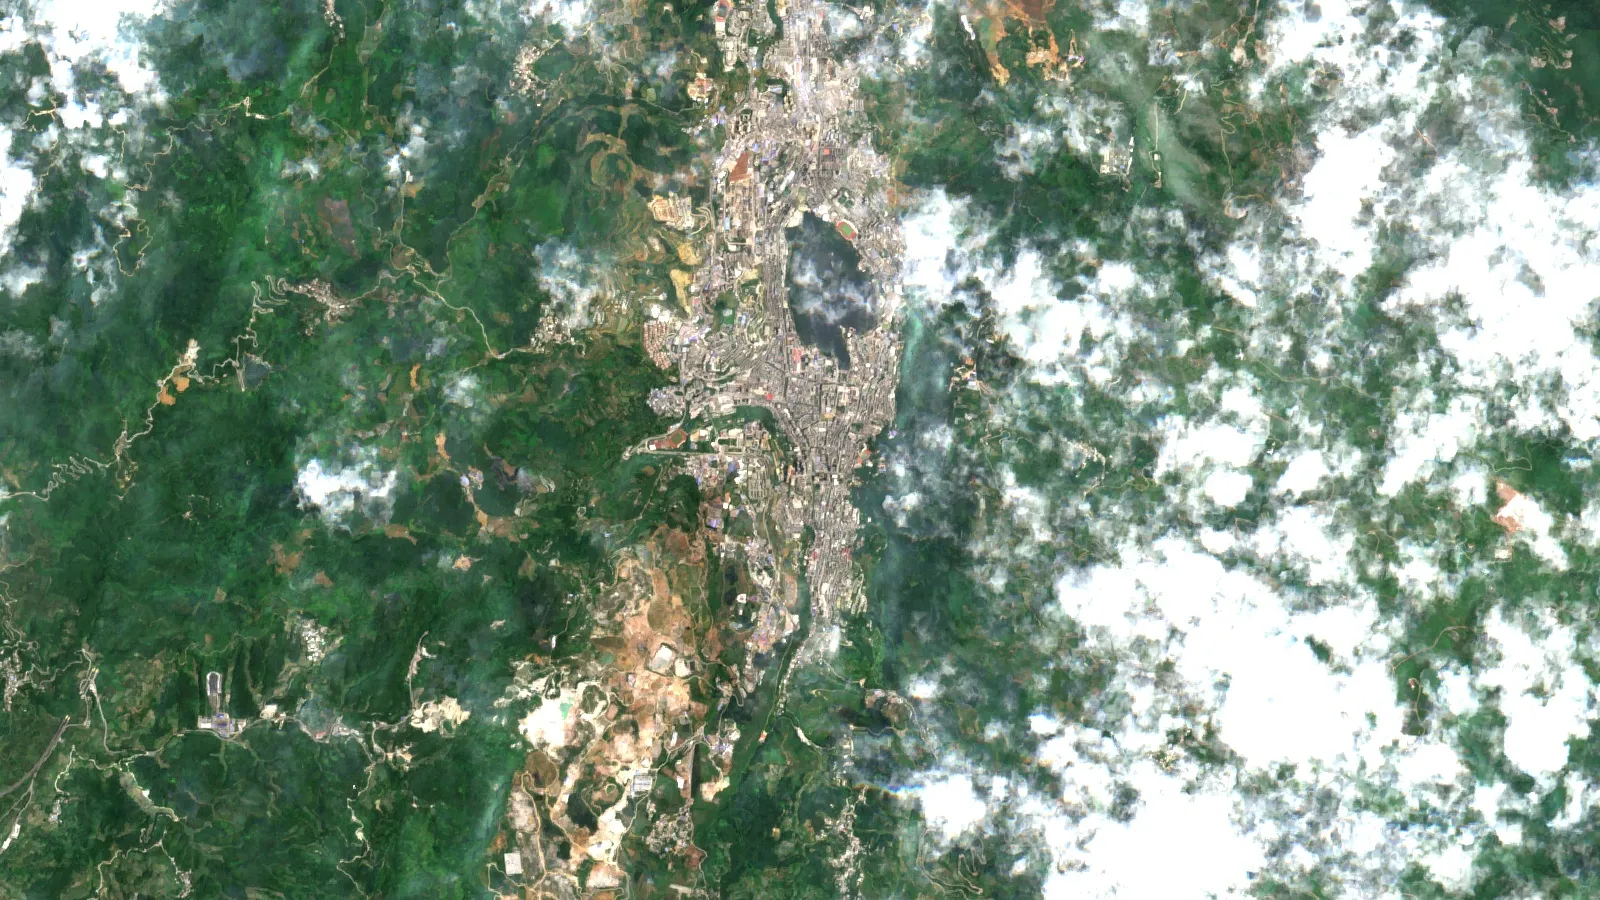
Tin deposits cluster in belts. The Southeast Asian tin belt stretches from China in the north, through Thailand, Burma (Myanmar) and Malaysia, to the Indonesian tin islands; its main part, from Burma and Thailand to Malaysia and Indonesia, is about 2,800 km long and 400 km wide. The Bolivian tin belt runs about 1,100 km through the Eastern Cordillera of Bolivia and reaches from southern Peru, where the San Rafael mine sits, to northern Argentina. The Gejiu district in Yunnan, China, is the largest primary (hard-rock) tin district in the world, with about 300 million tonnes of ore averaging 1% tin (USGS, citing Cheng and others, 2013). Because the belts are well mapped, USGS notes that undiscovered deposits are most likely near known ones.
In the United States, identified tin resources are small, mostly in Alaska, where the Lost River deposit on the Seward Peninsula is one of the few primary hard-rock tin deposits (USGS). Cornwall in England mined tin from at least Roman times and produced more than 2 million tonnes before the mines were largely exhausted. South Crofty, the last working Cornish mine, closed in 1998 (USGS).
Top tin-producing countries ranked by mine output
The ranking below uses USGS 2025 estimates of tin contained in mine output. Reserves are the part of resources that is economic to mine under USGS’s definitions, so they change as prices and costs change. The five largest producers made about three-quarters of the world total (220,000 of 290,000 t).
Chart
Tin mine production by country
Thousand tonnes of contained tin, 2025 estimate, eight largest producers
| Rank | Country | 2024 (tonnes Sn) | 2025 estimate (tonnes Sn) | Reserves (tonnes Sn) |
|---|---|---|---|---|
| 1 | China | 71,000 | 71,000 | 1,200,000 |
| 2 | Indonesia | 55,000 | 61,000 | 1,400,000 |
| 3 | Peru | 32,300 | 33,000 | 150,000 |
| 4 | Brazil | 27,600 | 28,000 | 700,000 |
| 5 | Congo (Kinshasa) | 26,000 | 27,000 | 91,000 |
| 6 | Bolivia | 21,200 | 15,000 | 400,000 |
| 7 (tie) | Australia | 11,300 | 12,000 | 570,000 |
| 7 (tie) | Burma (Myanmar) | 20,000 | 12,000 | 700,000 |
| 9 | Vietnam | 11,000 | 11,000 | 23,000 |
| 10 | Malaysia | 5,460 | 5,000 | not available |
| 11 | Rwanda | 4,100 | 4,600 | not available |
| 12 | Russia | 3,260 | 4,500 | 460,000 |
| 13 | Nigeria | 3,100 | 3,500 | not available |
| 14 | Laos | 1,860 | 1,800 | not available |
| – | Other countries | 1,570 | 1,700 | 310,000 |
| – | World total (rounded) | 294,000 | 290,000 | more than 6,000,000 |
Source: USGS Mineral Commodity Summaries 2026, tin (February 2026). The United States produced no mined tin.
Which countries gained or lost tin output
The 2025 estimates show a split. Indonesia rose by 6,000 t, to 61,000 t, while Bolivia fell from 21,200 t to 15,000 t and Burma from 20,000 t to 12,000 t. USGS also revised the 2024 figures for Brazil, Burma, Laos, Malaysia, Nigeria and Vietnam using company and government reports, so older tables you may find online can differ by several thousand tonnes. Congo (Kinshasa) edged up from 26,000 t to 27,000 t, helped by Bisie, described below, and Rwanda and Nigeria also rose, to 4,600 t and 3,500 t.
Chart
Change in tin mine output, 2024 to 2025
Thousand tonnes of contained tin, seven large producers
Tin mines and projects worth knowing
There is no single public ranking of individual tin mines, because many operators report on different bases (tin in concentrate, tin refined, 100% or an ownership share). The table lists mines with recent figures from the operator or a trade body, each on the basis stated. Grades are not comparable across rows: a mill feed grade, a resource grade and a district average measure different things.
| Mine or project | Country and operator | Deposit style | Published figures (period shown) |
|---|---|---|---|
| Bisie (Mpama North and South) | DRC; Alphamin Resources (84.14% of the operating company) | High-grade underground cassiterite | 18,576 t of contained tin in the 2025 financial year; 5,030 t in the quarter to 30 September 2026 at 3.2% Sn feed and 72.9% recovery |
| San Rafael and B2 tailings | Peru; Minsur | Underground, granite-related | 7,359 t of tin in concentrate from the mine in the second quarter of 2026 (9,511 t with B2 tailings), at a head grade of 2.88% Sn |
| Renison | Tasmania, Australia; Bluestone Mines Tasmania JV (Metals X 50%) | Skarn and carbonate replacement | 5,696 t of tin in concentrate in the half-year to 30 June 2026 (100% basis); resource 21.8 Mt at 1.38% Sn |
| Gejiu district | Yunnan, China | Greisen, skarn, replacement and veins | About 300 Mt of ore averaging 1% Sn (USGS, citing 2013 research) |
| Bangka and Belitung | Indonesia | Onshore and offshore placers | Seagoing dredges work Bangka; the Klappa Kampit mine on Belitung is the largest hard-rock tin deposit in the country (USGS, 2017) |
| South Crofty | Cornwall, UK; Cornish Metals (AIM: TIN) | Zoned greisen and replacement lodes | In development; dewatering had passed 400 m below surface by 12 October 2026; not yet in production |
Bisie, Democratic Republic of Congo
Alphamin Resources owns 84.14% of Alphamin Bisie Mining, which runs the Mpama North and Mpama South underground mines (Alphamin, 19 January 2026). The company says Mpama North has a run-of-mine grade (the grade of ore as it leaves the mine, before processing) of around 4% tin and describes it as the highest-grade tin mine in the world. Both plants use gravity separation with a small flotation step to clean the concentrate (Alphamin, operations page). Alphamin’s shares trade on the TSX Venture Exchange (AFM) and the JSE AltX (APH).
In the quarter to 30 September 2026 the mine made 5,030 t of contained tin from 213,454 t of ore, against an annual guidance of about 20,000 t. The company guided to an all-in sustaining cost of US$20,642 per tonne sold for the quarter (Alphamin, 6 October 2026). Its exploration shows the grades being drilled: one Mpama South hole cut 19.29 m (an apparent width, not a true width) at 5.76% Sn from 426 m depth, and an updated resource and reserve estimate is planned for late in the fourth quarter. The January 2026 release also reports security events in North Kivu province, about 200 km from the mine, a reminder that location risk is part of tin investing in Central Africa.
San Rafael, Peru
Minsur’s San Rafael underground mine produced 7,359 t of tin in concentrate in the second quarter of 2026, up 14% on the year, at a head grade (the grade of ore fed to the plant) of 2.88% Sn. For the first half it made 13,455 t at an average 2.64% Sn, and output including the B2 tailings reclaim was 9,511 t for the quarter (Shanghai Metals Market, 31 July 2026). In the third quarter of 2025 the mine’s cash cost was US$7,985 per tonne of tin (International Tin Association, 5 November 2025). San Germain is a high-grade satellite deposit of San Rafael, and Minsur raised exploration spending to expand the tin resource. San Rafael sits at the northern end of the Bolivian tin belt (USGS).
Renison, Tasmania
Metals X holds 50% of Renison through the Bluestone Mines Tasmania joint venture. The mine lies 15 km north-east of Zeehan, and Metals X describes it as one of the world’s largest operating underground tin mines and Australia’s largest primary tin producer. The ore is pyrrhotite-cassiterite replacement mineralisation hosted by three shallow-dipping dolomite horizons. The 2026 resource update lifted contained tin to 300,300 t in 21.8 Mt at 1.38% Sn, and the latest reserve quoted in that report, dated 31 March 2025, was 7.505 Mt at 1.37% Sn (a 2026 reserve update was due in the September quarter) (Metals X half-year report, 30 June 2026).
South Crofty, Cornwall
Cornish Metals (AIM: TIN) wholly owns the permitted South Crofty project and describes it as the highest-grade known tin resource not in production. In its 12 October 2026 update the company reported that dewatering had passed 400 m below surface, with the 400-level, about 730 m below surface, targeted in the first half of 2027, and that its Roskear West drilling confirmed tin lodes continuing west of the current resource (Cornish Metals, 12 October 2026). In its 10 June 2026 update it put the project’s net present value (6% discount rate) at about £500 million using a tin price of about US$53,000 per tonne, a company estimate rather than a forecast (Cornish Metals, 10 June 2026).
How cassiterite is mined and processed
Most placer tin is mined by open pit or dredging. Rivers can carry more sediment downstream and may be diverted, and offshore dredging in Burma, Indonesia, Malaysia and Thailand can affect seabed and water-column life (USGS). Hard-rock tin comes from underground mines or, where the lode is shallow, open pits. The route from ground to metal has five stages.
- Find and drill. Explorers trace granite contacts, greisen and stream-sediment tin anomalies, then drill to measure grade and thickness.
- Mine. Dredges, gravel pumps or open pits handle placers. Underground mines use drilling and blasting, often with backfill.
- Crush and grind. Hard rock is crushed and milled just fine enough to release the cassiterite grains, because over-grinding makes slimes that lose tin.
- Concentrate by gravity. Jigs, spirals and shaking tables exploit the high density, sometimes followed by flotation or magnetic steps to remove sulphides and iron minerals. Alphamin reports about 73% plant recovery at Bisie, which shows that a large share of the tin can still be lost to tailings.
- Smelt and refine. The concentrate goes to a smelter. Yunnan Tin Group was the largest refined-tin producer in 2022, ahead of Minsur, Yunnan Chengfeng and PT Timah (USGS Mineral Industry Surveys, tin in December 2022, citing the International Tin Association).
Responsible sourcing is part of the job. Tin is one of the four minerals (with tantalum, tungsten and gold) covered by the EU Conflict Minerals Regulation, in full force since 1 January 2021, which requires importers to carry out supply-chain due diligence (European Commission, trade policy). Buyers of a tin concentrate will ask where it came from.
▶ The seven environmental impacts of mining, explained in plain words with satellite maps. · 2:31
How much tin is left in the ground
USGS puts world tin reserves at more than 6 million tonnes, roughly 20 years of output at the 2025 rate. China and Indonesia hold the largest reserves, while Peru and Congo (Kinshasa), the third and fifth largest producers, report comparatively small reserve bases of 150,000 t and 91,000 t. USGS revised the reserves for Australia, Brazil, China, Congo, Indonesia and Peru in the 2026 edition. Reserves are a snapshot that operators update as they drill, so they are a poor guide to what is geologically present.
Chart
Tin reserves by country
Thousand tonnes of contained tin, eight largest reserve holders
Tin prices and mining costs
Tin is priced on the London Metal Exchange (LME). The annual average LME cash price was 1,500 US cents a pound in 2025, 10% above 2024, which is about US$33,000 per tonne (USGS). On 27 October 2026 the cash settlement was US$51,300 per tonne, or about US$23.27 a pound (Westmetall, from LME data). Price is an input, not a fact to bank on: always run a project at several prices.
Chart
Annual average LME cash price of tin
US$ thousand per tonne (converted from US cents per pound)
Costs differ by deposit type and by how each company defines them. Alphamin guided to an all-in sustaining cost of US$20,642 per tonne sold at Bisie for the September 2026 quarter, which includes off-mine costs that rise with the tin price. Minsur reported a mine cash cost of US$7,985 per tonne at San Rafael for the third quarter of 2025. These are different bases and should not be compared line by line. For your own project, the calculator below turns a grade, a recovery and a price into tonnes of tin, concentrate and revenue.
Calculator
What is a tin operation worth at your grade and price?
Enter ore tonnes, grade, recovery, concentrate grade, a tin price and a cost to estimate tin, concentrate, revenue and margin.
- Concentrate produced (tonnes): 6,364
- Payable revenue at your price (US$ million): $149
- Margin before tax, royalties and capital (US$ million): $99
Example values only, not a forecast or a company result. Prices are inputs: use today’s price. The tin price is US$ per tonne of contained tin; payable share is the percentage of the metal value the smelter pays for after treatment charges and penalties (an example, ask for a real offtake offer). Operating cost is US$ per tonne of ore and ignores royalties, tax and capital.
What tin is used for
Solder is the largest use of tin, at 51% of global use in 2023, and an estimated 92% of electronics solder was made without lead that year. Refined tin use was 357,100 t in 2023, down 3.9% on 2022, and recycled material supplied 34.2% of total tin use (International Tin Association, 30 October 2024). Other uses are tinplate for food cans, chemicals, lead-acid batteries and tin-copper alloys.
The US mix differs. In the United States, chemicals took 25% of tin, tinplate 16%, alloys 12% and solder 11%. The United States imported 32,000 t of refined tin in 2025 and relied on imports for 77% of its apparent consumption (USGS). A US company began building a US$65 million tin production facility in Martinsville, Virginia, in September 2025, expected to be operating by late 2026 (USGS).
How to screen ground for tin before you buy or stake
Use this checklist for a claim, a licence or a share in a tin explorer. It is a screening list, not a valuation.
- Check the geology first. Is there an evolved granite, greisen, or a river draining one? USGS finds that tin placers are almost always closely allied to the granites they come from.
- Ask what the grade is measured on. Feed grade, resource grade and concentrate grade are different. A 1% Sn resource is typical of large districts such as Gejiu; Bisie’s 3% plus feed is exceptional.
- Look at recovery. Fine cassiterite is lost in gravity plants, so ask for metallurgical test work and the recovery used in any study.
- Check who else works the ground. Placers are often held by artisanal miners. Confirm tenure, access and any overlapping claims at the regulator.
- Price the concentrate, not the metal. Smelters pay a percentage of the LME price after treatment charges and penalties, so use payable terms from a real offtake offer.
- Plan for traceability. Buyers in the EU and elsewhere expect due diligence on origin.
USGS notes that tin exploration has long used panning, trenching, drilling and assaying, with geophysical and geochemical surveys used to cover large areas and make drilling cheaper, and that barium, lithium, niobium, potassium, rubidium and zirconium are reliable chemical indicators of tin-bearing granites (USGS, 2017). Satellite imagery cannot see cassiterite grains, but it can map granite outlines, alteration, faults and old workings so that sampling begins in the right place. Farmonaut offers satellite-based mineral detection reports, delivered in 5 to 20 business days from a polygon or KML file, and you can ask for a quote through the mining query form or contact us.
Tin sits beside other granite-related metals. For tungsten, which often shares a granite source, see tungsten in Canada. For another base-metal producer ranking, see zinc mining and the top producing countries and where copper is found.
▶ Remote sensing for mining in three minutes: the six instrument families and why agreement between them matters. · 2:01
Much hard-rock tin and tantalum comes from pegmatites: see pegmatite deposits for types and examples.
Tantalum often comes from the same ores: see tantalum mines: top producers, owners and rules.
Frequently asked questions
What is cassiterite mining?
It is the extraction of cassiterite, the oxide ore of tin, from placer gravels or hard-rock lodes, followed by gravity concentration to make a tin concentrate that goes to a smelter. USGS calls cassiterite by far the predominant ore mineral of tin.
What is the ore of tin called?
Cassiterite, with the formula SnO2. Small amounts of tin are also recovered from sulphide minerals such as stannite, but cassiterite supplies almost all of the world’s tin.
Where are tin deposits found?
Mainly in belts of granite: the Southeast Asian belt from China to Indonesia, the Bolivian belt into southern Peru, Central Africa (DRC and Rwanda), Brazil, Australia (Tasmania) and Cornwall. About 80% of identified resources are placers and 20% hard-rock lodes (USGS).
Which country mines the most tin?
China, at an estimated 71,000 t in 2025, followed by Indonesia at 61,000 t. Indonesia has the larger reserves, 1.4 million t against China’s 1.2 million t (USGS).
How does cassiterite form, and why does it matter?
Tin-rich fluids released as evolved granite cools deposit cassiterite in veins, greisen and skarns near the granite. Erosion then moves it into rivers and coastal sands. It matters because tin is the key metal in solder and food-can coatings, and the United States relies on imports for 77% of its refined tin.
How rich is a tin ore?
Much lower than most people expect. Large resources run about 1% to 1.4% Sn (Gejiu about 1%; Renison 1.38%), while Alphamin’s Bisie mill feed was 3.2% in the September 2026 quarter and San Rafael’s head grade was 2.88% Sn in the second quarter of 2026. Sn is the chemical symbol for tin.
How is cassiterite separated from other minerals?
By density. After crushing and milling, jigs, spirals and shaking tables settle the heavy cassiterite out of lighter waste. Flotation or magnetic separation can remove sulphides and iron-bearing minerals from the concentrate.
Is tin mined in the United States?
No. USGS reports that tin has not been mined in the United States since 1993 or smelted since 1989. Identified US resources, mostly in Alaska, are small next to those of Southeast Asia, Africa, Australia, Bolivia, Brazil and Russia.
How much does tin cost today?
The LME cash settlement was US$51,300 per tonne on 27 October 2026 (Westmetall). The 2025 annual average was about US$33,000 per tonne (USGS). Check the LME for the latest price before using any figure in a model.
Are there working tin mines in the UK?
Not yet. South Crofty in Cornwall closed in 1998, and Cornish Metals is dewatering and building surface infrastructure to restart it. The company’s 12 October 2026 update does not report production.
What is a tin concentrate?
It is the heavy fraction a mill produces once waste rock has been removed, and it is what a smelter buys. Its tin content is far higher than the ore’s, which is why the calculator above asks for a concentrate grade as well as an ore grade. EU importers must carry out supply-chain due diligence on tin, so expect to be asked for proof of origin.
Not investment advice. Company figures are as reported by each operator on the dates shown.
This page is for information only. It is not investment advice. It names no security to buy or sell. Company figures are as reported by each operator on the dates shown; check filings and speak to a licensed adviser. Confirm licence and export rules with the regulator. If you sample or pan in the field, get the licence and the landowner’s permission first, stay off other people’s claims and protected land, and never use mercury.
Farmonaut mining
Map your own project area from space
Request a quote to screen a licence area for granite contacts, alteration and structures before you sample.

Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026: Tin: pubs.usgs.gov
- USGS, Professional Paper 1802-S: Tin (Kamilli, Kimball and Carlin, 2017): pubs.usgs.gov
- USGS, Mineral Industry Surveys: Tin in December 2022: apps.usgs.gov
- Alphamin Resources, Q3 guidance and exploration update (6 October 2026): alphaminresources.com
- Alphamin Resources, record FY2025 tin production and FY2026 guidance (19 January 2026): alphaminresources.com
- Alphamin Resources, operations page: alphaminresources.com
- Metals X, half-year report to 30 June 2026 (ASX): announcements.asx.com.au
- International Tin Association, Minsur Q3 revenue surges on higher tin production (5 November 2025): internationaltin.org
- International Tin Association, Tin use in recovery cycle (30 October 2024): internationaltin.org
- Cornish Metals, operations update for the South Crofty tin project (10 June 2026): investegate.co.uk
- Westmetall, LME tin cash-settlement price (27 October 2026): westmetall.com
- European Commission, Conflict Minerals Regulation: policy.trade.ec.europa.eu
- Shanghai Metals Market, Minsur Q2 2026 production (31 July 2026): news.metal.com
- Cornish Metals, operations update for the South Crofty tin project (12 October 2026): mfn.se
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS
 Sean Mining Limited
 NTS Group (Pty) Ltd











