

Copper supply · Country comparison
Copper Mine Supply Growth: DRC vs Chile vs Peru
Copper mine supply growth in 2025 favoured the DRC: up about 7% to 3.2 million tonnes, while Chile fell about 4% and Peru about 1.5%, on USGS estimates. Here is what sits behind those numbers.
Key takeaways
- USGS estimates 2025 mine output at 5.3 Mt for Chile, 3.2 Mt for the DRC and 2.7 Mt for Peru, from a world total of 23 Mt.
- The DRC’s share is about 14% of mine output and about 10% of refined output; reported exports were 3.41 Mt in 2025 (CTCPM, via Makanisi).
- Kamoa-Kakula produced 212,146 t in the first nine months of 2026, against 290,000-310,000 t guided (Ivanhoe, October 2026).
- ICSG cut its 2026 world mine growth forecast to 1.3% in October 2026 and expects 3.1% in 2027.
In this article
- The Kakula Flood: Why the Growth Number Moved So Much
- Chile, Peru, and the DRC Side by Side
- DRC's Share of Global Copper Supply: Confirmed vs. Estimated
- What the Disruptions Did to Copper Prices
- Growth Forecasts, and What Could Break Them
- Copper Supply-Shock Calculator
- Tracking Supply Risk From Orbit
- Frequently Asked Questions
- Summary: The Numbers Worth Tracking
Between 2024 and 2025 the DRC grew its copper mine output by about 7% to 3.2 million tonnes, while Chile fell about 4% to 5.3 million tonnes and Peru slipped about 1.5% to 2.7 million tonnes, on U.S. Geological Survey estimates published in 2026. On a world total of 23 million tonnes, that gives Chile about 23%, the DRC about 14% and Peru about 12%. The DRC grew even though one of its largest mines lost a large share of its planned output to a flood.
The rest of this page shows how those numbers were built, how to separate mine output from exports, and which recovery dates matter. It is written for consultants and project teams who need a supply figure that traces back to a named source. The shares above are our own arithmetic from the USGS table, so you can repeat them, and the calculator further down lets you test a change in any country.
| Measure | Chile | DRC | Peru |
|---|---|---|---|
| Mine output 2024 (thousand t Cu) | 5,510 | 2,990 | 2,740 |
| Mine output 2025, estimate (thousand t Cu) | 5,300 | 3,200 | 2,700 |
| Change 2024 to 2025 | -3.8% | +7.0% | -1.5% |
| Share of world mine output 2025 | 23.0% | 13.9% | 11.7% |
| Refinery output 2025, estimate (thousand t Cu) | 1,700 | 2,800 | 340 |
| Reserves (thousand t Cu) | 180,000 | 80,000 | 85,000 |
| First 7 months of 2026, mine output (ICSG, preliminary) | -7% | About unchanged | +2.2% |
Table sources: USGS Mineral Commodity Summaries 2026 for tonnages, with changes and shares calculated by us; International Copper Study Group (ICSG) press release of 24 September 2026 for the last row. USGS rounds its estimates and its world total, so treat the percentages as close approximations. All tonnages are contained copper, meaning the metal inside the product and not the weight of ore or concentrate.
The Kakula Flood: Why the Growth Number Moved So Much
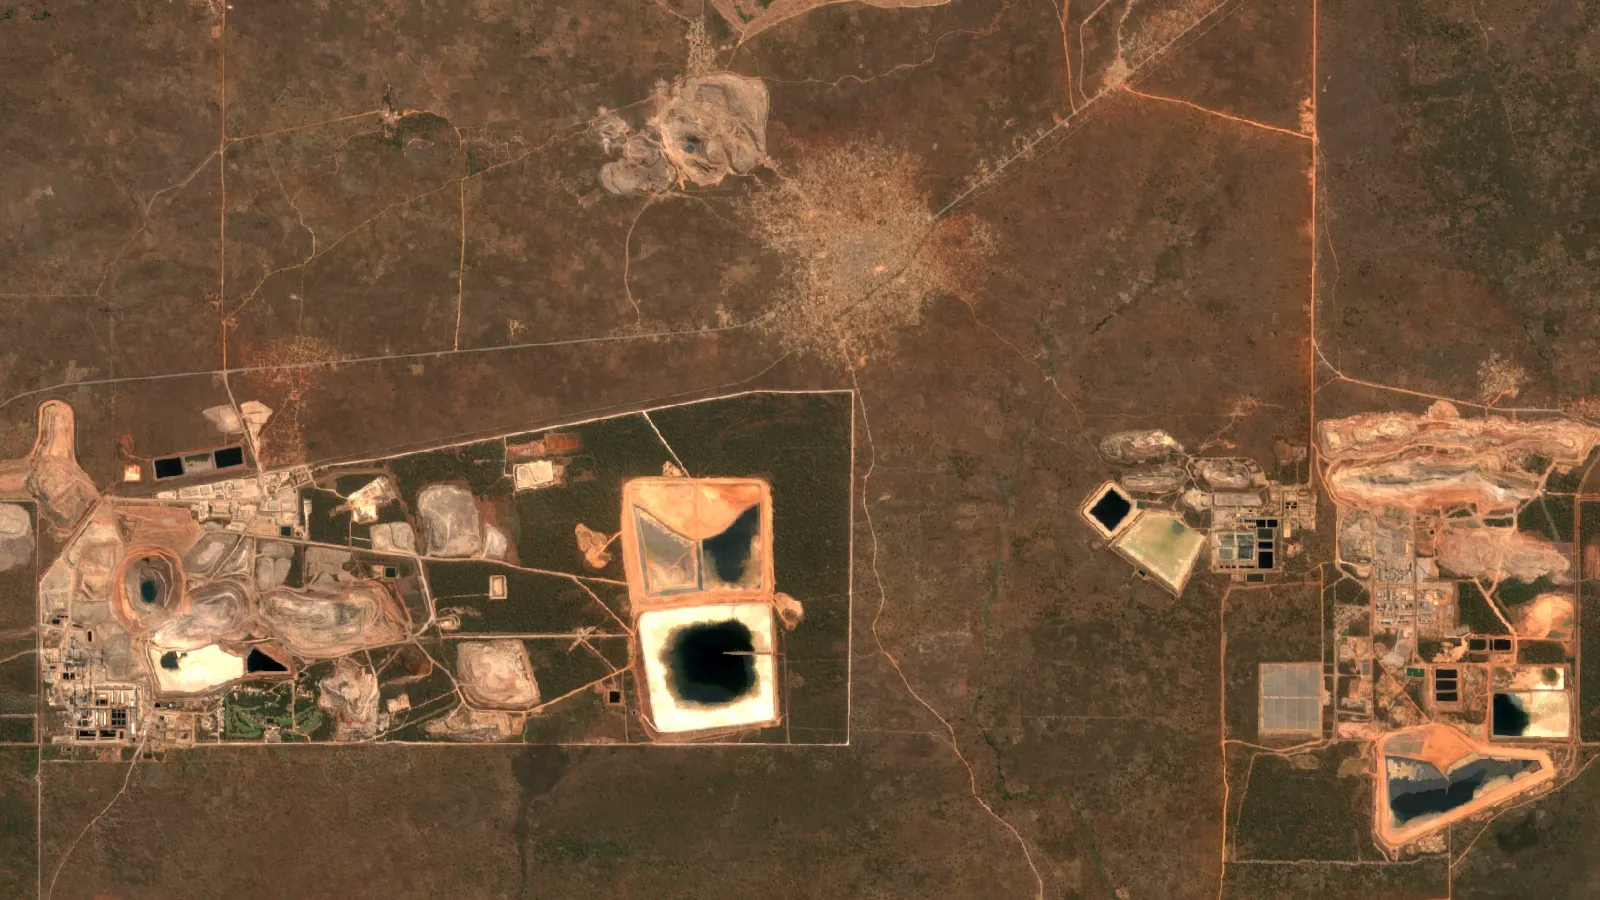
Much of the DRC supply story since 2025 traces to one project. Kamoa-Kakula is operated by Ivanhoe Mines, with Zijin Mining and the DRC government as partners. In May 2025, seismic activity and flooding closed part of the Kakula underground mine. Ivanhoe had guided to 520,000-580,000 tonnes of copper for 2025 and about 600,000 tonnes for 2026. It then cut 2025 guidance to 370,000-420,000 tonnes and dropped the 2026 target. Measured midpoint to midpoint, that was a cut of about 28%.
Chart
Kamoa-Kakula copper in concentrate by quarter
Tonnes of copper, combined Phase 1, 2 and 3 concentrators
The complex finished 2025 with 388,838 tonnes of copper in concentrate, inside the revised range. In that January 2026 release Ivanhoe still pointed to 380,000-420,000 tonnes for 2026. That number did not last. By July 2026 Ivanhoe’s 2026 range was 290,000-310,000 tonnes, measured as copper in anode, blister or saleable slag concentrate, and 380,000-420,000 tonnes had become the guidance for 2027.
The latest quarter shows a partial recovery. Ivanhoe reported 76,401 tonnes in saleable products for the third quarter of 2026, after 71,417 tonnes and 64,328 tonnes in the first two quarters. That adds up to 212,146 tonnes for nine months. The company says output is trending towards the lower end of guidance, and that the third-quarter figure includes 6,904 tonnes of older high-grade fines designated for sale. Ore milled rose to 3.49 million tonnes from 2.97 million tonnes in the second quarter, while feed grade fell to 2.22% copper from 2.39%. Grade here means the share of copper in the ore.
One project matters at world level because annual growth is small. A 150,000-tonne gap against plan is about 0.65% of a 23-million-tonne world total, and ICSG’s growth forecasts for a whole year sit in the low single digits. So one mine can decide whether a year looks strong or weak.
How to read Kamoa-Kakula’s figures
Do not compare the numbers above without checking the basis. The 2025 result is copper in concentrate. The 2026 guidance is copper in saleable products, after the on-site smelter began producing anode. A concentrate is ore upgraded at the mill, and an anode is a cast plate of nearly pure copper made at a smelter. The chart below stays on one basis, copper in concentrate, for five quarters.
Chile, Peru, and the DRC Side by Side
Three countries produced close to half of the world’s mined copper in 2025: 11.2 million of 23 million tonnes on the USGS estimates. The 2025 ranking is Chile first, the DRC second and Peru third. China, at 1.8 million tonnes, and Russia, at 1.3 million tonnes, follow well behind.
Chart
Top copper mining countries by estimated output
Thousand tonnes of contained copper, 2025 estimate, largest eight listed
Chile remains the largest producer. The U.S. International Trade Administration’s Chile guide gives 5.5 million tons for 2024 and a 24% share with no year stated, which matches the USGS figures for 2024. The newer USGS estimate puts 2025 at 5.3 million tonnes and about 23%. ICSG says Chilean mine output fell another 7% in the first seven months of 2026, mainly on lower output at El Teniente, Escondida and Spence.
The DRC has the fastest growth of the three and the widest gap between its fortunes at one mine and its national total. ICSG’s preliminary data shows why: in the first seven months of 2026, DRC concentrate output fell 30% because of Kamoa, yet electrowon output rose about 6%, which left the national total about unchanged. Electrowinning (SX-EW) recovers copper from oxide ore by leaching and plating it, without a concentrator or smelter. For a wider view of individual operations, see our ranking of copper mines in the DRC.
Peru is the steady one. USGS shows 2.74 million tonnes in 2024 and 2.7 million tonnes in 2025. ICSG reports a 2.2% rise in the first seven months of 2026, mainly from significantly higher production at Antamina, while Las Bambas, Antapaccay, Southern Peru Copper, Quellaveco, Cerro Verde and Marcobre either declined or stayed about level. The Trade Administration’s Peru guide says mining averaged about 10% of Peruvian GDP over 2021-2024 and that major projects worth $54.6 billion await development. That guide also calls Peru the world’s second-largest copper producer, which no longer matches the USGS table.
Reserves tell a different story from output. Reserves are the part of a deposit that can be mined at a profit today. USGS lists 180 million tonnes for Chile, 85 million for Peru and 80 million for the DRC, out of 980 million worldwide. So the DRC produces more copper than Peru from a slightly smaller reserve base. For more on where those deposits sit, see where copper is found, and for the operators behind the tonnes, our list of the largest copper mining companies.
▶ How copper moves from a large Chilean open pit into electric vehicles. · 6:03
DRC’s Share of Global Copper Supply: Confirmed vs. Estimated
The DRC’s share of world copper mine output was about 13.9% in 2025 (3.2 million of 23 million tonnes), up from about 13.0% in 2024, on USGS estimates. That is the cleanest answer, because both numbers come from one table.
The export figure is higher and comes from a different source. Makanisi, citing the DRC mines ministry’s statistics unit (CTCPM), reports copper metal exports of 3,407,134 tonnes in 2025, against 3,100,234 tonnes in 2024 and 1,797,836 tonnes in 2021. Cathode, the finished refined product, made up 2,847,442 tonnes, or 84%. Dividing those exports by the USGS world mine total gives about 14.8%. That is a rough comparison only, because it sets one government’s export count against another agency’s production estimate.
Three reasons these figures can differ:
- Different counters. USGS publishes a rounded estimate. The ministry unit counts reported export shipments.
- Timing. Metal shipped in one year may have been mined in the previous one, and stocks can build at site. Kamoa-Kakula alone held about 43,000 tonnes of copper in inventory at the end of the third quarter of 2026.
- Product mix. Export totals combine cathode, smelted metal and contained copper in other products, so check what each line includes.
Refined output is a third measure. USGS puts DRC refinery production at 2.8 million tonnes in 2025, about 9.7% of a 29-million-tonne world total, and second only to China among the countries listed. Those refined tonnes fit with the high cathode share of exports. A report that quotes “the DRC’s share” could therefore mean about 10%, 14% or 15%, depending on the measure, so ask which one it uses.
To update the number yourself, open the copper chapter of the USGS Mineral Commodity Summaries, which is published each year. Take the Congo (Kinshasa) tonnage and divide it by the world total on the same table. For in-year direction, read ICSG’s monthly press releases, which give country changes on a preliminary basis.

▶ A longer look at the DRC’s copper deposits in the Central African Copperbelt. · 13:34
What the Disruptions Did to Copper Prices
Copper averaged 421.6 cents per pound on COMEX in 2024, and USGS estimates about 480 cents for 2025. On 5 November 2026, Trading Economics showed copper at US$6.37 per pound, down 3.40% over the past month and 28.54% higher than a year earlier, based on a contract for difference that tracks the benchmark. The same page gives an all-time high of US$6.85 in September 2026. On the London Metal Exchange, the International Copper Association Australia reported a three-month contract close of US$14,436 per tonne on 14 October 2026, with an intraday record of US$14,875 on 10 September.
Chart
Who gained and lost mine output
Thousand tonnes of contained copper, selected countries
Lost mine tonnes are one driver among several. The World Bank’s April 2026 commodity outlook expected copper to reach a record annual high in 2026, up about 20%, on resilient demand and persistent supply constraints. The copper association’s weekly note adds another sign of tight concentrate: the 2026 benchmark for treatment and refining charges, the fees smelters earn for processing concentrate, settled at zero. For a longer view of price swings, see our copper price volatility analysis.
The picture is less simple at the refined level. ICSG’s preliminary balance shows a surplus of about 32,000 tonnes of refined copper in the first seven months of 2026, and its October forecast also shows a small surplus for the year. So mine supply and refined supply can tell different stories in the same year. When concentrate is short, smelters suffer first, while SX-EW producers and scrap-based refiners can keep growing.
Chile’s El Teniente and Indonesia’s Grasberg
The DRC was not the only source of lost tonnes. A fatal accident at Codelco’s El Teniente division on 31 July 2025 cut that division’s output from 356,400 tonnes in 2024 to 310,100 tonnes in 2025, according to Codelco’s 2025 financial report. The effects continued: Codelco’s own first-half 2026 production fell 11% to 564,000 tonnes, with El Teniente down 27%.
Indonesia took the largest country fall in the USGS table, from 1.01 million tonnes in 2024 to 710,000 tonnes in 2025, after a mud rush at Grasberg in September 2025. Freeport-McMoRan’s July 2026 release expected Grasberg operator PTFI’s overall rates at about 65% in the second half of 2026, 80% by mid-2027 and near full capacity by the end of 2027.
The USGS estimates do not show every country falling. Russia rose from 1.02 to 1.3 million tonnes and Zambia from 823,000 to 940,000 tonnes between 2024 and 2025. Those gains are a reason to keep the whole table in view rather than only the top three.
Growth Forecasts, and What Could Break Them
ICSG has lowered its 2026 world mine growth forecast twice. It was 2.3% in October 2025, then 1.6% in April 2026, then 1.3% in October 2026, with the latest cut tied to Chile, China and Indonesia. ICSG’s October forecast expects 3.1% growth in 2027 as Indonesia and the DRC recover, Chile and Zambia improve, and new capacity ramps up.
Chart
ICSG’s forecast for 2026 world mine growth
Percent growth, by forecast date
That forecast already looks demanding when set against actual data. ICSG’s September 2026 release shows world mine output down 1% in the first seven months of 2026. Reaching 1.3% growth for the full year would need a strong finish.
On the refined side, ICSG forecasts a surplus of 104,000 tonnes for 2026 and 368,000 tonnes for 2027, as refined output growth moves from 0.4% to 3.4% and usage growth from 1.5% to 2.5%. ICSG itself warns that actual balances have differed from its forecasts because of unforeseen events, and that its figures leave out unreported Chinese stock changes.
Five things to check when you update these numbers:
- Kamoa-Kakula’s fourth-quarter result against the 290,000-310,000 tonne range, and any change to the 380,000-420,000 tonne range for 2027.
- El Teniente and other Codelco divisions. Codelco’s half-year figures show how far the recovery has gone.
- Grasberg’s ramp-up against Freeport-McMoRan’s 65% and 80% operating rate marks.
- DRC export policy. The Trade Administration’s DRC guide describes a four-month cobalt export suspension from February 2025 and quotas planned from October 2025. Those measures concern cobalt, but a consultant modelling DRC copper should note the precedent.
- Peru’s community disputes. The Peru guide describes persistent social unrest around mining, including disputes over artisanal miners’ formalization.
Copper Supply-Shock Calculator
Enter any country’s output, the world total and a percentage change. The calculator shows the new share, the effect on world supply, and the value of the tonnes gained or lost at a price you choose. It is the same arithmetic behind the shares on this page. It holds the rest of the world steady, so it leaves out offsets from other mines, stocks and scrap.
Calculator
How far does one country’s change move world supply?
Enter one country’s output, the world total and a percentage change.
- Share before the change: 13.9%
- Tonnes gained or lost (thousand t): -160.0
- Change in world supply: -0.70 %
- Value of that copper, US$: -$2,240,000,000
Defaults use USGS 2025 estimates for the DRC and the world (Mineral Commodity Summaries 2026); the change and the price are examples, not forecasts. Holds the rest of the world steady. Price is an input: use today’s price.
Tracking Supply Risk From Orbit
Consultants who screen copper ground usually start with public geology and national statistics, then narrow the area with imagery before paying for field work. Farmonaut’s satellite-based mineral detection screens a licence boundary for exploration targets ahead of drilling. Results are targets, not a resource estimate. Ground work and drilling are still needed to confirm them.
Supply events like those above also show why a project review should cover more than geology. Our note on mining risk management covers geotechnical, price and policy exposure, and although it is written around gold, the same categories apply to copper. To discuss a specific area, use the mining query form or contact us directly.
▶ What AI and satellite data can and cannot do in mineral exploration. · 4:37
Frequently Asked Questions
What percentage of global copper supply comes from the DRC?
About 14% of world mine output in 2025, based on the USGS estimates of 3.2 million tonnes out of 23 million tonnes. Its share of refined output is lower, at about 10%.
How much copper does the DRC export?
The DRC mines ministry’s statistics unit reported 3,407,134 tonnes of copper metal exports in 2025, up from 3,100,234 tonnes in 2024, as cited by Makanisi. Cathode made up 84% of the total.
Which country is the largest producer of copper in the world?
Chile, with about 5.3 million tonnes in 2025, or about 23% of the world total, on USGS estimates. The DRC is second and Peru third.
How much copper is mined each year?
USGS estimates about 23 million tonnes of contained copper in both 2024 and 2025. Refineries produced about 29 million tonnes in 2025, because refined output also includes copper from scrap.
How much copper is left in the world?
USGS lists reserves of 980 million tonnes. Its most recent global assessment, as of 2015, showed 1.5 billion tonnes of identified resources and an estimated 3.5 billion tonnes undiscovered. Reserves are economic today, while resources are a much wider category.
Is copper mine supply growing or falling?
ICSG’s preliminary data shows world mine output down 1% in the first seven months of 2026, while its October 2026 forecast is for 1.3% growth in the full year and 3.1% in 2027.
What is the copper supply forecast?
ICSG expects world mine output to grow 3.1% and refined output 3.4% in 2027, with a refined surplus of 368,000 tonnes. It warns that actual balances can differ from these forecasts.
What disrupted copper supply in Chile, the DRC and Indonesia?
Three site events stand out: the May 2025 seismic activity and flooding at Kakula, the July 2025 accident at El Teniente, and the September 2025 mud rush at Grasberg. All three still affected output in 2026.
Why did Kamoa-Kakula’s guidance change so often?
Ivanhoe reset its plans as it assessed the damage and rebuilt mining rates across the complex. Its measure also moved from copper in concentrate to copper in saleable products, so older and newer ranges are not directly comparable.
Does the DRC have a copper export quota?
The U.S. Trade Administration’s guide describes the suspension and quotas for cobalt, not copper. Check current DRC government notices before relying on this for a contract or a model.
Summary: The Numbers Worth Tracking
- Chile: 5.3 million tonnes in 2025, about 23% of world mine output, down about 4% on 2024 (USGS).
- DRC: 3.2 million tonnes in 2025, about 14%, up about 7% (USGS); exports of 3.41 million tonnes (CTCPM, via Makanisi).
- Peru: 2.7 million tonnes in 2025, about 12%, down about 1.5% (USGS); up 2.2% in January-July 2026 (ICSG).
- Kamoa-Kakula: 212,146 tonnes in the first nine months of 2026, against 290,000-310,000 tonnes guided for the year (Ivanhoe).
- World mine growth: 1.3% forecast for 2026 and 3.1% for 2027, with output down 1% in the first seven months of 2026 (ICSG).
- Price: US$6.37 per pound on 5 November 2026 (Trading Economics). Use today’s price in any model.
Over the period the DRC gained share and Chile lost it, while Peru held close to level. The next numbers to watch are the fourth-quarter reports from Kamoa-Kakula and Grasberg and the next USGS table.
This page is for information only. It is not investment advice.
Farmonaut mining
Map your mining site from space
Send a licence boundary and get satellite-screened exploration targets to review before field work.

Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026: Copper: pubs.usgs.gov
- ICSG, Monthly press release, 24 September 2026: icsg.org
- ICSG, Copper Market Forecast 2026/2027, 23 April 2026: icsg.org
- Canadian Mining Journal, ICSG forecast report, 14 October 2026: canadianminingjournal.com
- Ivanhoe Mines, Q3 2026 production results, 8 October 2026: ivanhoemines.com
- Ivanhoe Mines, Q2 2026 financial results, 29 July 2026: tradingview.com
- Ivanhoe Mines, 2025 production results, 15 January 2026: newsfilecorp.com
- Miningmx, Ivanhoe cuts guidance, 12 June 2025: miningmx.com
- Makanisi, DRC copper production and exports in 2025: makanisi.org
- U.S. International Trade Administration, Chile mining guide: trade.gov
- U.S. International Trade Administration, Peru mining guide: trade.gov
- U.S. International Trade Administration, DRC mining guide: trade.gov
- Codelco, Operational and financial report 2025: codelco.com
- Codelco, First-half 2026 results: codelco.com
- Freeport-McMoRan, Q2 2026 earnings release: s22.q4cdn.com
- Trading Economics, Copper, 5 November 2026: tradingeconomics.com
- International Copper Association Australia, Copper Weekly Brief, 15 October 2026: copper.com.au
- World Bank Blogs, Metal prices surge as supply pressures intensify: blogs.worldbank.org
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd

 Licence holder · Nigeria · Gold + lithium










