

DRC copper · Ranked mine list
Top 10 Copper Mines in DRC Ranked by Output
Tenke Fungurume, Kamoa-Kakula and Sicomines lead the DRC’s copper mines, and ten mines produced 63% of the country’s 3.49 million tonnes in 2025. This page gives owners, output, cobalt quotas, mining code terms and a royalty calculator.
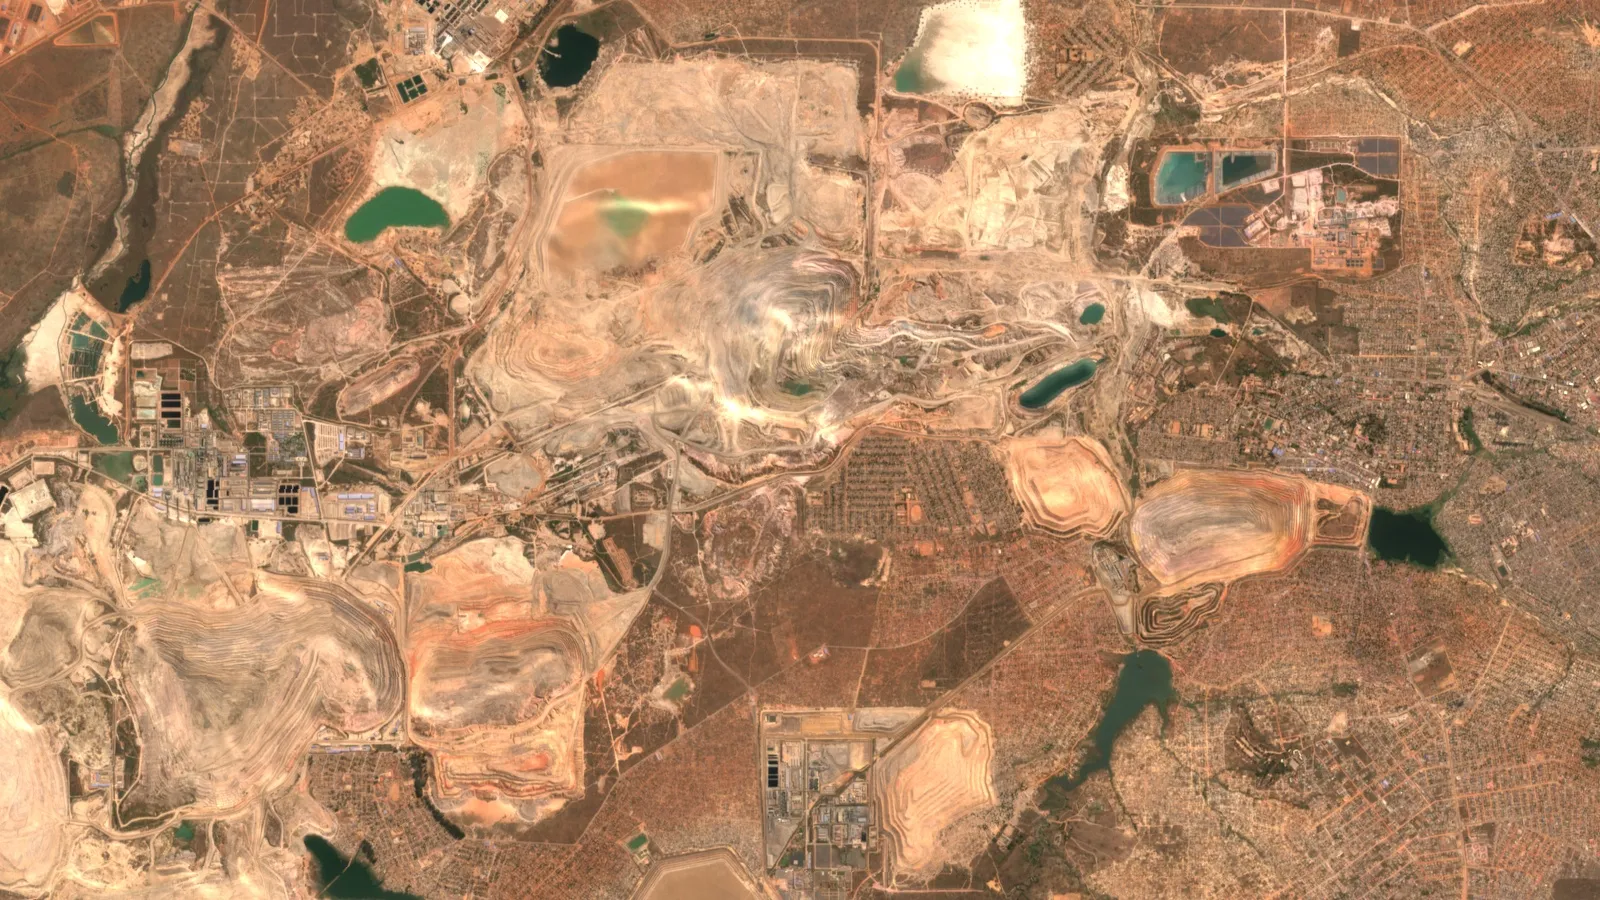
Key takeaways
- The DRC mined an estimated 3.2 million tonnes of copper in 2025, second to Chile, and holds 80 million tonnes of reserves, about 8% of the world total (USGS, 2026).
- Tenke Fungurume (CMOC 80%) is the largest mine at 509,352 t in 2025; Kamoa-Kakula (Ivanhoe 39.6%, Zijin 39.6%, DRC government 20%) is second at 425,802 t (CTCPM ministry bulletin, 2025).
- The ten mines in the ranking produced about 2.2 million tonnes, 63% of the ministry’s national total of 3,485,269 t (CTCPM, 2025).
- Cobalt is a by-product: the DRC mined about 74% of world cobalt in 2025, and exports run under an ARECOMS quota of 87,000 t plus a 9,600 t strategic quota for 2026 (USGS, 2026; Cobalt Institute, May 2026).
- Mining code royalties are 3.5% on copper and 10% on cobalt, charged on gross commercial value (EY, 2018; Law.asia).
In this article
- Top 10 copper mines in DRC ranked by latest full-year output
- Mine-by-mine notes: owners, output and what changed
- How much copper does the DRC produce, and what are its reserves?
- Cobalt by-product: why it matters for copper mines in the DRC
- Export quotas: how operators responded
- DRC mining rules that affect a copper licence
- Royalty on copper and cobalt: a worked example
- Where the copper is: geology of the Central African Copperbelt
- What to watch next in DRC copper
- Frequently asked questions
Short answer. The largest copper mines in the Democratic Republic of the Congo (DRC) are Tenke Fungurume, Kamoa-Kakula, Sicomines, Kisanfu, Kolwezi (the Musonoi mine) and Kamoto. The Ministry of Mines puts national copper production at 3,485,269 tonnes for 2025, and these six mines produced about 1.8 million tonnes of it, roughly half (CTCPM mining statistics bulletin, 2025). The US Geological Survey estimates that the country mined 3.2 million tonnes in 2025, second only to Chile, and holds 80 million tonnes of copper in reserves (USGS Mineral Commodity Summaries, 2026).
This page ranks the ten biggest copper mines in the DRC with their current owners, latest output and recent changes. It then covers the cobalt that comes out of the same ore, the export quotas that now shape what these mines sell, the mining code terms that apply to a licence holder, and a royalty calculator. A few terms first. Concentrate is crushed and upgraded ore that is shipped to a smelter. Blister and anode are smelter products that go on to final refining. Cathode is refined copper sheet, the form traders buy. Cobalt hydroxide is an intermediate cobalt product made at the same plants that make copper cathode.
Top 10 copper mines in DRC ranked by latest full-year output
The table is ranked by 2025 copper production in the Ministry of Mines bulletin (Table 9), published by the ministry’s technical cell for mining coordination and planning (CTCPM) in 2026. It is the only source that covers every operator on one basis. Company reports use their own bases, for example copper in concentrate or saleable copper, so they do not always match the ministry figure; both are shown. Ownership comes from the operators’ own pages and filings. The ten mines in the table produced about 2.2 million tonnes in 2025, 63% of the ministry’s national total.
Chart
Copper output by operator in 2025, as each company reports it
Thousand tonnes, 100% basis; the bases differ by company (see notes)
| Rank | Mine or operator | Province | Owners | 2025 copper, ministry (t) | Company-reported detail |
|---|---|---|---|---|---|
| 1 | Tenke Fungurume (TFM) | Lualaba | CMOC 80%; Gécamines is the state partner | 509,352 | CMOC reports TFM and Kisanfu together: 741,100 t copper and 117,500 t cobalt in 2025 |
| 2 | Kamoa-Kakula | Lualaba | Ivanhoe Mines 39.6%, Zijin Mining 39.6%, Crystal River 0.8%, DRC government 20% | 425,802 | 388,838 t copper in concentrate; 2026 guidance 290,000 to 310,000 t saleable copper |
| 3 | Sicomines | Lualaba (Kolwezi) | Chinese consortium including China Railway Group and Sinohydro, with Gécamines | 257,926 | Rated capacity 253,500 t of cathode a year (China Railway Engineering Group) |
| 4 | Kisanfu (KFM; the bulletin row is labelled CMOC) | Lualaba | CMOC 71.25% | 228,107 | Phase II adds 100,000 t of annual copper capacity, expected in 2027 |
| 5 | Kolwezi (COMMUS, Musonoi) | Lualaba | Zijin Mining 67%, after a 5% transfer to the DRC government in early 2024 | 191,801 | Zijin lists 118,000 t of copper for 2025 on a 100% basis |
| 6 | Kamoto (KCC) | Lualaba | Glencore 70%, Gécamines 25%, DRC State 5% | 188,710 | 106,400 t copper in the first half of 2026 (Glencore, both KCC and Mutanda 138,400 t) |
| 7 | Kai Peng Mining | Haut-Katanga | Shenzhen Yite Holding | 110,345 | Exported 110,344 t of cathode |
| 8 | Metalkol RTR | Lualaba | Eurasian Resources Group (ERG) | 98,815 | Reprocesses tailings into cathode and cobalt hydroxide |
| 9 | BMS | Lualaba | Boss Mining (ERG and Gécamines joint venture), if the bulletin’s BMS is Boss Mining | 96,036 | Exported 96,036 t of cathode |
| 10 | Deziwa (Somidez) | Lualaba | China Nonferrous Metal Mining Corporation with Gécamines | 89,037 | Exported 105,110 t of cathode |
Two well-known mines fall just outside the list. Glencore’s Mutanda produced 49,644 t and MMG’s Kinsevere 48,951 t in the ministry’s data. Both are covered below. The table shows output, not quality. Ivanhoe describes Kamoa-Kakula as the world’s highest-grade major copper mine, and its mill feed ran at 2.22% to 2.47% copper across the last five quarters it reported, which means less rock moved per tonne of metal.
Mine-by-mine notes: owners, output and what changed
Tenke Fungurume and Kisanfu: the CMOC mines
China’s CMOC Group runs the two largest copper-cobalt mines in the country. It owns 80% of Tenke Fungurume (TFM) and 71.25% of Kisanfu (KFM), and reports that the two together produced 741,100 t of copper and 117,500 t of cobalt in 2025 (CMOC, DRC operations page). TFM has five production lines with capacity above 450,000 t of copper a year, and KFM has one line above 200,000 t. CMOC lists TFM resources of 29.57 million tonnes of copper at 2.25% and Kisanfu resources of 4.01 million tonnes at 1.79%. In the first half of 2026 the group produced 387,961 t of copper, up 9.73% on the same period a year earlier (CMOC, first-half results). For more on the land and water around the mine, see our profile of the Tenke Fungurume mine.
State miner Gécamines holds a right to buy part of TFM’s output. In January 2026 it announced a plan to ship 100,000 t of TFM copper to the United States under an agreement between the two governments (Mongabay).
Kamoa-Kakula: the highest-grade large copper mine
Kamoa-Kakula is a joint venture between Ivanhoe Mines (39.6%), Zijin Mining (39.6%), Crystal River Global (0.8%) and the DRC government (20%). It lies about 25 km west of Kolwezi (Ivanhoe Mines). It produced 388,838 t of copper in concentrate in 2025, inside its revised guidance of 380,000 to 420,000 t, after flooding at the Kakula underground mine forced a dewatering programme (Ivanhoe, 2025 production results).
The third quarter of 2026 was the best of the year so far. Saleable copper reached 76,401 t, up 19% on the 64,328 t of the second quarter, and Ivanhoe kept its 2026 range of 290,000 to 310,000 t of saleable copper while saying output is trending toward the low end (Ivanhoe, third-quarter 2026 results). The January guidance of 380,000 to 420,000 t counted copper in concentrate, so the two ranges are on different bases. The complex now has its own smelter, designed for 500,000 t a year, which made its first anode in December 2025. In the third quarter it ran at about 60% of design capacity and produced a record 118,638 t of sulphuric acid, a by-product sold to other mines.
Sicomines: the copper-cobalt mine built on an infrastructure deal
The Sino-Congolaise des Mines (Sicomines) is a copper-cobalt mine at Kolwezi on 11.05 square kilometres. China Railway Engineering Group, one of its Chinese partners, reports 250 million tonnes of ore at 3.47% copper and 0.215% cobalt, and a capacity of 253,500 t of cathode and 5,180 t of cobalt in crude hydroxide a year (China Railway Engineering Group). The ministry bulletin shows 257,926 t of copper produced and 230,464 t of cathode exported in 2025, which makes it the third-largest copper mine in the country.
Sicomines was set up as a minerals-for-infrastructure deal. In March 2024 the DRC and its Chinese partners, including Sinohydro and China Railway Group, signed a revised agreement that raised the infrastructure commitment from US$3 billion to up to US$7 billion and said the Chinese partners will pay 1.2% in royalties to the state each year, with the same shareholding structure (Reuters via Mining.com, March 2024).
Kolwezi (Musonoi): Zijin’s second Congolese mine
Zijin Mining operates the Kolwezi copper mine through its COMMUS subsidiary. It owns 67% after transferring 5% to the DRC government in early 2024. The mine is an open pit with flotation and hydrometallurgy (acid leaching) plants, with capacity above 120,000 t of copper and 2,000 t of cobalt a year and resources of 1.1261 million tonnes of copper at 3.38%. Zijin lists 2025 production of 118,000 t of copper and 21 t of cobalt on a 100% basis (Zijin Mining, Kolwezi). The ministry bulletin records a higher copper figure for COMMUS, 191,801 t, so check which basis a source uses before you compare mines. On Zijin’s own figure Kolwezi would rank sixth, behind Kamoto, but it stays in the top ten either way.
Kamoto and Mutanda: the Glencore mines
Kamoto Copper Company (KCC) is owned 70% by Glencore, 25% by Gécamines and 5% by the DRC State (KCC). Glencore also operates Mutanda, which restarted mining in 2025. The two together produced 247,800 t of own-sourced copper in 2025, up 10%, and 33,500 t of cobalt, down 5% (Glencore, full-year 2025 production report). In the first half of 2026 they produced 138,400 t of copper, 66% more than a year earlier, of which KCC made 106,400 t and Mutanda 32,000 t (Glencore, half-year 2026 production report).
In February 2026 Glencore signed a non-binding agreement to sell a 40% stake in its DRC mines to the Orion Critical Mineral Consortium, a US-backed buyer (Mining.com).
The next tier: Kai Peng, Metalkol, BMS, Deziwa, Kinsevere and Chemaf
Four operators produced between 89,000 and 110,000 t in 2025 (ranks 7 to 10 above). Kai Peng Mining belongs to Shenzhen Yite Holding and runs an electrolytic copper plant in the Likasi Industrial Park (Yite Holding). Metalkol RTR, owned by ERG, reprocesses old tailings near Kolwezi, and ERG says S&P Global described it as the world’s most cost-effective primary copper mine (ERG Africa). Deziwa is run by Somidez, a partnership between China Nonferrous Metal Mining Corporation and Gécamines, according to the Congolese outlet Makanisi, which reads the same ministry bulletin.
MMG’s Kinsevere in Haut-Katanga made 52,791 t of copper cathode in 2025, up 18%, and MMG guides to 65,000 to 75,000 t for 2026 while reporting that DRC cobalt sales limits have kept its cobalt plant on care and maintenance (MMG, fourth-quarter 2025 production report). Chemaf, which owns the Mutoshi and Etoile projects, was approved for acquisition by Virtus Minerals on 13 March 2026 (Virtus Minerals). The approval was issued under the Mining Code, which requires state authorisation when a licence-holding company changes hands.
How much copper does the DRC produce, and what are its reserves?
USGS estimates the DRC mined 3.2 million tonnes of copper in 2025, up from 2.99 million in 2024, out of a world total of 23 million tonnes, so the country supplies about 14% of the world’s mined copper. Only Chile, at 5.3 million tonnes, mined more; Peru was third at 2.7 million (USGS, 2026). The ministry’s own count for 2025, 3.49 million tonnes, is close to that estimate.
Chart
DRC copper metal exports have nearly doubled in four years
Thousand tonnes of copper metal exported, 2021 to 2025
Reserves tell a different story. USGS puts DRC copper reserves at 80 million tonnes, behind Chile (180 million), Australia (100 million) and Peru (85 million), level with Russia, and about 8% of the world’s 980 million tonnes. The DRC ranks second for production but only tied fourth for reserves, which is why new discoveries and expansions matter to its output. For how these figures compare with other producers, see our guide to the largest producer of copper.
Growth has been fast. The ministry bulletin shows copper metal exports rising from 1.80 million tonnes in 2021 to 3.40 million in 2025, nearly doubling in four years. Cathode alone was 2,847,442 t in 2025, of which Lualaba province exported 2,099,554 t and Haut-Katanga 747,888 t. Every tonne of cathode exported in 2025 came from these two provinces, which sit on the Central African Copperbelt, the arc of sediment-hosted copper deposits that runs from the DRC into Zambia. Copper mining in the Congo is therefore a story of two provinces, and within them of a few districts around Kolwezi, Fungurume and Likasi.
The copper price drives how much of this ore is worth mining. Three-month copper on the London Metal Exchange traded at US$14,487.50 a tonne at 1700 GMT on 27 October 2026 (Reuters via Mining.com), and the cash contract traded US$199.50 a tonne above the three-month price, a sign of tight near-term supply. Prices change daily; check the LME before you use any figure in a deal.
▶ Farmonaut explainer on how copper starts as a mine, using Chile as the example. · 6:03
Cobalt by-product: why it matters for copper mines in the DRC
Cobalt is mined in the DRC as a by-product of copper. USGS estimates that the country produced 230,000 t of cobalt in 2025 out of a world total of 310,000 t, about 74%, and holds 6 million tonnes of the world’s 12 million tonnes of reserves (USGS, 2026). The Cobalt Institute puts the DRC’s share of mined supply at 73% in 2025, with Indonesia, where cobalt comes from nickel, at 14% (Cobalt Institute, Cobalt Market Report, May 2026).
Chart
Cobalt exports fell sharply in 2025 as the export ban took hold
Thousand tonnes of cobalt exported (bulletin label: cobalt métal)
The cobalt-to-copper ratio varies by mine. The Cobalt Institute says a typical DRC asset has about ten tonnes of copper for every tonne of cobalt, while Kisanfu is closer to 2.6 to 1, and estimates that Kisanfu made more than 80,000 t of cobalt in hydroxide in 2025. That ratio sets how much a quota or a cobalt price move affects a mine’s revenue. Our guide to cobalt mines in the world covers the other producing countries.
Export quotas: how operators responded
On 22 February 2025 the DRC banned all cobalt exports after prices fell to a historic low; hydroxide delivered to China was as low as US$5.60 a pound in mid-February. The ban was extended in June, then replaced in October 2025 by a quota system run by the regulator ARECOMS and set to run until at least the end of 2027. The quota for 2026 is 87,000 t of cobalt, 7,250 t a month, plus a strategic quota of 9,600 t and the 18,125 t allocated for the last quarter of 2025, which ARECOMS let producers roll forward. Quotas are based on average production in the previous three years, and exporters prepay a 10% royalty on their maximum quota (Cobalt Institute, May 2026). Cobalt hydroxide prices rose by more than 300% during 2025 as supply tightened.
Chart
Glencore’s DRC mines made more copper and less cobalt
KCC and Mutanda combined, thousand tonnes, first half of each year
Operators responded by moving effort toward copper. Glencore says it will prioritise copper over cobalt while the quotas are in force, stores cobalt above its allocation inside the country, and expects 2026 quotas of 16,100 t at KCC and 6,700 t at Mutanda including carry-over from 2025 (Glencore, full-year 2025 report). In the first half of 2026 its DRC cobalt output fell 51% to 8,700 t while copper rose 66%. Cobalt metal prices rose from about US$24.25 a pound at the start of 2026 to about US$25.60 by the end of June (Glencore, half-year report 2026).
DRC mining rules that affect a copper licence
If you hold or plan to buy a licence, these are the terms that matter most. They come from the 2018 revision of the Mining Code, summarised by EY, and from the quota rules above.
- Exploration licence: granted for five years and renewable once, for all minerals.
- Exploitation licence: an initial term of up to 25 years, renewable in periods of no more than 15 years.
- State shareholding: the state takes 10% non-dilutable shares when mining rights are granted or transferred, plus a further 5% on each renewal (Law.asia). Several large mines go further, as the ownership table above shows.
- Windfall tax: a special tax of 50% applies to windfall profit.
- Share transfers: a takeover of a company holding an exploitation licence needs prior state authorisation, which is why Chemaf’s sale went to the mines ministry.
- Stability clause: reduced to five years.
- Cobalt exports: only companies with an ARECOMS quota can export, and the regulator can withdraw a quota for a producer that processes third-party material, transfers its quota or does not export its allocation.
The foreign-owned mines in the table, from Kamoa-Kakula to KCC, hold their licences through Congolese companies in which the state or Gécamines has a stake. Rules change, and ownership approvals are decided case by case, so use a Congolese mining lawyer before you sign anything.
▶ Farmonaut explainer on small-scale mining licences for foreigners in Africa. · 5:16
Royalty on copper and cobalt: a worked example
The 2018 Mining Code charges a royalty on gross commercial value: 3.5% for base metals such as copper, and 10% for strategic substances, a class that includes cobalt, germanium and coltan (EY; Law.asia). The calculator below applies those rates to a copper-cobalt mine. Enter your own tonnes and prices. The payable share lets you test a cobalt hydroxide sale at less than the metal price.
Calculator
What royalty would a copper-cobalt sale pay in the DRC?
Enter your own tonnes, prices and rates.
- Copper sales value (US$): $1,450,000,000
- Cobalt sales value, payable basis (US$): $275,577,500
- Royalty on copper (US$): $50,750,000
- Royalty on cobalt (US$): $27,557,750
- Total royalty as share of sales: 4.5%
Example values only, not a forecast. The 3.5% rate for copper and 10% for cobalt follow the 2018 Mining Code as summarised by EY (2018) and Law.asia, charged on gross commercial value; confirm the rate in your own licence. One tonne is 2,204.62 lb, fixed in the formula. Prices and the cobalt payable share are examples: use today’s price. The result excludes the ARECOMS quota prepayment, other taxes and contract terms.
Where the copper is: geology of the Central African Copperbelt
Most DRC copper comes from sediment-hosted stratiform deposits, layers of copper minerals that formed in ancient sedimentary rock and lie flat or gently dipping. USGS lists sediment-hosted stratiform copper deposits in the DRC and Zambia among the main hosts of the world’s cobalt resources, alongside nickel laterites and magmatic nickel-copper sulphide deposits. Ivanhoe describes Kamoa-Kakula as a very large, near-surface, flat-lying stratiform deposit. Zijin’s Kolwezi is an open pit with flotation and hydrometallurgy plants, while Kakula is an underground mine.
For a licence holder, the practical question is where within the licence to drill first. Satellite data can screen a licence for alteration and surface signatures before any drilling. Farmonaut turns a licence boundary (KML, KMZ or polygon) into a satellite mineral-detection report in 5 to 20 business days; the result is a set of exploration targets, not a resource estimate. If you hold ground in the Copperbelt, you can send a licence polygon through the mining query form, read how satellite-based mineral detection works, or contact us. For other regions see where copper is found and our guide to copper deposits.
▶ Farmonaut explainer: remote sensing for mining in three minutes. · 2:01
What to watch next in DRC copper
- Kamoa-Kakula smelter ramp-up: it ran at about 60% of its 500,000 t design capacity in the third quarter of 2026, and Ivanhoe set 2027 guidance for the complex at 500,000 to 540,000 t of copper.
- Kisanfu Phase II: CMOC expects 100,000 t a year of added copper capacity in 2027.
- Cobalt quotas: ARECOMS has said it may adjust quotas each quarter, and the current system runs to the end of 2027.
- Ownership shifts: the Glencore-Orion agreement was announced in February 2026 as non-binding, and Chemaf’s change of control was approved in March 2026.
- Power and acid: Kamoa-Kakula’s 60 MW hybrid solar plant ramped up in September 2026 and cut on-site diesel generator use by 40%, and its sulphuric acid sold at about US$900 a tonne on average contract prices in the third quarter.
These are dated company statements, not forecasts of our own. Check each operator’s latest quarterly report before you rely on a figure.
For tin, tantalum, gold and diamonds beyond the Copperbelt, see the DRC minerals map.
For the DRC’s coltan output and supply rules, see tantalum mines.
Frequently asked questions
How many copper mines are there in the DRC?
The ministry bulletin for 2025 lists more than 50 operators with copper output, from industrial mines to small cathode producers. Ten of them produced about 63% of the national total, and six produced about half.
Which is the largest copper mine in the DRC?
Tenke Fungurume, operated by CMOC, with 509,352 t of copper in the ministry’s 2025 data. CMOC owns 80% of it. Kamoa-Kakula is second with 425,802 t in the ministry data; Ivanhoe reports 388,838 t of copper in concentrate.
Who owns Kamoa-Kakula?
Ivanhoe Mines owns 39.6%, Zijin Mining 39.6%, Crystal River Global 0.8% and the DRC government 20% (Ivanhoe Mines, 2026).
What is the Sicomines copper-cobalt mine?
Sicomines is a joint venture at Kolwezi between Chinese state-owned groups, including China Railway Group and Sinohydro, and the Congolese side. It was created as a minerals-for-infrastructure deal and revised in March 2024 to raise the infrastructure commitment to up to US$7 billion. It has a rated capacity of 253,500 t of cathode a year and produced 257,926 t of copper in 2025 in the ministry’s data.
How much copper does the DRC have in reserves?
USGS puts DRC copper reserves at 80 million tonnes, about 8% of the world’s 980 million tonnes (USGS, 2026). Reserves are the part of a deposit that can be mined at a profit with current technology and prices, so they move with the copper price and new drilling.
Is the DRC the second-largest copper producer?
Yes. USGS estimates 3.2 million tonnes in 2025, behind Chile’s 5.3 million and ahead of Peru’s 2.7 million (USGS, 2026).
Where is copper mined in the Congo?
All the cathode the DRC exported in 2025 came from Lualaba and Haut-Katanga provinces in the south-east, on the Central African Copperbelt. Lualaba exported 2,099,554 t of copper cathode in 2025 and Haut-Katanga 747,888 t (CTCPM bulletin, 2025).
Why is cobalt mentioned with copper in the DRC?
Cobalt occurs in the same ore. Mines recover it as a by-product at the same plants, usually as cobalt hydroxide. The DRC supplies about three-quarters of the world’s mined cobalt, so its export rules move the cobalt price.
What royalty do DRC copper mines pay?
The 2018 Mining Code sets 3.5% for copper and 10% for cobalt, charged on gross commercial value (EY, 2018). Under its 2024 agreement the Sicomines Chinese partners also agreed to pay 1.2% in royalties to the state each year.
Are the cobalt export quotas still in force?
Yes. The quota system started in October 2025, is administered by ARECOMS and is set to run until at least the end of 2027. The 2026 quota is 87,000 t of cobalt plus a strategic quota of 9,600 t (Cobalt Institute, May 2026).
This page is for information only. It is not investment advice or legal advice. Company names, owners and output figures are facts, not recommendations. Ownership, quotas and royalty terms change; confirm them with the company, the regulator (ARECOMS and the Ministry of Mines) and a Congolese mining lawyer. Satellite results are exploration targets that sit ahead of a resource estimate. Prospecting needs the permission of the licence holder and the regulator, and mercury must never be used.
Farmonaut mining
Screen your Copperbelt licence from space
Request a quote to screen a licence with satellite data and get ranked exploration targets, ahead of a resource estimate.

Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026: Copper: pubs.usgs.gov
- USGS, Mineral Commodity Summaries 2026: Cobalt: pubs.usgs.gov
- DRC Ministry of Mines, CTCPM, Statistiques minières exercice 2025: wpstorage7ceb827ed5.blob.core.windows.net
- Ivanhoe Mines, Q3 2026 production results (8 October 2026): ivanhoemines.com
- Ivanhoe Mines, 2025 production results and 2026 guidance (15 January 2026): ivanhoemines.com
- Ivanhoe Mines, Kamoa-Kakula Copper Complex: ivanhoemines.com
- CMOC Group, The DRC: copper and cobalt: en.cmoc.com
- CMOC Group, first-half 2026 results (20 August 2026): en.cmoc.com
- Glencore, Full Year 2025 Production Report (29 January 2026): glencore.com
- Glencore, Half-Year Production Report 2026 (29 July 2026): glencore.com
- Glencore, Half-Year Report 2026 (5 August 2026): glencore.com
- Kamoto Copper Company, ownership: kamotocoppercompany.com
- Zijin Mining, Kolwezi Copper Mine: zijinmining.com
- MMG, Fourth Quarter 2025 Production Report (22 January 2026): mmg.com
- Cobalt Institute, Cobalt Market Report 2025 (May 2026): cobaltinstitute.org
- EY, Democratic Republic of Congo reforms Mining Code (2018): globaltaxnews.ey.com
- Law.asia, Analysis of revised Mining Code in Democratic Republic of Congo: law.asia
- Reuters via Mining.com, Sicomines agreement signed (14 March 2024): mining.com
- China Railway Engineering Group, Sicomines S.A.: crecg.com
- Mongabay, DRC plans to export 100,000 metric tons of copper to the US (January 2026): news.mongabay.com
- Mining.com, Glencore to sell 40% stake in Congo mines (3 February 2026): mining.com
- Virtus Minerals, Ministry of Mines approves Chemaf transfer of control (13 March 2026): virtusminerals.com
- Reuters via Mining.com, Copper price climbs on AI rebound (27 October 2026): mining.com
- ERG Africa, ERG committed to the Copperbelt: ergafrica.com
- Yite Holding, KaiPeng Mining: en.yiteholdings.com
- Makanisi, La RDC toujours 2eme producteur mondial de cuivre en 2025: makanisi.org
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS
 Sania Corporation
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited

 Licence holder · Nigeria · Gold + lithium
 Client · Somalia · Gold










