

Diamond mining · Ownership ranked
Who Owns Most Diamond Mines? Owners Ranked by Output
Alrosa (29.8 million carats in 2025) and De Beers (21.7 million) mine about half of the world’s rough diamonds, with governments holding large stakes in both. See owners ranked, output and value by country, and a share calculator.
Key takeaways
- Alrosa reported 29.8 million carats for 2025 and De Beers 21.7 million; the world total was 98.8 million (Kimberley Process, 2025).
- Russia, Botswana and Angola mined 63% of the world’s carats and 71% of the value in 2025 (Kimberley Process).
- De Beers is owned 85% by Anglo American and 15% by Botswana; Debswana and Namdeb are 50:50 with the Botswana and Namibia governments (Anglo American).
- Russian federal and regional bodies hold 58% of Alrosa (Alrosa shareholder page).
- Anglo American is selling De Beers; at its 30 July 2026 results it was not exclusive with any one bidder (National Jeweler).
In this article
- Who owns most diamond mines? The owners ranked by output
- How we ranked the owners
- Who owns the diamond mines in Africa
- Who controls the diamond industry: output and value by country
- The De Beers sale and what it could change
- What to check before relying on an ownership claim
- Who owns the most diamonds in the world?
- Calculator: a company's share of world rough output
- What satellite images can show about a diamond mine
- Frequently asked questions
No single company owns most diamond mines. By volume the two largest owners are Alrosa, the Russian state-linked miner, which reported 29.8 million carats for 2025 (Reuters via Kitco, August 2026), and De Beers, owned 85% by Anglo American and 15% by the Government of Botswana, which recovered 21.7 million carats (Anglo American Q4 2025 production report). Against a world total of 98.8 million carats in 2025 (Kimberley Process, 2025 global summary), that is roughly half of world supply between them. Governments sit inside both: the Russian federal and regional authorities hold 58% of Alrosa, and Botswana and Namibia each own half of the main De Beers mining ventures in their countries.
This page lists the owners, shows which countries produce the carats and the value, explains the pending sale of De Beers, and separates owning mines from owning stones. A calculator at the end turns any company’s output into a share of the world total.
Who owns most diamond mines? The owners ranked by output
Rough diamonds are measured in carats (one carat is 0.2 gram). The table ranks owners by their latest reported annual output, with the ownership shown as each company or regulator states it. Output figures are on the basis each company reports and are not strictly comparable (see the note under the table).
Chart
Rough diamond production by country
Million carats, 2025
| Owner | Main mines | Who owns it | Latest output |
|---|---|---|---|
| Alrosa | Yakutia and Arkhangelsk regions, Russia | Russian Federation 33.03%, Republic of Sakha (Yakutia) 25.00%, municipal districts 8.00%, other shareholders 33.97% (Alrosa) | 29.8 million carats in 2025 |
| De Beers Group | Jwaneng and Orapa (Botswana), Namdeb and Debmarine Namibia, Venetia (South Africa), Gahcho Kué (Canada) | Anglo American 85%, Government of Botswana 15%; mining ventures shared with governments (Anglo American) | 21.7 million carats in 2025 |
| Petra Diamonds | Cullinan (South Africa); Finsch, placed in business rescue in 2026 | Petra Diamonds | 2.34 million carats in the year to 30 June 2026 (Finsch counted to 31 May) |
| Burgundy Diamond Mines | Ekati, Northwest Territories, Canada | Australia-based Burgundy Diamond Mines (Canadian subsidiaries in receivership) | Closing: in receivership since 14 July 2026. The October 2025 plan ran to 2040 (Burgundy) |
| Lucara Diamond | Karowe, Botswana | 100% Lucara | Not reported in the sources reviewed |
| Rio Tinto | Diavik, Canada (production ended March 2026); Argyle, Australia (closed 2020) | Operator of Diavik | Nil; both mines are in closure |
Petra’s nine-month carat figure comes from its fourth-quarter operating update, which also reports that Finsch was placed in business rescue (a South African court-supervised restructuring) in the quarter and that its operations were suspended from 10 June 2026. Rio Tinto marked the last day of production at Diavik on 26 March 2026 after 23 years and more than 150 million carats; the same report names Burgundy as owner of Ekati. Ekati has since been put into court-appointed receivership (14 July 2026) after a sale process found no buyer, and is being wound down (Government of the Northwest Territories, 14 July 2026). The Argyle mine, famous for pink diamonds, stopped mining in November 2020. Lucara describes Karowe as 100% owned.
How we ranked the owners
The metric is annual rough diamond output in carats, as reported by each owner for its latest full year or, for Petra, its financial year to 30 June 2026. The table is not a full list. It covers the owners whose output we could source, plus the owners whose recent closures changed the map. Catoca in Angola (about 59% Endiama and 41% Taadeen) and the producers in Zimbabwe and the DRC are not ranked because we found no comparable annual carat figure for them. For Lucara we show ownership only. De Beers reports on a 100% basis except Gahcho Kué, which it counts at its 51% share, so its 21.7 million carats understates the mines it operates. Alrosa’s figure covers its own mines. Output is not value: a million carats from Namibia is worth far more than a million from the Democratic Republic of the Congo (see the price chart below).
Countries tell the same story from the other side. The Kimberley Process, the intergovernmental scheme that tracks rough diamond trade to exclude conflict stones, publishes production by country each year. Russia produced 31.5 million carats in 2025, 32% of the world total, followed by Botswana at 15.5 million and Angola at 15.2 million.
Who owns the diamond mines in Africa
Most African diamond mines are held through state partnerships, not by private owners alone. De Beers works with the Government of Botswana through Debswana, a 50:50 joint venture that recovers diamonds from four mines including Jwaneng, and with the Government of Namibia through Namdeb (on land) and Debmarine Namibia (offshore), also 50:50. In South Africa, De Beers Consolidated Mines, a joint venture with Ponahalo Holdings, runs Venetia (Anglo American). The Botswana model matters because the state takes both a share of profit and a share of the ownership: Mining.com, in a Bloomberg report of April 2026, notes that Debswana makes up about a fifth of the country’s GDP.
Chart
Output fell in most major producers
Million carats, 2024 against 2025
Elsewhere ownership is more mixed. In Angola, the Catoca kimberlite mine is held 59% by the state company Endiama and 41% by Taadeen, a subsidiary of Oman’s sovereign wealth fund, which replaced Alrosa in May 2025 (Mining.com). Angola produced 15.2 million carats worth US$1.8 billion in 2025, about US$119 a carat. The Democratic Republic of the Congo reported 8.9 million carats but only US$5 a carat, because most of its output is industrial quality: the USGS estimates 7 million carats of Congolese output as industrial in 2025 (USGS Mineral Commodity Summaries 2026). Zimbabwe reported 4.2 million carats at US$24 a carat.
Botswana’s and Namibia’s output both fell in 2025 as De Beers cut production to match weak demand; De Beers reports that maintenance shutdowns at Jwaneng and Orapa cut its fourth-quarter output by 35%. Botswana’s reported output dropped from 18.1 million carats in 2024 to 15.5 million in 2025, while Angola rose from 14.0 to 15.2 million.
▶ Whether a foreigner can hold a small-scale mining licence in Africa. · 5:16
Who controls the diamond industry: output and value by country
Control of supply sits with a handful of countries. Russia, Botswana and Angola together mined 63% of the world’s carats in 2025 and 71% of the value, using the Kimberley Process 2025 summary (US$2.72 billion, US$1.98 billion and US$1.81 billion of a US$9.23 billion total). Canada mined 14.1 million carats but at only US$63 a carat; Namibia mined just 2.1 million carats yet earned US$721 million, from stones recovered on land by Namdeb and offshore by Debmarine Namibia.
Chart
Average value of rough diamonds by producer
US$ per carat, 2025
Price per carat is the better guide to who holds the high-value supply. Namibia (US$344) and Lesotho (US$331) lead, ahead of Botswana at US$128. Russia’s average was US$86. De Beers says it and its partners produce around one third of the world’s rough diamonds by value, which is why its sale matters more than its carat count suggests.
The world’s output fell in both volume and value in 2025: 98.8 million carats and US$9.23 billion, against 107.9 million carats and US$9.53 billion in 2024. Both Alrosa and De Beers cut output because lab-grown diamonds and weak demand for smaller stones hurt prices. Alrosa has been under Western sanctions since 2022, suspended low-margin assets in 2025 and 2026, and reported a first-half 2026 net loss of 9.5 billion roubles (Reuters via Kitco, August 2026). It guides to 25 to 26 million carats for 2026.
The De Beers sale and what it could change
Anglo American is selling its 85% of De Beers. At its half-year results on 30 July 2026 the chief executive said the process was in its final phase and that it was a private sale, not a listing. He also told reporters (as relayed by MiningMx) that Anglo was not exclusive with any one consortium; regulatory approvals in the United States, China and Europe are expected to take about a year after signing. Botswana, which owns 15%, has said it wants to raise its stake, with Bloomberg reporting in April 2026 that the government wanted more than 50%. In July 2026 a Botswana minister told parliament that Anglo had identified a consortium led by former De Beers chief executive Gareth Penny as preferred bidder, proposing to include Angola and Namibia (Reuters via U.S. News, 17 July 2026). Anglo has not confirmed a buyer. If a deal is signed, the owners of the largest producer by value would change, but the Debswana and Namdeb partnerships with the governments are a separate layer.
Diamonds and the wider industry are covered on our other pages: a list of the biggest diamond mines on Earth, how diamond exploration finds kimberlite and alluvial deposits, and mining areas in Botswana and neighbouring countries.
▶ What mining adds to an economy: exports, jobs, revenue and energy-transition minerals. · 5:03
What to check before relying on an ownership claim
Ownership changes faster than most web pages. Check four things before you quote a stake. First, the owner’s own shareholder page or latest annual report, as for Alrosa above. Second, the production report of the parent company, which states the reporting basis (100% of a mine or the owner’s share). Third, the licence register of the country concerned, which names the licence holder even when a joint venture sits above it. Fourth, the date: the stake of a government in a company can move with a single transaction, as the De Beers sale shows. Kimberley Process figures are published roughly seven to eight months after the year ends (the 2025 summary is dated 13 August 2026), so the latest full-year production by country is for 2025.
Who owns the most diamonds in the world?
The question has two readings. At source, the answer is the mine owners above. Once stones leave the mine, ownership spreads across traders, cutters, retailers and private buyers, and no public register adds it up. What the Kimberley Process does count is rough diamonds crossing borders: in 2025 the United Arab Emirates reported 91.2 million carats of rough imports, the European Union 31.6 million and China 16.4 million (Kimberley Process, 2025).
Producers also hold stock. Alrosa reported diamond inventories worth 150.8 billion roubles at the end of the first half of 2026, which it says it is working down as the market recovers. That is unsold rough, not a measure of all diamonds owned. Anyone asking who owns most of the diamonds in the world is best served by the mine-owner table: those are the owners who decide how many new carats reach the market each year.
Calculator: a company’s share of world rough output
Use the calculator below to test any owner’s share. The defaults are Alrosa’s 2025 output, the Kimberley Process world total and the state holders’ 58% of Alrosa; change them to compare another producer.
What satellite images can show about a diamond mine
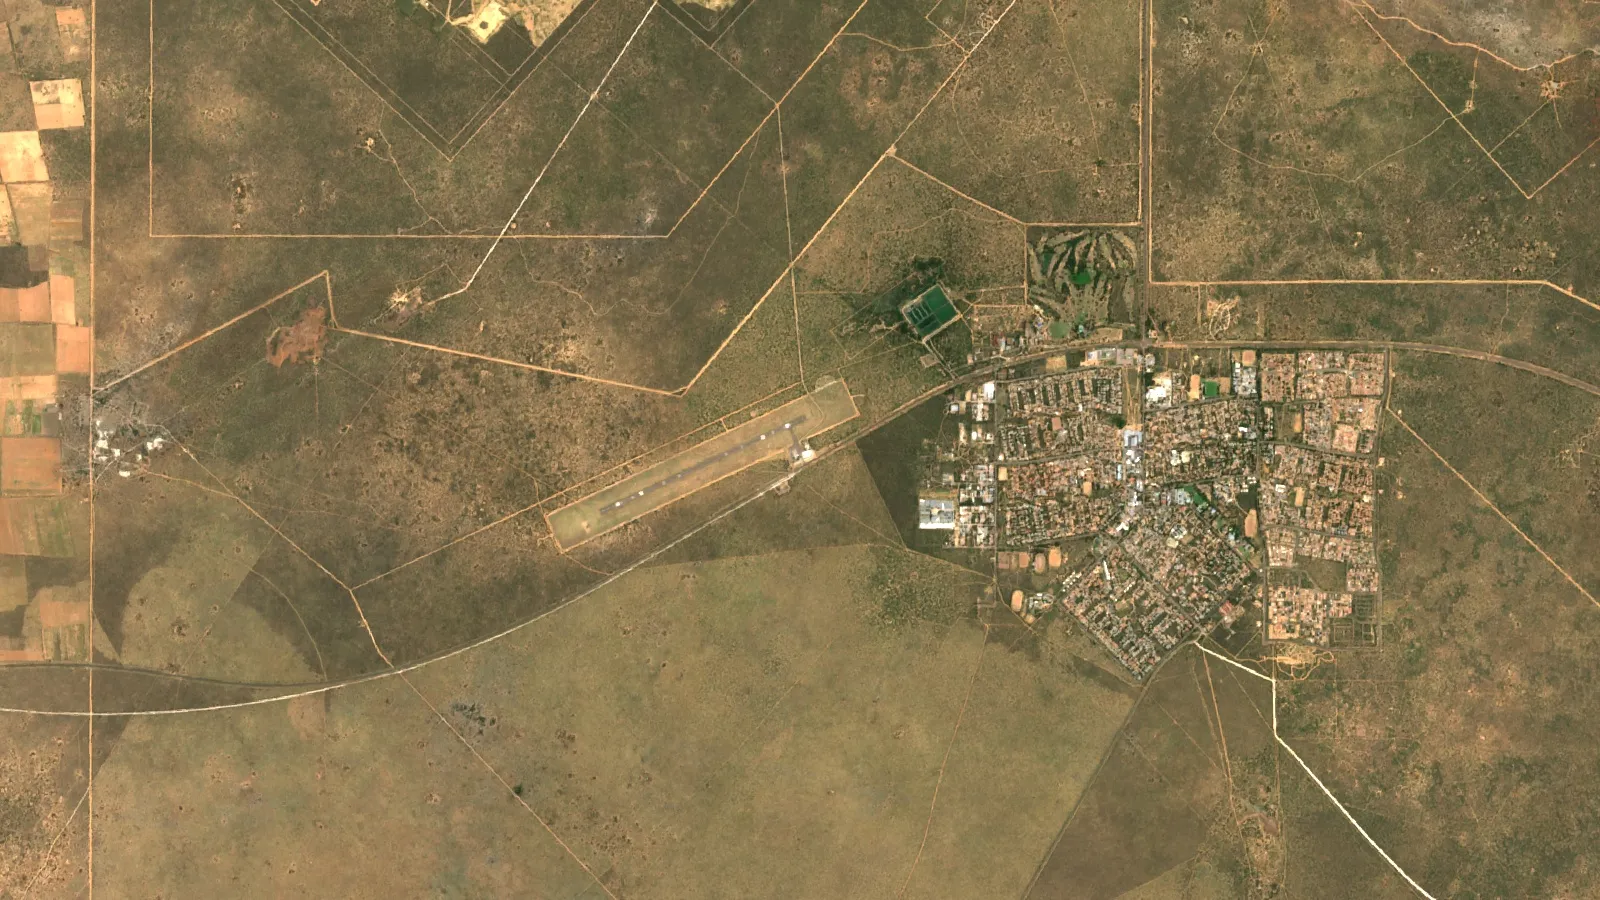
Diamond ownership is public record, but the size and activity of a mine are visible from space. Open pits, tailings and haul roads show up in multispectral imagery, and a licence owner can compare a mine footprint year on year. For exploration, satellite data ranks ground for follow-up sampling and does not confirm a pipe. Farmonaut lists diamonds among the materials its satellite-based mineral detection service covers; licence owners can describe their site through the mining query form or contact the team.
▶ Remote sensing for mining in three minutes. · 2:01
Frequently asked questions
Who owns most of the diamond mines?
No single owner. Alrosa (29.8 million carats in 2025) and De Beers (21.7 million) are the two largest by output, and together they account for about half of world supply. Governments hold large stakes in both through direct shareholdings and joint ventures.
Who owns the most diamonds in the world?
At source, the owners of the largest mines, led by Alrosa and De Beers. After mining, stones are spread across traders, retailers and buyers, and no public register totals them.
Who owns De Beers now?
Anglo American owns 85% and the Government of Botswana 15%. Anglo is selling its stake; reports in July 2026 named a preferred bidder, but Anglo had not confirmed a buyer at its 30 July 2026 results.
Who owns Debswana?
Debswana is a 50:50 joint venture between the Government of Botswana and De Beers. It recovers diamonds from four mines, including Jwaneng.
Who owns Alrosa?
The Russian Federation holds 33.03%, the Republic of Sakha (Yakutia) 25.00%, municipal districts of Yakutia 8.00%, and other shareholders 33.97%, according to Alrosa’s shareholder page.
Who owns the diamond mines in Africa?
Mostly state partnerships or joint ventures. Botswana and Namibia each own half of the main De Beers mining ventures in their countries; Angola’s Catoca is held 59% by the state company Endiama and 41% by Taadeen, an Oman sovereign-fund subsidiary; and Lucara owns Karowe in Botswana outright.
Which country produces the most diamonds?
Russia, at 31.5 million carats and US$2.72 billion in 2025 (Kimberley Process). Botswana and Angola follow in volume; Botswana is second by value.
Who controls the diamond market and supply?
Producers set the supply: Russia, Botswana and Angola together mined about 63% of the carats and 71% of the value in 2025. Alrosa has been under Western sanctions since 2022.
Is any big diamond mine still in operation in Canada?
Only one: Gahcho Kué (De Beers is the majority shareholder). Diavik stopped production in March 2026, and Ekati (Burgundy) was placed in receivership on 14 July 2026 and is being wound down.
Why are diamond mines closing?
Rough prices and demand fell as lab-grown diamonds took share, particularly in smaller stones. Argyle closed in 2020 at the end of its life, Diavik in 2026, and Finsch entered business rescue in 2026.
How many carats does the world mine each year?
98.8 million carats worth US$9.23 billion in 2025, down from 107.9 million carats and US$9.53 billion in 2024 (Kimberley Process).
Not investment advice. Ownership structures and sale processes change; check company filings before relying on any stake.
This page is for information only. It is not investment advice.
Farmonaut mining
Map your own project area from space
Describe your licence area and request a quote for a satellite mineral screening report.

Mining Pro sample view, synthetic data
Keep reading
Sources
- Kimberley Process Statistics, Annual Global Summary 2025: kimberleyprocessstatistics.org
- Kimberley Process Statistics, Annual Global Summary 2024: kimberleyprocessstatistics.org
- Kimberley Process Statistics, public statistics area: kimberleyprocessstatistics.org
- Anglo American, Q4 2025 production report: angloamerican.com
- Anglo American, Diamonds: angloamerican.com
- Alrosa, Shareholders structure: alrosa.ru
- Reuters via Kitco, Alrosa 2025 output (23 Dec 2025): kitco.com
- Reuters via Kitco, Alrosa H1 2026 loss (27 Aug 2026): kitco.com
- National Jeweler, De Beers sale update (30 Jul 2026): nationaljeweler.com
- Mining.com (Bloomberg), De Beers bid deadline (10 Apr 2026): mining.com
- BNN Bloomberg (Canadian Press), Diavik last day of production (26 Mar 2026): bnnbloomberg.ca
- Petra Diamonds, Q4 and FY 2026 operating update: investegate.co.uk
- Lucara Diamond, investors: lucaradiamond.com
- Burgundy Diamond Mines, Ekati life-of-mine plan update: burgundydiamonds.com
- USGS, Mineral Commodity Summaries 2026: diamond (industrial): pubs.usgs.gov
- Wikipedia, Argyle diamond mine: en.wikipedia.org
- Wikipedia, Catoca diamond mine: en.wikipedia.org
- Reuters via US News, Botswana on De Beers buyer (17 Jul 2026): money.usnews.com
- Government of the Northwest Territories, Ekati receiver appointment (July 2026): gov.nt.ca
- Mining.com, Oman firm replaces Alrosa in Catoca: mining.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Mulopwe Metals Mining Ltd
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited

 Exploration consultancy · South Africa · Gold










