

Reviewed September 2026 against USDA Economic Research Service, USDA National Agricultural Statistics Service, and USAFacts.
Try it: Run your own numbers →
Table of Contents
- Introduction: Imports, Production, and Testing in US Agriculture
- US Agricultural Imports: Scale and Composition
- Top Agricultural States: Where Production Actually Happens
- Top Imported Agricultural Products by Category
- Trend #1: Agricultural Machinery and Equipment Imports
- Trend #2: Specialty Crop and Horticultural Imports
- Trend #3: Supply Chain Resilience and New Trade Flows
- Trend #4: Inputs and Feed — Seeds, Fertilizers, Grains
- Agricultural Subsidies in the United States: What the Data Shows
- The US Agricultural Testing Market
- Trend #5: Precision Technology and Imported Hardware
- Trend #6: China Trade — Competition and Collaboration
- Trend #7: Policy, Standards, and Regulatory Shifts
- Calculator: Estimate Your Farm’s Import Exposure
- How Farmonaut Supports Import-Dependent Operations
- Frequently Asked Questions
- Farmonaut Subscriptions
- Conclusion
- Try it: Run your own numbers
Introduction: Imports, Production, and Testing in US Agriculture
US farms produced $573 billion worth of agricultural output in 2024, according to USDA’s Economic Research Service, while the country imported $213 billion in agricultural goods the same year — machinery, specialty crops, fertilizers, and feed that domestic production either cannot supply seasonally or cannot supply as cheaply. Those two numbers, side by side, are the whole story: US agricultural imports supplement a production base that is already the largest in the world, rather than replacing it.
This piece answers the questions people actually bring to it: which states produce the most, how import volumes break down by category, what federal subsidies actually cost taxpayers, and how big the agricultural testing market has become as food-safety and precision-farming rules tighten. Every figure below carries its source and its publication date, plus a note on where to find the next update — because production values, import totals, and market-size estimates all get revised on fixed annual or quarterly schedules, and a number frozen in this article will eventually go stale.
US Agricultural Imports: Scale and Composition
According to USDA’s Economic Research Service, total US agricultural trade data puts total agricultural imports at $213 billion for 2024. The largest single category is horticultural products — fruits, vegetables, beverages, oils, and cut flowers — which together account for 50% of all US agricultural import value in 2024, per the same ERS reporting. That single figure explains most of what shows up at a US grocery store in January that could not have been grown in the US in January: winter avocados, off-season berries, cut flowers, and tropical beverages like coffee and cocoa that the US does not commercially grow at scale.
- ✔ US agricultural imports serve two functions: filling seasonal and climatic gaps in domestic supply, and providing access to machinery, components, and specialty inputs that are more efficiently produced abroad.
- 📊 Data point: Horticultural products (fruits, vegetables, beverages, oils, cut flowers) made up 50% of the $213 billion import total in 2024 — USDA ERS.
- ⚠ Structural risk: Concentration in a small number of supplier countries for machinery components and select inputs exposes the sector to tariff and logistics shocks.
- 🌎 Trade balance context: At $573 billion produced domestically against $213 billion imported, US agriculture is a net exporter overall — imports fill specific gaps rather than substituting for domestic output.
💡 Key Insight:
Half of everything the US imports under the agricultural label is horticultural — produce, beverages, oils, and flowers — not grain, not machinery, and not livestock feed. Any analysis of import trends that leads with machinery or grain is starting from the smaller half of the picture.
For the current-quarter breakdown, USDA ERS publishes updates on a quarterly cycle at its agricultural trade at a glance page, with more granular monthly data available through USDA’s Foreign Agricultural Service trade data system within roughly 60 days of month-end. Neither the import totals nor the category shares in this article should be treated as fixed — check those pages directly if you need a figure newer than the 2024 data cited here.
Top Agricultural States: Where Production Actually Happens
California is the top agricultural state by production value, at $67.4 billion in 2024, according to USDA NASS state-level reporting. That single state’s output is larger than the entire agricultural economy of most countries, driven by specialty and high-value crops — fruits, vegetables, tree nuts, and dairy — that concentrate in California’s climate zones rather than spreading evenly across the country.
Ranking “most agricultural states” or “top 5 agricultural states” by a single metric is harder than it looks, because the answer changes depending on whether you rank by total production value, by acreage, by number of farms, or by a specific commodity. What the brief for this article can confirm directly from USDA NASS 2024 data:
| Rank / Category | Figure | Value | Source |
|---|---|---|---|
| #1 state by production value | California | $67.4 billion (2024) | USDA NASS |
| Top crop nationally by value | Corn for grain | $64.7 billion (2024) | USDA NASS |
| #2 crop nationally by value | Soybeans | $44.1 billion (2024) | USDA NASS |
| Soybean production volume | United States total | 4.37 billion bushels (2024) | USDA NASS |
| Soybean yield | National average | 50.7 bushels/acre (2024) | USDA NASS |
| Cotton production volume | United States total | 14.4 million 480-lb bales (2024) | USDA NASS |
A genuine “top 5” or “most agricultural states” ranking requires the full state-by-state table, which USDA NASS publishes each February in its Crop Values annual summary alongside the separate Farm Income and Wealth Statistics and Census of Agriculture releases for acreage and farm-count rankings. The February 2025 release (covering 2024 data, cited throughout this section) is the USDA NASS Crop Values summary this article draws from. The next edition, covering 2025 production, publishes in February 2026 — visit data.nass.usda.gov and search “Crop Values” for the current release rather than relying on a cached ranking. Because production value rankings shift with commodity prices as much as with harvested volume, a state’s rank can move year to year even when its physical output barely changes — always check the vintage on any “top state” claim you read.



Top Imported Agricultural Products by Category
USDA ERS groups agricultural imports into a small number of broad categories, and the horticultural share is the one figure this article can state with full confidence: 50% of the $213 billion imported in 2024. The category table below reflects that reporting structure — treat the categories that are not individually broken out in the ERS summary (sugar and tropical products, grains, meat and dairy) as the remaining roughly half, since ERS does not publish a further per-crop dollar split in the summary cited here.
| Category | Share of 2024 Import Value | What It Covers | Source |
|---|---|---|---|
| Horticultural products | 50% | Fruits, vegetables, beverages (coffee, cocoa), edible oils, cut flowers | USDA ERS, 2024 |
| All other categories combined | ~50% | Grains, sugar and tropical products, meat and dairy, machinery, fertilizer, feed | USDA ERS, 2024 (aggregate; not broken out further in cited summary) |
For a category-by-category dollar breakdown beyond the horticultural headline figure — separate values for imported machinery, imported fertilizer, or imported grain — the ERS agricultural trade at a glance page and the more detailed FAS trade data system (fas.usda.gov/data/trade) are the correct places to pull current figures; this research brief does not contain a further per-commodity import split, so this article states the gap rather than estimating a number that was not verified.
Trend #1: Agricultural Machinery and Equipment Imports
Machinery importation shapes how quickly US farms can mechanize, automate, and reduce labor dependency. Tractors, combines, GPS guidance systems, and precision components arrive from a concentrated set of supplier countries, meaning disruptions at a handful of ports or a handful of manufacturers can ripple across planting and harvest schedules nationwide.
- 🚜 Tractors & Combines: High-power, fuel-efficient models support field crops, soy, corn, and specialty harvests, reducing labor requirements per acre.
- 🛰️ Sensors & Automation: GPS guidance, variable-rate technology, and sensor arrays integrate directly with precision agriculture platforms.
- 🔩 Spare Parts: Fast access to spare parts and compatible implements minimizes downtime during narrow planting and harvest windows.

Trade conflicts and global logistics disruptions have repeatedly exposed the risk of relying on a narrow supplier base for machinery components. Farm equipment dealers and large operations increasingly track import channel reliability as a planning input, not an afterthought.
❓ Common Mistake:
Limiting machinery purchases to domestic brands alone can cut off access to specialized field implements built for crops or terrain not well served by US manufacturers.

Trend #2: Specialty Crop and Horticultural Imports
Horticultural imports — fruits, vegetables, beverages, oils, and cut flowers — are the single largest category of US agricultural imports at 50% of the $213 billion 2024 total, per USDA ERS. This is driven by two separate forces: crops the US climate cannot produce at all (coffee, cocoa, many tropical fruits) and crops the US produces seasonally but consumers want year-round (berries, avocados, leafy greens, citrus).
- 🥑 Avocados, mangos, berries: Sourced to cover the US off-season, supplementing domestic California and Florida production windows.
- 🌶️ Peppers, tomatoes, leafy greens: Extend shelf availability beyond regional growing seasons.
- ☕ Coffee, cocoa, tropical spices: The US has no meaningful commercial production of these crops, making imports the entire supply.

For an itemized dollar breakdown within horticulture — separate 2024 values for avocados versus berries versus cut flowers — the research base for this article confirms only the 50% aggregate share from USDA ERS; a further per-crop split was not part of the verified brief, so treat any more granular number you see elsewhere as needing its own source check against ERS’s detailed trade tables.
Trend #3: Supply Chain Resilience and New Trade Flows
Port capacity, inland rail and truck links, and labor availability at entry terminals all determine how reliably imported inputs and machinery reach US farms during time-sensitive planting and harvest windows. A single labor dispute or weather event at a major port can create shortages for inputs that have no domestic substitute on short notice.
Key Infrastructure and Supply Chain Adjustments
- 🚢 Modernized ports: Reduce customs delays on perishables and time-sensitive farm inputs.
- ⛏️ Rail & truck links: Connect coastal and border entry points to inland farming regions.
- ⚠ Risk hotspots: Weather volatility and labor disputes at major terminals can create sudden shortages for inputs and machinery with no quick domestic substitute.
🌐 Key Insight:
Farm supply resilience increasingly depends on tracking logistics data and maintaining relationships with multiple suppliers for critical equipment and inputs, rather than single-sourcing on price alone.

Supply Chain Resilience Checklist
- ✔ Diversify origins for grains, fertilizers, and feed rather than relying on one supplier country.
- ✔ Track logistics digitally via satellite and IoT tools to spot disruption early.
- ✔ Verify import standards compliance for pest and disease mitigation before goods reach the farm.
- ✔ Watch infrastructure investment — port and roadway upgrades change effective import costs over time.
- ✔ Build contingency plans for input and equipment shortages before, not during, planting season.
For agri-logistics operations moving imported equipment or inputs inland, Farmonaut’s Fleet Management Solutions track vehicle use and delivery timing via satellite-derived routing data.

Trend #4: Inputs and Feed — Seeds, Fertilizers, Grains
Seeds, feed grains, and fertilizers are among the most strategically important import categories because they directly determine planting decisions each season. The US both exports and imports large volumes in these categories — specialty and non-GMO varieties are often produced more efficiently overseas, and certain fertilizer inputs are cheaper to import than to manufacture domestically at scale.
Seeds: Hybrid and specialty seed imports support diversification in planting strategy where domestic breeding programs do not cover a specific trait or crop type.
Fertilizers: Nitrogen, phosphate, and potash imports respond directly to price differentials and domestic supply constraints in a given season.
Feed grains: Imports supplement livestock feed supply during drought years or when international corn and soy prices undercut domestic sourcing.
🌱 Pro Tip: Monitoring real-time input price and availability data helps agribusiness managers plan around import timing. Farmonaut’s satellite monitoring suite and API supply field-condition data that complements input-cost tracking.
Input Import Trends
- ✔ Regional variation: Midwest operations lean on imported seed genetics and crop protection; livestock-intensive states depend more on feed and forage imports.
- ✔ Agrochemicals: Crop protection agents for resistant weed species are increasingly sourced globally.
- ✔ Planting decisions: Input pricing — domestic versus imported — directly shapes crop mix choices each season.
- ✔ Resource optimization: Precision input application, guided by satellite and digital tools, reduces overuse of both domestic and imported inputs.

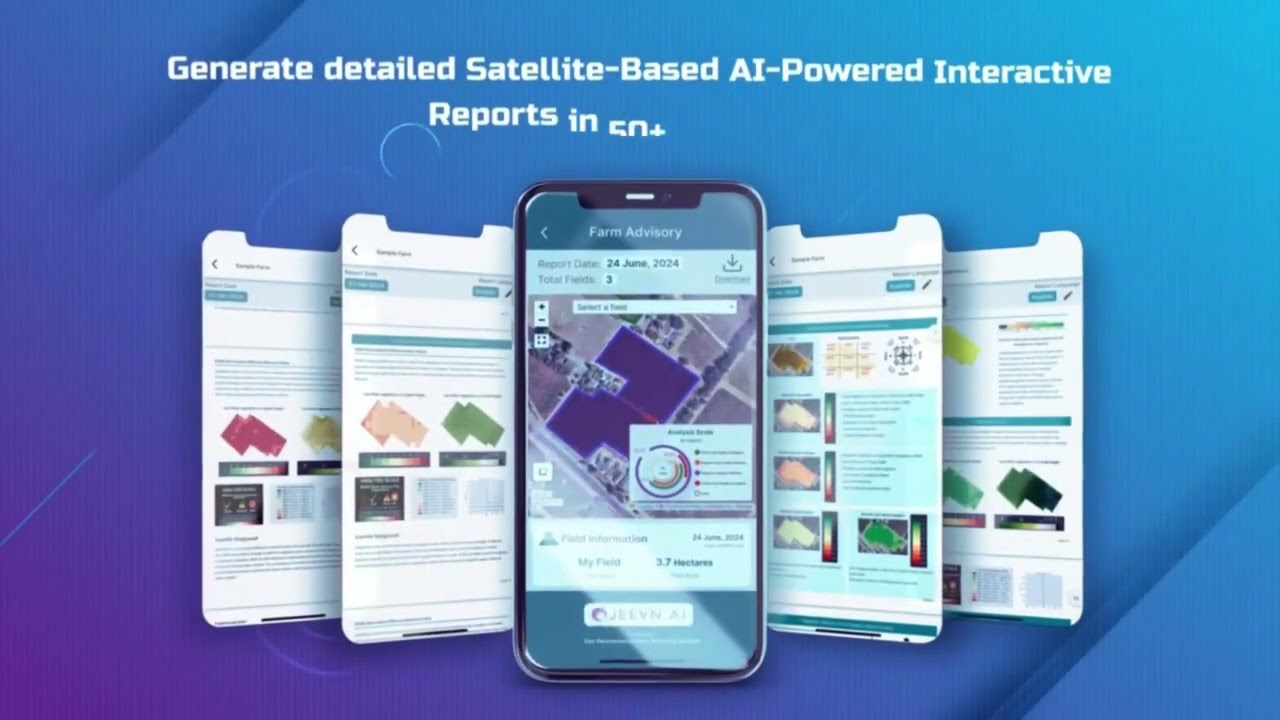
For AI-powered decision support on planting and input use, Farmonaut’s JEEVN AI Advisory System provides field-level insight — see Large-Scale Farm Management.
Agricultural Subsidies in the United States: What the Data Shows
Federal direct commodity crop subsidies totaled $9.3 billion in 2024, according to USDA data compiled by USAFacts. That figure covers direct payment programs tied to specific commodity crops — it does not include the separate federal crop insurance program, which is the larger of the two subsidy channels by dollar volume.
Crop insurance premiums totaled $17.3 billion in 2024, of which approximately $8.1 billion was the federal subsidy portion covering part of farmers’ premium costs, per the same USAFacts analysis of USDA subsidy data. Combined, direct commodity payments and the crop insurance subsidy put total federal support in the neighborhood of $17.4 billion for 2024 ($9.3B direct + $8.1B insurance subsidy) — a figure worth naming precisely because “farm subsidies” gets quoted in the press using either the direct-payment number alone or a combined figure, and the two are frequently confused.
| Subsidy Channel | 2024 Value | What It Covers |
|---|---|---|
| Direct commodity crop subsidies | $9.3 billion | Payments tied to specific commodity crops (corn, soy, wheat, cotton, etc.) |
| Federal crop insurance subsidy | ~$8.1 billion (of $17.3B total premiums) | Government-subsidized portion of farmer-paid insurance premiums |
| Combined federal support (approx.) | ~$17.4 billion | Direct payments plus insurance subsidy, 2024 |
These figures come from USDA program data as compiled and published by USAFacts; USDA’s Farm Service Agency and Risk Management Agency update program payment totals on their own schedules following each program year’s close-out, typically with a lag of several months after the crop year ends. For the current subsidy year’s figures once they publish, check USDA FSA’s payment data directly rather than assuming the 2024 figures above still hold — commodity subsidy totals move with both enrollment and commodity prices from year to year.
The US Agricultural Testing Market
The US agricultural testing market was valued at $1.59 billion in 2025, according to IMARC Group’s market sizing report. This market covers soil testing, seed and crop genetic testing, pesticide residue testing, and food safety testing services used across the production and supply chain — a distinct market from agricultural production itself, and one growing specifically because of tightening food-safety regulation and expanding precision-farming adoption.
Whether this market “fits” a search for US agricultural imports is a fair question — the connection is real but indirect: imported produce and inputs are subject to testing and compliance regimes (pesticide residue limits, phytosanitary certification) that feed demand for the same testing infrastructure serving domestic production. If you arrived here specifically researching agricultural testing services, laboratories, or market sizing rather than trade flows, treat this section as the answer and the rest of the article as adjacent context.
| Metric | Value | Period | Source |
|---|---|---|---|
| US agricultural testing market size | $1.59 billion | 2025 | IMARC Group |
This is a research-firm market estimate rather than a government statistic, so treat it accordingly — different research houses (IMARC, Mordor Intelligence, Market Data Forecast) publish their own sizing methodologies and will show different absolute figures even when describing the same market. IMARC’s report is the one cited in the brief for this article; for the current estimate, check the IMARC Group US agricultural testing market report directly, since these firms typically refresh their forecasts annually, with reports using the current year as baseline generally appearing in the third quarter.
Trend #5: Precision Technology and Imported Hardware
Precision agriculture adoption in the US continues to draw on imported components and finished hardware — planters, drones, irrigation controllers, and autonomous guidance systems — even as domestic manufacturers compete in the same space. This is less a single “trend” than a steady multi-year shift in what farm equipment contains, regardless of where it is assembled.
- 🕹️ Precision planters & drones: Optimize planting density, input rates, and field-level yield response.
- 🤖 Autonomous tractors: GPS- and AI-guided machinery targets fuel savings and precise seeding and nutrient delivery.
- 📡 Field sensors: Multispectral, soil moisture, and pest-monitoring sensors feed both machinery controllers and cloud-based farm management software.

Precision agriculture adoption rates specifically — what share of US farms use variable-rate technology, drone scouting, or autonomous guidance — are not part of the verified data for this article; USDA’s Census of Agriculture and ERS technology-adoption surveys are the correct primary sources for that figure, and the Census of Agriculture next publishes in full in 2027. If you need a current adoption percentage for a specific technology, pull it directly from ERS’s precision agriculture adoption data series rather than a secondary market report.
Trend #6: China Trade — Competition and Collaboration
Trade flows between the US and China run in both directions and shape farm planning decisions in both countries. The US exports substantial volumes of soybeans, corn, and sorghum to China, while importing feedstuffs, fertilizer components, and select machinery parts from Chinese suppliers.
- ✔ Shifts in Chinese demand for US soybeans and corn directly influence domestic pricing and planting decisions in major grain-producing states.
- ✔ US imports of machinery components, sensors, and fertilizers from China can lower input costs but introduce tariff and geopolitical exposure.
- ✔ Tariff negotiations and phytosanitary compliance requirements affect both the export and import sides of this relationship simultaneously.
🌏 Key Insight:
Policy shifts affecting US-China agricultural trade can reshape commodity, fertilizer, and machinery markets simultaneously — tracking tariff and quota changes is a standing requirement for agribusiness planning, not a one-time check.
For traceability across cross-border supply chains, Farmonaut’s Blockchain Traceability Tools verify product movement from seed to shelf for internationally traded farm products.
Trend #7: Policy, Standards, and Regulatory Shifts
Import flows operate within a standing framework of standards and risk assessments that determine what the US can import and under what conditions. This framework does not reset each year — it evolves incrementally, with ongoing scrutiny in a consistent set of areas:
- ✔ Pesticide residue limits and maximum allowable levels for imported foods and feeds
- ✔ Machine safety and electrical compatibility standards for imported equipment
- ✔ Animal and plant health controls, including screening for invasive pests and diseases
- ✔ Grower and processor compliance documentation for sustainability, labor, and traceability requirements
⚖️ Compliance Note:
Consistent documentation and digital traceability are required for both importers and exporters to maintain market access across North American, European, and Asian trading partners.
To document sustainability practices and carbon impact for compliance purposes, see Farmonaut’s Carbon Footprinting Tool.
Calculator: Estimate Your Farm’s Import Exposure
Use the figures you actually pay for seed, fertilizer, and machinery parts to see what share of your input budget is exposed to import-driven price or supply shocks.
Run your own numbers
Assumptions: this is a planning estimate, not a forecast. It assumes your import-share and price-shock percentages are your own best estimates for your operation and does not account for hedging, forward contracts, or insurance offsets. It excludes labor, land, and capital equipment depreciation costs entirely.
How Farmonaut Supports Import-Dependent Operations
As a satellite technology company, Farmonaut focuses on the field-level and logistics-level visibility that matters once imported inputs, seeds, or machinery are already on the farm. Real-time monitoring does not change import policy or pricing, but it does help operators respond faster when imported inputs underperform, arrive late, or need to be substituted mid-season.
- ✔ Optimize resource use: The Satellite Advisory Platform supports planning around localized field conditions, including when integrating imported seeds, feeds, or machinery.
- 📊 Field-level insight: API and app-based monitoring track crop vigor regardless of input origin, flagging emerging stress or water issues early.
- 🔄 Traceability: Farmonaut Traceability Solutions support compliance with domestic and international import/export documentation standards.
- ⚡ Fleet and resource management: AI-powered logistics tools help manage delivery timing for equipment and inputs.
- 🌱 Environmental monitoring: Satellite carbon footprinting supports sustainability-linked import/export certification requirements.
Whether you are a farmer tracking soil health after using imported fertilizer, an agribusiness optimizing import logistics, or a policy analyst monitoring input compliance, Farmonaut's platform and API provide field-level data to support those decisions.
Platform Use Cases
- 🌿 Large-scale farm monitoring for US growers integrating imported seeds and feeds.
- 🚚 Logistics tracking for agri-importers distributing equipment nationwide.
- 📜 Traceability compliance for exporters meeting EU and Asian market standards.
- 💧 Water resource precision for farms using imported irrigation technologies.
- 🧮 Carbon auditing for sustainable sourcing certification.
Frequently Asked Questions
What is the total value of US agricultural imports?
USDA's Economic Research Service reported total US agricultural imports at $213 billion for 2024, against $573 billion in total domestic agricultural production the same year. Check the ERS trade data page directly for the current figure, updated quarterly.
What is the top agricultural state in the United States?
California led all states in agricultural production value at $67.4 billion in 2024, per USDA NASS. Rankings for "top 5" or "most agricultural states" depend on whether you measure by production value, acreage, or farm count — USDA NASS publishes the full state table each February.
How much does the US government spend on agricultural subsidies?
Direct commodity crop subsidies totaled $9.3 billion in 2024, with an additional roughly $8.1 billion in federal crop insurance premium subsidies (out of $17.3 billion in total premiums), according to USDA data compiled by USAFacts.
How big is the US agricultural testing market?
The US agricultural testing market was valued at $1.59 billion in 2025, according to IMARC Group. This covers soil, seed, pesticide-residue, and food-safety testing services, separate from agricultural production or import value.
What share of US agricultural imports are horticultural products?
Horticultural products — fruits, vegetables, beverages, oils, and cut flowers — made up 50% of the $213 billion in US agricultural imports in 2024, per USDA ERS.
How can technology solutions like Farmonaut help manage agricultural imports?
Farmonaut provides real-time field monitoring, AI-based advisory, blockchain traceability, and logistics management tools via its web and mobile app and API, supporting import-dependent planning and compliance documentation.
📧 Stay Ahead: Access affordable Farmonaut subscriptions for satellite-powered, AI-driven advisory, crop monitoring, and logistics tools for farmers, importers, and agribusinesses across the United States.



Conclusion
US agricultural imports and domestic production tell a complementary story, not a competing one: $573 billion produced against $213 billion imported in 2024, with half of that import total made up of horticultural products the domestic growing season simply cannot supply year-round. California's $67.4 billion production lead, corn's $64.7 billion crop value, and the $9.3 billion in direct farm subsidies are each moving numbers on their own annual publication schedule — the durable part of this article is not any single figure but the method: go to USDA NASS each February for production values and state rankings, USDA ERS quarterly for trade totals, and USAFacts or USDA FSA directly for subsidy program data, rather than relying on any secondary summary — including this one — as a permanent source.
Discover how Farmonaut supports growers, input traders, and policy planners with real-time crop and logistics intelligence, or use the API platform for custom agriculture supply chain solutions.

 XOS Realty
 Geospatial Lab Africa
 KhetiBuddy
 Agro La Gándara
 Global Agrifood
 HIPSAC
 ZOL Zimbabwe
 Juligerm
 AdBio
 MISE Maroc
 NWNS
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 Croptimum
 DnCubed
 Field Capacity
 Indosistim Teknologi

