

Seeds and soil products · Buyer guide
Soil Product and Seed Brands Seen as Innovation Leaders
Two companies held 72% of US corn acres and 66% of soybean acres in 2018-20 (USDA ERS), and the top four own 95% of corn seed patents and variety rights (USDA AMS). Here is who leads in seeds and soil biologicals, and how to test a new product on your own fields.
Key takeaways
- In soil products, Corteva (Stoller and Symborg, bought March 2023) and Novonesis (Novozymes plus Chr. Hansen, January 2024) have the largest dated biologicals deals.
- Two seed companies accounted for 72% of US planted corn acres and 66% of soybean acres in 2018-20 (USDA ERS, 2023).
- Bayer, Corteva, ChemChina and BASF own 97% of canola, 95% of corn, 84% of soybean and 74% of cotton seed intellectual property (USDA AMS, 2023).
- The seven largest seed companies raised crop research spending from under $2 billion in 1990 to over $7 billion by 2014 (USDA ERS).
- Brand perception is not proof: read the seed tag, ask for independent trials, and check the break-even yield gain at your own price.
In this article
- Which brands lead innovation in seeds and soil products?
- How we chose the companies
- Who sells the seed: market share data
- Who owns the ideas: patents and variety rights
- Soil products: biologicals, biostimulants and inoculants
- Types of good seed companies
- Technology behind new seed
- How to judge a seed or soil product on your farm
- Does a premium seed or soil product pay? Break-even check
- Rules and challenges for seed and soil innovation
- Sustainability claims: what to check
- FAQ
In soil products, the brands perceived as leaders in innovation are the big seed and crop input groups that have bought or built biological units, plus a few specialists. Corteva calls itself a global leader in biologicals after it closed its purchase of Stoller and Symborg in March 2023, and Novonesis was formed in January 2024 when Novozymes and Chr. Hansen merged. In seeds, Corteva and Bayer lead: two companies held 72% of US planted corn acres and 66% of soybean acres in 2018-20, according to the USDA Economic Research Service report on concentration in agribusiness.
“Perceived as a leader” is not the same as “best for your farm”. This guide separates the two. It shows who holds the seed market and the patents, who is building soil biologicals, what the labels and rules in the US and Europe require, and how to judge a new seed or soil product on your own fields. It also gives a break-even calculator so you can test whether a premium product pays at your prices.
Which brands lead innovation in seeds and soil products?
There is no official ranking of “innovation”. We use three measures that are published: share of seed sales, share of seed patents and variety rights, and spending on crop research. On all three, a short list of companies stands out. The seven largest seed companies named by the ERS are Bayer, Corteva, Syngenta, BASF, Limagrain, KWS and Rijk Zwaan. Together they raised crop research spending from under $2 billion in 1990 to over $7 billion by 2014, and as a group they have put about 10% of their farm product sales into research.
| Company | Main strength | Soil or biological unit | Best for |
|---|---|---|---|
| Corteva | Corn and soybean seed (Pioneer), variety rights | Stoller and Symborg, bought 2023 | Row-crop growers who want seed and biologicals from one dealer |
| Bayer | Corn and soybean traits and patents | Seed treatments | Growers who rely on trait packages and herbicide systems |
| Syngenta | Seed and crop protection | Syngenta Biologicals | Mixed seed and spray programmes |
| BASF | Cotton and canola seed | Seed treatments | Cotton growers in the US South |
| Novonesis | Microbes and enzymes | Microbial soil and seed products | Growers testing inoculants and microbial seed treatments |
| Limagrain, KWS | Cereals, beet, forage, corn in Europe | Not the main focus | European arable and grass growers |
| Rijk Zwaan, Sakata, Bejo | Vegetable seed | Not the main focus | Vegetable and salad growers |
| Johnny’s Selected Seeds | Organic and market-garden seed | Not the main focus | Small growers and organic farms in North America |
The table lists strengths, not scores. Earlier versions of this page gave each company an “innovation score”. Those scores had no published source, so we removed them.
Chart
US corn seed sales by company after the mergers
ERS post-merger estimate of US corn retail seed sales shares, based on 2016-17 shares of the merged firms
How we chose the companies
We kept companies that meet at least one of these tests: a top place in US seed sales in the ERS market share table; a large share of seed patents and variety rights in the USDA Agricultural Marketing Service seed competition report of March 2023; a named place among the seven largest seed companies by research spending; or a completed, dated deal that gave them a soil biologicals business. We added vegetable and organic seed houses because many readers search for garden, tomato and herb seed, and these firms supply that market.
We did not use market research firms’ “top 10” lists, because their methods are not public. We also did not rank companies on taste, flavour or service, because no neutral data exist for that.
Who sells the seed: market share data
The US corn and soybean seed market has become far more concentrated since 2000. The ERS table of retail seed sales shows that “all other” companies sold 40.5% of corn seed in 2000-03 but only 16.1% in 2016-17. In soybeans, the share for all other companies fell from 51.8% to 21.9% over the same period. The four-firm share reached 80% in corn and 75% in soybeans by 2016-17, and 94% of cotton area by 2018-20.
After the 2018-19 mergers, the ERS estimates Corteva held 38.3% of corn seed sales and Bayer 33.3%, based on the 2016-17 shares of the merged firms. In soybeans the estimate is Corteva 37.7% and Bayer 28.2%. In cotton, by planted area in 2018-20, Bayer brands had 38.4%, Americot 27.2%, Corteva 17.5% and BASF 10.5%.
The OECD figures quoted by the AMS report point the same way. In 2016, four companies controlled 91% of US cotton seed market value, 82% of maize seed and 69% of soybean seed. Market share shows who farmers buy from. It does not prove who has the best products for a given field.
Chart
Seed sales held by smaller US companies
Percent of US retail seed sales outside the leading firms (‘all others’), by period
Who owns the ideas: patents and variety rights
New seed is protected in two ways in the US: Plant Variety Protection (PVP) certificates and utility patents. The AMS report counted both from 1970 to 2020. It found that the top four companies (Bayer, Corteva, ChemChina and BASF) own 97% of canola, 95% of corn, 84% of soybean, 74% of cotton and 51% of wheat intellectual property.
Chart
Seed patents and variety rights held by the top four
Percent of US patents and PVP certificates owned by Bayer, Corteva, ChemChina and BASF, by crop (1970-2020 grants)
The split inside each crop differs. In corn, Bayer owns 57% of the protection, including 71% of corn patents, while Corteva owns 28%, including 53% of corn PVP certificates. In soybeans, Bayer owns 43% and Corteva 33%. In wheat, ownership is spread wider: Corteva 23%, Bayer 17% and ChemChina 11%, with public breeders and smaller firms holding the rest.
The pace of new protection has risen too. ERS counted 5,137 plant patents, 5,010 utility patents and 2,028 PVP certificates for new crop varieties from 2016 to 2020, more than double the count of a decade earlier. Corn hybrids also turn over faster than they used to: the average commercial life of a new hybrid fell from around 4-5 years in 1997 to under 3 years by 2009, according to a study cited by ERS.
Soil products: biologicals, biostimulants and inoculants
When people ask which brands lead innovation in soil products, they usually mean biologicals. These are products made from microbes or natural substances, used on seed, in furrow or on soil. They fall into two groups with different rules.
Biopesticides
Products that control pests, diseases or weeds are pesticides, even when they are natural. In the US, the EPA’s biopesticides page explains that they include naturally occurring substances, microorganisms that control pests, and pesticidal substances produced by plants with added genetic material. They must be registered under FIFRA before sale. Check the label and your state’s rules before you apply any product.
Biostimulants and nutrient efficiency products
Biostimulants claim to help plants use nutrients or cope with stress. The European Union defines them in its fertilising products law. Under Regulation (EU) 2019/1009, a plant biostimulant stimulates plant nutrition processes independently of its nutrient content, with the sole aim of improving nutrient use efficiency, tolerance to abiotic stress, quality traits or the availability of confined nutrients in the soil or rhizosphere. Products that meet the rules can carry CE marking across the EU. In the US, check how your state regulates fertilizer and soil amendment products.
Who is building soil biologicals
Two dated deals stand out. On 2 March 2023, Corteva said it had closed its purchase of Symborg, a microbial firm based in Murcia, Spain, and Stoller, which it called one of the largest independent biologicals companies, based in Houston, Texas (Corteva press release). In the same release, Corteva said it expects biologicals to be the fastest-growing crop protection segment, reaching 25% of the market by 2035. That is a company forecast, not an independent figure.
On 29 January 2024, Novozymes and Chr. Hansen completed their merger to form Novonesis, which brings together about 10,000 people (Novonesis announcement). Both firms had long sold microbes and enzymes, including farm uses such as seed inoculants.
Smaller specialists also shape opinion among growers, and many start-ups sell nitrogen-fixing microbes or soil amendments. Their size makes it hard to compare them with the groups above on published data, so test any product on your own ground before you scale it.
Types of good seed companies
“Good” depends on what you grow. Seed houses tend to specialise, and the best supplier for a 2,000-acre corn farm is not the best one for a market garden.
Field crop seed companies
These supply corn, soybeans, cotton, canola, wheat and other row crops. They compete on yield trials, traits and dealer support. Ask for local, independent trial data, not just the company’s own plots. The AMS report notes that the cost of entering trials is borne by the companies, which can keep smaller breeders out.
Grass and forage seed companies
These supply pasture, hay and turf seed. Forage is the crop where the top five firms own the least protection: the AMS report found that companies outside the top five own 53% of forage intellectual property. That leaves room for regional breeders. Pick varieties tested in your climate zone and check the purity and germination on the tag.
Vegetable and tomato seed companies
Firms such as Rijk Zwaan, Sakata and Bejo breed hybrids for disease resistance, shelf life and yield in tomatoes, lettuce, carrots and brassicas. Rijk Zwaan is one of the seven largest seed companies by research spending in the ERS analysis. Ask which resistances a variety carries, and match them to the diseases you see.
Garden, herb and organic seed companies
Home and small-market growers buy from catalogue houses such as Johnny’s Selected Seeds. Certified organic farms in the US must follow the National Organic Program rule. Under 7 CFR 205.204, producers must use organically grown seed, but may use untreated non-organic seed when an equivalent organic variety is not commercially available, or non-organic seed treated only with a National List substance when no equivalent organic or untreated variety is available. Organic seed must always be used for edible sprouts. Check with your certifier before you buy.
Technology behind new seed
Five tools account for much of the change in seed breeding over the last two decades.
- Marker-assisted selection: breeders use DNA markers to find plants with a wanted gene, such as disease resistance, without waiting for the full crop to grow.
- Genomic selection: statistical models predict a plant’s value from its whole DNA profile, so weak lines can be dropped early.
- Gene editing: tools such as CRISPR make small, targeted changes. Rules differ by country, so check what is approved where you farm and sell.
- Trait stacking: several traits, such as insect and herbicide tolerance, are combined in one hybrid.
- Seed treatments and coatings: fungicides, insecticides or microbes are applied to the seed so protection starts at planting.
Satellite and field data now feed into this work as well. Breeders and seed dealers compare how hybrids perform across many fields, and growers compare their own strips. Traceability tools help keep a record of each seed lot from the bag to the field; see our page on product traceability.

▶ The five stages of crop farming, from seed to harvest, and where new technology fits in. · 12:13
How to judge a seed or soil product on your farm
A big brand name does not mean a product will pay on your soil. Use these steps before you buy at scale.
- Read the tag or label. The Federal Seed Act is a truth-in-labeling law. Seed shipped between US states must show purity, germination, noxious weed seeds per pound, any chemical treatment, the kind and variety, and the shipper’s name. For soil products, check what the label claims and whether the product is registered as a pesticide or sold as a fertilizer.
- Ask for independent trials. University and state variety trials are more useful than a dealer’s demonstration plot.
- Run a side-by-side strip. Plant the new product next to your usual one in the same field, with the same management, and repeat it in more than one field.
- Measure the result. Use yield monitor data, and look at crop health maps during the season so you can see where differences start.
- Do the sums. Compare the extra cost per acre with the extra yield times your expected price. The calculator below does this.
Crop health maps from satellites can show whether a treated strip stays greener than the check strip through the season. Farmonaut provides these maps for drawn fields, and developers can pull the same data through the satellite and weather API.

▶ How satellite NDVI maps show crop stress before you can see it, useful for comparing test strips. · 4:09
Does a premium seed or soil product pay? Break-even check
A new hybrid, seed treatment or biological only pays if the extra yield is worth more than the extra cost. The break-even yield gain is simple: extra cost per acre divided by crop price. At an extra cost of US$15 per acre and corn at US$4.20 per bushel (example values), you need about 3.6 more bushels per acre just to break even. Enter your own numbers below.
Try the numbers for your own farm below.
Rules and challenges for seed and soil innovation
Seed and soil product makers work under several layers of rules. Seed labelling is federal for interstate trade in the US and also covered by state seed laws. Biopesticides need EPA registration. Biostimulants in the EU need to meet the fertilising products regulation to carry CE marking. Gene-edited crops face different rules in each country.
Access to plant genetic resources is also governed by treaty. The International Treaty on Plant Genetic Resources for Food and Agriculture, run through FAO, is an agreement between member countries and the European Union to conserve, use and manage crop genetic resources. It underpins how breeders share material from gene banks.
Concentration is the other debate. The AMS report records concerns from farmers and smaller breeders that fewer firms mean fewer choices and higher prices. It also records the industry’s view: the American Seed Trade Association told USDA its members spend on average 15% of revenue on research and development. Both views are in the public record; growers can judge them by price and choice in their own area.
Sustainability claims: what to check
Many seed and soil product makers now make sustainability claims, such as lower fertilizer use, better soil carbon or less water. Ask three questions. Is the claim measured on farms like yours? Is it per acre or per unit of yield? Who checked it? If a product is meant to cut emissions, you can track the farm-level effect with a carbon footprinting approach. Machinery use also matters for emissions and cost; our page on fleet management covers that side.
Biologicals can also be part of an integrated plan with lower chemical use, but results vary with soil, weather and crop. Get advice from a local agronomist or extension service before you change a fertilizer or pest programme.
Related pages on our site: crop monitoring apps.
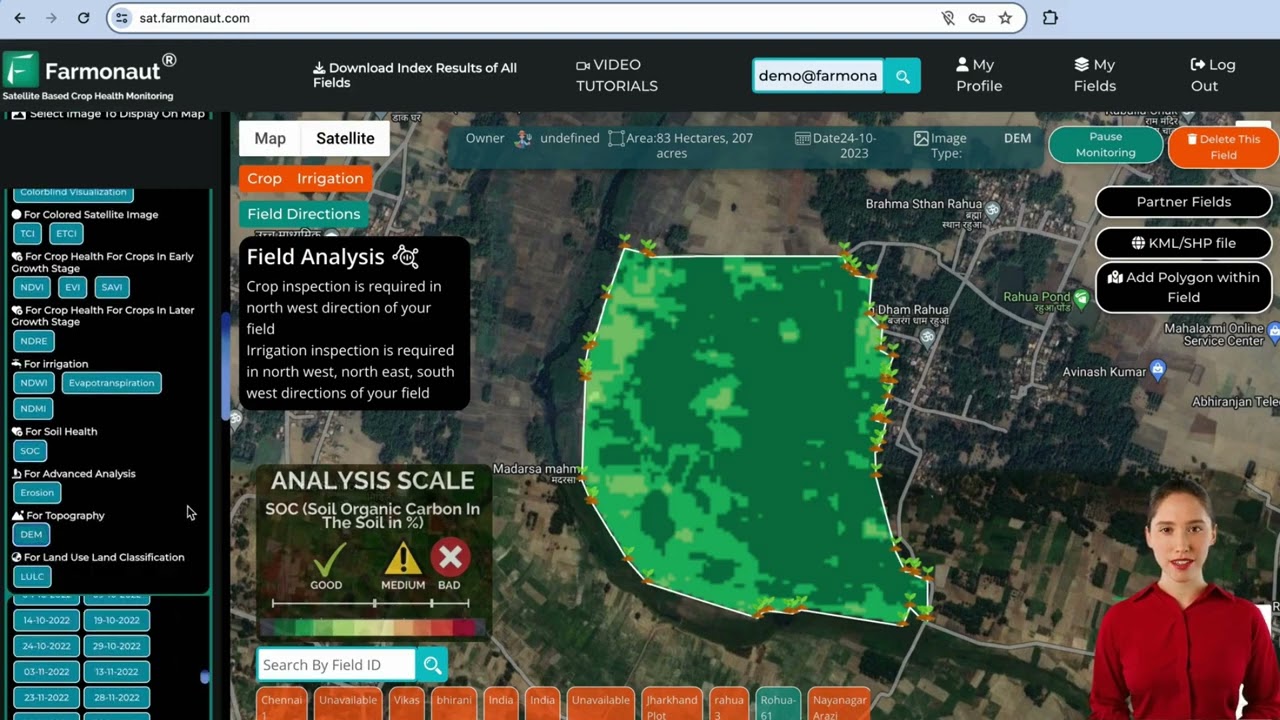
▶ A walk-through of Farmonaut’s web app for satellite field monitoring. · 8:02
FAQ
In soil products, which brands are perceived as leaders in innovation?
The groups with the largest dated biologicals deals are seen as leaders: Corteva, after buying Stoller and Symborg in 2023, and Novonesis, formed from Novozymes and Chr. Hansen in 2024. Bayer, Syngenta and BASF also sell biological and seed treatment products. Perception is not proof, so trial products on your own fields.
Which companies lead US seed sales?
Corteva and Bayer. ERS estimates that two companies held 72% of US planted corn acres and 66% of soybean acres in 2018-20.
In grass seed, which brands are perceived as leaders in innovation?
Forage and grass seed is less concentrated than corn or soybeans. Companies outside the top five own 53% of forage intellectual property (AMS, 2023), so regional breeders and firms such as Limagrain and KWS matter more here. Choose by local trial data.
What should a seed tag show?
Under the Federal Seed Act, interstate seed must show purity, germination, noxious weed seeds per pound, any chemical treatment, kind and variety, and the shipper’s name and address.
Can organic farms use non-organic seed?
Yes, in limited cases: untreated non-organic seed when an equivalent organic variety is not commercially available, or seed treated only with a National List substance when no organic or untreated equivalent is available (7 CFR 205.204). Sprout seed must always be organic. Ask your certifier.
How do I know if a premium product paid off?
Plant side-by-side strips, measure yield, and compare the extra bushels times your price with the extra cost per acre. The break-even calculator on this page does the sum.
Farmonaut agriculture API
Build field data into your agtech product
Seed, soil product and agtech teams can pull satellite crop health, soil moisture and weather data for any field through the Farmonaut agriculture API. See /farmonaut-agriculture-api.




Sources
- USDA ERS, Concentration and Competition in U.S. Agribusiness (EIB-256), June 2023: ers.usda.gov
- USDA ERS, EIB-256 full report (PDF), 2023: ers.usda.gov
- USDA AMS, More and Better Choices for Farmers: Promoting Fair Competition and Innovation in Seeds, March 2023: ams.usda.gov
- USDA AMS, Federal Seed Act: ams.usda.gov
- eCFR, 7 CFR 205.204 Seeds and planting stock practice standard: ecfr.gov
- US EPA, Biopesticides: epa.gov
- Regulation (EU) 2019/1009 on EU fertilising products: eur-lex.europa.eu
- FAO, International Treaty on Plant Genetic Resources for Food and Agriculture: fao.org
- Corteva, Corteva Agriscience completes acquisitions of Symborg and Stoller, 2 March 2023: corteva.com
- Novonesis, Combination of Novozymes and Chr. Hansen now successfully completed, 29 January 2024: novonesis.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 NWNS
 Hydenmet
 Dirks Bros Farms
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 Croptimum
 DnCubed
 Field Capacity
 Indosistim Teknologi
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC

 Licence holder · Niger · Gold
 Licence holder · Nigeria · Gold + lithium
 Client · Somalia · Gold










