

Metals compared · Investor guide
Best Metals to Invest In: 4 Compared by Price and Supply
Copper, silver, nickel and uranium side by side: price averages from the World Bank, mine supply from the USGS, market balances from the ICSG and INSG, and the ETFs, miners and trusts that hold them. Not investment advice.
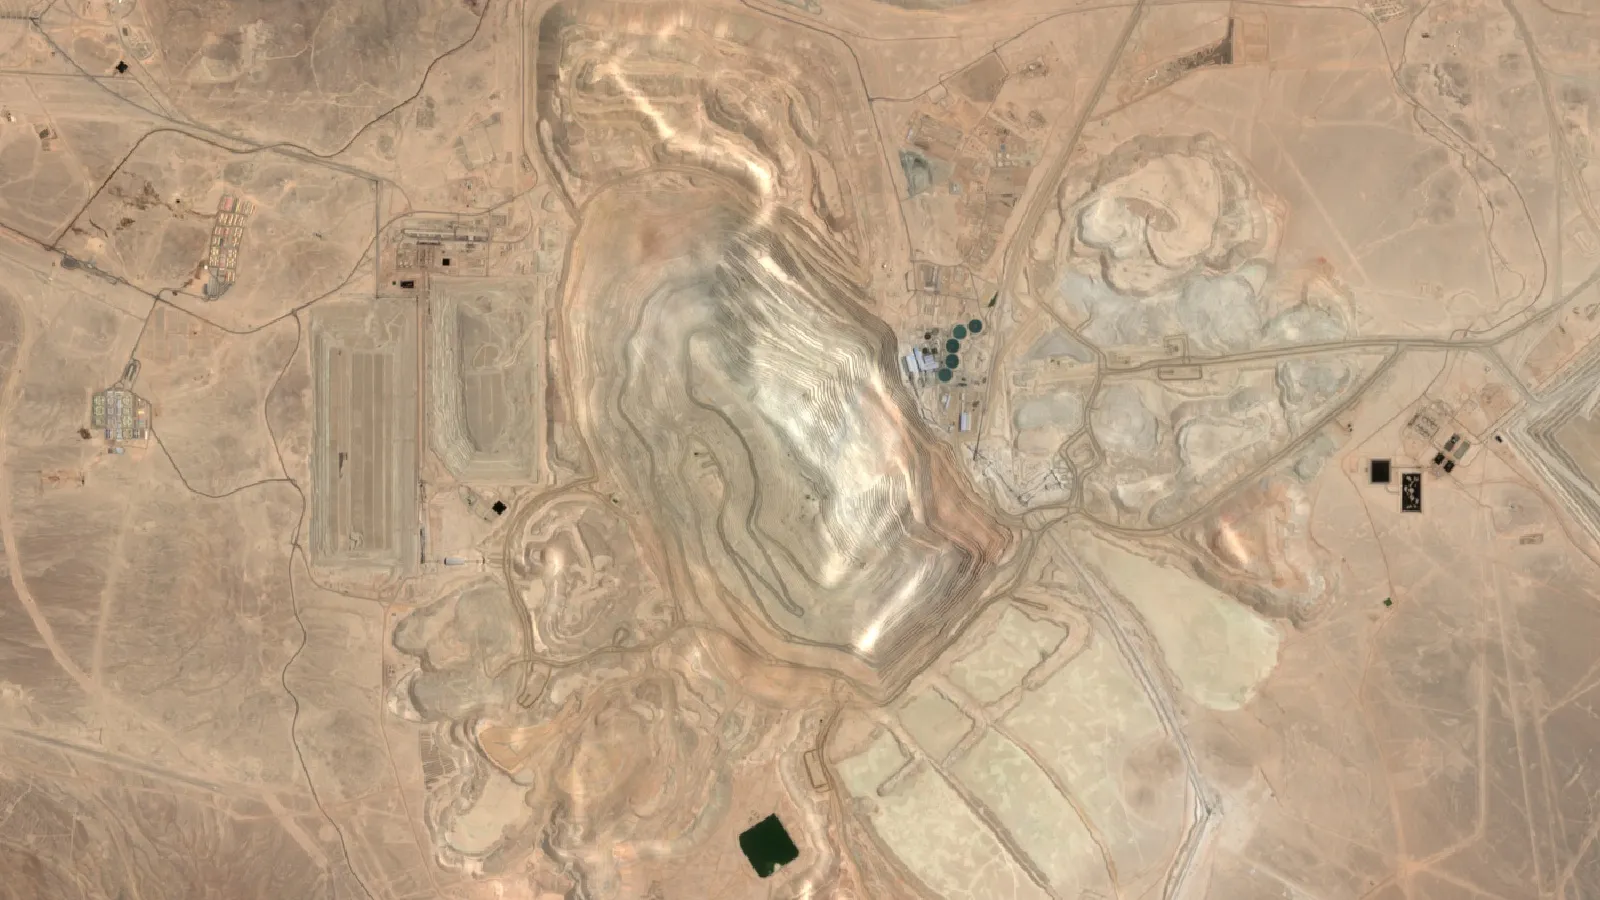
Key takeaways
- Silver’s World Bank average rose from US$23.4 per ounce in 2023 to US$84.0 in January to March 2026, then fell to US$62.9 in July to September.
- Copper averaged US$9,947 per tonne in 2025 and US$14,474 in September 2026 (World Bank, 2 October 2026); the ICSG forecasts a small refined surplus in 2026.
- Nickel is in forecast surplus: 19,000 t in 2026 and 70,000 t in 2027 (INSG, 13 October 2026), and Indonesia mines about 67% of the world total (USGS, 2026).
- Uranium is sold mostly under term contracts; Cameco’s month-end spot was US$89.63 per pound on 30 September 2026, and Kazakhstan mined 39% of 2024 supply (WNA).
- Fund fees range from 0.50% (SLV) to 0.75% (URNM, NIKL) as of October 2026; a miners fund follows companies, not just the metal.
In this article
- Best metals to invest in: how we compare four metals
- Price history side by side
- Copper: supply, demand and ways to hold it
- Silver: industrial demand, investment demand and supply
- Nickel: stainless steel, Indonesia and a surplus
- Uranium: term contracts, reactors and Kazakhstan
- Supply concentration: who mines each metal
- How investors get exposure: ETFs, miners and physical metal
- How much does a metal price move change a miner's margin?
- What the numbers do not tell you
- Frequently asked questions
There is no single best metal to invest in, and this page does not pick one. What it does is put copper, silver, nickel and uranium side by side using dated, sourced numbers: how their prices moved, how much is mined and where, what drives demand, and how an investor can hold each one through funds, mining companies or physical metal. In the World Bank price series, the average silver price in July to September 2026 was US$62.9 per troy ounce, against US$23.4 for the whole of 2023, while nickel averaged US$16,575 per tonne in the same quarter, below its 2023 average of US$21,521. Those two numbers show why the answer depends on what you want and when you look.
This is general information, not investment advice. Metals prices move daily, funds change their holdings, and you should read each fund’s prospectus and the original sources before acting. Where a figure can change, we give the date and the publisher.
Best metals to invest in: how we compare four metals
Most readers comparing metals want one of three things: a metal whose demand looks durable, a metal whose price has been rising, or a way to hold a metal without storing it. These are different questions, and the same metal can look strong on one and weak on another. Nickel, for example, has a clear industrial use in stainless steel, but its annual average price fell for three years in a row from 2023 to 2025. Silver has the opposite pattern: a price that more than tripled from 2023 to the first nine months of 2026 on an average basis, followed by a sharp fall from the January peak.
We compare the four metals named in the title on the same five points, and every point has a source you can open:
- Price history. Annual and quarterly averages from the World Bank Pink Sheet (October 2026 edition), the US Geological Survey (USGS) and, for uranium, Cameco’s month-end spot series.
- Supply. Mine output and the share of the largest producing country, from the USGS Mineral Commodity Summaries and the World Nuclear Association.
- Demand. End uses and forecasts from the International Copper Study Group (ICSG), the International Nickel Study Group (INSG), the Silver Institute and the World Nuclear Association.
- Market balance. Whether the latest forecast shows a surplus or a deficit, and who made the forecast.
- Ways to hold it. Exchange-traded funds (ETFs), mining company shares and physical metal, with fund fees and holdings dated.
We do not rank the metals, give price targets or say which to buy. A metal that is in surplus can still rise if investors buy it, and a metal in deficit can still fall. The table below is a snapshot, not a verdict.
| Metal | 2025 average price | September 2026 price | Largest use | Largest miner’s share of world output | Latest market balance forecast |
|---|---|---|---|---|---|
| Copper | US$9,947 per tonne (LME) | US$14,474 per tonne, monthly average | Building construction, 42% of US use | Chile, 23% (2025 estimate) | Refined surplus of 96,000 t in 2026 and 377,000 t in 2027 (ICSG, April 2026) |
| Silver | US$39.8 per ounce (LBMA) | US$64.6 per ounce, monthly average | Industry, about 58% of 2025 demand | Mexico, 24% (2025 estimate) | Deficit of 46.3 million ounces in 2026 (Silver Institute, April 2026) |
| Nickel | US$15,162 per tonne (LME) | US$16,324 per tonne, monthly average | Stainless and alloy steels, over 85% of US use | Indonesia, 67% (2025 estimate) | Surplus of 19,000 t in 2026 and 70,000 t in 2027 (INSG, October 2026) |
| Uranium | US$73.5 per pound, average of month-end spot values | US$89.63 per pound, spot on 30 September | Fuel for about 440 power reactors (WNA, 2024) | Kazakhstan, 39% (2024) | No single forecast; reactor needs of about 68,920 tU in 2025 (World Nuclear Association) |
Sources: World Bank Pink Sheet, 2 October 2026; Cameco uranium price series; USGS Mineral Commodity Summaries 2026 for copper, silver and nickel. The silver industry share is our calculation from Silver Institute figures: industrial demand of 657.4 million ounces out of 1.13 billion ounces in 2025. The uranium annual average is the simple mean of Cameco’s twelve month-end spot values.
Price history side by side
The chart below sets all four metals to 100 in 2023 so that a US$25,000 metal and a US$25 metal can share one axis. The 2026 point is the average of the January to March, April to June and July to September quarters for the three World Bank metals, and the average of nine month-end values for uranium. Treat it as a nine-month figure, not a full year.
Chart
Price index, 2023 = 100
2026 is a nine-month average
Three patterns stand out. Copper rose in every period shown, to about 58% above its 2023 average. Nickel was lower than its 2023 level in every later period, and its 2026 average was still about 19% below 2023. Silver rose most, from US$23.4 in 2023 to a 2026 nine-month average of about US$73.5, but the quarterly figures show a sharp reversal inside the year: US$84.0 in January to March 2026, US$73.5 in April to June and US$62.9 in July to September. The Silver Institute reports that silver reached an all-time high above US$121 on 29 January 2026 before dropping back to the mid-US$70s by early April.
A longer view shows that these moves are not new. The USGS publishes annual averages that go back to 2021, and the table puts them next to uranium.
| Annual average | 2021 | 2022 | 2023 | 2024 | 2025 (estimate) |
|---|---|---|---|---|---|
| Copper, LME cash, US cents per pound | 422.5 | 399.8 | 384.8 | 414.7 | 440 |
| Nickel, LME cash, US$ per tonne | 18,476 | 25,815 | 21,495 | 16,812 | 15,000 |
| Silver, bullion, US$ per troy ounce | 25.23 | 21.88 | 23.54 | 28.37 | 38 |
| Uranium, US$ per pound U3O8 (Cameco month-end spot, mean) | 35.3 | 49.8 | 62.5 | 85.1 | 73.5 |
USGS figures are from the Mineral Commodity Summaries 2026 chapters for copper, nickel and silver; the 2025 values are USGS estimates and differ slightly from the final World Bank averages. Nickel shows the largest swing: it rose 40% from 2021 to 2022 and then fell by about 42% by 2025. Uranium more than doubled from 2021 to 2024. Past prices do not predict future prices, and an annual average hides large moves inside the year.
Prices on 15 October 2026: silver was quoted at US$56.98 per ounce (bid) at 14:50 New York time on Kitco. Trading Economics, which tracks futures and contracts for difference rather than a physical price, showed copper at US$6.52 per pound (an all-time high of US$6.85 in September 2026) and nickel at US$15,250 per tonne, its lowest since December 2025. Cameco’s series puts uranium spot at US$89.63 per pound at the end of September 2026. These are values seen on 15 October 2026; the linked pages are live and will show different numbers later.
Copper: supply, demand and ways to hold it
Copper is used where electricity is carried, and so demand follows construction, power grids, vehicles and equipment. In the United States, the Copper Development Association’s split, quoted by the USGS, is building construction 42%, electrical and electronic products 23%, transportation equipment 18%, consumer and general products 10% and industrial machinery 7%. Globally, the ICSG expects refined copper use to grow 1.6% in 2026 and 2% in 2027, and it lists energy transition, urbanisation and data centres as supports. Asia outside ASEAN and the former Soviet states used 20.1 million tonnes of the 28.2 million tonnes of refined copper consumed in 2025, so Chinese demand sets much of the tone.
On supply, the USGS puts world mine output at 23 million tonnes in 2025 (estimate), with Chile at 5.3 million, the Democratic Republic of the Congo at 3.2 million and Peru at 2.7 million. Those three produced about 49% of the world total. Reserves are 980 million tonnes, which is roughly 43 years of output at the 2025 rate (our calculation, and reserves change as prices and technology change). The ICSG says mine output will grow only 1.6% in 2026 because of lower expected output in the Democratic Republic of the Congo, Chile and Indonesia, and because the Grasberg and Kamoa mines are still limited after incidents in 2025.
The ICSG’s April 2026 balance is a small refined surplus: 96,000 tonnes in 2026, compared with a deficit of 150,000 tonnes it had forecast in October 2025, and 377,000 tonnes in 2027. The group warns that the balance depends on Chinese stock changes it cannot see and on the conflict in the Middle East. It also says that actual outcomes have, on recent occasions, differed from its forecasts. For deeper background on where copper is found, see our guide to copper deposits, top countries and where to explore and the explanation of porphyry copper deposits, which supply most of the world’s copper.
Ways to hold copper. Physical copper is bulky and low in value per kilogram, so most investors use funds or shares. The United States Copper Index Fund (CPER) tracks an index of COMEX copper futures rather than holding metal, so its return can differ from the spot price. The Global X Copper Miners ETF (COPX) holds mining company shares: on 14 October 2026 it had 40 holdings, a 0.65% total expense ratio and US$6.97 billion in net assets. Individual miners carry their own risks. Freeport-McMoRan (NYSE: FCX) sold 710 million pounds of copper in the second quarter of 2026 at an average realised price of US$6.17 per pound, with unit net cash costs of US$1.97 per pound. A separate guide covers copper stocks and seven risk checks.

▶ Looks at the copper deposits of the Democratic Republic of the Congo and the Central African Copperbelt. · 13:34
Silver: industrial demand, investment demand and supply
Silver is both an industrial input and a store of value, and this is why its price can move for reasons that have nothing to do with factories. The Silver Institute’s World Silver Survey 2026, produced by Metals Focus, found that total demand fell 2% in 2025 to 1.13 billion ounces. Industrial demand fell 3% to 657.4 million ounces, as solar makers cut silver use and substituted other materials, while coin and bar demand rose 14%. Jewellery fabrication fell 8% and silverware 21%. The Institute expects industrial use to be supported by AI infrastructure, cars and power grids, and expects further losses in photovoltaics.
Supply is mostly a by-product. The USGS notes that silver is mainly obtained from lead-zinc, copper and gold mines, in that order of output. The Silver Institute reports that mine production rose 3% to 846.6 million ounces in 2025 and recycling rose 2% to 197.6 million ounces, a 12-year high. In its February 2026 outlook it said that primary silver mines supply only 28% of mine output, which means silver supply often depends on decisions made for copper, zinc or gold. The USGS lists Mexico (6,300 tonnes), Peru (3,600) and China (3,400) as the largest producers in 2025 (estimates).
The Silver Institute counts 2025 as the fifth year in a row in which demand exceeded supply, and in April 2026 it forecast a deficit of 46.3 million ounces in 2026. A deficit is filled from above-ground stocks, so it does not by itself set the price. The price record in 2025 was linked by the same report to a liquidity squeeze and high lease rates in October 2025, which are market-structure events and not a shift in mining.
Ways to hold silver. The iShares Silver Trust (SLV) holds metal: its page shows a 0.50% sponsor fee, the LBMA Silver Price as its benchmark, about 494 million ounces in the trust and net assets of US$28.9 billion on 14 October 2026. Its 52-week net asset value range was US$42.13 to US$107.35, a gap that shows the volatility of the metal itself. The Global X Silver Miners ETF (SIL) holds 39 mining stocks with a 0.65% expense ratio as of the same date. Miners add operating risk: Pan American Silver (NYSE and TSX: PAAS) reported attributable silver output of 6.47 million ounces in the second quarter of 2026 and silver all-in sustaining costs of US$17.80 per ounce. Physical coins and bars are also an option, with dealer premiums and storage costs that vary by seller.
Nickel: stainless steel, Indonesia and a surplus
Nickel’s demand is mostly steel. The USGS says that stainless and alloy steel and nickel-containing alloys typically account for more than 85% of US consumption. Batteries are a smaller and less certain part. The INSG’s October 2026 statement says nickel’s role in the battery market has grown more gradually than anticipated because it competes with lithium iron phosphate chemistries, and that global stainless melt shop output rose 5% in the first half of 2026.
Chart
World nickel market balance
Thousand tonnes, surplus
Supply is the story. The USGS estimates world mine output at 3.9 million tonnes in 2025, of which Indonesia produced 2.6 million, or about 67% (our calculation). New Caledonia produced 140,000 tonnes. Indonesia’s government approved a lower ore quota for 2026 than for 2025, and the INSG notes that applications for 2027 quotas open between 1 October and 15 November 2026. Because one country dominates, a policy change there can move the world price.
The balance has swung. The INSG reports implicit surpluses of 116,000 tonnes in 2024 and 299,000 tonnes in 2025, and forecasts 19,000 tonnes in 2026 and 70,000 tonnes in 2027. In April 2026 it had expected a deficit of 32,000 tonnes for 2026 (Reuters via Kitco), so the latest forecast is a reversal. The INSG also says its figures are uncertain, particularly for Indonesian output. The chart shows the four balances.
Producers feel the squeeze. Eramet reported that the adjusted EBITDA of its nickel activity (excluding SLN) was EUR 95 million in 2025, down 64% from the year before.
Ways to hold nickel. Nickel is the hardest of the four to buy as a simple fund. Metal is traded in 6-tonne futures contracts on the London Metal Exchange, which is a market for professionals. The Sprott Nickel Miners ETF (NIKL) holds mining company shares: its fund documents show 26 holdings and net assets of US$53.7 million on 30 June 2026, a 0.75% total annual operating expense ratio (prospectus, 30 April 2026) and a launch date of 21 March 2023. A small fund can have wider trading spreads, which is a cost to check. Otherwise investors buy shares of diversified miners whose nickel is only part of the business.
Uranium: term contracts, reactors and Kazakhstan
Uranium is not traded like copper. The World Nuclear Association (WNA) explains that most uranium is sold under 3 to 15 year term contracts with utilities, with spot trade a smaller share, about one-quarter in the last decade. Cameco notes that uranium does not trade on an open market and that buyers and sellers negotiate privately, so published prices come from reporting firms (UxC and TradeTech). The same Cameco series gives month-end spot values of US$94.28 per pound in January 2026 and US$89.63 in September 2026. In its first-half 2026 results, Kazatomprom said long-term prices were in the mid-to-high US$90s per pound. That is a producer’s statement, not an independent assessment.
Chart
Uranium mine output by country
Tonnes of uranium, selected countries (Uzbekistan is an estimate)
Demand is fairly predictable because it follows reactor numbers. The WNA’s World Nuclear Fuel Report 2025 estimates reactor requirements at about 68,920 tonnes of uranium (tU) in 2025, rising to just over 150,000 tU in 2040 in its Reference Scenario, with capacity growing from 398 gigawatts in June 2025 to 746 gigawatts. Its Lower and Upper scenarios give 107,000 and 204,000 tU, so the range of outcomes is wide, and it depends on government decisions and construction.
Supply is concentrated. WNA data show that in 2024 mines produced 60,213 tU, of which Kazakhstan supplied 39%, Canada 24% and Namibia 12%, and 55% came from in situ leaching, a method that dissolves uranium underground and pumps it to the surface. The chart compares 2015 with 2024. Canada, Namibia and Uzbekistan produced more; Niger and Australia produced less. Supply risks are specific: Kazatomprom reported that work on its TQZ sulphuric acid plant was suspended after possible fossil finds on the site, which could delay the plant by 6 to 12 months; it said it expected no material effect on mining and would factor the issue into its 2027 production guidance.
Ways to hold uranium. Uranium has two paths that copper and nickel lack. The first is physical uranium held in trusts: the Sprott Physical Uranium Trust (TSX: U.U and U.UN) buys and holds physical uranium for unit holders. Check each trust’s own documents for its holdings. The second is mining shares. The Global X Uranium ETF (URA) has 60 holdings and a 0.69% expense ratio as of 14 October 2026, and the Sprott Uranium Miners ETF (URNM) shows a 0.75% total annual operating expense ratio (prospectus, 30 April 2026) and, in its 30 June 2026 report, 27 holdings, net assets of US$1.90 billion, Cameco as a large share holding and a 13% position in the Sprott Physical Uranium Trust. Cameco guides to 19.5 to 21.5 million pounds of U3O8 from its own operations in 2026, according to its second-quarter 2026 report.
▶ Short clay-animation explainer on the Kanyemba uranium deposit in Zimbabwe, which has no working mine, as one example of uranium in Africa. · 4:27
Supply concentration: who mines each metal
For a metal investor, concentration matters because one country’s tax change, export rule or accident can move the price. The chart shows the share of world mine output from the single largest producing country. Nickel is the most concentrated, with Indonesia at about two-thirds of the world total. Copper and silver are more spread out, though each metal’s largest producer is still close to a quarter of supply. The uranium figure is for 2024, and the others are USGS estimates for 2025. We calculated each share from the published country and world totals.
Chart
Largest producer’s share of world mine output
Percent; uranium 2024, others 2025 estimate
A second concentration point is the processing step. Mines are only the first stage: the USGS data show China producing 14 million tonnes of refined copper in 2025 (estimate) against 1.8 million tonnes of mined copper, which means refiners buy concentrate from other countries. A reader who wants a full picture should look at refining capacity as well as mine output.
How investors get exposure: ETFs, miners and physical metal
There are three common routes, and they carry different risks. A fund that holds metal (SLV for silver, or a uranium trust) follows the metal price less fees. A fund that holds miners follows company results, which depend on prices, costs, mine accidents, taxes and debt. Futures-based funds follow a contract and can lag the spot price when contracts roll. The table gives dated fund facts for each metal.
| Metal | Holds metal | Holds miners | Cost data (date) |
|---|---|---|---|
| Copper | CPER holds COMEX copper futures through an index, not metal | COPX, 40 holdings | COPX 0.65% (14 October 2026) |
| Silver | SLV holds about 494 million ounces | SIL, 39 holdings | SLV 0.50% sponsor fee; SIL 0.65% (14 October 2026) |
| Nickel | No physical-nickel fund covered here | NIKL, 26 holdings (30 June 2026) | NIKL 0.75% (prospectus, 30 April 2026) |
| Uranium | Sprott Physical Uranium Trust; Yellow Cake plc | URA, 60 holdings; URNM, 27 holdings (30 June 2026) | URA 0.69% (14 October 2026); URNM 0.75% (prospectus, 30 April 2026) |
Fund fees are an annual percentage of assets, so they build up. A 0.65% fee on US$10,000 costs about US$65 a year at the start; the calculator below handles a different question, which is how a metal price move changes the profit of a mining company that sells it. Mining shares react more strongly than the metal because most of a mine’s costs are fixed. If a miner’s cash cost is US$2 per pound and copper falls from US$6 to US$5, the price falls 17% but the cash margin falls 25%. Freeport’s guidance gives a real example of the cost base: the company expects unit net cash costs of about US$1.90 per pound of copper for 2026.
How much does a metal price move change a miner’s margin?
Use the calculator to test your own numbers: the volume a mine sells, its cash cost per pound, and a price now and a price after a move. Defaults are round example values, not a benchmark and not any company’s figures. Enter today’s price from a live source. The calculator is written for pounds of copper; for another metal, use the same unit for price and cost, such as US$ per ounce for silver.
Calculator
How does a price move change a miner’s margin?
Enter your own numbers. Results update as you type.
- Margin per lb now: $4
- Margin per lb after: $3
- Price change: -16.7
- Annual cash margin change (US$ million): -$1,000
Example values only, not a benchmark and not any company’s figures. Prices are inputs: example, use today’s price. Freeport-McMoRan reported unit net cash costs of US$1.97 per pound of copper in Q2 2026 (company release). Money in US$.
What the numbers do not tell you
Price history is one input, not a forecast. Four limits are worth knowing before reading any list of the best metals to invest in.
- Averages hide swings. Silver’s quarterly average fell from US$84.0 to US$62.9 inside nine months in 2026, and SLV’s 52-week range was US$42.13 to US$107.35.
- Forecasts get revised. The INSG turned a 32,000-tonne nickel deficit forecast into a 19,000-tonne surplus in six months, and the ICSG turned a 150,000-tonne copper deficit into a 96,000-tonne surplus. The Silver Institute’s 2026 deficit forecast moved from 67 million ounces in February to 46.3 million ounces in April.
- Funds are not the metal. A miners fund holds companies, a futures fund holds contracts, and a trust holds metal. Each can differ from the headline price.
- Costs and tax are personal. Fees, trading spreads, taxes on gains and currency effects depend on where you live and how you buy. Ask a licensed adviser about your own case.
For readers who work on the supply side, the same metals begin as exploration targets. Farmonaut screens licence areas from satellite data for copper, nickel, uranium and other minerals, which helps decide where to send crews. It says nothing about metal prices and is not a resource estimate. If you are weighing a project rather than a fund, see our note on what mining investors check, or request a quote or contact the team.
Related reading on this site: Silver Supply Shortage: Deficit Data and Causes.
We cover a connected topic in Wheaton vs Pan American Silver: Output, Costs, Risk.
Frequently asked questions
Which is the best metal to invest in: copper, silver, nickel or uranium?
No source can answer that for every investor, and this page does not rank them. The sourced facts differ: copper demand is tied to construction and power, silver has a large investment component, nickel is in forecast surplus, and uranium is sold mostly under term contracts. Your time horizon, risk limit and tax position decide which facts matter.
Should investors choose copper over silver?
The two behave differently. From 2023 to the first nine months of 2026, the average copper price rose about 58% on the World Bank series, and silver rose about 214%, but silver fell about 25% from its January to March average to July to September. Copper is used up in buildings and wires, while silver demand is split between industry and investors. Neither history guarantees a future result. This is not investment advice.
How do I invest in nickel?
The options are shares of mining companies, a small miners ETF (NIKL, 0.75% expense ratio, US$53.7 million in net assets on 30 June 2026), or London Metal Exchange futures, which are aimed at professional traders. Check each fund’s holdings, spreads and fees before using it.
Is nickel in surplus or deficit?
The INSG’s 13 October 2026 statement shows surpluses of 299,000 tonnes in 2025, 19,000 tonnes in 2026 and 70,000 tonnes in 2027. In April it had expected a 2026 deficit of 32,000 tonnes. The group says Indonesian production is the main uncertainty.
Is silver mostly an industrial metal or an investment metal?
Both. The Silver Institute reports industrial demand of 657.4 million ounces in 2025, about 58% of total demand of 1.13 billion ounces, and a 14% rise in coin and bar demand. Both parts matter to the price.
Why do uranium prices differ between sources?
There is no open exchange price. Reporting firms such as UxC and TradeTech publish spot and long-term indicators from surveys, and futures prices may differ. Cameco’s month-end spot was US$89.63 per pound on 30 September 2026, while Kazatomprom described long-term prices in the mid-to-high US$90s.
Can I buy physical uranium?
Individuals rarely hold uranium directly because buying, storing and moving it is regulated and costly. Trusts such as the Sprott Physical Uranium Trust hold it on behalf of unit holders, and shares can be bought on stock exchanges. Read the trust’s documents for how metal is held, priced and sold.
What is the difference between a metal ETF and a miners ETF?
A metal ETF, such as SLV, holds the metal and aims to follow its price less fees. A miners ETF, such as COPX, SIL, URA, URNM or NIKL, holds company shares, so its result depends on company costs, debt and management as well as the metal price. A futures ETF, such as CPER, holds contracts.
Does the “world surplus” or “deficit” decide the price?
Not on its own. The ICSG says its copper balance can shift with unreported Chinese stocks, and the Silver Institute notes that silver deficits are filled from above-ground stocks. Prices also respond to investor buying, interest rates and currency moves.
Where can I check current metal prices?
Use the London Metal Exchange for copper and nickel, the LBMA for silver, and UxC, TradeTech or Cameco’s published series for uranium. The World Bank Pink Sheet gives monthly averages for copper, nickel and silver. Always note the date and the contract when you copy a price.
Is this page investment advice?
No. It is general information based on public sources, last reviewed on 16 October 2026. It does not consider your goals or finances. Not investment advice.
This page is for information only. It is not investment advice. Prices and fund data are dated and change daily; read each fund’s prospectus before acting.
Farmonaut mining
Screen a project area from space before you invest in exploration
Send a KML, KMZ or polygon and Farmonaut screens the area from satellite data in 5 to 20 business days.

Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026: Copper: pubs.usgs.gov
- USGS, Mineral Commodity Summaries 2026: Silver: pubs.usgs.gov
- USGS, Mineral Commodity Summaries 2026: Nickel: pubs.usgs.gov
- World Bank, Commodity Price Data (Pink Sheet), 2 October 2026: thedocs.worldbank.org
- ICSG press release, Copper Market Forecast 2026/2027 (23 April 2026): icsg.org
- INSG press release, October 2026 meetings (13 October 2026): insg.org
- Silver Institute, World Silver Survey 2026 release (15 April 2026): silverinstitute.org
- Silver Institute, 2026 outlook (10 February 2026): silverinstitute.org
- World Nuclear Association, World Uranium Mining Production: world-nuclear.org
- World Nuclear Association, World Nuclear Fuel Report 2025: world-nuclear.org
- World Nuclear Association, Uranium Markets: world-nuclear.org
- Cameco, Uranium Price series: cameco.com
- Cameco, 2026 Q2 report: cameco.com
- Kazatomprom, 1H2026 financial results: kazatomprom.kz
- Freeport-McMoRan, Q2 2026 earnings release: s22.q4cdn.com
- Pan American Silver, Q2 2026 report: panamericansilver.com
- Eramet, 2025 full-year results: eramet.com
- Global X, COPX: globalxetfs.com
- Global X, SIL: globalxetfs.com
- Global X, URA: globalxetfs.com
- iShares Silver Trust (SLV): ishares.com
- USCF, United States Copper Index Fund (CPER): uscfinvestments.com
- Sprott Funds Trust, prospectus (485BPOS, 30 April 2026): URNM and NIKL: sec.gov
- Sprott Funds Trust, semi-annual report (N-CSRS, 30 June 2026): sec.gov
- Kitco, silver price (15 October 2026): kitco.com
- Trading Economics, copper: tradingeconomics.com
- Trading Economics, nickel: tradingeconomics.com
- The Northern Miner, Sprott Physical Uranium Trust: northernminer.com
- Kitco/Reuters, Global nickel market set for surplus this year and next, INSG says (13 October 2026): kitco.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 CIMISCO SARL
 Mining SARL
 SenGold Invest SAS
 Sania Corporation
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE











