

Copper market · Forecast comparison
Copper Supply and Demand Forecast Compared
The ICSG expects a refined copper surplus of 368,000 tonnes in 2027; BMO and BMI expect deficits. This page compares the published supply, demand and price forecasts, explains the gap, and lets you test a price move on a mine’s margin.
Key takeaways
- The ICSG (14 October 2026) forecasts refined copper surpluses of 104,000 t in 2026 and 368,000 t in 2027, with usage growth of 1.5% and 2.5%.
- The four 2027 average price forecasts in the table range from about US$11,240/t (Cochilco, August 2026) to US$14,675/t (BMO, October 2026).
- The split comes from US stocks of 1.5 to 2 million t: Macquarie counts them as surplus, BMO as metal moved from hidden stocks to visible US warehouses (Mining.com, 14 October 2026).
- Chile, Congo and Peru mined about 49% of the world’s copper in 2025 (USGS estimate), so single mine outages move the balance.
- The IEA sees the 2035 supply gap narrowing to about 25% from about 30%, based on the project pipeline (IEA, 2026).
In this article
- Copper supply and demand forecast: the short answer
- What the ICSG forecasts for mines, refineries and users
- Copper price forecasts from banks and Cochilco compared
- Why the forecasts disagree: the US stockpile and the tariff decision
- Where copper supply comes from and what can go wrong
- Copper price history behind the forecasts
- Copper demand drivers: where the extra tonnes are used
- How analysts turn supply and demand into a price forecast
- What a price change does to a mine's cash margin
- Long-run supply gap, recycling and the search for new mines
- What to watch next in the copper market
- Frequently asked questions
Copper supply and demand forecast: the short answer
The two big forecasters disagree on direction. The International Copper Study Group (ICSG), the intergovernmental body that tracks the market, said on 14 October 2026 that it expects a surplus of refined copper: 104,000 tonnes in 2026, widening to 368,000 tonnes in 2027 (Canadian Mining Journal, 14 October 2026). Goldman Sachs and BMO, by contrast, see a tighter market outside the United States, because 1.5 to 2 million tonnes of metal now sit in US warehouses (Mining.com, 14 October 2026).
Price forecasts for 2027 span a wide range as a result. Cochilco, Chile’s copper commission, projects an average of US$5.10 per pound (about US$11,240 per tonne), while BMO Capital Markets projects US$14,675 per tonne. This page lays out both sets of numbers side by side, explains why they differ, and gives a calculator so you can test what a different price would do to a mine’s cash margin. Copper is measured in tonnes (t, metric) and in pounds (lb); one tonne is 2,204.62 lb.
All figures below carry a date. Forecasts change every quarter.
What the ICSG forecasts for mines, refineries and users
The ICSG publishes its outlook twice a year, in April and October. The October 2026 edition, agreed at meetings in Lisbon, covers three parts of the chain: mines that dig ore, smelters and refineries that turn it into cathode (refined copper), and the factories that use cathode (Canadian Mining Journal).
Chart
ICSG growth forecasts for 2027
Per cent growth in 2027 over 2026
| Measure (ICSG, 14 October 2026) | 2026 | 2027 |
|---|---|---|
| World mine production growth | 1.3% (April estimate: 1.6%) | 3.1% |
| Refined production growth | 0.4% | 3.4% |
| Refined usage growth | 1.5% | 2.5% |
| Refined balance | surplus of 104,000 t | surplus of 368,000 t |
The 2026 mine estimate was cut because of lower output in Chile, China and Indonesia. Grasberg in Indonesia and Kamoa-Kakula in the Democratic Republic of Congo are still limited after incidents in 2025. Growth is coming from Oyu Tolgoi in Mongolia, Batu Hijau in Indonesia and Antamina in Peru, among others. For 2027 the ICSG expects the recovery at Grasberg and Kamoa-Kakula, plus better output in Chile and Zambia, to lift mine growth to 3.1%.
The ICSG lists the energy transition, urbanisation, digitalisation and AI infrastructure such as data centres as longer-term demand drivers, with Asia the main source of growth. It also warns that its numbers are vulnerable to supply disruptions and to the conflict in the Middle East, and that its estimate of Chinese demand leaves out changes in unreported stocks held by state agencies, producers and traders (Canadian Mining Journal).
A surplus in these tables is a statistical gap of a few hundred thousand tonnes in a market of roughly 28 million tonnes of usage a year. Cochilco puts its own 2026 surplus at 225,000 tonnes, or 0.8% of demand, and says that is too small to describe oversupply (Miningreporters, 21 August 2026).
Copper price forecasts from banks and Cochilco compared
The table lists the forecasts in published reports, with the date of each report. Averages are annual; “year-end” and “within a year” are targets for a point in time and are not the same thing. Cochilco quotes US cents or dollars per pound, so we converted its figures to US$ per tonne.
Chart
Average copper price forecasts, 2026 and 2027
US$ per tonne; Cochilco converted from US$ per pound
| Forecaster and date | 2026 | 2027 | Market balance view |
|---|---|---|---|
| Macquarie, October 2026 | US$13,573/t average | US$12,750/t average | 223,000 t surplus in 2026; more than 700,000 t a year from 2027 |
| BMO Capital Markets, October 2026 | US$13,619/t average | US$14,675/t average | 83,000 t surplus in 2026; small deficits from 2027 |
| BMI (Fitch Solutions), October 2026 | US$13,500/t average | US$12,900/t average | 43,000 t surplus in 2026; deficit from 2027 |
| Cochilco, second-quarter report, August 2026 | US$5.95/lb (about US$13,120/t) | US$5.10/lb (about US$11,240/t) | 225,000 t surplus in 2026; 179,000 t in 2027 |
| Goldman Sachs, 1 June 2026 | US$13,735/t at year-end | not stated in the cited report | deficit of 640,000 t outside the US in 2026 |
| Citi, 1 June 2026 | US$14,500/t within a month of 1 June 2026 | US$15,000/t within a year of 1 June 2026 | not stated in the cited report |
The Macquarie, BMO and BMI figures come from a Mining.com round-up published on 14 October 2026. The year-to-date average that these 2026 forecasts are being compared with was US$13,471 per tonne (Mining.com). Cochilco raised its 2026 forecast from US$5.55 per pound in May to US$5.95 in August, and kept 2027 at US$5.10 (Kitco/Reuters, 19 May 2026); the table uses its second-quarter report (Miningreporters). Goldman’s year-end target rose to US$13,735 from US$12,465 on 1 June 2026, after it cut its 2026 mine supply forecast by 350,000 tonnes (Economies.com, 1 June 2026). In a note dated 1 June 2026, Citi forecast US$14,500 per tonne within a month and US$15,000 within a year (CNBC, 1 June 2026). This page records published forecasts; it makes no prediction and gives no advice.
Why the forecasts disagree: the US stockpile and the tariff decision
Most of the gap comes from one question: is the copper piled up in the United States a surplus or a reserve? Mining.com writes that the forecasters’ differences open up from 2027 and “come down to how much of the 1.5 to 2 million tonnes of copper now sitting in the United States is counted as surplus” (Mining.com).
- Macquarie treats the stock as surplus. It expects mine supply to grow 4.9% in 2027 and 4.3% in 2028, and global demand growth to slow to 1.5% in 2027. It calls the market “very binary” because the US Section 232 trade review could go either way.
- BMO reads the stock as metal that moved from hidden stocks, such as China’s strategic reserve, to visible US warehouses. On that view, today’s price is “fundamentally supported”, and it raised its long-term price by 47% to US$16,000 per tonne in real terms.
- BMI sits between them: it still sees the rally as running ahead of fundamentals but expects a deficit from 2027, widening to 1.7 million tonnes by 2035 as demand grows 3% to 4% a year.
The tariff matters because copper in the US and copper in London have traded at different prices. Comex, the New York futures market, set a record settlement of US$6.89 per pound on 9 September 2026, then fell more than 5% the next day after a report that the White House tariff plan had stalled. Macquarie’s four scenarios run from no announcement at all (which it rates most likely) to a firm decision against a duty (least likely), in which “the CME price will most likely collapse”. BMO expects no decision before the US midterm elections in November (Mining.com).
The US Geological Survey adds context on how much copper the US makes and uses. US mines produced an estimated 1.0 million tonnes in 2025, and net import reliance was 57% of apparent consumption (USGS, Mineral Commodity Summaries 2026). Copper was added to the 2025 US critical minerals list in November 2025.
Where copper supply comes from and what can go wrong
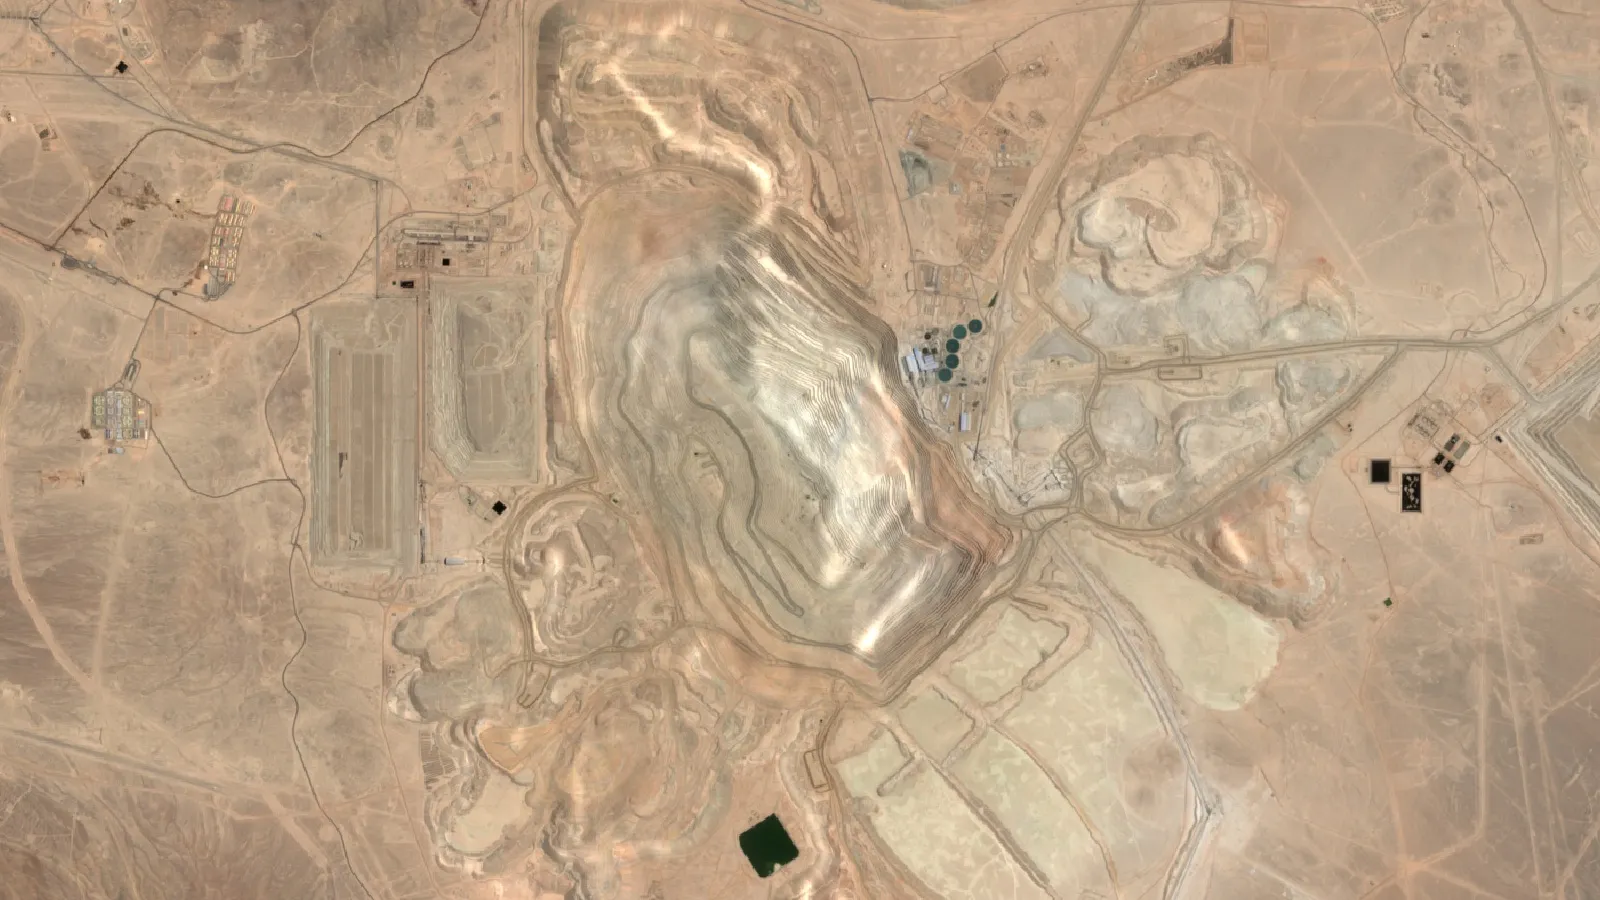
Copper mining is concentrated. Chile, the Democratic Republic of Congo and Peru together produced an estimated 11.2 million tonnes of the world’s 23 million tonnes in 2025, about 49% (USGS, 2026 estimates). Chile’s output fell from 5.51 to an estimated 5.30 million tonnes between 2024 and 2025, while Congo rose from 2.99 to 3.20 million tonnes (USGS).
Chart
Copper mine production by country
Thousand tonnes of contained copper, 2025 estimate
Because supply is concentrated, single events move the balance. Cochilco expects world mine output to grow only 0.2% in 2026, to 23.57 million tonnes, with Indonesia down 18.9% as Grasberg recovers and Kamoa-Kakula faces geotechnical and water problems. Output is projected to rebound 3.8% in 2027 (Miningreporters). In mid-October 2026, workers at Antofagasta’s Centinela had just returned to talks after a week-long stoppage, the open pit at Codelco’s El Teniente remained shut after a deadly landslide, and BHP’s Escondida, the world’s largest copper mine, had a preliminary deal to avert a strike, which supervisors approved on 15 October (Mining.com).
Smelters are under strain too. A smelter treats concentrate (the product of a mine’s mill) and charges the miner a fee. The International Energy Agency (IEA) reports that the benchmark smelter fee was settled at US$0 per tonne for 2026, the lowest ever agreed, and spot charges have been negative since 2024 (IEA, Global Critical Minerals Outlook 2026). Cochilco records spot values as low as minus 40.45 US cents per pound against a historical average of 20.7. That means concentrate is scarce while smelting capacity is growing; the ICSG expects the 2027 recovery in mine output to ease the shortage.
For a look at the types of ore body behind this supply, see our guide to copper deposits, top countries and where to explore and the one on porphyry copper deposits, the type that supplies most of the metal from Chile.
Copper price history behind the forecasts
The forecasts start from a price that has risen sharply. The USGS records the London Metal Exchange (LME) grade A cash price averaging 384.8 US cents per pound in 2023 and an estimated 440 cents in 2025 (about US$9,700 per tonne). In 2026 the metal averaged US$13,471 per tonne to 14 October, and LME cash copper settled at a record US$14,822 per tonne on Monday 12 October 2026 (Mining.com). The IEA says base-metal prices, including copper, rose by one-third between January 2025 and April 2026 (IEA).
Chart
Average LME copper price, 2021 to 2026
US$ per tonne; 2025 is a USGS estimate; 2026 is the year-to-date average to 14 October as stated by Mining.com (benchmark not named)
For a view of the price itself, with a chart of the drivers, read our page on the copper price per tonne, and for the longer view our copper price outlook. Prices in this article are snapshots with the date shown; the LME and Comex publish the current number.
Copper demand drivers: where the extra tonnes are used
Copper is used in wiring, motors, transformers, grids, pipes and electronics. In the United States, the Copper Development Association’s split of copper and copper-alloy products was building construction 42%, electrical and electronic products 23%, transportation equipment 18%, consumer and general products 10% and industrial machinery 7% (USGS). Those shares are for the US only and do not describe the world.
Globally, China matters most. Cochilco expects world refined demand of 27.86 million tonnes in 2026, up 1.9%, with China taking 57.6% of it, or 16.05 million tonnes (Miningreporters). Macquarie expects no growth at all in Chinese demand in 2027, because construction-related copper use is shrinking about 9% a year and air-conditioner makers are looking again at aluminium. Demand from grid expansion, electric vehicles and data centres is the growth story elsewhere; BMI assumes 3% to 4% a year in the longer run.
Electric vehicles use more copper than petrol cars because of their motors, batteries and charging cables. Our short explainer follows a car’s copper from a pit in Chile to the driveway.
Mines are also copper users: electric drills, haul trucks and conveyors need cable and motors. Our article on electrification of mining equipment covers the benefits, and the page on global copper demand in million metric tons gives earlier history.
▶ Follows an electric car’s copper from a hole in Chile to the driveway. · 6:03
How analysts turn supply and demand into a price forecast
A balance forecast is only the first step. Analysts then ask how much stock the market holds, how costly the marginal tonne is, and which policy risks could shift metal between regions. The steps below show the order most forecasters follow.
Infographic
A copper forecast in 4 steps
- 1Count mine supplyStart from the project pipeline, then subtract an allowance for strikes, accidents and falling ore grades.
- 2Add refining and scrapSmelter capacity and recycled metal decide how much concentrate becomes cathode.
- 3Estimate usageBuild demand by region from grids, buildings, vehicles and data centres, with China as the largest block.
- 4Adjust for stocks and policyDecide which exchange and warehouse stocks count, and what a tariff would do to flows, then read off a price.
What a price change does to a mine’s cash margin
Forecast ranges matter most to the people who run mines. A mine selling concentrate receives a percentage of the contained copper (the payable share) and pays cash costs per pound of copper sold. The calculator below turns a price and a price move into revenue and a cash margin before tax, depreciation, royalties and capital spending. All inputs are examples. Use today’s price and your own costs.
Calculator
What does a copper price move do to a mine’s cash margin?
Enter your own tonnes, price, payable share, cash cost and price move.
- Annual cash cost (US$): $440,924,000
- Cash margin at your price (US$): $807,076,000
- Cash margin after the price move (US$): $619,876,000
- Break-even price (US$/t): $4,593
Example values only, not any company’s figures. Prices are inputs: example, use today’s price (US$ per tonne). 1 tonne = 2,204.62 lb. Result is cash margin before tax, royalties, depreciation and capital spending.
Long-run supply gap, recycling and the search for new mines
The IEA’s 2026 outlook projects that copper supply from today’s project pipeline will fall short of demand in 2035 by about 25%, narrower than the roughly 30% in its 2025 edition because projects in the Democratic Republic of Congo and Zambia advanced (IEA). That is a pipeline gap, not a forecast of what will happen: new projects, scrap and efficiency can close part of it. The IEA expects secondary supply (recycling) to double its contribution by 2040 under current policies, with average recycling rates for key energy minerals rising from about 10% to close to 20%.
Investment is moving toward copper. Spending by copper-focused companies rose 8% in 2025, even though total critical mineral investment fell 9%, and exploration spending on copper was steady while lithium and nickel exploration fell about 45% (IEA). Strong demand for high-quality copper assets drove a 20% rise in overall deal value in 2025.
Finding new tonnes is slow and expensive, and a hole in the wrong place costs as much as one in the right place. Satellite imagery is one way explorers narrow a large licence area before they send crews or drill rigs. Farmonaut’s satellite mineral detection reports screen an area for exploration targets ahead of a resource estimate. They do not replace drilling.
▶ Shows how satellite data narrows where to drill, using memes and a plain explainer. · 4:26
What to watch next in the copper market
- The US Section 232 copper decision. BMO expects no decision before the November midterm elections; Macquarie rates a quiet 1 January with no announcement as its most likely case. A surprise either way would move the gap between Comex and LME prices.
- Escondida labour talks. BHP and Escondida’s supervisors reached a three-year labour deal, which supervisors approved on 15 October 2026 (Miningreporters).
- Grasberg and Kamoa-Kakula restarts. Goldman does not expect either mine at full capacity before 2028 (Economies.com), while ICSG expects a recovery in 2027.
- Chinese demand and scrap. China’s secondary refined output is heading for 3.3 million tonnes this year from 2.8 million (BMO, via Mining.com).
- The next ICSG and Cochilco updates. The ICSG publishes its next forecast in April; Cochilco reports quarterly.
Frequently asked questions
Will there be a copper surplus or a deficit in the coming years?
The ICSG forecasts a refined surplus of 104,000 tonnes in 2026 and 368,000 tonnes in 2027 (14 October 2026). Cochilco shows surpluses too, of 225,000 and 179,000 tonnes. BMO and BMI expect deficits from 2027. The answer depends on how forecasters count the stock held in the United States.
What is the copper supply forecast for the next two years?
The ICSG expects world mine production to grow 1.3% in 2026 and 3.1% in 2027, and refined production to grow 0.4% and 3.4%. Cochilco is lower for 2026 at 0.2% mine growth and higher for 2027 at 3.8%.
What is the copper demand forecast?
ICSG expects refined usage to grow 1.5% in 2026 and 2.5% in 2027. Cochilco puts 2026 demand at 27.86 million tonnes, up 1.9%. Macquarie expects 1.5% global growth in 2027 with no growth in China.
What is the copper price forecast?
The four 2027 averages in the table range from about US$11,240 per tonne (Cochilco) to US$14,675 per tonne (BMO), with Macquarie at US$12,750 and BMI at US$12,900 (reports dated August and October 2026). Citi, in June 2026, forecast US$15,000 within a year.
Why is copper so expensive now?
Cochilco and the IEA point to constrained mine supply, lower ore grades and disruptions at large mines such as Grasberg and Kamoa-Kakula, together with demand from grids, electrification and data centres. Tariff uncertainty has also pulled metal into the United States.
How big is the copper supply gap?
The IEA says that, based on the project pipeline, supply would fall about 25% short of demand in 2035, down from about 30% in its previous outlook. It treats this as a gap that policy, recycling and new projects could narrow.
Which countries mine the most copper?
Chile mined an estimated 5.3 million tonnes in 2025, followed by the Democratic Republic of Congo at 3.2 million, Peru at 2.7 million and China at 1.8 million (USGS, 2026).
How much copper does the world use each year?
Cochilco puts 2026 refined demand at 27.86 million tonnes (August 2026 report), with China taking 57.6% of it. The ICSG and Cochilco measure usage differently, so compare each forecaster only with itself.
What is a copper tariff and why does it move prices?
A tariff is a tax on imports. The US has been deciding whether to apply one to refined copper. Uncertainty has led buyers to ship metal to the US early, which tightened supply elsewhere and widened the gap between New York and London prices (Citi and Macquarie, via CNBC and Mining.com).
How can I test what a price move does to a copper mine?
Use the calculator on this page. Enter annual tonnes, a price, the payable share, your cash cost per pound and a percentage price move to see revenue, cash margin and break-even price.
This page is for information only. It is not investment advice. It reports published forecasts and gives no price targets or recommendations.
Farmonaut mining
Screen a licence area from space
Investors can see how satellite data screens a licence area for copper exploration targets, ahead of a resource estimate.

Mining Pro sample view, synthetic data
Keep reading
Sources
- Canadian Mining Journal, Global copper surplus to more than triple by 2027: ICSG (14 Oct 2026): canadianminingjournal.com
- Mining.com, Copper price forecasts lifted for 2026 but tariff collapse still on the table (14 Oct 2026): mining.com
- Miningreporters, Cochilco forecasts copper at $5.95 in 2026, declining to $5.10 in 2027 (21 Aug 2026): miningreporters.com
- Kitco/Reuters, Cochilco raises 2026 copper price forecast (19 May 2026): kitco.com
- CNBC, Citi turns bullish on copper (1 Jun 2026): cnbc.com
- Economies.com, Goldman Sachs and Citi raise copper price forecasts (1 Jun 2026): economies.com
- IEA, Global Critical Minerals Outlook 2026, executive summary: iea.org
- USGS, Mineral Commodity Summaries 2026: Copper: pubs.usgs.gov
- International Copper Study Group, press releases: icsg.org
- Mining.com.au, ICSG sees global refined copper surplus widening in 2027 (15 Oct 2026): mining.com.au
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa











