

Lithium triangle · Country comparison
South American Lithium Mining Challenges by Country
South American lithium mining challenges centre on water, brine chemistry and Indigenous consent, and they differ by country. USGS counts 64 of the world’s 150 million tonnes of lithium resources in Argentina, Bolivia and Chile. This guide compares the three with dated, sourced figures.
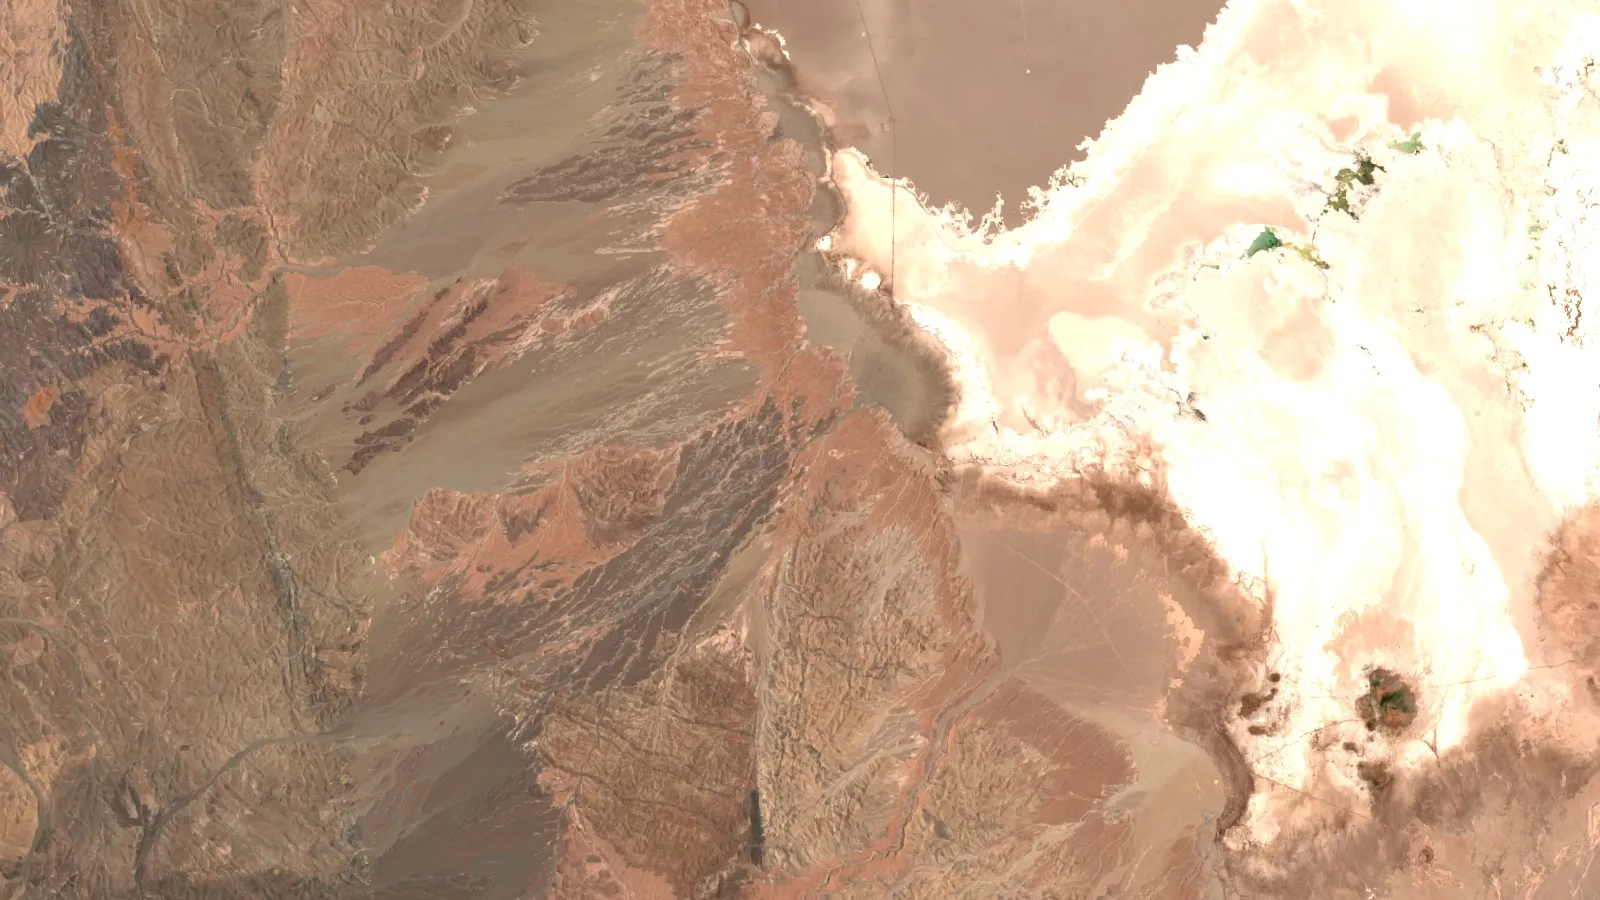
Key takeaways
- The lithium triangle holds about half of the world’s lithium deposits, according to ESA; USGS resource figures for Argentina, Bolivia and Chile total 64 of about 150 million tonnes, or about 43% (2026).
- Chile produced an estimated 56,000 t of lithium in 2025 and Argentina 23,000 t, up from 13,800 t in 2024; Bolivia has no commercial-scale output (USGS lists no figure; Harvard Growth Lab, 2026).
- Water footprints measured at two Argentine sites run from 51.0 to 135.5 m3 per tonne of carbonate, and part of the Atacama salt flat is sinking 1 to 2 cm a year (peer-reviewed studies, 2024-2025).
- Brine chemistry differs: the magnesium-to-lithium ratio is about 19:1 at Uyuni, 6:1 at Atacama and 1:1 at Hombre Muerto, so processing difficulty and cost vary (Harvard Growth Lab, 2026).
- Consent is contested in all three countries: Chile’s 25 community agreements give no veto, Argentina’s Supreme Court is hearing the Salinas Grandes case, and in Bolivia a 2025 court suspension of two contracts was lifted within days, while Congress has still not approved them.
In this article
- Lithium triangle in South America: who holds and produces what
- Water challenges: how brine lithium uses a desert aquifer
- Brine chemistry and extraction hurdles
- Chile: the Atacama and a state-majority model
- Argentina: provincial permits, court cases and fast growth
- Bolivia: Uyuni, state control and stalled contracts
- Community rights and consent in the lithium triangle
- Price swings and who carries the risk
- Challenges compared: Chile, Argentina and Bolivia
- What satellite data shows about brine operations
- Due diligence checklist for a salar project
- Frequently asked questions
The main challenges of South American lithium mining are water, brine chemistry and community consent, and they differ in each country of the lithium triangle. Chile pumps brine from a desert basin where parts of the ground are sinking. Argentina is growing fast while courts test its permits. Bolivia holds large resources but has not reached commercial output. The European Space Agency says the triangle holds about half of the world’s lithium deposits, and USGS resource figures for Argentina, Bolivia and Chile add up to roughly 43% (ESA, 2026; USGS, 2026).
This guide is written for consultants, licence holders and investors who need the facts behind the headlines. Each figure carries its source and date, claims that are disputed are marked as disputed, and the sections follow the questions people search most: where the triangle is, how brine mining uses water, why brine chemistry matters, and how each country handles Indigenous consultation. For the geology of brine, pegmatite and clay deposits, see our guide to lithium deposit types.
Lithium triangle in South America: who holds and produces what
The lithium triangle is the high-altitude Andean plateau where Chile, Argentina and Bolivia meet. Its lithium sits in brine, a salty groundwater that fills the pore space under dry salt flats called salars. The International Institute for Sustainable Development (IISD) lists salar-brine deposits as 57% of global lithium reserves by deposit type, with hard-rock pegmatites at 26% (IISD commodity profile, 2026).
Chart
Lithium resources by country
Million tonnes of contained lithium, measured and indicated, selected countries
The three countries are at very different stages. Chile has produced from the Salar de Atacama for decades. Argentina’s output has grown quickly from several salars in the provinces of Jujuy, Salta and Catamarca. Bolivia has the Salar de Uyuni but has not started commercial production. The table sets out the USGS figures, which are in tonnes of contained lithium and are estimates for the latest year.
| Country | Resources (million t Li) | Reserves (million t Li) | Mine output 2025, estimate (t Li) | Who leads development |
|---|---|---|---|---|
| Chile | 13 | 9.2 | 56,000 | Private producers under state contracts; state-majority joint venture at the Atacama from 2025 |
| Argentina | 28 | 4.4 | 23,000 | Private operators holding provincial permits |
| Bolivia | 23 | Not listed by USGS | Not listed by USGS | State company YLB, which holds a legal monopoly |
Source for the three numeric columns: USGS Mineral Commodity Summaries (February 2026). A resource is mineral that may become economic; a reserve is the part that is economic to extract today, so Bolivia’s large resource and missing reserve figure reflect an undeveloped deposit, not a small one. Chile and Argentina together made about 27% of the world’s estimated 290,000 t of mine output in 2025 (USGS, 2026). Argentina’s estimated output rose from 13,800 t in 2024 to 23,000 t in 2025, an increase of about two-thirds, and its permits are now being tested in court.
Water challenges: how brine lithium uses a desert aquifer
Brine mining pumps salty water from below the salar into shallow evaporation ponds. Sun and wind concentrate the lithium over many months, and most of the water leaves as vapour. Reuters reported in 2024 that about 90% of the water is lost to the atmosphere in this process (Reuters via Kitco, 2024). Communities around the Atacama worry that mining may be depleting both scarce fresh water and the brine itself, which reduces what is available to people and wildlife (Reuters, 2024).
Chart
Water footprint at two Argentine lithium sites
Cubic metres of water per tonne of lithium carbonate, from environmental impact reports (2021 data)
How much water per tonne of lithium
Studies measure this in different ways, so the numbers cannot be compared directly. A peer-reviewed study of environmental impact reports for two Argentine operations found a water footprint of 51.0 m3 per tonne of lithium carbonate at Olaroz, based on 2021 data and including grey water (water needed to dilute pollution) (Jujuy) and 135.5 m3 at Fénix (Catamarca). Fénix uses 2.7 times more per tonne, yet the authors rate its effect on local water as moderate because more water is available there. Olaroz uses less per tonne, but its footprint equals the water use of about 32,238 residents of Susques, the nearest town, which has fewer than 2,100 people; the Fénix figure equals about 141,047 residents of Antofagasta de la Sierra, also under 2,100. The authors add that the reports they used are incomplete in places (Heliyon, 2025).
For the Salar de Atacama, a life-cycle study from TU Berlin covering 2022 and 2023 found a scarcity-weighted impact of 442 m3 “world equivalents” per tonne of lithium product, and 326 of those came from brine production. A world-equivalent volume adjusts for how scarce water is in the place where it is used. The final processing stages added little, because they use desalinated water. Between the 2020-2021 and 2022-2023 periods, all indicators in the study improved by 9% to 42% (Marinova et al., Journal of Cleaner Production, 2024).
Regional water use and subsidence
Writing in October 2026, researchers writing in New Security Beat cite a 2026 report that lithium and copper mining account for nearly 65% of regional water use in the Atacama area (New Security Beat, October 2026). Pumping can also lower the ground. A University of Chile study using radar satellites found part of the Atacama salt flat sinking by 1 to 2 cm a year, in an area of about 8 km by 5 km where pumping is most intense (Reuters via Kitco, 2024). A second analysis with the PAZ and Sentinel-1 satellites measured about 1.5 cm of sinking over seven months above depleted aquifers (ESA, January 2026).
Wildlife and a disputed study
A study in the Royal Society’s Proceedings B linked falling flamingo numbers in the Atacama to water taken by miners. It reported that James’s and Andean flamingos declined by 10% to 12% there, while numbers on salt flats without mining stayed steady. SQM disagreed with key parts, said its own monitoring shows stable flamingo populations, and noted that satellite estimates of water use can be too high or too low (Reuters via Mining.com, 2022). Both positions are on record, and on-site measurement is the missing piece.
Calculator
How much water could a lithium operation use in a year?
Enter your own output, footprint and local water use.
- Same volume as water used by this many people: 18,630
- Olympic pools of water: 408.0
- Carbonate sold per m3 of water (US$): $275
Example values only, not a benchmark or forecast. The default footprint of 51.0 m3 per tonne is the Olaroz figure and 135.5 is Fénix (Heliyon, 2025). An Olympic pool is taken as 2,500 m3. The resident comparison is a simple volume comparison, not the study’s own method. Price is an input: example, use today’s price.
Brine chemistry and extraction hurdles
Brine is not the same everywhere, and its chemistry decides how hard extraction is. The key number is the magnesium-to-lithium (Mg:Li) ratio. Magnesium behaves like lithium in many chemical steps, so a high ratio means more reagents, more waste and lower recovery. A Harvard Growth Lab paper gives Mg:Li ratios of about 19:1 for the Salar de Uyuni, 6:1 for the Salar de Atacama and 1:1 for Hombre Muerto in Argentina; mining industry data give lower floors of above 14:1 for Uyuni and about 4:1 for Atacama (Harvard Growth Lab, April 2026).
Chart
Magnesium-to-lithium ratio by salar
Higher ratios make brine harder and costlier to process
Climate adds a second hurdle. Mining industry data put evaporation at the Atacama operation near 3,500 mm a year with only a few millimetres of rain, while Uyuni has more rain, a cooler climate and an evaporation rate less than half as high (PorterGeo ore deposit database). The Harvard paper says seasonal rainfall on the Bolivian Altiplano makes pond evaporation unreliable. Even where the climate suits it, ponds are slow: brine moves from roughly 200 to 1,000 parts per million lithium to as much as 6,000 ppm over 18 to 24 months (Mining.com, Lithium ABC).
Does direct lithium extraction solve it?
Direct lithium extraction (DLE) is a group of technologies that pull lithium out of brine with sorbents, membranes or solvents instead of ponds. A Nature Reviews Earth & Environment review found some DLE methods reach lithium recovery above 95%. It also found that only 30% of DLE tests used real brines, that some methods need heat up to 80 degrees Celsius, fresh water and chemicals, and that DLE’s fresh water use needs urgent measurement because some methods may use more than ponds do, which matters in arid places (Nature Reviews Earth & Environment, 2022). Reuters reported in 2024 that DLE was still in the testing phase, and that Chile’s two producers, SQM and Albemarle, aimed to switch to it (Reuters via Kitco, 2024). Bolivia’s two planned plants with Chinese and Russian partners are also DLE designs.
Chile: the Atacama and a state-majority model
The Salar de Atacama holds about 25% of the world’s known lithium reserves, according to Climate Home News. Its Lickanantay Indigenous communities have protested the industry for decades, warning that ponds deplete scarce and sacred water (Climate Home News, March 2026).
In December 2025 Codelco, the state copper company, and SQM completed NovaAndino Litio, a joint venture with state majority that is planned to run to 2060. It follows a partnership agreement signed on 31 May 2024 and an Indigenous consultation led by the development agency Corfo, and it keeps operations running under current Corfo contracts and the ones that apply from 2031 (Codelco press release, 27 December 2025).
The consultation outcome is mixed, and both views are documented. Climate Home News reports that 25 communities signed governance agreements. These include more than 100 meetings a year with community representatives, an Indigenous Advisory Council that meets twice a year, and commitments to water-saving technology. The communities did not gain a veto or a shareholder role. In January 2024, villages closest to the operations blocked access roads, saying the Council of Atacameño Peoples no longer spoke for them, and a separate deal for the five nearest villages divided the Lickanantay. The company says it acted in good faith and with respect for community timelines. SQM’s current concessions run to 2030, and the Salar Futuro expansion will need further consultations. The same report (written in March 2026) says the government is negotiating two more lithium partnerships with Rio Tinto; Codelco signed a partnership agreement with Rio Tinto for the Maricunga salt flat in May 2025, with closing still pending, and that President José Antonio Kast has promised to respect the signed contracts (Climate Home News, March 2026).
▶ The seven environmental impacts of mining, explained in clay · 2:31
Argentina: provincial permits, court cases and fast growth
Argentina’s growth has come with legal challenges over consultation. In the north-west, Indigenous communities of the Salinas Grandes and Laguna de Guayatayoc basin, together with the environmental group FARN, filed a constitutional protection action in 2019. They argue that lithium and borate projects were approved one by one, without consultation and consent and without a basin-wide environmental assessment. In October 2025, FARN reported that Argentina’s Supreme Court had declared itself competent to hear the case and gave Jujuy, Salta and the national state 30 days to report on the permits in question (FARN, October 2025). FARN is a party to the case, so treat its account as the plaintiffs’ view of the procedure; the court’s ruling on the merits is the document to wait for.
Chart
Lithium mine output, selected countries
Tonnes of contained lithium
A provincial court has already acted. On 13 March 2024 the Catamarca provincial Supreme Court ordered authorities to stop granting new authorisations around the Salar del Hombre Muerto until a cumulative impact report covers the whole salt flat and the Los Patos river, and said projects must carry out consultation of affected communities. The case was brought by the cacique of the Atacameños del Altiplano community (AIDA, March 2024). The practical lesson for anyone assessing a project is that a court may ask for a cumulative, basin-wide water study, as in Catamarca, rather than a single-project assessment.
The water numbers differ by site, as shown above. Olaroz and Fénix are operating sites with different technologies and very different local water supplies, which is why one Argentine average hides more than it shows.
Bolivia: Uyuni, state control and stalled contracts
The Salar de Uyuni is the largest salt lake in the Andes, covering about 10,582 km2 (PorterGeo), but Bolivia has no commercial-scale lithium production. The Harvard Growth Lab paper notes that the state company Yacimientos de Litio Bolivianos (YLB) holds a monopoly over evaporite resources and that YLB had invested more than US$800 million by 2024 without reaching large-scale commercial output (Harvard Growth Lab, April 2026).
The history shows how consultation and politics interact. A 2018 joint venture with the German firm ACI Systems was voided after the 2019 ouster of President Evo Morales, and communities had objected to a proposed 3% royalty for the region. Two later contracts, with a Chinese consortium led by CBC and with Russia’s Uranium One, planned DLE plants at Uyuni. The authors of an October 2026 analysis, who study prior consultation in the lithium sector, write that both contracts breached Bolivian law requiring environmental studies and Indigenous consent, and that Congress has not approved them (New Security Beat, October 2026).
In May 2025 a mixed court at Colcha K, in Potosí, suspended Congress’s handling of both deals after a complaint from Indigenous groups, but on 5 June 2025 the same court rejected the complaint and lifted the suspension (La Región via Business & Human Rights Resource Centre, June 2025). YLB holds 51% of each venture. When the suspension was first reported, the government said it had not been formally notified and that its legislative process would continue (Mining.com, June 2025). Under President Rodrigo Paz, the government has signed a preliminary agreement with a German-Australian consortium, EAU Lithium, for smaller salars but has not set out a clear lithium policy. Local communities say their main concern is the quantity and quality of water. A rainfall decline of more than a decade and shallow groundwater around the salar that already exceeds WHO drinking-water guidelines for natural reasons make that concern hard to answer without independent water data.
Community rights and consent in the lithium triangle
The legal question running through all three countries is whether Indigenous communities must be consulted, and whether they must consent, before a project goes ahead. The Argentine plaintiffs rely on the right of Indigenous peoples to prior consultation and consent. In Bolivia, the law requires environmental studies and prior consultation, and the dispute is over whether they happened. In Chile, Corfo ran a consultation, and the agreement that followed gave communities participation rights but no veto.
Benefit sharing is the second question. The Chilean agreements promise larger payments than before and were criticised for rewarding the communities nearest the ponds most. A policy expert at the Natural Resource Governance Institute told Climate Home News that without legislation setting minimum benefits for large projects, communities that negotiate first or hardest get the better deal (Climate Home News, March 2026). Bolivian communities have asked for a specific lithium law, royalties that are shared fairly and a plan for regional development (New Security Beat, October 2026).
Traceability is part of the same debate, because buyers increasingly ask where battery metals come from and under what conditions. Origin records cannot replace a consultation record or independent water data.
Price swings and who carries the risk
Lithium prices have moved sharply, and that affects how much money is available for water monitoring, community payments and new technology. USGS reports the annual average price of battery-grade lithium carbonate, in real terms, at US$11,700 per tonne in 2021, US$63,700 in 2022, US$11,800 in 2024 and an estimated US$9,000 in 2025 (USGS, 2026). Trading Economics, which tracks the China price on a different basis, showed 100,050 yuan per tonne on 28 October 2026, down about 19% in a month and up about 26% on a year earlier (Trading Economics, 28 October 2026).
Chart
Battery-grade lithium carbonate, annual average price
US$ per tonne, real terms, 2025 is an estimate
Payments to communities follow the price. Under the Atacama agreements, Indigenous communities could collectively receive roughly US$30 million a year depending on the lithium price and their distance from the ponds, about double what SQM now pays under its existing contracts. The government says payments to local and regional authorities could bring total contributions to US$150 million a year (Climate Home News, March 2026). The video below explains how mining income reaches an economy through exports, jobs and revenue.
▶ The benefits of mining to an economy: exports, jobs, revenue and energy-transition minerals · 5:03
Challenges compared: Chile, Argentina and Bolivia
| Challenge | Chile | Argentina | Bolivia |
|---|---|---|---|
| Water | Atacama pumping area is sinking 1-2 cm a year; lithium and copper mining reported at nearly 65% of regional water use | Footprint of 51.0 to 135.5 m3 per tonne at two sites; water supply differs by salar | Rainfall decline; baseline water data lacking; groundwater naturally contaminated |
| Brine chemistry | Mg:Li about 6:1, high evaporation, ponds in use | Mg:Li about 1:1 at Hombre Muerto, easier processing | Mg:Li about 19:1; rainfall limits evaporation; DLE planned |
| Consent and consultation | Corfo-led consultation; 25 community agreements; no veto; community divisions | Supreme Court case on Salinas Grandes; Catamarca court order on Hombre Muerto | Court suspension of two contracts (May 2025) was lifted in June 2025; Congress has not approved them |
| Who decides | National state and Corfo contracts | Provincial permits plus federal courts | State monopoly through YLB |
| Output status | Producer, 56,000 t Li (2025 estimate) | Producer, 23,000 t Li (2025 estimate) | No commercial-scale output |
Sources are those cited in the sections above; the output row is from USGS (2026).
What satellite data shows about brine operations
Satellites can measure some of these issues from a distance. The ESA example used radar interferometry (InSAR), which compares radar images taken at different times to detect millimetre-scale ground movement, and the flamingo study used satellite images of ponds to estimate water extracted. Optical imagery such as Sentinel-2 shows pond area, vegetation and surface water over time, and rainfall records show the climate context. These tools can flag where to look, but they cannot show groundwater levels or the effect on a community, and they are not an environmental or social clearance.
Farmonaut analyses satellite imagery for mineral exploration, including lithium, from an area outline supplied as a KML, KMZ or polygon, and it can screen a licence area before field work begins. You can also start a project in the Farmonaut web app. For hard-rock and other lithium regions, see our guides to lithium in Australia and to Bolivia’s lithium reserves compared with the world.
Due diligence checklist for a salar project
- Who holds the water rights, and for how long? Ask for the permit, the volume and the expiry date.
- Is there a basin-wide water model? The Catamarca order shows courts may ask for cumulative studies.
- What is the brine’s Mg:Li ratio and sulfate level? Compare it with 19:1 at Uyuni and 6:1 at Atacama.
- Which process is proposed, and has it been tested on this brine? Only 30% of DLE tests used real brines in the Nature review.
- What did the consultation record show? Look for the date, the communities involved, the minutes and any court filings.
- Is the ground stable? InSAR time series over the field can show subsidence.
- What price does the project need? Compare it with the swings in the price chart above.
This page is for information only and does not assess any particular project.
For Europe’s emerging supply, see lithium mining in Europe, project by project.
Frequently asked questions
What is the lithium triangle in South America?
It is the Andean region where Chile, Argentina and Bolivia meet, with salt flats whose brines hold lithium. ESA says it holds about 50% of the world’s lithium deposits, and USGS resource figures for the three countries total 64 million of about 150 million tonnes, or about 43%.
Which country in the lithium triangle produces the most lithium?
Chile, with an estimated 56,000 t of contained lithium in 2025, compared with 23,000 t for Argentina. Bolivia has no commercial-scale output (USGS lists no figure; Harvard Growth Lab, 2026).
What are the biggest challenges for South American lithium mining?
Water use in arid basins, brine chemistry that raises processing difficulty, and consultation with Indigenous communities. Prices, legal uncertainty over permits and slow adoption of new extraction technology add to these.
What are the water and chemical challenges facing South American lithium mining?
On water, ponds lose about 90% of the water to evaporation, land above depleted aquifers is sinking by about 1 to 2 cm a year in part of the Atacama, and one Argentine site uses 135.5 m3 per tonne of carbonate. On chemistry, a high magnesium-to-lithium ratio, 19:1 at Uyuni, needs more processing, while heavy rain on the Altiplano limits evaporation.
What are the extraction hurdles facing South American lithium production?
Slow pond evaporation of 18 to 24 months, high Mg:Li ratios in Bolivia, and DLE that is still unproven at scale on real brines. Permits and consultation can also delay projects, as the court cases above show.
How much water does lithium mining use in the Atacama and Argentina?
Measured footprints range from 51.0 to 135.5 m3 per tonne of carbonate at two Argentine sites, and the TU Berlin study gives 442 m3 world-equivalents per tonne for the Atacama. The methods differ, so compare each study with itself rather than across studies.
How bad is lithium mining for the environment?
Impacts depend on the site and the method. Documented effects include ground subsidence of 1 to 2 cm a year in part of the Atacama and a disputed link to falling flamingo numbers. Water footprints vary widely between salars, and SQM says its own monitoring shows stable flamingo populations.
Why has Bolivia not produced lithium at scale?
The Harvard Growth Lab points to a state monopoly, more than US$800 million spent with minimal output (2,462 t of carbonate against a planned 15,000 t) and difficult brine chemistry. Two planned DLE plants also lack congressional approval, and a 2025 court challenge to them was rejected within days (New Security Beat, October 2026; Business & Human Rights Resource Centre, June 2025).
Do Indigenous communities have to consent to lithium projects?
The law differs by country. Bolivian law requires prior consultation and environmental studies, and Argentina’s plaintiffs rely on the right to prior consultation and consent. In Chile the Atacama agreements gave communities participation but no veto, according to Climate Home News.
Does direct lithium extraction solve the water problem?
Not yet proven. Some DLE methods reach more than 95% lithium recovery, but a review found few tests on real brines and that some methods may need as much or more fresh water than ponds.
Can satellites monitor lithium brine operations?
They can track pond area, surface water and ground movement. ESA’s PAZ and Sentinel-1 study measured about 1.5 cm of subsidence over seven months. Satellite data does not replace groundwater measurement.
This page is for information only. It is not investment advice or legal advice. Court cases, permits and contracts change; confirm the current status with the regulator or the court.
Farmonaut mining
Map your mining site from space
Send a KML, KMZ or polygon and Farmonaut screens the ground with satellite imagery before field work, with a report in 5-20 business days.

Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026: Lithium (February 2026): pubs.usgs.gov
- ESA Earth Online, PAZ reveals how lithium extraction causes sinking land (13 January 2026): earth.esa.int
- IISD, Commodity profile: Lithium (June 2026): iisd.org
- Reuters via Kitco, Lithium mining is slowly sinking Chile’s Atacama salt flat (22 August 2024): kitco.com
- Heliyon, The water footprint of lithium extraction technologies: insights from environmental impact reports in Argentina’s salt flats (2025): pmc.ncbi.nlm.nih.gov
- Marinova et al., Water footprint of battery-grade lithium production in the Salar de Atacama, Journal of Cleaner Production (2024): depositonce.tu-berlin.de
- New Security Beat (Wilson Center), Paz’s plans for lithium in Bolivia need community voices (6 October 2026): newsecuritybeat.org
- Reuters via Mining.com, In Chile’s Atacama, lithium mining stirs fight over flamingos (19 May 2022): mining.com
- Harvard Growth Lab, Bolivia’s Economic Pivot, Working Paper 264 (April 2026): growthlab.hks.harvard.edu
- PorterGeo, Ore deposit description: Salar de Atacama, Uyuni and Hombre Muerto: portergeo.com.au
- Mining.com, Brine mining the Puna for potash and lithium: mining.com
- Nature Reviews Earth & Environment, Environmental impact of direct lithium extraction from brines (2022): nature.com
- Climate Home News, Landmark deal to share Chile’s lithium windfall fractures Indigenous communities (March 2026): climatechangenews.com
- Codelco, Codelco and SQM form NovaAndino Litio (27 December 2025): codelco.com
- FARN, Supreme Court steps in: a landmark case for environmental and Indigenous rights in Argentina (17 October 2025): farn.org.ar
- AIDA, Court decision stops new lithium mining projects in Argentine salt flat (27 March 2024): aida-americas.org
- Mining.com, Bolivian court pauses Chinese, Russian lithium deals (2 June 2025): mining.com
- Trading Economics, Lithium carbonate price (28 October 2026): tradingeconomics.com
- Business & Human Rights Resource Centre, Bolivian judge lifts order suspending lithium contracts (June 2025): business-humanrights.org
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd

 Licence holder · Nigeria · Gold + lithium










