

Mining studies · NI 43-101 and S-K 1300
PEA Mining Study: From Resource Estimate to Feasibility
A PEA in mining is the first public economic study of a mineral resource: under NI 43-101 it may use Inferred resources only with equally prominent cautionary statements, it can show potential viability but never reserves, and a first-time PEA on a material property needs an independent technical report filed within 45 days.
Key takeaways
- The order is fixed: a classified mineral resource first, then a PEA (optional), then a pre-feasibility study, then a feasibility study.
- A PEA may include Inferred resources, capital and operating costs and cash flows, but it cannot declare reserves or claim that economic viability has been shown (NI 43-101 s. 2.3(3), 3.4(e)).
- CIM requires at least a pre-feasibility study before any resource becomes a reserve, and Inferred material can never be converted.
- For SEC filers, S-K 1300 sets cost accuracy at about ±50%, ±25% and ±15% for the three study levels, with contingency caps of 25%, 15% and 10%.
- A first-time PEA on a material property needs an independent technical report filed within 45 days (s. 4.2(5), 5.3).
In this article
- Where a PEA mining study sits between discovery and a build decision
- Step one: the mineral resource estimate behind every study
- The PEA under NI 43-101: what it may and may not include
- PEA mining vs pre-feasibility vs feasibility: the stages compared
- Accuracy, contingency and what a study costs
- What makes a bankable feasibility study for mining projects
- Why studies fail, and how to plan one that does not
- Where satellite mineral detection fits before the first estimate
- Frequently asked questions about PEA mining studies
Ask a room of junior-company geologists what “PEA mining” means and you will get one answer and several arguments. The answer: a preliminary economic assessment is the study that first puts a dollar figure on a mineral resource, and in Canada it is defined and policed by National Instrument 43-101. The arguments are about everything around it. How good does the resource estimate need to be? How much Inferred material is too much? When does a PEA mining study start to look like a pre-feasibility study, and why do regulators object when it does?
This guide follows a project through that sequence. It starts with the resource estimate, because every later number is built on it, then takes the PEA mining study apart line by line against NI 43-101, its Companion Policy and CSA Staff Notice 43-307. It then compares PEA mining studies with the pre-feasibility study (PFS) and the definitive or bankable feasibility study (FS, DFS or BFS), using the accuracy and contingency limits the SEC wrote into S-K 1300. It is written for CEOs, VPs Exploration, project geologists and IR teams at TSX, TSXV and CSE issuers, and for the consultants and investors who read their filings.
If you want the estimation workflow in more depth, our step-by-step guide to mineral resource estimation covers it. For the lender’s view of the final study, see what a bankable feasibility study has to show, and for a worked layout, our mining feasibility study example.
NRCan treats a positive PEA, together with enough Indicated resources, as the point where exploration ends and deposit appraisal begins.
Where a PEA mining study sits between discovery and a build decision
Between a drill hit and a construction decision sit four kinds of work, each more expensive and more reliable than the last. A mineral resource estimate says what is in the ground and how confident the geologists are. A preliminary economic assessment asks whether that resource could plausibly be mined at a profit. A pre-feasibility study compares mining and processing options, chooses one, and can declare the first mineral reserve. A feasibility study engineers the chosen option in enough detail for a board or a lender to commit.
The PEA mining study is the only optional stage. Some companies skip it and go from a resource estimate straight into a PFS. Many juniors publish one because it is the first document that turns ounces or pounds in the ground into a net present value, and the market notices. The CSA said as much in Staff Notice 43-307: a PEA is “generally the first signal to the public” that a project has potential viability.
Infographic
From drill hole to a build decision: six steps
- 1Drill and verifyDatabase, QA/QC and density checks (CIM 2019).
- 2Resource estimateBlock model classified as Inferred, Indicated or Measured.
- 3PEAPotential viability; may use Inferred with cautions (s. 2.3(3)).
- 4Pre-feasibilityPreferred option and the first reserves (CIM 2014).
- 5FeasibilitySelected option; basis to finance (CIM 2014).
- 6Build decisionPermits, finance and construction.
Natural Resources Canada draws the same line in its spending statistics. In the definitions behind the Canadian Mineral Exploration Information Bulletin, the exploration phase ends when a deposit has sufficient Indicated mineral resources and a positive preliminary economic assessment that justifies costly deposit appraisal. Deposit appraisal then covers the work needed for the pre-feasibility and final feasibility studies. The bulletin counts PEA, PFS and FS costs inside these two work phases, so the totals below include study spending as well as drilling.
Spending on that pipeline has held up. NRCan reports exploration and deposit appraisal spending of $3.8 billion in 2021, $4.4 billion in 2022 and $4.2 billion in both 2023 and 2024. Preliminary data put 2025 at $4.4 billion, with deposit appraisal up $215 million on the year, and spending intentions for 2026 at $5.3 billion, which would be a new high if realized. Junior companies spent $2.27 billion in 2025 on preliminary figures.
Chart
Exploration and deposit appraisal spending in Canada
C$ billion; 2025 preliminary (p), 2026 spending intentions (i)
How long the studies take
A finished study is no promise of a quick start. S&P Global Market Intelligence’s lead-time research found that mines starting production between 2020 and 2023 took an average of 17.9 years from discovery, against 12.7 years for mines started between 2005 and 2009, with longer exploration, permitting and study phases and a longer gap between finishing feasibility work and starting construction. Its July 2026 analysis found that projects which have completed feasibility studies but are not yet operating are looking at nearly 30 years, mostly because of permitting. S&P revisits these numbers every year or two, so check for a later cohort.
Step one: the mineral resource estimate behind every study
Nothing in a PEA mining model can be stronger than the resource underneath it. Under the CIM Definition Standards (adopted May 2014 and incorporated into NI 43-101), a Mineral Resource is a concentration of material of economic interest “in such form, grade or quality and quantity that there are reasonable prospects for eventual economic extraction.” That last phrase, often shortened to RPEEE, is what separates a resource from a pile of assays. The Qualified Person has to state the basis for it, including cut-off grade, recovery, price, mining method and costs.
CIM also says how long “eventual” can be. For some coal, iron and potash deposits it may cover more than 50 years. For many gold deposits, CIM says the concept “would normally be restricted to perhaps 10 to 15 years,” and often much less.
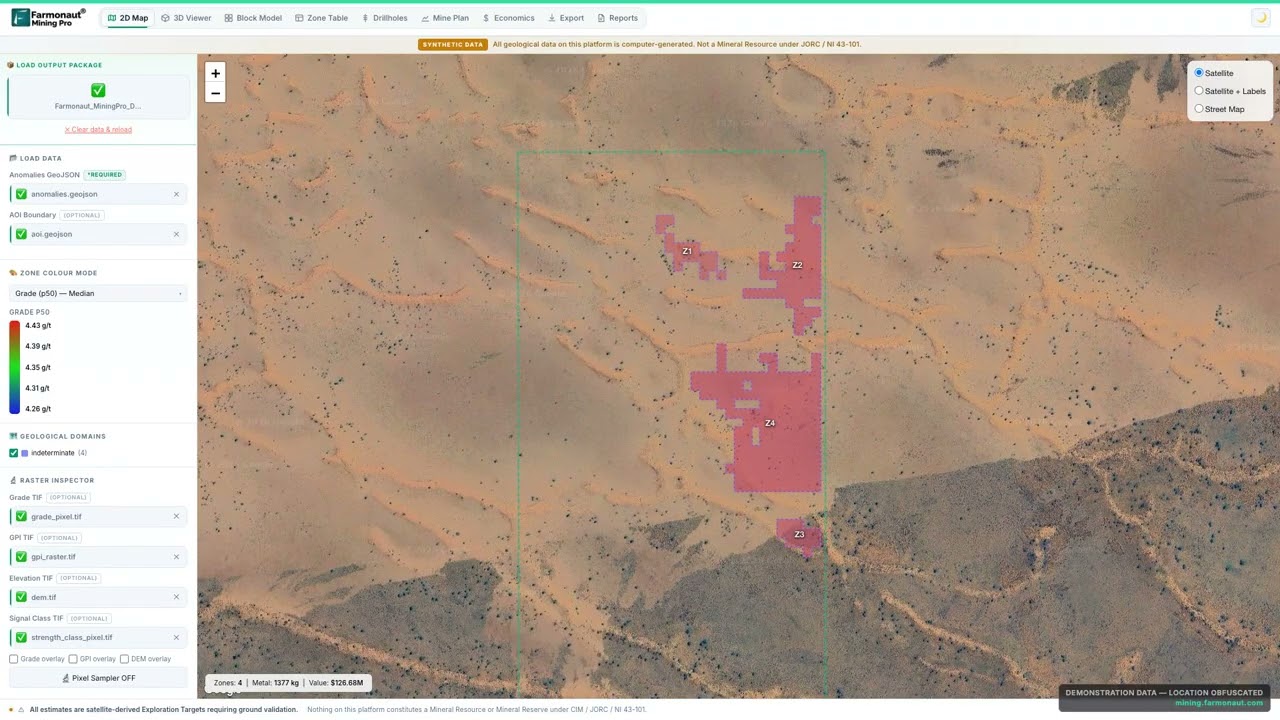
▶ How exploration data moves step by step toward a classified resource, from our Mining Pro course (15:11). · 15:11
The estimation workflow, in the order CIM sets out
The CIM Estimation of Mineral Resources and Mineral Reserves Best Practice Guidelines (November 2019) are not a recipe, and they say so. They do set out the order that most resource geologists follow:
- Database and QA/QC. Collars, surveys, logs and assays in a documented database, with blanks, duplicates and standards checked, and the QP’s own verification of the data against laboratory certificates.
- Bulk density. CIM calls density “as important a part” of the estimate as volume or grade, and warns that voids and porous material can inflate tonnage.
- Geological and mineralization models. Wireframes of lithology, structure, alteration and mineralized zones, then estimation domains that group material with similar grade behaviour.
- Exploratory data analysis. Statistics per domain, including the geological “nugget effect” that matters so much in gold.
- Outliers and grade capping. High-grade outliers can cause serious overestimation, so they are capped (top cut), spatially restricted or handled by indicator methods, and the choice is documented.
- Compositing. Samples combined to a uniform length, such as a bench height or the dominant assay interval, without crossing domain boundaries.
- Variography. Variograms or correlograms that measure how far grade continuity reaches in each direction.
- The block model and its estimate. Grades interpolated into blocks by inverse distance, kriging or simulation, then validated against the drill data.
- Classification and reporting. Blocks sorted into Inferred, Indicated and Measured, constrained by a pit shell or mineable shapes, and reported at a stated cut-off.
What the block model in mining actually is
A block model is a 3D grid of cells, each carrying an estimated grade, density, domain code and, later, a confidence class. CIM’s guidelines say the block size depends on the geometry of the mineralization, the mining method and drill spacing, and that the workflow should be compatible with “the anticipated mining method(s) and related equipment.” For an early-stage project a global estimate of tonnes and grade may be enough; an advanced project needs a model good enough for short- to medium-range planning. The same block model then feeds the PEA mining plan, pit or stope design, so a block model mining engineers cannot use becomes the first problem in the economic study.
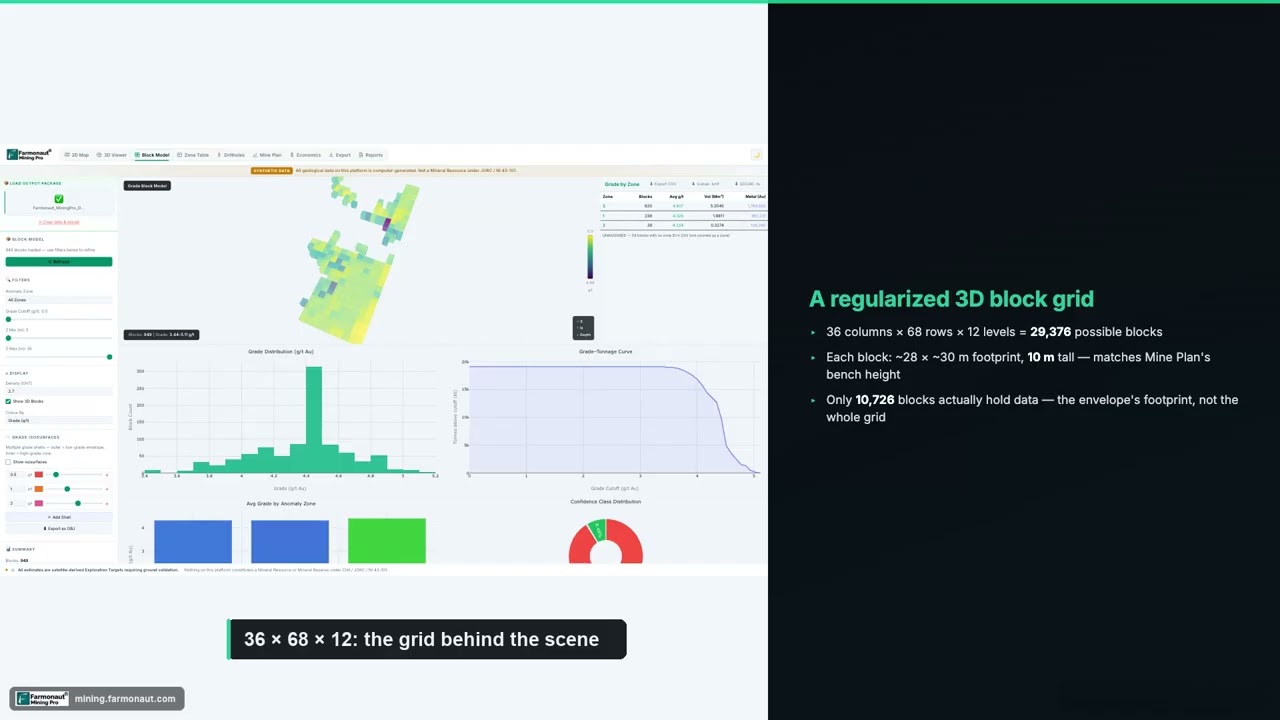
▶ What a block model holds and how engineers read it (5:23). · 5:23
Inferred, Indicated and Measured: what each study may use
The three confidence categories decide which study can use which tonnes. The table puts the CIM definitions next to the study rules in NI 43-101.
| Category (CIM 2014) | Geological evidence | Can it support… | Can it become a reserve? |
|---|---|---|---|
| Inferred | Limited; enough to imply but not verify continuity | A PEA, with the s. 2.3(3) cautionary statements. Never a PFS or FS economic analysis | No. CIM says it “must not be converted” |
| Indicated | Adequately detailed; enough to assume continuity between data points | A pre-feasibility study, which CIM says can serve as the basis for major development decisions | Yes, to a Probable reserve only |
| Measured | Detailed and reliable; enough to confirm continuity | Detailed mine planning and final evaluation in a feasibility study | Yes, to Proven, or to Probable if the Modifying Factors are less certain |
Two rules from NI 43-101 travel with every resource statement. Section 2.2 bars adding Inferred resources to the other categories. Section 3.4 requires the effective date, the quantity and grade of each category, the key assumptions and methods, the known risks and, whenever an economic analysis of resources is disclosed, an equally prominent statement that “mineral resources that are not mineral reserves do not have demonstrated economic viability.” That sentence will appear again in every PEA mining headline you publish.
Cut-off grade and the constraining shell
RPEEE is not just a cut-off grade. For open-pit resources, CIM’s guidelines say the test should consider technical limits such as wall slopes as well as an economic limit, and that at a minimum this is handled with constraining surfaces, usually optimized pit shells. For underground resources, the material must show spatial continuity within a potentially mineable shape, and low-grade “must take” material inside that shape has to be included. Reporting every block above cut-off with no shape around it is the selective reporting bias CIM warns about.
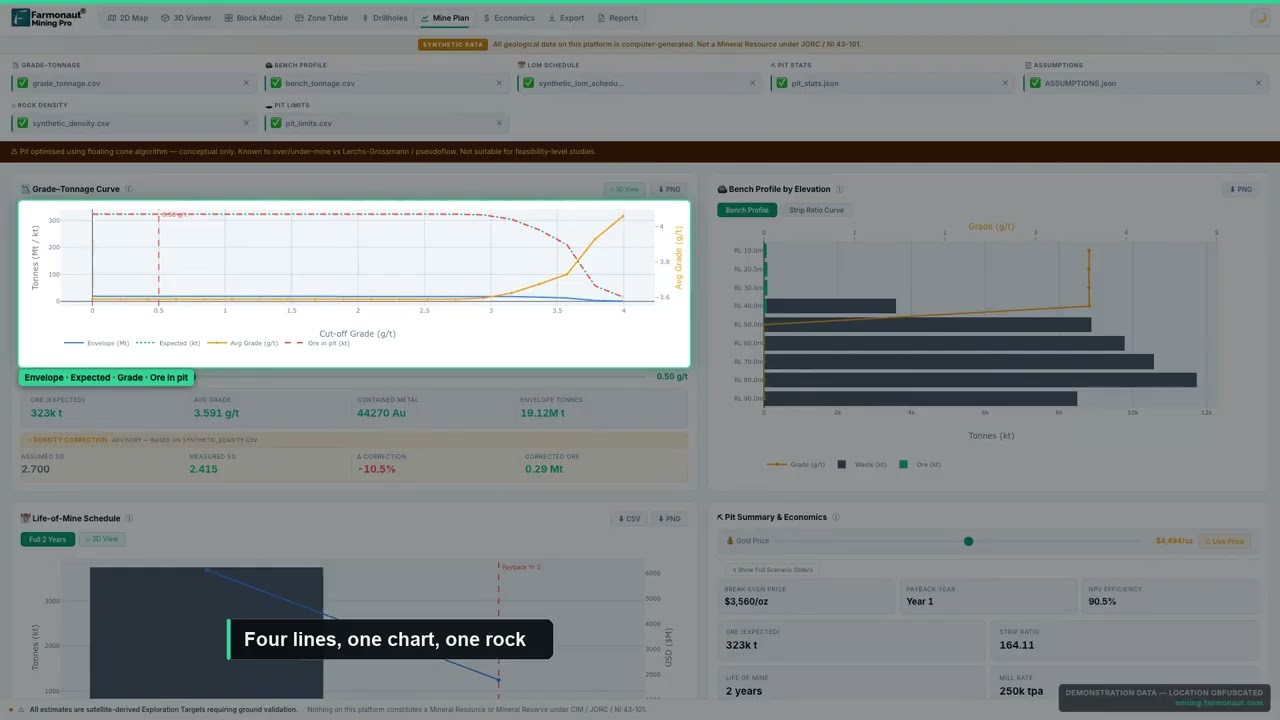
▶ How tonnage and average grade trade off as the cut-off moves (4:46). · 4:46
The PEA under NI 43-101: what it may and may not include
NI 43-101 defines a preliminary economic assessment as “a study, other than a pre-feasibility or feasibility study, that includes an economic analysis of the potential viability of mineral resources.” The Companion Policy adds that it can include what is commonly called a scoping study, that it might be based on Measured, Indicated or Inferred resources or a combination, and that the CSA treats forecasts of mine production rates, capital and operating costs and projected cash flows as the kind of economic analysis that makes a study a PEA. In plain terms, a PEA mining study is the Canadian legal name for what the JORC world calls a scoping study, with Canadian disclosure rules attached.
What a PEA mining study may include
- ✔ Inferred mineral resources in the mine plan and cash flow, which section 2.3(3) allows as an exception to the general ban in s. 2.3(1)(b).
- Measured and Indicated resources, alone or mixed with Inferred.
- Capital and operating cost estimates, production schedules, cash flows, NPV, IRR and payback. Items 16 to 22 of Form 43-101F1 serve as the reporting framework for a PEA as well as a PFS and FS.
- Alternative scenarios for an advanced project. The CSA broadened the definition so issuers can re-scope a project, for example a different throughput, an open pit versus underground, oxide versus sulphide, or a different process route.
- A study done after a PFS or FS, as long as it discusses whether the existing reserves and study remain current (s. 2.3(3)(c)).
What PEA mining disclosure must say, every time
Section 2.3(3) of NI 43-101 sets three conditions for disclosing a PEA that includes or is based on Inferred resources. The disclosure must state, with equal prominence, that the PEA is preliminary in nature, that it includes Inferred resources considered too speculative geologically to have the economic considerations applied to them that would let them be categorized as reserves, and that there is no certainty the PEA will be realized. It must state the basis of the PEA and the QP’s qualifications and assumptions. And it must describe the PEA’s impact on any pre-feasibility or feasibility study on the property. On top of that comes the s. 3.4(e) statement that resources which are not reserves have no demonstrated economic viability.
What a PEA mining study may not do
- ⚠ Call itself a PFS or FS. Section 2.3(4) bars the terms unless the study meets the CIM definitions.
- Declare mineral reserves. CIM requires at least a pre-feasibility study before resources convert.
- Use an exploration target or a historical estimate in the economics. The Companion Policy says the 2.3(3) exception does not stretch that far.
- Show a gross metal value. Section 2.3(1)(c) bans it, and the Companion Policy calls it misleading because it ignores costs and recoveries.
- Count by-products that are not in the resource. Staff Notice 43-307 calls cash flows from un-estimated by-products misleading.
- ⚠ Claim, or imply, that viability has been shown. Talking about “mineable resources” or “ore” does exactly that.
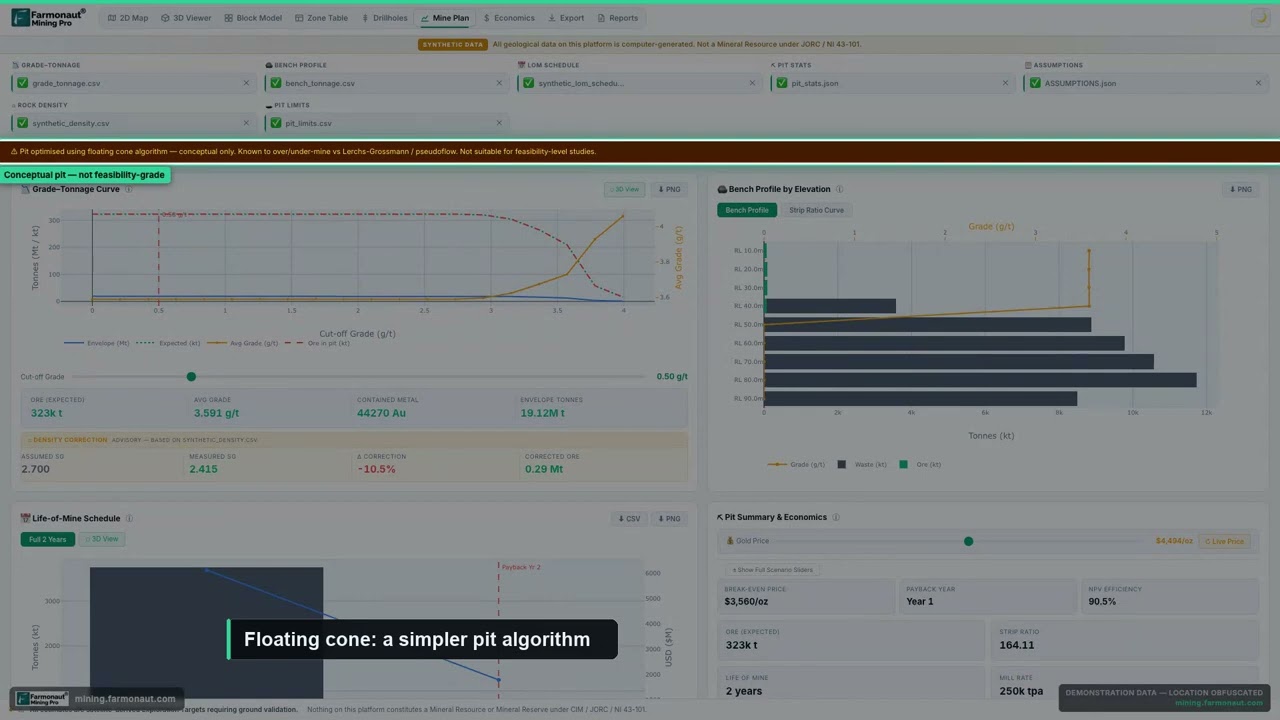
▶ How pit optimization turns a block model into the pit shell that a PEA mine plan starts from (5:12). · 5:12
Where the CSA has pushed back
Staff Notice 43-307, published on August 16, 2012, lists the situations in which staff may conclude that an issuer is treating its PEA mining study as a PFS. They include leaving out the s. 3.4(e) cautionary statement, using the PEA to justify going directly to a feasibility study or a production decision, disclosing “mineable” resources or “ore,” and saying a PEA was done “at or close to” PFS level. The notice also rejects a PEA run alongside a PFS or FS when its effect is to bring Inferred resources into the PFS or FS, even as a sensitivity case.
The consequences are spelled out. Staff will generally ask the issuer to restate and re-file. If it does not, it can be placed on the default list, ordered to re-file or cease traded, and a prospectus review can slow down or stall. The notice also warns that overly optimistic assumptions are forward-looking information without a reasonable basis under NI 51-102.
Technical report triggers and the 45-day clock
A first-time disclosure of a PEA mining study on a property material to the issuer triggers a technical report under s. 4.2(1)(j). Section 4.2(5) gives 45 days from the disclosure, or less if the same disclosure appears in a preliminary short form prospectus or a directors’ circular, and the issuer must issue a news release on filing that reconciles any material differences. Section 5.3 requires the report to be prepared by one or more independent Qualified Persons when it supports a first-time resource, reserve or PEA. Staff Notice 43-307 adds that PEA mining results in corporate presentations, fact sheets or on a website can trigger the same requirement. Reports are filed on SEDAR+.
Once a property has resources supported by a PEA, PFS or FS, it becomes an “advanced property” under NI 43-101, and items 15 to 22 of Form 43-101F1 (reserves, mining and recovery methods, infrastructure, markets, environment, costs and economic analysis) apply to its technical report. Item 22 requires annual cash flow forecasts, NPV, IRR, payback, the taxes and royalties, and sensitivity to price, grade and costs.
If you also file with the SEC: the S-K 1300 initial assessment
US registrants follow subpart 1300 of Regulation S-K, where the nearest equivalent is the “initial assessment” that every resource must rest on. Its rules in 17 CFR 229.1302 go further than NI 43-101 on Inferred material. If the QP includes Inferred resources in the economic analysis, the filing must carry the same kind of cautionary statement, disclose the percentage of the resources in the cash flow that is Inferred, and show the results excluding Inferred resources with equal prominence. Cash flow in an initial assessment is optional, but if it is included the cost estimates must be accurate to about ±50% with contingency of no more than 25%.
Calculator
How much of your PEA mine plan is Inferred?
Enter the tonnes and grades in the mine plan to see the Inferred share of tonnes and contained ounces.
- Inferred share of plan tonnes: 40.0%
- Measured and Indicated contained: 231,485 oz
- Inferred contained: 128,603 oz
Example values only, not a benchmark. Troy ounces = tonnes x grade (g/t) / 31.1035, in situ, before dilution, mining losses and recovery. S-K 1300 (17 CFR 229.1302(d)(4)(ii)) requires SEC filers to disclose the percentage of the resources in the cash flow that is Inferred and the results without them; NI 43-101 s. 2.3(3) does not require the percentage, but readers will ask. Not a resource or reserve statement. General information, not legal or investment advice.
Run the default numbers and a plan with 40% of its tonnes in the Inferred category carries about 36% of its ounces there, because the Inferred material in this example is lower grade. Flip the grades and the ounce share rises above the tonnage share. Either way, that number is the first thing an analyst or a CSA reviewer will look for, and a PEA mining release that leaves it out invites the question.
PEA mining vs pre-feasibility vs feasibility: the stages compared
The study names vary a little between reporting codes, but the sequence does not. The JORC Code (2012 edition) calls the first economic test a Scoping Study: an order-of-magnitude study of potential viability, enough to show that moving to a pre-feasibility study is reasonably justified. In Canada the PEA mining study fills that slot, with the added rules above. The PFS and FS definitions in NI 43-101 come straight from CIM.
| Stage | Purpose | Resource basis | Cost accuracy (S-K 1300) | Main output |
|---|---|---|---|---|
| Resource estimate | Quantify tonnes and grade with stated confidence | Drill data, QA/QC, geological model | No cost estimate | Classified resource and technical report |
| PEA / scoping study | Test potential viability; is a PFS justified? | Measured, Indicated and Inferred, with cautions | About ±50%, contingency 25% or less, if costs are included | Concept mine plan, cash flow, go or no-go for PFS |
| Pre-feasibility (PFS) | Compare options; choose mining and processing method | Measured and Indicated only in the economics | About ±25%, contingency 15% or less | Preferred case; first Probable or Proven reserve |
| Feasibility (FS, DFS, BFS) | Engineer the selected option for a decision to build and finance | Measured and Indicated only in the economics | About ±15%, contingency 10% or less | Basis for the construction and finance decision |
Mining pre-feasibility studies (PFS)
The pre-feasibility study is where options are compared and narrowed. CIM defines it as a comprehensive study of a range of options, at a stage where a preferred mining method or pit configuration is established and an effective processing method is determined, with a financial analysis based on reasonable assumptions on the Modifying Factors. It must be enough for a Qualified Person, acting reasonably, to decide whether all or part of the resource can be converted to a reserve. CIM makes the PFS “the minimum prerequisite” for that conversion, so mining pre feasibility studies are usually the first point at which a project can report reserves. You will also see a mining pre feasibility study written as “prefeasibility” or “preliminary feasibility study”; all three name the same stage.
Definitive and bankable feasibility studies (DFS / BFS)
CIM defines a Feasibility Study as a comprehensive technical and economic study of the selected development option, with appropriately detailed assessments of the Modifying Factors and detailed financial analysis, necessary to demonstrate that extraction is reasonably justified. Its results “may reasonably serve as the basis for a final decision by a proponent or financial institution to proceed with, or finance” the project. That clause is why companies call it a definitive feasibility study or a bankable feasibility study, and why BFS mining shorthand is so common in lender documents. CIM adds that a proponent financing a project itself still needs the confidence a financial institution would require.
Accuracy, contingency and what a study costs
How sure can you be of the capital number at each stage? Industry sources and the SEC give slightly different answers. The AusIMM Bulletin article by AMC Consultants’ Peter McCarthy, first published in 2015, says there is no international agreement on study accuracy, puts scoping accuracy at usually 30 to 35%, and notes that some companies accept ±50%. AMC Consultants gives 30 to 35% for scoping and 20 to 25% for a PFS. S-K 1300 is the only one of these that writes numbers into a rule, in Table 1 of 17 CFR 229.1302(d): about ±50% for an initial assessment that includes costs, ±25% for a pre-feasibility study and ±15% for a feasibility study.
Chart
How wide the capital cost band may be at each study level
Low and high end of the estimate, as % of the point estimate (100 = the estimate)
NI 43-101 itself sets no accuracy percentage. It leaves the level of detail to the CIM definitions and to the QP. Canadian issuers that are also SEC registrants, other than those using the Form 40-F route, work to the S-K 1300 table, and many Canadian reports quote similar ranges, so it is a useful yardstick either way.
Contingency: the allowance that will be spent
CIM’s 2019 guidelines describe contingency as an estimate of unknown costs that are likely to occur but cannot yet be identified, and say plainly that “the contingency allowance will be spent” and is not there to cover scope changes. S-K 1300 caps it at 25% for an initial assessment, 15% for a PFS and 10% for a feasibility study. A PEA mining estimate that carries 8% contingency is claiming more confidence than the rules ask of a feasibility study.
Chart
The contingency ceiling tightens at each study level
Maximum contingency in capital and operating cost estimates, %
Calculator
How wide is your capital cost band at each study level?
Enter your capital cost point estimate and its contingency, both in US$ million.
- PEA-level band, low end (US$ million): $200
- Pre-feasibility band, low end (US$ million): $300
- Pre-feasibility band, high end (US$ million): $500
- Feasibility band, low end (US$ million): $340
- Feasibility band, high end (US$ million): $460
- Contingency as share of estimate before it: 17.6%
Amounts are in US dollars (US$ million); use C$ consistently if your study reports in Canadian dollars. The bands apply the S-K 1300 accuracy levels in 17 CFR 229.1302(d), Table 1 (about ±50% initial assessment, ±25% pre-feasibility, ±15% feasibility) symmetrically to your estimate; real estimates are often skewed upward and achieved accuracy is often worse. Contingency share = contingency / (estimate minus contingency); S-K 1300 ceilings are 25%, 15% and 10%. Illustrative arithmetic only, not a cost estimate or engineering advice.
What the studies themselves cost
We looked for an official or industry-body benchmark for the cost of a PEA mining study, a PFS or a feasibility study and did not find one we could cite. Budgets depend on the commodity, the deposit, the number of options studied and how much drilling, metallurgical test work and baseline work is already done. NRCan’s survey counts PEA, PFS and FS costs inside its exploration and deposit appraisal totals, but does not report them separately. Treat any single percentage you hear as a starting point for a conversation with your engineering consultants, not a budget. If the study itself still needs funding, our guide on where to meet mining investors and what they check covers that raise.
The economic model inside every study
Capital and operating cost estimates feed a model that produces NPV, IRR, payback and annual cash flow, as Item 22 of Form 43-101F1 requires. CIM’s guidelines expect the discount rate to reflect the cost of capital, the stage of the project (PEA mining study, PFS, FS or operating mine) and country risk, and they expect sensitivity tests on both positive and negative changes in price, grade, recovery and costs. For gold, operating cost is often benchmarked as all-in sustaining cost (AISC), the measure set out in World Gold Council guidance.
NPV = Σ (Revenuet − Opext − Capext − Taxt − Royaltiest) / (1 + r)t
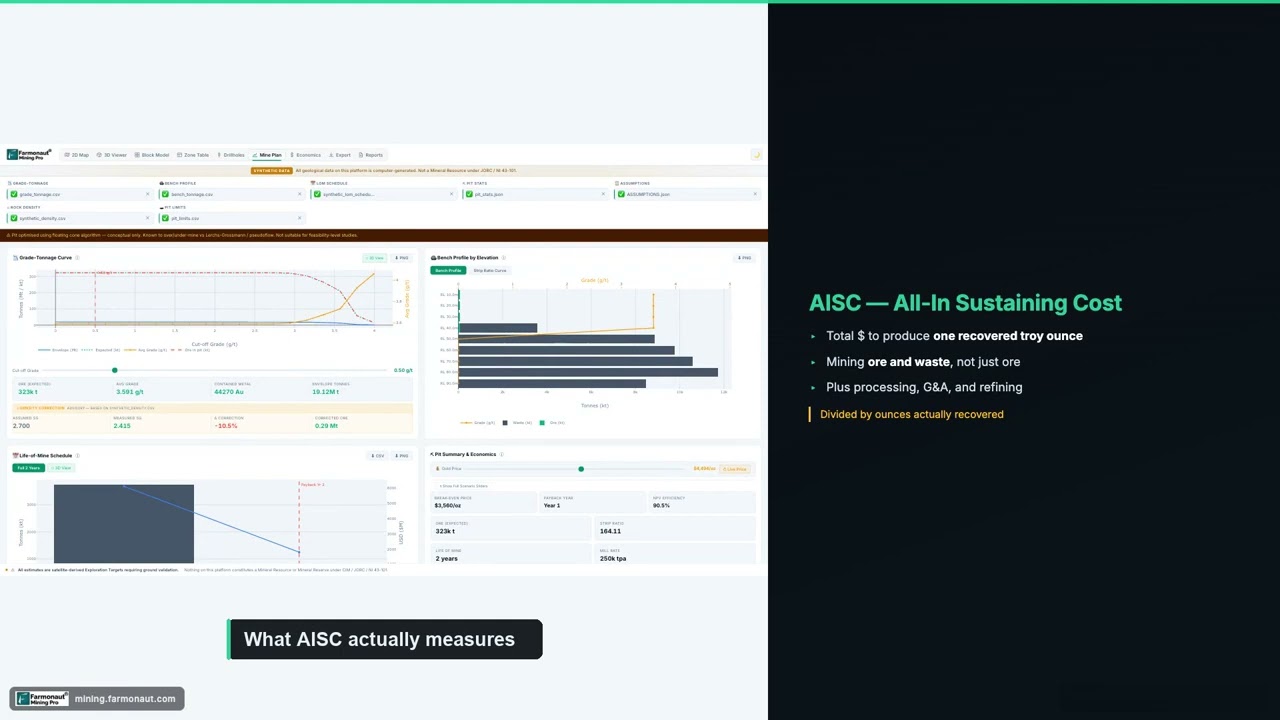
▶ What all-in sustaining cost includes and why gold studies quote it (4:44). · 4:44
S-K 1300 caps contingency at 10% in a feasibility study, and at 25% in an initial assessment that includes costs.
What makes a bankable feasibility study for mining projects
“Bankable” is not a category in NI 43-101, CIM or JORC. It is shorthand for a feasibility study that lenders and their independent engineers are willing to rely on when deciding to fund construction. A bankable feasibility study for mining projects is judged less by its title than by its quality and completeness:
- ✔ Reserves, not just resources: a code-compliant Mineral Reserve with enough mine life to repay debt with a margin.
- ✔ Engineering to the right depth: designs and quotes detailed enough to support feasibility-level cost accuracy.
- Proven metallurgy: test work on representative samples, supporting the recovery in the model; S-K 1300 adds pilot plant work “if required, based on risk.”
- Independent review: lenders usually appoint an independent engineer to check the study.
- 📊 Environmental and social standards: banks that follow the Equator Principles apply them to project finance where total project capital costs are US$10 million or more, with the IFC Performance Standards behind them.
- ⚠ Permits and title: a clear path to the mining right and key permits, checked against the official register.
A study that meets the CIM definition of a Feasibility Study is not automatically bankable, and one labelled “bankable” still has to pass review. How the money is then layered, from equity to project debt, is set out in how mine projects are funded from licence to mill, and private funds read studies the same way; see how mining private equity and VC funds pick projects.
The seven workstreams, and how deep each goes
Every study from PEA mining to feasibility covers the same workstreams. What changes is the depth, and S-K 1300’s Table 1 spells that out better than most textbooks.
- Geology and resources. The block model, classification and resource statement described above.
- Mine design and planning. In an initial assessment the method is defined “broadly as surface or underground” with production rates assumed. A PFS draws detailed layouts for each alternative; a feasibility study finalizes one.
- Processing. An initial assessment assumes the method and throughput. A PFS needs detailed bench tests and a flow sheet; a feasibility study finalizes the flow sheet and adds pilot testing where the risk calls for it.
- Site infrastructure. Power, water, roads, camp and tailings: first “whether or not access to power and site is possible,” then designs suitable for cost estimates, then final designs.
- Environment and permitting. A list of required permits and agencies and the baseline needs at the first stage, detailed baselines and a preliminary impact assessment at PFS, completed baselines and a final assessment at FS.
- Costs and the financial model. Optional in an initial assessment; revenues based on at least a preliminary market study at PFS and a final market study or letters of intent at FS.
- Risk and opportunity. Sensitivity tests and a register of what could go wrong. CIM’s guidelines expect a resource risk assessment and peer review as well.
Why studies fail, and how to plan one that does not
Most failed studies trace back to rushing the early stages or under-investing in data. The usual causes:
- ⚠ Thin geology: too few holes, poorly placed, give a resource that shrinks or shifts when infill drilling arrives.
- Optimistic metallurgy: recoveries based on a few favourable samples rather than representative material.
- A PEA used as a PFS: jumping from a PEA mining study to a full feasibility study, which Staff Notice 43-307 lists as a sign an issuer is treating its PEA as a PFS.
- Late ESG work: baselines started too late, delaying permits.
- Accuracy claims the study cannot carry: presenting a PEA mining estimate as if it had feasibility-level precision.
- ⚠ Cost and schedule optimism: thin contingency, short ramp-up and low capital.
Planning a feasibility study for mining projects
A study is a project in its own right, with a budget, a schedule and a team. Most owners appoint a lead engineering consultant to integrate the workstreams, with specialists for resources, geotechnics, metallurgy, hydrogeology, environment and infrastructure. CIM recommends that where responsibilities are split, each Qualified Person accepts responsibility for their own part, so bring the QPs in from the start rather than at sign-off. Then sequence the slow work first:
- Close the data gaps early: infill holes, geotechnical holes and metallurgical samples usually take the longest.
- Fix the design basis: throughput, product and price deck agreed before engineering starts.
- Run options in the PFS, then lock them: reopening them in the feasibility study costs time and money.
- Review before release: an internal or independent review catches errors that would otherwise surface in lender due diligence or a CSA review.
Scope each study to the decision it supports. A PEA mining study only needs to show whether a PFS is justified. A PFS must pick an option and support a first reserve. A feasibility study must support a build-and-finance decision. Over-scoping an early study wastes money; under-scoping a late one wastes time when lenders send it back. For a wider view of what investors check before they fund the next stage, see our overview of gold mining investment routes and the checks to run.
Gold and bulk commodities: where the emphasis shifts
The framework is the same for every commodity; the emphasis is not. A gold PEA mining study usually turns on grade continuity and metallurgy. Nuggety gold changes grade sharply over short distances, which is why CIM singles out the nugget effect, and recovery depends on whether the material is free-milling, refractory or oxidised. A bulk commodity study, such as iron ore, is dominated by scale, product specification and logistics, where rail, port and shipping can decide viability more than the deposit itself. CIM’s different “eventual” horizons, decades for bulk commodities and 10 to 15 years for many gold deposits, reflect the same difference.
Where satellite mineral detection fits before the first estimate
Satellite analysis is not a resource estimate, a PEA mining study or a feasibility study, and it cannot replace drilling. Its value comes earlier: it helps a project decide where to explore and drill, so the resource that every later study depends on is built on the best ground. Our satellite-based mineral detection analyses multispectral and hyperspectral imagery for the spectral signatures of minerals and alteration, and flags likely mineralised zones, alteration halos, faults and fractures before field teams deploy.
- ✔ Input: your licence or claim coordinates, KML/KMZ or polygon, plus the country and target mineral.
- ✔ Speed and cost: early-exploration timelines from months to days and up to 80 to 85% lower early-exploration cost, with reports in 5 to 20 business days.
- Deliverables: high-potential zones, prospectivity heatmaps, estimated location and depth ranges, geological interpretation, and PDF plus georeferenced GIS files.
- Premium+: TargetMax™ Drilling Intelligence adds recommended drilling angles and interactive 3D subsurface models, to help plan the drilling a resource estimate relies on.
- ⚠ Limits: satellite targets are exploration targets, not mineral resources or reserves, and they are not prepared or approved by a Qualified Person. They must be tested by fieldwork and drilling before they feed any estimate or study.
See a typical deliverable in our satellite-driven 3D mineral prospectivity mapping overview. We have scanned 100,000+ hectares for 20+ mineral types across 25+ countries. To start, map your ground on mining.farmonaut.com: Map Your Mining Site, or send your boundary through our mining query form to get a quote. If you are also checking title, our mining cadastre portal guide by country lists the official registers, and our guide to drilling technologies in mineral exploration covers the next step.
Frequently asked questions about PEA mining studies
What is a PEA in mining?
A preliminary economic assessment is defined in NI 43-101 as a study, other than a pre-feasibility or feasibility study, that includes an economic analysis of the potential viability of mineral resources. It can include a scoping study, and it is usually the first study that publishes an NPV for a deposit.
Can a PEA mining study include Inferred resources?
Yes. Section 2.3(3) of NI 43-101 allows it if the disclosure states with equal prominence that the PEA is preliminary, that Inferred resources are too speculative geologically to be categorized as reserves, and that there is no certainty the PEA will be realized, plus the basis and the QP’s assumptions and the impact on any PFS or FS.
What is the difference between PEA mining, a PFS and a feasibility study?
A PEA tests potential viability and may use Inferred resources. A pre-feasibility study compares options, picks the preferred mining and processing method and can support the first reserve. A feasibility study engineers the selected option in enough detail to support a decision to build and finance. Under S-K 1300, cost accuracy tightens from about ±50% to ±25% to ±15%.
Can a PEA mining study declare mineral reserves?
No. CIM makes a pre-feasibility study the minimum prerequisite for converting resources to reserves, and Staff Notice 43-307 warns that calling resources “mineable” or “ore” in a PEA treats them as reserves.
How accurate is a PEA mining cost estimate?
NI 43-101 sets no percentage. S-K 1300 requires about ±50% with contingency of no more than 25% if an initial assessment includes costs, and AMC Consultants puts scoping accuracy at 30 to 35%. Achieved accuracy is often worse than the target.
What is a mineral resource estimate?
It is a QP’s estimate of the tonnes and grade of material with reasonable prospects for eventual economic extraction, classified as Inferred, Indicated or Measured under the CIM Definition Standards, and reported with its effective date, assumptions, methods and risks.
What is a block model in mining?
A 3D grid of blocks, each holding an estimated grade, density and domain, built from drill data by methods such as inverse distance or kriging. CIM’s 2019 guidelines say block size should suit the mineralization, the drill spacing and the planned mining method.
When must a PEA mining technical report be filed?
Within 45 days of first disclosing the PEA on a material property, or earlier if the disclosure is also in a preliminary short form prospectus or a directors’ circular. The report must be prepared by independent Qualified Persons for a first-time PEA.
What does BFS mean in mining?
Bankable feasibility study: a feasibility study of the quality lenders and their independent engineers will rely on to fund construction. “Bankable” is not a formal code category; the CIM term is Feasibility Study.
Is a mining pre feasibility study the same as a PFS?
Yes. Pre-feasibility, prefeasibility and preliminary feasibility study all name the same stage, and NI 43-101 s. 2.3(4) bars using the terms for a study that does not meet the CIM definition.
Can Farmonaut prepare a PEA mining study or feasibility study?
No. We do not prepare resource estimates, PEAs or feasibility studies, and we do not act as a Qualified Person. We provide satellite-based mineral detection that helps target early exploration and drilling, the work later studies depend on.
This article is general information about mining studies and disclosure rules. It is not engineering, tax, legal or investment advice; confirm with your advisers and the exchange. The calculators are illustrative arithmetic on your own inputs. Satellite results are exploration targets, not mineral resources or reserves.
Farmonaut mineral detection
Map your mining site from space
Send your claim or licence boundary as KML, KMZ or a polygon. Farmonaut returns ranked satellite exploration targets for it, usually in 5 to 20 business days.

Keep reading
Sources
- Ontario Securities Commission Bulletin, NI 43-101, Form 43-101F1 and Companion Policy 43-101CP as in force from 30 June 2011 (2011): mrmr.cim.org
- CSA Staff Notice 43-307, Mining Technical Reports: Preliminary Economic Assessments (2012): osc.ca
- CIM, Definition Standards for Mineral Resources and Mineral Reserves (2014): mrmr.cim.org
- CIM, Estimation of Mineral Resources and Mineral Reserves Best Practice Guidelines (2019): mrmr.cim.org
- Legal Information Institute, 17 CFR 229.1302, Qualified person, technical report summary and technical studies (S-K 1300): law.cornell.edu
- eCFR, 17 CFR part 229 subpart 229.1300, Disclosure by registrants engaged in mining operations: ecfr.gov
- Natural Resources Canada, Canadian Mineral Exploration Information Bulletin (April 2026): natural-resources.canada.ca
- JORC, Australasian Code for Reporting of Exploration Results, Mineral Resources and Ore Reserves (2012): jorc.org
- AusIMM Bulletin, Feasibility studies for mining projects (AMC Consultants, 2015): ausimm.com
- AMC Consultants, Feasibility studies for mining projects: amcconsultants.com
- S&P Global Market Intelligence, Mine permitting delays and the discovery-to-production timeline (July 2026): spglobal.com
- S&P Global Market Intelligence, Average lead time almost 18 years for mines started in 2020-23: spglobal.com
- Equator Principles Association, About the Equator Principles: equator-principles.com
- World Gold Council, Guidance Note on Non-GAAP Metrics: AISC and AIC: gold.org
- SEDAR+, Canadian securities filings system: sedarplus.ca
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Southbridge & Wess PDC Ltd
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited











