

Diamond, gold and silver · Where they are found
Where Is Diamond Mostly Found? 7 Regions, Gold and Silver
Diamond is mostly found in Russia, Botswana, Angola and Canada, which mined about 77% of the world’s carats in 2025 (Kimberley Process). The stones come from kimberlite pipes and the gravels eroded from them. Gold and silver spread differently, as the rankings below show.
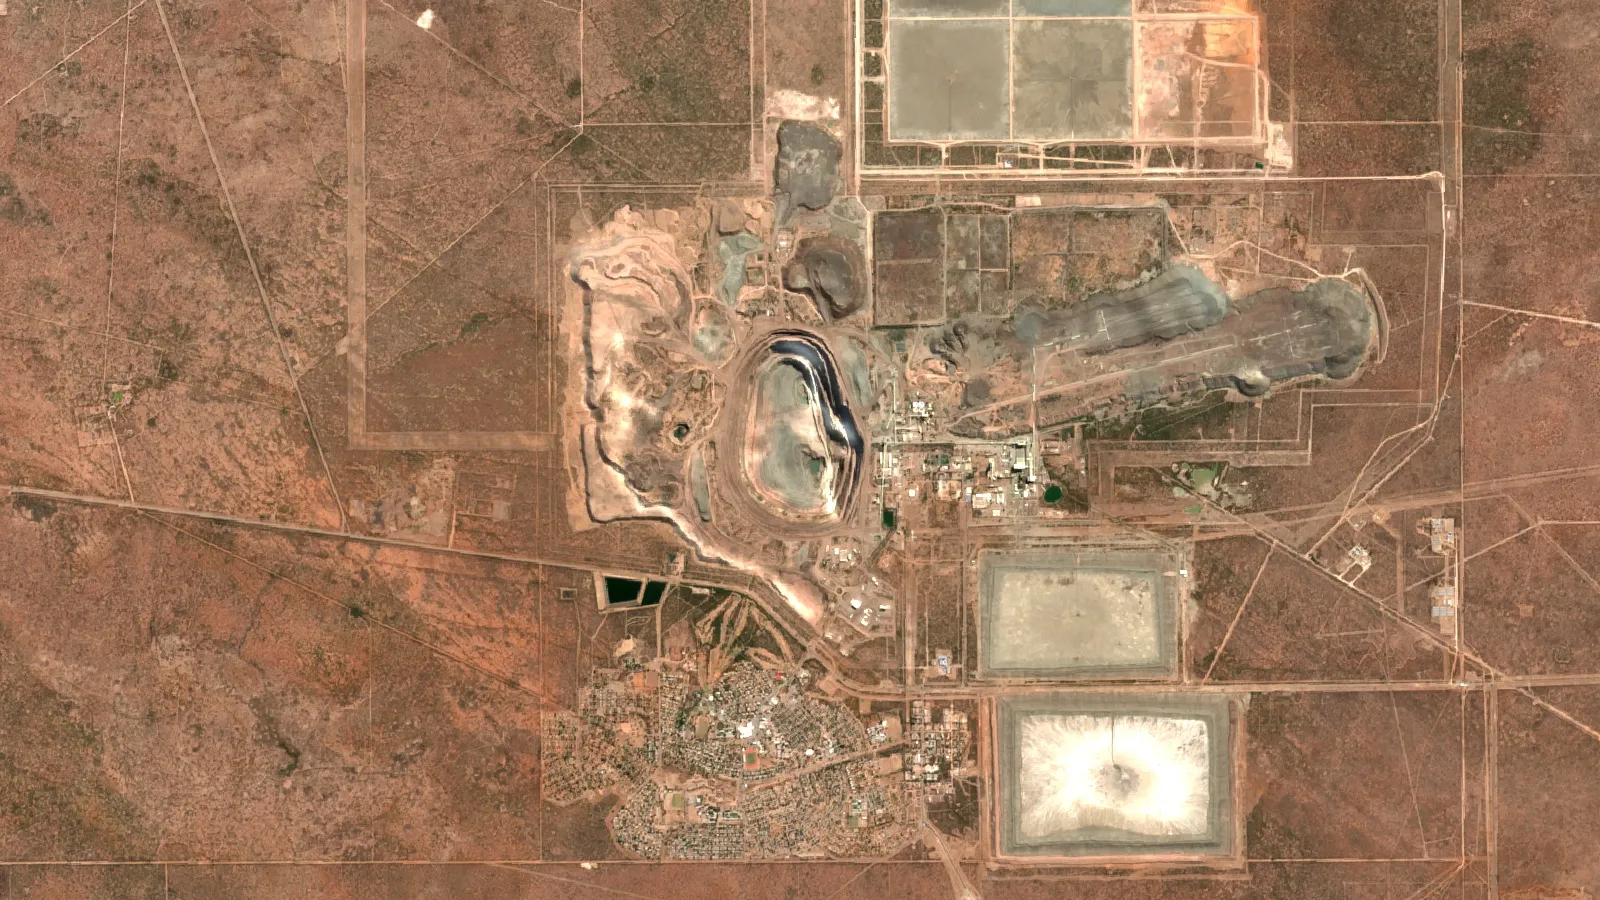
Key takeaways
- Russia mined 31.5 million of the world’s 98.8 million carats in 2025, about 32% (Kimberley Process).
- Namibia averaged US$344 a carat in 2025 against about US$5 in DR Congo, so carats alone do not show value (Kimberley Process).
- China led gold at an estimated 380 tonnes of 3,300 tonnes in 2025 (USGS, 2026).
- Mexico led silver at an estimated 6,300 tonnes of 26,000 tonnes in 2025 (USGS, 2026).
- Only about a quarter of mined silver comes from primary silver mines (World Silver Survey 2026).
In this article
Diamond is mostly found in Russia, Botswana, Angola and Canada, which together mined about 77% of the world’s 98.8 million carats of rough stones in 2025, according to the Kimberley Process Annual Global Summary. A carat is 0.2 grams. Russia alone supplied about 32%. Geologically, the stones come from kimberlite pipes, which are narrow columns of volcanic rock, and from river, beach and seabed gravels that were washed out of those pipes.
Gold and silver follow different rules. Gold is spread across many countries, and silver comes mostly as a by-product of mines that dig for other metals. This page gives the seven leading regions for each one, with the output figures, the mines behind them, and a calculator for testing what a diamond parcel could be worth.
Where is diamond mostly found? The 7 top regions
The ranking below uses carats mined in 2025 from the Kimberley Process, the government scheme that tracks rough diamond trade. The top seven producers made about 96% of the world’s carats. African producers made more than half of the total.
Chart
Rough diamond output by country
Million carats, seven largest producers, 2025
- Russia, Yakutia: 31.5 million carats. Almost all of it comes from Alrosa, whose listed assets sit in units at Mirny, Nyurba and Udachny. The company also mines in the Arkhangelsk province in the northwest, where the Lomonosov deposit is described by the Gemological Institute of America as Europe’s first diamond mine.
- Botswana, Orapa and Jwaneng: 15.5 million carats. De Beers reports 7.9 million carats from the Orapa group and 7.3 million from Jwaneng in 2025. Both belong to Debswana, a 50:50 venture with the government, and Anglo American calls Jwaneng one of the world’s richest diamond mines.
- Angola, Lunda Norte and Lunda Sul: 15.2 million carats. Output is concentrated in these two northeastern provinces, from both kimberlite pipes and alluvial gravels. Catoca, an open-pit mine near Saurimo in Lunda Sul, is the best-known operation.
- Canada, Northwest Territories: 14.1 million carats. This total will fall. Rio Tinto’s Diavik delivered its final production on 26 March 2026 after 23 years and more than 150 million carats. Ekati was set to close in August 2026, which would leave Gahcho Kué as the country’s one operating mine, with production there due to end in late 2027.
- Democratic Republic of Congo, Kasai: 8.9 million carats. IPIS estimates that about 450,000 artisanal miners, meaning small-scale diggers working mostly by hand, supply 60% to 80% of export volumes. The stones are low in value, at about US$5 a carat in 2025.
- South Africa, Limpopo and Gauteng: 5.6 million carats. De Beers runs Venetia in Limpopo and Petra Diamonds runs Cullinan. National Jeweler reported in 2026 that De Beers planned a two-year production pause at Venetia from the second half of the year.
- Zimbabwe, Marange: 4.2 million carats. The Marange field is its best-known source, and it averaged about US$24 a carat in 2025.
For the country table by value and past years, see our ranking of the top diamond producing countries. For the companies behind the mines, see the biggest diamond companies by carats.
Most carats is not the same as most value
Carat counts can mislead a reader who cares about money. In 2025, Russia’s stones averaged US$86 a carat, Botswana’s US$128 and Canada’s US$63, while Namibia’s reached US$344 and Lesotho’s US$331. Namibia ranks eighth by carats, at 2.1 million, yet it produced US$721 million of rough, about seven times the 2025 production value of Zimbabwe’s 4.2 million carats. Much of its output comes from the sea: vessels recover diamond gravel from the Atlantic seabed at about 90 to 150 metres. Russia still led by total value, at US$2.72 billion of the world’s US$9.23 billion.
Reserves point the same way, with one caveat
The U.S. Geological Survey puts Russia’s reserves at 750 million carats of a world total of 1,700 million, or about 44%. That table covers natural industrial diamond only, so it is not a measure of gem stones. USGS also says natural deposits have been discovered in more than 35 countries, which is why “found” and “mined at scale” are different questions.
Why diamonds are found where they are
Diamonds form far below the surface, in the cold, thick roots beneath the oldest parts of continents. Geologists call these old continental blocks cratons, and the root beneath one is called a keel. A review in Gems & Gemology explains that the keel can reach about 250 km deep, and that only this zone is cold enough at high enough pressure to keep diamonds stable. The same review shows that lithospheric diamonds are often older than 1 billion years, while most kimberlite eruptions are younger than 550 million years. The volcano is only the elevator. It did not make the stones.
Infographic
How a diamond reaches the surface in 5 steps
- 1Forms deepCarbon crystallises in the cold root under an old continent.
- 2WaitsStones can sit in the keel for more than a billion years.
- 3EruptsA kimberlite magma rises and carries some stones with it.
- 4Sets in a pipeThe magma cools in a narrow pipe, the primary deposit.
- 5ErodesWater moves some stones into gravels, the alluvial deposit.
Chart
Average value per carat
US$ per carat of rough, selected producers, 2025
That gives anyone screening ground a simple order of questions:
- Is it on an old craton? The review’s world map shows most kimberlite-hosted localities on or near ancient crust.
- Is there a pipe? Primary deposits are kimberlite, or the related rock lamproite. Not every kimberlite carries stones worth mining, so finding one is only a first step.
- Is there a gravel trail? Secondary, or alluvial, deposits form when erosion frees stones and water carries them away. They can lie far from their source, as in the Kasai and along the Namibian coast.
Alrosa’s own portfolio shows how the two types compare. For deposits currently explored, it lists 10 primary and 9 alluvial, with 93% of the diamonds in primary deposits and 7% in alluvial ones. It gives an average grade of about 1.01 carats per tonne.
How the main diamond deposit types are mined
| Deposit type | Where it dominates | Usual method | What to check first |
|---|---|---|---|
| Kimberlite pipe | Yakutia, Botswana, Northwest Territories, Lunda Sul | Open pit, then underground as the pit deepens | Diamonds per tonne and value per carat, from a bulk sample |
| Lamproite pipe | Argyle in Western Australia, closed in November 2020 | Open pit, then underground | Stone size and colour, since many small stones can sell cheaply |
| River and floodplain gravel | Kasai, Lunda Norte, West African rivers | Artisanal digging, or dredging and small plants | Who holds the licence, and whether the gravel has been worked already |
| Marine gravel | Namibia’s Atlantic coast | Specialised vessels | Mostly a large-company business because of the capital needed |
A satellite cannot see a diamond or a buried pipe directly. What imagery can do for a licence holder or consultant is map old workings, drainage and gravel terraces, and surface changes, so that ground crews sample in better places. Any such map gives targets for follow-up and never confirms that stones are present.
Calculator
What could a diamond parcel be worth before costs?
Enter your own sample results and a price for that deposit.
- Gross value at your price (US$): $900,000
- Gross value per tonne processed (US$): 90.00
Example values only, not a benchmark or a forecast. Grade is carats per hundred tonnes (cpht). Prices are inputs: use today’s price for your own stones. The result is gross value before mining, processing, royalties and tax.
Where is gold mostly found? 7 leading regions
Gold is far less concentrated than diamond. China led in 2025 with an estimated 380 tonnes out of a world total of 3,300 tonnes, according to USGS Mineral Commodity Summaries 2026. The top seven countries in that table made about 49% of world output, and “other countries” made nearly a third. As a dated price marker, gold was about US$4,122 per troy ounce at 9:10 a.m. Eastern on 5 November 2026 (Fortune).
Chart
Gold mine output by country
Tonnes, seven largest producers, 2025 estimates
- China: 380 tonnes. The World Gold Council also names China as the largest producer, at around 10% of global mine output.
- Russia: 310 tonnes. USGS gives this as an estimate and ranks Russia second in the world.
- Australia, led by Western Australia: 280 tonnes. Geoscience Australia’s resource tables give the national picture. The best-known site is the Kalgoorlie Super Pit.
- Canada: 200 tonnes. The World Gold Council’s 2025 supply review credits growth to three new mines: Blackwater, Back River and Valentine Lake.
- United States, Nevada: 160 tonnes. USGS says Nevada made about 64% of US gold and Alaska about 22%. Nevada’s output centres on the Carlin Trend, a belt of sediment-hosted deposits where the gold is usually too fine to see.
- Ghana: 150 tonnes. The same World Gold Council review credits Newmont’s Ahafo North project, higher output at Obuasi, and more artisanal gold for the 2025 rise.
- Mexico: 140 tonnes. Much of this comes from mixed metal mines. Peñasquito in Zacatecas, for example, produces gold, silver, lead and zinc.
South Africa no longer makes this list, at 90 tonnes in 2025, yet history still favours it. Consultants at SRK estimate that 30% to 40% of all gold ever mined, more than 1.6 billion ounces, came from the Witwatersrand Basin. The full list by country is in our guide to the top gold producing countries.
Where gold sits in the rock
- Lode or vein deposits: gold in quartz veins along old faults, mined underground or in open pits. Kalgoorlie is a famous example.
- Sediment-hosted deposits: very fine gold spread through sedimentary rock, as in Nevada.
- Ancient conglomerates: gold in old pebble beds called reefs, as in the Witwatersrand.
- Placer deposits: loose gold in river gravel. USGS records several large placer mines in Alaska and many smaller ones there and in the western states.
- By-product gold: gold recovered during base-metal processing. USGS puts this at about 7% of US gold, chiefly from copper ores.
▶ How gold is mined and refined, step by step from rock to ring · 5:27
Where is silver mostly found? 7 leading regions
Mexico mined the most silver in 2025, an estimated 6,300 tonnes of a world total of 26,000 tonnes, or about 24%, according to USGS. The top seven made about 72%. Silver was about US$52.85 per troy ounce at 6 a.m. Eastern on 5 November 2026 (Fortune). More detail on the leader is in which country mines the most silver.
Chart
Where mined silver comes from
Million troy ounces by main mine type, 2025
Chart
Silver mine output, 2024 and 2025
Tonnes, seven largest producers; 2025 figures are estimates
- Mexico, Zacatecas: 6,300 tonnes. Peñasquito was the world’s largest silver mine in 2025 at 28 million ounces, in the Silver Institute’s World Silver Survey 2026. Fresnillo, Saucito and Juanicipio are also in Mexico.
- Peru, central Andes: 3,600 tonnes. Antamina, a copper and zinc mine, ranked second in that survey at 17.7 million ounces.
- China: 3,400 tonnes. USGS gives the national figure only.
- Bolivia: 1,500 tonnes. San Cristóbal made 17.6 million ounces in 2025, level with Juanicipio.
- Chile: 1,400 tonnes. Copper mines contribute. Escondida, covered among the largest copper mines, made 7.8 million ounces.
- Poland: 1,300 tonnes. Silver here comes with copper. The survey lists the KGHM group at 41.1 million ounces, which is a combined group figure, not one mine.
- Russia: 1,200 tonnes. USGS shows a fall from 1,280 tonnes in 2024, while the World Silver Survey shows Russian output up 23% in 2025, so the sources differ.
Which mines lead the list changes often with ore grade, so see our table of the largest silver mines in the world for all 17 producers above 8 million ounces.
Why silver follows other metals
Only about a quarter of mined silver comes from mines whose main product is silver. The World Silver Survey splits 2025 output into 249.1 million ounces from lead-zinc mines, 237.3 million from copper mines, 221.1 million from primary silver mines and 134.7 million from gold mines. So a rise in silver prices does not by itself bring much new supply, because many of those mines are planned around another metal. For a consultant or investor reading a silver claim, this also means the host ore often matters as much as the silver grade. Grade is the amount of metal in each tonne of rock, given for silver in grams per tonne (g/t).
Silver, gold and diamond compared
| Question | Diamond | Gold | Silver |
|---|---|---|---|
| Top producer, 2025 | Russia, 31.5 million carats | China, 380 tonnes | Mexico, 6,300 tonnes |
| Top producer’s share | About 32% | About 12% | About 24% |
| Share of top seven | About 96% | About 49% | About 72% |
| Main source rock | Kimberlite pipes and gravels from them | Veins, sediment-hosted ores, conglomerates, placers | Lead-zinc, copper, silver and gold ores |
| Data source | Kimberley Process | USGS | USGS |
The Kimberley Process figures are reported by member governments, while the USGS figures for 2025 are estimates. The two series are not directly comparable, so read the shares as a guide to concentration.
▶ Seven environmental impacts of mining, explained in plain words · 2:31
What to check before you act on a region
A famous district does not make a particular licence valuable. If you own or are assessing ground, work through these steps in order.
▶ What satellites can and cannot show when screening ground for gold · 4:25
- Confirm the title. Check the licence or claim with the official cadastre, including holder, expiry and minerals covered. Some diamond areas also carry Kimberley Process export rules.
- Screen the geology. For diamonds, start with craton position and known pipes. For gold and silver, look at host rock, faults and past workings.
- Review earlier work. Read government reports and old sampling data. Check whether the gravels were already mined.
- Sample before you value. Diamonds need bulk samples to estimate value, since a few large stones can change the average price. Gold and silver need assays from a lab.
- Price it on the right basis. Use the value per carat for that deposit, not a national or world average.
- Plan for closure and water. Rehabilitation is a cost from the first year. At Diavik, Rio Tinto is decommissioning buildings and returning lake water to the pits. Tailings and water rules vary by country, so confirm them with the regulator.
Early-stage screening is one place Farmonaut fits. Its satellite-based mineral detection ranks target zones on a licence boundary for ground follow-up, and results are exploration targets, not a resource estimate. You can send a project query or contact the team.
Frequently asked questions
Where is diamond mostly found in the world?
Mostly in Russia, Botswana, Angola and Canada, which mined about 77% of the world’s carats in 2025 on Kimberley Process figures. Russia alone mined 31.5 million of the 98.8 million carats.
Which country has the most diamonds?
Russia leads both output and reserves. USGS lists 750 million carats of natural industrial diamond reserves for Russia, of 1,700 million worldwide. No equivalent reserve table covers gem diamonds in that report.
Which continent produces the most diamonds?
Africa. African producers made more than half of world carats in 2025, led by Botswana, Angola and the Democratic Republic of Congo.
What rock are diamonds found in?
Mostly kimberlite, a volcanic rock that carried them up from the deep mantle. Some mines work lamproite, the host at Argyle in Australia. Others work gravels eroded from these rocks.
How deep do diamonds form?
Most mined diamonds form in the thick roots under old continents, which can reach about 250 km deep according to a Gems & Gemology review. A small group, called superdeep diamonds, comes from even farther down.
Are diamonds found in the United States?
Yes, but not at commercial scale. USGS reports no domestic mine output of natural industrial diamond stone. Crater of Diamonds State Park in Arkansas lets the public search a 37-acre field on the eroded surface of a volcanic crater.
Are there still diamond mines in Australia?
Argyle, the country’s main mine, stopped in November 2020, and Australia was not among the producers reporting output to the Kimberley Process for 2025.
Where is gold mostly found?
By country, China, Russia and Australia mined the most in 2025, on USGS estimates. By rock type, it occurs in quartz veins, sediment-hosted ores, ancient conglomerates and river placers.
Where is silver mostly found?
Mexico, Peru and China led in 2025. Most silver comes from lead-zinc, copper and gold mines rather than from silver mines alone.
Which is rarer, gold or diamond?
The two are not measured alike, so output alone does not settle it. In 2025 the world mined 98.8 million carats of diamond, which is about 20 tonnes by weight, against about 3,300 tonnes of gold. Much of that diamond is low-value, as Congo’s US$5 a carat average shows.
This page is for information only. It is not investment or legal advice. Prospect only with permission and the right licence, follow safety rules, and never use mercury.
Farmonaut mining
Map your mining site from space
Send a licence boundary for a satellite screen that ranks target zones for ground follow-up. Results are exploration targets, not a resource estimate.

Mining Pro sample view, synthetic data
Keep reading
Sources
- Kimberley Process, Annual Global Summary 2025: kimberleyprocessstatistics.org
- USGS, Mineral Commodity Summaries 2026: Diamond (Industrial): pubs.usgs.gov
- USGS, Mineral Commodity Summaries 2026: Gold: pubs.usgs.gov
- USGS, Mineral Commodity Summaries 2026: Silver: pubs.usgs.gov
- Shirey and Shigley, Recent Advances in Understanding the Geology of Diamonds, Gems & Gemology (2013): gia.edu
- Gems & Gemology, Geology and Development of the Lomonosov Deposit (2017): gia.edu
- Alrosa, Resources and Assets: alrosa.ru
- De Beers, Production Report for the Fourth Quarter of 2025 (5 February 2026): debeersgroup.com
- Anglo American, Diamonds: angloamerican.com
- Lobito Corridor Intelligence, Diamond Production in Angola (May 2026): lobitocorridor.com
- Rio Tinto, Diavik delivers its final production (26 March 2026): riotinto.com
- National Jeweler, Ekati to close (July 2026): nationaljeweler.com
- National Jeweler, De Beers second-quarter production (July 2026): nationaljeweler.com
- IPIS, Diamonds in the DRC: ipisresearch.be
- World Diamond Council, Namibia case study: worlddiamondcouncil.org
- World Gold Council, Global mine production by country: gold.org
- World Gold Council, Gold Demand Trends full year 2025: Supply: gold.org
- Geoscience Australia, Australian Resources and Mineral Statistics, 2026 preliminary tables: ga.gov.au
- SRK Consulting, 140 Years of Mining the Witwatersrand Basin: srk.com
- Metals Focus for the Silver Institute, World Silver Survey 2026: silverinstitute.org
- Fortune, Current price of gold (5 November 2026): fortune.com
- Fortune, Current price of silver (5 November 2026): fortune.com
- Arkansas State Parks, Crater of Diamonds State Park: arkansasstateparks.com
- Gems & Gemology, Black Diamonds from Marange, Zimbabwe (2018): gia.edu
- Diavik: riotinto.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group

 Licence holder · Nigeria · Gold + lithium










