

Rare earths · Project timelines
Rare Earth Mine Timeline: Real Projects, Years and Costs
No average build time exists for rare earth mines, so this page uses dated projects. Iluka’s Eneabba refinery runs about five years from decision to commissioning; S&P Global finds 15.7 years from discovery to production for other metals.
Key takeaways
- Eneabba refinery (Iluka): decision 4 April 2022 with a capital estimate of A$1.0 to 1.2 billion and first production scheduled for 2025; commissioning now scheduled for mid 2027, capital estimate A$1.7 to 1.8 billion, construction 60% complete on 19 August 2026 (Iluka, ASX, 2022 and 2026).
- Across 127 mines of other metals started since 2002, discovery to production averaged 15.7 years, of which 11.9 went on discovery, exploration and studies (S&P Global, 2024).
- Averages from discovery to production: Zambia 34 years, United States almost 29, Canada 27, Australia 20 for critical-mineral mines, not including rare earths (S&P Global, 2024).
- Lynas’s Kalgoorlie plant budget rose from A$730 million to about A$800 million between August 2023 and April 2024, with first feed in December 2023 (Lynas, ASX, 2024).
- China mined 270,000 tonnes of rare earth oxide equivalent in 2025 and the United States 51,000 (USGS, 2026, estimates).
In this article
- How long does it take to build a rare earth mine and processing plant?
- Rare earth project timelines from real projects
- Where the years go: five stages
- Average years from discovery to production by country
- What a delay costs: interest, ramp-up and market timing
- Timeline and delay calculator
- Rare earth mine production outside China
- What you can do before the first drill hole
- How satellite screening shortens the first stage
- Risks that stretch the schedule
- Frequently asked questions
No source gives an average build time for rare earth mines, and the S&P Global samples below exclude them. The nearest sourced benchmarks are these. Iluka took its decision to build the Eneabba rare earth refinery in Western Australia on 4 April 2022 and now schedules commissioning for mid 2027, about five years later. For mines of other metals, S&P Global found 29 years from discovery to production in the United States and 20 in Australia. A rare earth project owner should plan in decades from discovery and in single-digit years from the investment decision.
This page uses dated project milestones, filings and regulator documents to show where those years go, what a delay costs, and what you can do before the first drill hole. It ends with a calculator for your own stage lengths and a set of answers to common questions. Terms are explained the first time they appear.
How long does it take to build a rare earth mine and processing plant?
Three separate clocks run on a rare earth project, and mixing them up is the most common error in published timelines.
- Discovery to first production. This is the full history of a deposit, from the first anomaly to the first saleable concentrate. S&P Global measured it for 127 mines that started up since 2002 and found a 15.7-year average. Their sample covers gold, copper, nickel, silver and zinc mines, not rare earths, so it is a benchmark from other metals, not a rare earth figure.
- Investment decision to first product. This is the clock a lender and a contractor care about. The Eneabba refinery is a live example: decision in April 2022, first production then scheduled for 2025, commissioning now scheduled for mid 2027 (60% built in August 2026).
- First product to full output. Ramp-up (raising a new plant step by step to its design rate) can take years. Lynas reported first feed into its new Kalgoorlie plant in December 2023, first carbonate in the June 2024 quarter, and was still reporting ramp-up work in its 2026 annual report.
A mine alone is only the first half of the job. Rare earth ore is usually turned into a mineral concentrate on site, then cracked and leached with acid or alkali, then split into individual oxides by solvent extraction (a chemical process that separates elements that behave almost alike). That second half, the processing plant, is where the longest delays and the largest cost increases have happened in the cases below.
Rare earth project timelines from real projects
The table gives dated milestones from company filings and public documents. It is not a ranking and it is not a forecast. Each project has a different start point, so compare the shape of the delays, not the totals.
| Project | Dated milestones | What it shows |
|---|---|---|
| Mountain Pass, California (MP Materials) | Rare earths found by uranium prospectors in 1949. MP Materials acquired the site in July 2017. It finished recommissioning its separation plant in 2023. The heavy rare earth facility was selected in February 2022, with commissioning expected in 2026 (February 2026 annual report; the second-quarter 2026 results give no update). A second magnet plant is expected to begin commissioning in 2028 (MP Materials annual report). | Restarting an existing mine took about six years to reach separated oxide. Each later step, from heavy rare earths to magnets, adds another build cycle. |
| Mt Weld and Kalgoorlie, Western Australia (Lynas) | Feasibility study completed in March 2005. The regulator dates operations at Mt Weld to 2007. The new Kalgoorlie cracking plant received first feed in December 2023, and its budget moved from A$730 million to about A$800 million between August 2023 and April 2024. | A producing mine can run for years before its processing chain is complete. Budget and commissioning dates moved together. |
| Eneabba refinery, Western Australia (Iluka) | Investment decision 4 April 2022, first production then scheduled for 2025. The capital estimate at the decision was A$1.0 to 1.2 billion (ASX, 4 April 2022) and A$1.7 to 1.8 billion by December 2024. On 22 June 2026 the refinery was over 50% complete and commissioning was scheduled for mid 2027; on 19 August 2026 Iluka said construction was 60% complete and first feedstock would arrive in 2027 (half-year results). | About five years from decision to commissioning. The first-production date moved from 2025 and the capital estimate rose from A$1.0 to 1.2 billion to A$1.7 to 1.8 billion. |
Two of the three cases, Kalgoorlie and Eneabba, show the same pattern: budgets and dates moved after the decision, once engineering, supply chains and labour met reality. Mountain Pass shows a different delay: each downstream step adds its own build cycle. That does not mean a new project will fail. It means a schedule with no slack is a warning sign for lenders, partners and licence holders.
Where the years go: five stages
This page uses five stages. The durations of each stage differ by deposit, country and ore type, so this page gives sourced benchmarks where they exist and leaves the rest to your own inputs in the calculator.
Infographic
Five stages from discovery to saleable product
- 1Explore and studyMap, sample, drill, test the ore and finish feasibility work.
- 2Permit and secure landEnvironmental approval, licences, water, waste and land access.
- 3Develop the mineDesign, roads, earthworks, tailings storage and equipment.
- 4Build the plantCracking, leaching, solvent extraction, utilities and residue handling.
- 5Commission and ramp upHot tests, saleable product, buyer approval, then design output.
Chart
Where the years go before a mine starts
Average years, 127 mines started since 2002 (gold, copper, nickel, silver, zinc; not rare earths); “Decision” is the time between feasibility and the construction decision
Stage 1: Exploration, resource definition and studies
This stage covers mapping, sampling, drilling, a resource estimate (a statement of how much material is in the ground and at what grade), metallurgical test work and the studies that follow: a scoping study, a pre-feasibility study and a definitive feasibility study. In the S&P Global sample it is the longest stage by far: 11.9 of the 15.7 years.
Rare earths add two special tasks. Test work must prove that the ore can be turned into products a buyer will accept, and each deposit has its own mix of light and heavy rare earths, so a flowsheet that works elsewhere cannot be copied. Plan for several rounds of pilot testing before a definitive study. Satellite screening belongs here: it narrows the ground you need to walk, sample and drill, which shortens the first part of this stage rather than the engineering that follows.
Stage 2: Permitting and land access
Permits are not one approval. They are a stack: an environmental assessment, a mining licence, water and waste permits. Rare earth processing leaves residues, and regulators can set limits on their radioactivity, as the Malaysian example below shows.
- In the United States, S&P Global reports that an environmental impact statement under the National Environmental Policy Act takes roughly four years by the government’s own estimate, before litigation risk is counted.
- In Western Australia, the Environmental Protection Authority recommended approval of the Mt Weld life-of-mine proposal on 9 November 2023, followed by a three-week public appeal period closing 30 November 2023, and the Minister for Environment approved the proposal in Ministerial Statement 1216, published on 20 December 2023 (Lynas compliance report).
- In Malaysia, the operating licence for Lynas’s processing plant was renewed for 10 years from 3 March 2026. The licence requires an alternative cracking process so that the plant no longer produces water leach purification (WLP) residue above 1 becquerel per gram after 2 March 2031, with the change to start under an agreed plan by March 2028 (Lynas annual report).
Land access is the other half of this stage. A deposit under a town, a farm, a protected area or a community’s land can be excellent rock and still unmineable. Check land status early, before design money is spent.
Stage 3: Mine development
Mine development means final mine design, access roads, site earthworks, waste rock and tailings storage, power, water and the first fleet of equipment. For scale, the USGS estimates that the United States produced 51,000 tonnes of rare earth oxide equivalent in 2025, almost all from one open pit. Tailings design deserves early attention: the EPA Western Australia report notes that research at Mt Weld cut the volume of tailings needing storage by 50%.
Stage 4: Processing plant construction
The plant is the hardest part. It needs acid or alkali supply, large volumes of water, steady power, a long line of solvent extraction circuits, effluent handling and a way to dispose of residues. The plant also needs trained operators, which are scarce. Order long-lead items, such as extraction equipment and control systems, as soon as the decision is taken.
Stage 5: Commissioning, ramp-up and first sales
Commissioning moves a plant from cold tests to hot tests to saleable product. Ramp-up raises output to design rate. Buyers qualify products before they sign long contracts, so first sales can lag first product. MP Materials, for example, started to commission its magnet equipment at the end of 2025 and describes magnet qualification with customers as continuing in the second quarter of 2026.
Average years from discovery to production by country
Where a project sits matters nearly as much as what it mines. S&P Global’s 268-mine study of critical-mineral mines found large gaps between countries. The chart shows the averages reported by S&P Global. It does not include rare earth mines, and for mines not yet in production the study assumes a 2030 start.
Chart
Average years from discovery to first production
Critical-mineral mines in S&P Global’s 268-mine study; rare earths not included; non-operating mines assumed to start in 2030
What a delay costs: interest, ramp-up and market timing
A delay costs money in three ways. The first is interest on money already drawn. The second is revenue pushed back. The third is a missed market window. The Eneabba refinery shows how fast the first one grows: Iluka expects to have drawn the first A$1.25 billion of its A$1.65 billion government loan by the end of 2026, when the plant should be about 75% built (ASX announcement, June 2026). Every month of delay on drawn debt is a month of interest on a very large balance.
Iluka’s April 2022 plan gave first production in 2025; the June 2026 notice gives commissioning in mid 2027, and the August 2026 results say first feedstock arrives in 2027. For a project that sells separated oxides, revenue arrives later by about that gap, while fixed costs of the owner’s team and site continue.
Market timing is the third effect. The USGS reports an average 2025 price for neodymium-praseodymium oxide (NdPr, the pair used in the strongest permanent magnets) of about US$69 per kilogram, against US$124 in 2022. A project that moves into a lower-price period can fail a financing test it passed at decision. Test your own schedule and loan with the calculator below.
Timeline and delay calculator
Use the calculator to see how long your own project takes from the start of studies to full ramp-up, and what a further slip costs in interest. Stages are entered as sequential periods. If you run stages in parallel, enter only the extra time each one needs after the earlier stage has finished.
Calculator
How long will my project take, and what does a slip cost?
Enter your own stage lengths, debt and interest rate.
- Total schedule in months: 102 months
- Schedule with the extra delay: 9.5 years
- Interest cost of the delay (simple interest): 40.0 US$ million
Example values only, not benchmarks or forecasts. Stages are added one after another: if stages overlap, enter only the extra time each needs. Interest is simple interest on drawn debt (US$), your own loan terms apply. Construction covers mine development and plant construction together.
Rare earth mine production outside China
The chart below puts the build times above in context. China produced 270,000 tonnes of rare earth oxide equivalent in 2025, according to USGS, which is more than all other countries combined by a wide margin. Outside China the producing countries are few, and several were flat or lower between 2024 and 2025. That is what slow build times look like from the supply side: the list of new producers does not grow quickly. The chart shows selected producers outside China, with the 2025 figures marked as estimates by USGS.
Chart
Rare earth mine production outside China
Tonnes of rare earth oxide equivalent; selected producers
What you can do before the first drill hole
In the S&P Global sample, 11.9 of 15.7 years went on discovery, exploration and studies. Five early steps can shorten the first two stages.
- Test the ore before the study. A bench test on core samples tells you whether the ore can make a saleable product. Do this before committing to a definitive study.
- Map land access and protected areas first. Overlay your licence on land use, communities, water and protected areas. Remove ground that cannot be mined from the plan before design work starts.
- Start environmental baselines early. Water, air, fauna and community studies take a full seasonal cycle at least. Begin them while drilling is under way, not after.
- Agree the waste plan. The licence condition on residue radioactivity at Lynas Malaysia shows that waste is a licence matter, not an afterthought.
- Order long-lead items on the decision date. Delays on extraction equipment and control systems have delayed commissioning in the cases above.
The video below explains remote sensing, a tool for the first two steps.
▶ Explains the six instrument families used in remote sensing for mining and why agreement between them matters. · 2:01
How satellite screening shortens the first stage
Satellite imagery cannot see rare earths directly. It maps surface rock types, alteration, structures, vegetation and land cover around a licence area, and it can show which parts of a large licence deserve ground work first. That narrows the area to walk, sample and drill. Farmonaut takes a licence boundary or a KML or KMZ polygon and returns a satellite-based screening report, which is an exploration target and sits ahead of a resource estimate. Farmonaut reports that its early screening can cost up to 80-85% less than conventional early exploration and takes 5 to 20 business days. See satellite-based mineral detection for the method, or request a quote for your own licence. Questions about the service can go through contact us.
The same view also helps with land-access checks. The video below shows how a survey found that a large share of anomalous ground sat under a town.
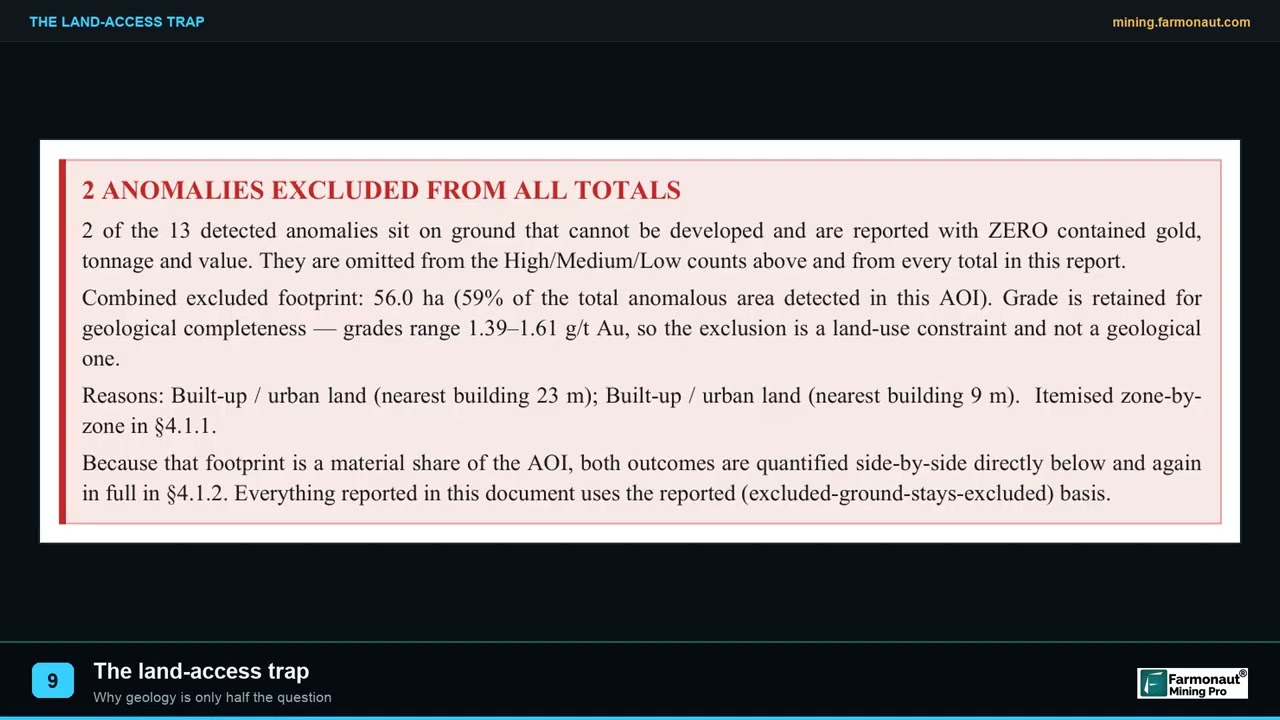
▶ Shows a survey where 59% of the anomalous ground sat under a town, a land access problem. · 2:05
Risks that stretch the schedule
- Permitting and litigation. S&P Global found more litigation mentions for US mining properties than for Canadian and Australian properties combined. A permit granted is not always a permit that survives challenge.
- Cost growth. Both Lynas Kalgoorlie (A$730 million to about A$800 million) and Eneabba (A$1.0 to 1.2 billion at the April 2022 decision, A$1.7 to 1.8 billion by December 2024) saw estimates move upward after the decision. Include a contingency larger than a normal mine project.
- Ramp-up shortfalls. Lynas reported ramp-up challenges at Kalgoorlie, including a power outage in January 2024, and completed process modifications at Kalgoorlie in the year to June 2026 while ramp-up continued.
- Market risk. Prices for NdPr oxide fell from US$124 per kilogram in 2022 to US$55 in 2024 (USGS annual averages) before rising to about US$69 in 2025 (estimate).
- Waste and radioactivity. Residue rules are written into licences, as the Malaysian condition shows.
▶ Explains seven environmental impacts of mining in plain words, with satellite maps. · 2:31
We cover a connected topic in Copper Mine Valuation: Build an NPV Model Step by Step.
For a closer look at a related question, see our guide: Phoenix Gold Mine Colorado: Tours, Prices and Real Gold.
Frequently asked questions
How long does it take to build a rare earth mine?
There is no published average for rare earth mines. For mines of other metals, S&P Global found 15.7 years from discovery to production across 127 mines started since 2002, and 17.9 years for the smaller group that started in 2020 to 2023. From the investment decision to commissioning, the Eneabba refinery is on a path of about five years.
How long does it take to build a rare earth processing plant?
Eneabba is on a path of about five years from decision to commissioning. Iluka’s Eneabba refinery was approved in April 2022 and is scheduled for commissioning in mid 2027. Lynas’s Kalgoorlie plant received first feed in December 2023 and produced its first carbonate in the June 2024 quarter. Use your own engineer’s schedule and add contingency.
Why does permitting take so long for rare earth projects?
Environmental assessments, water and waste permits, land access and radioactive-material rules all apply, often with several agencies. In the United States the government estimates about four years for an environmental impact statement alone (S&P Global, 2024).
What is the biggest cause of delay?
In the S&P Global sample, 11.9 of 15.7 years go on discovery, exploration and studies. After the decision to build, the cases above show delays from cost growth, equipment supply and ramp-up.
How much does a rare earth refinery cost?
Iluka’s Eneabba refinery has a capital estimate of A$1.7 to 1.8 billion (June 2026). Lynas’s Kalgoorlie plant has a budget of about A$800 million (April 2024). Costs depend on capacity, location and the products made.
Does a mine need its own processing plant?
No. Mt Weld in Western Australia ships concentrate to separate processing sites at Kalgoorlie and in Malaysia. The mine and plant timelines can therefore differ.
Which countries mine the most rare earths?
China produced 270,000 tonnes of oxide equivalent in 2025, the United States 51,000, Australia 29,000 and Burma 22,000 (USGS, 2026, estimates).
Can overlapping stages shorten the schedule?
Yes, but only if risks are managed. Starting environmental baselines during drilling and ordering long-lead items at decision time can save months. Starting construction before permits are secured risks wasted money.
How can satellites help early on?
They can screen a large licence for surface signs of alteration, structure and rock type, so drilling goes to the best ground first. The result is an exploration target, not a resource estimate.
Where can I get a satellite screening report for my licence?
You can ask for a quote with your licence boundary or coordinates.
This page is for information only. It is not investment advice. Company figures come from filings dated as shown and can change; check the latest announcement before relying on them.
Farmonaut mining
Get a quote for a satellite screen of your licence
Send your licence boundary and get a quote for a satellite screening report that ranks exploration targets ahead of any resource estimate.

Mining Pro sample view, synthetic data
Keep reading
Sources
- S&P Global, press release on mine development times (18 July 2024): press.spglobal.com
- S&P Global Market Intelligence, Mine Development Times: The U.S. in Perspective (June 2024): cdn.ihsmarkit.com
- USGS, Mineral Commodity Summaries 2026: Rare Earths: pubs.usgs.gov
- Iluka Resources, ASX announcement on the Eneabba refinery (June 2026): announcements.asx.com.au
- Iluka Resources, Eneabba Project Update (4 July 2022): iluka.com
- MP Materials, annual report on Form 10-K for 2025: s25.q4cdn.com
- MP Materials, second quarter 2026 results: mpmaterials.com
- Lynas Rare Earths, 2026 Annual Report: announcements.asx.com.au
- Lynas Rare Earths, quarterly report (April 2024): announcements.asx.com.au
- Lynas Rare Earths, 2024 Annual Report: announcements.asx.com.au
- EPA Western Australia, media statement on the Mt Weld life-of-mine proposal (9 November 2023): epa.wa.gov.au
- NASA Earth Observatory, Mountain Pass Rare Earth Mine: earthobservatory.nasa.gov
- Mining Technology, the history of Lynas’s Mount Weld mine: mining-technology.com
- Iluka Resources, ASX investor presentation on the Eneabba decision (4 April 2022): announcements.asx.com.au
- Lynas Rare Earths, Mt Weld Rare Earths Project Ministerial Statement 1216: lynasrareearths.com
- Iluka Resources, 2026 half-year results teleconference transcript: iluka.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd

 Licence holder · Nigeria · Gold + lithium










