

Coal · Company ranking
Largest Coal Companies in the US Ranked by Output
Peabody Energy is the largest US coal producer, with 95.8 million short tons or 18.7% of national output in 2024 (EIA). See all 20 major producers, which are listed, and what each reported for 2025 and expects for 2026.
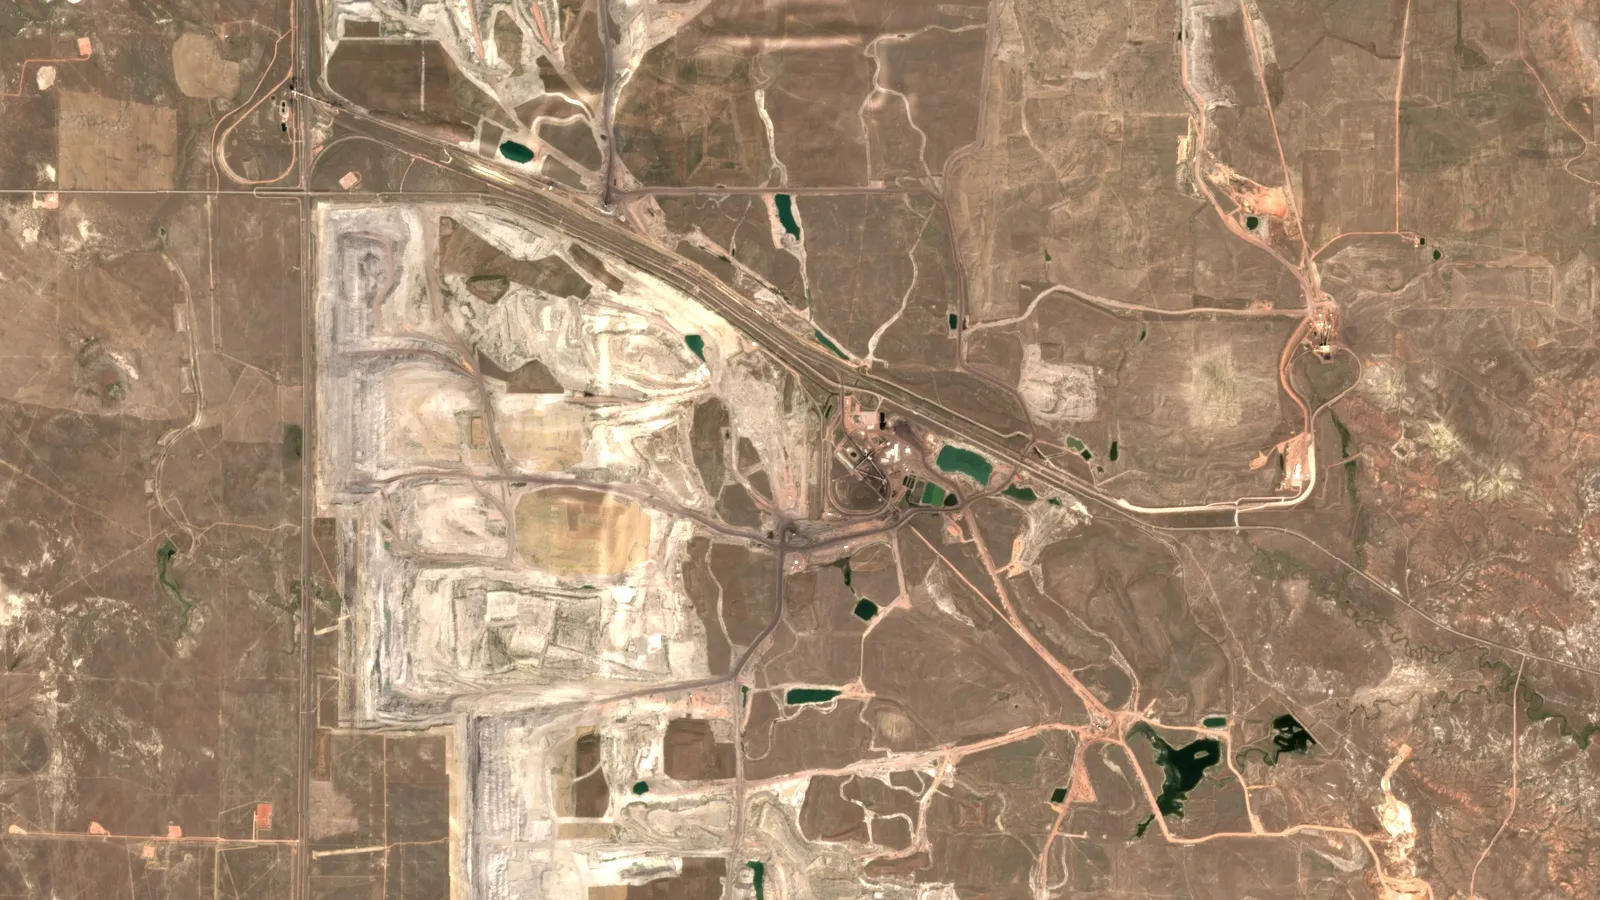
Key takeaways
- Peabody controlled 95.8 million short tons (18.7%) of US coal output in 2024 and Core Natural Resources 84.3 million tons (16.4%), out of 512.5 million tons (EIA Annual Coal Report 2024).
- The 20 largest producers controlled 84.5% of US output; eight of them, or their parents, are listed, and the rest are private or tribal (EIA; company filings).
- Core was formed by the merger of CONSOL Energy and Arch Resources on 14 January 2025 and trades on the NYSE as CNR.
- In 2025 Peabody sold 122.0 million tons (including Australia), Alliance 33.0 million, Alpha 15.3 million and Warrior a record 9.6 million (company releases, February 2026).
- The EIA estimates US output at 528.4 million tons in 2025 and forecasts 521.4 million for 2026 (Short-Term Energy Outlook, October 2026). This page is not investment advice.
In this article
- Largest coal companies in the US, ranked by EIA output
- How we ranked the companies
- Publicly traded coal companies and what they own
- Peabody Energy: the biggest US coal producer
- Core Natural Resources: Arch and CONSOL combined
- Alliance Resource Partners: Illinois Basin and Appalachia
- NACCO Industries: contract lignite mines
- Metallurgical coal producers: Alpha, Warrior, Coronado and Ramaco
- Private and tribal coal producers
- How the top producers changed year on year
- Surface and underground mining at the big producers
- Biggest coal mines in the US and who runs them
- US coal production trend and forecast
- Coal stock facts to check before you compare companies
Largest coal companies in the US, ranked by EIA output
Peabody Energy is the largest coal company in the United States. It controlled 95.8 million short tons of US coal output in 2024, or 18.7% of the national total of 512.5 million short tons, according to the EIA Annual Coal Report 2024 (published November 2025). Core Natural Resources ranks second with 84.3 million tons, and Navajo Transitional Energy Company third with 37.1 million tons. Together the top two producers controlled about 35% of all US coal mined that year.
Chart
Largest US coal producers by output, 2024
Million short tons mined in the US, by controlling company
This page ranks every company that the US Energy Information Administration (EIA) lists as a major producer, shows which ones are listed on a stock exchange, and sets out what each listed company reported for 2025 and expects for 2026. It also gives the national output trend and a calculator for revenue per ton. The figures are facts from government data and company filings. This page is not investment advice.
How we ranked the companies
The ranking metric is coal production in short tons in 2024, by controlling company, from Table 10 of the EIA Annual Coal Report 2024. That is the newest full-year federal table of producers by company. The EIA defines the controlling company as the one that controls the coal, in particular its sale. Most often that is the mine owner, but not always.
- One short ton is 2,000 pounds (about 0.907 metric tonnes). US federal data and US company filings use short tons. Companies with Australian mines, such as Peabody and Coronado, report some volumes in metric tonnes.
- Every qualifier is included. The EIA lists 20 companies that each produced more than 5 million short tons in 2024. All 20 appear in the table below, listed or private.
- US output only. The EIA counts coal mined in the United States. A company’s own total can be larger because it includes mines abroad, or smaller because it reports tons sold rather than tons mined.
- Company figures for 2025 come from each company’s own results release or annual report, dated in the text. They are not on the same basis as the EIA table, so we show them separately.
Two terms appear often. Thermal coal (also called steam coal) is burned in power plants to make electricity. Metallurgical coal (met or coking coal) is baked into coke for blast-furnace steelmaking and sells at a much higher price per ton. The Powder River Basin (PRB) of Wyoming and Montana is the main source of low-cost thermal coal; most US met coal comes from central Appalachia and Alabama.
| Rank | Controlling company (EIA name) | Listed? | 2024 US output (thousand short tons) |
|---|---|---|---|
| 1 | Peabody Energy | NYSE: BTU | 95,789 |
| 2 | Core Natural Resources | NYSE: CNR | 84,312 |
| 3 | Navajo Transitional Energy Co | No (Navajo Nation enterprise) | 37,112 |
| 4 | Alliance Resource Partners | Nasdaq: ARLP | 32,166 |
| 5 | David Michael Jamison / Petri E Koivula | No | 26,614 |
| 6 | ACNR Holdings | No | 26,100 |
| 7 | NACCO Industries | NYSE: NC | 23,480 |
| 8 | Alpha Metallurgical Resources | NYSE: AMR | 15,518 |
| 9 | Foresight Energy | No | 15,447 |
| 10 | Vistra | Utility (NYSE: VST) | 8,917 |
| 11 | Seven Global Investments | No | 8,821 |
| 12 | Warrior Met Coal | NYSE: HCC | 8,247 |
| 13 | Global Mining Group | No | 7,068 |
| 14 | Westmoreland Mining Holdings | No | 6,862 |
| 15 | Prairie State Energy Campus | No | 6,818 |
| 16 | Peter Kiewit Sons’ | No | 6,753 |
| 17 | Coronado Coal | Parent on ASX: CRN | 6,163 |
| 18 | Wolverine Fuels | No | 6,108 |
| 19 | J Clifford Forrest | No | 5,610 |
| 20 | Iron Senergy Holding | No | 5,153 |
The 20 companies above controlled 433.1 million tons, or 84.5% of US output in 2024; all other producers made the remaining 79.5 million tons (EIA, November 2025). The “Listed?” column is our addition from company filings. Vistra is an electricity company whose Luminant arm runs the Kosse lignite mine in Texas, so coal is a small part of its business.
Publicly traded coal companies and what they own
Eight of the 20 major producers, or their parents, have shares that trade on a public exchange. The table lists each one by what it mines in the US, its listing and its main coal type. It states facts from filings and is not a recommendation.
| Company | Listing | Main US coal type | Main US basins |
|---|---|---|---|
| Peabody Energy | NYSE: BTU | Thermal (PRB and Illinois Basin); met coal in Australia | Powder River Basin, Illinois Basin |
| Core Natural Resources | NYSE: CNR | Thermal and met | Northern and central Appalachia, PRB, Colorado |
| Alliance Resource Partners | Nasdaq: ARLP | Thermal | Illinois Basin, northern Appalachia |
| NACCO Industries | NYSE: NC | Lignite under contract to power plants | North Dakota, Mississippi |
| Alpha Metallurgical Resources | NYSE: AMR | Met | Central Appalachia |
| Warrior Met Coal | NYSE: HCC | Met | Alabama (Black Warrior Basin) |
| Coronado Global Resources | ASX: CRN | Met | Virginia and West Virginia; also Queensland, Australia |
| Ramaco Resources | Nasdaq: METC | Met | Southern West Virginia and southwest Virginia |
Ramaco is below the EIA’s 5-million-ton line, so it is not in the ranked table, but it is a listed US coal producer that sold 3.8 million tons in 2025, according to its 2025 Form 10-K. Vistra is listed too, but as a power company it is not a coal stock in the usual sense.
Peabody Energy: the biggest US coal producer
Peabody (NYSE: BTU) is based in St. Louis. Its largest asset is the North Antelope Rochelle Mine in Wyoming’s Powder River Basin, which produced 59.8 million short tons in 2024 and was the biggest coal mine in the country by a wide margin (EIA Annual Coal Report 2024, Table 9). Peabody also runs the Caballo and Rawhide mines in the PRB and the Bear Run surface mine in Indiana, among others.
In 2025 Peabody sold 122.0 million tons across all segments. The results release of 5 February 2026 breaks this into 84.5 million tons from the Powder River Basin, 13.4 million tons of other US thermal coal, 15.4 million tons of seaborne thermal coal and 8.6 million tons of seaborne metallurgical coal. The two seaborne segments are mostly Australian mines, so Peabody’s US total in 2025 was about 98 million tons.
The PRB shipped 4.9 million tons more in 2025 than in 2024. Peabody linked that to higher natural gas prices and more power demand, including from data centres, which raised coal plant use. The company’s main growth project is the Centurion underground met coal mine in Queensland, Australia. Peabody said in February 2026 that the longwall was about to start cutting coal two months ahead of schedule, with an estimated 3.5 million tons of premium hard coking coal in 2026.
Core Natural Resources: Arch and CONSOL combined
Core Natural Resources (NYSE: CNR) was formed when CONSOL Energy and Arch Resources completed an all-stock merger on 14 January 2025, according to the merger completion release filed with the SEC. Shares began trading as CNR on 15 January 2025, replacing CONSOL’s CEIX ticker. The head office is in Canonsburg, Pennsylvania.
The combined company’s main operations are the Pennsylvania Mining Complex (the Bailey, Enlow Fork and Harvey underground mines), the Leer and Leer South met coal mines in West Virginia, West Elk in Colorado, and the Black Thunder and Coal Creek surface mines in Campbell County, Wyoming, as described in the 2024 Form 10-K, which put Black Thunder’s proven and probable reserves at about 378 million tons at the end of 2024. Because the EIA’s 2024 table was compiled after the merger, it lists the combined business at 84.3 million tons; the EIA’s 2023 table showed Arch (75.3 million tons) and CONSOL (26.4 million tons) separately.
2025 was a difficult operating year. A fire at Leer South halted longwall mining there, and West Elk had to move to a new coal seam. In its fourth-quarter 2025 release (12 February 2026), Core said longwall mining at Leer South had resumed and both mines entered 2026 at targeted rates. Fourth-quarter sales were 7.8 million tons of high calorific value thermal coal, 2.3 million tons from the met segment and 12.6 million tons from the PRB.
Core’s 2026 guidance is 85.6 to 91.4 million tons of sales: 8.6 to 9.4 million tons of coking coal, 30.0 to 32.0 million tons of high calorific value thermal coal and 47.0 to 50.0 million tons from the PRB.
Alliance Resource Partners: Illinois Basin and Appalachia
Alliance Resource Partners (Nasdaq: ARLP) is a master limited partnership, so investors hold units rather than shares and receive quarterly cash distributions. Its mines include Hamilton, River View, Gibson South and MC Mining in the Illinois Basin, and Tunnel Ridge and Mettiki in northern Appalachia. River View in Kentucky produced 9.0 million tons in 2024 and Tunnel Ridge in West Virginia 6.0 million tons (EIA, Table 9).
The partnership’s fourth-quarter 2025 release (2 February 2026) reported 33.0 million tons of coal sold and 33.2 million tons produced in 2025. Its 2026 guidance is 33.75 to 35.25 million tons of sales: 26.0 to 27.0 million tons from the Illinois Basin and 7.75 to 8.25 million tons from Appalachia. Alliance also owns oil and gas mineral interests, which earned US$137.8 million in royalty revenue in 2025, so not all of its income is from coal.
NACCO Industries: contract lignite mines
NACCO (NYSE: NC) works differently from the other producers. Through North American Coal, its Utility Coal Mining segment runs lignite mines next to the power plants that burn the coal: Coteau, Coyote Creek and Falkirk in North Dakota and Mississippi Lignite Mining Company in Mississippi. Lignite is the lowest-rank coal, with a high moisture content, so it is rarely shipped far.
At Coteau, Coyote Creek and Falkirk, the power-plant customers fund the operating costs, capital and final reclamation, and NACCO earns a management fee per ton or per million British thermal units delivered, according to its 2025 Form 10-K. That structure means NACCO has little exposure to spot coal prices at those mines. The Mississippi mine is the exception: NACCO carries its costs and capital. Coteau’s Freedom Mine produced 11.9 million tons in 2024, the sixth-largest US mine (EIA, Table 9).
NACCO also has a Contract Mining segment that serves limestone quarries and other industrial-mineral producers, and its Sawtooth Mining subsidiary is the mining contractor for the Thacker Pass lithium project in Nevada. Readers comparing NACCO with other coal stocks should note that much of its value comes from fee-based contracts, not from selling coal at market prices.
Metallurgical coal producers: Alpha, Warrior, Coronado and Ramaco
Four listed companies mine mainly met coal in the US. Their volumes are smaller than the thermal producers, but each ton sells for several times the price of PRB coal, and most of it is exported to steelmakers abroad.
Chart
Coal sold in 2025 by listed producers
Million tons sold, company-reported; Peabody includes its Australian mines
Alpha Metallurgical Resources
Alpha (NYSE: AMR), based in Bristol, Tennessee, mines met coal in Virginia and West Virginia. Its full-year 2025 results (27 February 2026) reported 15.3 million tons sold. For 2026 Alpha guided to 15.1 to 16.5 million tons of shipments, of which 14.4 to 15.4 million tons are met coal and 0.7 to 1.1 million tons thermal coal. The EIA put Alpha’s 2024 US output at 15.5 million tons.
Warrior Met Coal
Warrior (NYSE: HCC) mines premium met coal from deep underground longwall mines in Alabama’s Black Warrior Basin. Its No. 7 mine produced 5.3 million tons in 2024 (EIA, Table 9). The company’s fourth-quarter 2025 release (12 February 2026) reported record 2025 sales of 9.6 million short tons, up 21% on 2024, and record production of 10.2 million tons.
The growth came from Blue Creek, a new longwall mine whose longwall commissioning began in October 2025, eight months ahead of schedule according to the company. Blue Creek sold 1.5 million tons in 2025. Warrior’s 2026 guidance is 12.5 to 13.5 million tons of sales and 12.0 to 13.0 million tons of production, and it expects the total Blue Creek project to cost US$995 million to US$1.075 billion.
Coronado Global Resources
Coronado (ASX: CRN) is listed in Australia. Its US operations are Buchanan in Virginia and Logan in West Virginia; it also owns the Curragh complex in Queensland. Its 2025 full-year results (24 February 2026) reported group saleable production of 16 million metric tonnes, with 2026 guidance of 16 to 17 million tonnes. The company said the Buchanan expansion and the Mammoth underground project in Australia were completed in 2025. The EIA put Coronado’s US output at 6.2 million short tons in 2024.
Ramaco Resources
Ramaco (Nasdaq: METC and METCB), based in Lexington, Kentucky, runs the Elk Creek, Berwind, Knox Creek and Maben met coal complexes in West Virginia and Virginia. It sold 3.8 million tons of coal in 2025 against 4.0 million tons in 2024, and reported revenue of US$536.6 million (Form 10-K for 2025). Ramaco is also developing the Brook Mine near Sheridan, Wyoming, as a rare earth element and critical mineral project in coal and carbonaceous rock. The company published an initial mineral resource estimate in September 2025; a resource is not a reserve, and the project is at an early stage. Our page on Wyoming rare earth deposits covers the geology of the area.
Private and tribal coal producers
More than half of the 20 major producers are not listed, so their numbers appear only in federal data. They matter to anyone studying the industry because they control almost a third of US output.
- Navajo Transitional Energy Company (NTEC) is owned by the Navajo Nation; the EIA’s 2020 table named the controlling company as the Navajo Nation itself. NTEC runs Antelope and Cordero Rojo in Wyoming and Spring Creek in Montana. Antelope produced 15.0 million tons and Spring Creek 13.1 million tons in 2024 (EIA, Table 9).
- Eagle Specialty Materials operates the Belle Ayr and Eagle Butte mines in the PRB (14.6 million and 11.0 million tons in 2024); the EIA lists its controlling owners as David Michael Jamison and Petri E Koivula.
- ACNR Holdings is the controlling company for 26.1 million tons; the EIA mine table shows large West Virginia underground mines run by Marshall County, Marion County, Harrison County and Ohio County Coal Resources, each producing 5.6 to 9.0 million tons in 2024.
- Foresight Energy mines in the Illinois Basin and controlled 15.4 million tons in 2024.
- Buckskin Mining Company runs the Buckskin Mine in Wyoming (6.8 million tons), and Westmoreland runs the Rosebud Mine in Montana (6.0 million tons).
- Prairie State Energy Campus controls the Lively Grove Mine in Illinois (6.8 million tons), which supplies the power plant of the same name.
For buyers who need a reliable coal supplier for an industrial plant, these private producers sell under contract just as the listed ones do. The EIA’s mine-level tables list who operates each large mine, which is the starting point for a supplier search.
How the top producers changed year on year
US output fell 11.3% in 2024, from 578.0 million tons to 512.5 million tons, and most of the large producers mined less (EIA Annual Coal Reports 2023 and 2024). Peabody went from 104.3 million tons to 95.8 million, NTEC from 45.7 million to 37.1 million, and ACNR from 32.2 million to 26.1 million. Alliance slipped from 34.9 million to 32.2 million tons and Alpha from 16.2 million to 15.5 million. NACCO was almost flat at 23.5 million tons because its output follows the needs of the power plants it supplies under contract.
Chart
Output change at large US coal producers
Million short tons mined in the US, by controlling company
The comparison for Core needs care. In the 2023 table Arch Resources (75.3 million tons) and CONSOL Energy (26.4 million tons) appear as two companies with a combined 101.7 million tons. The 2024 table lists Core at 84.3 million tons. Part of that fall came from lower PRB demand and part from mine problems, so it should not be read as a single cause. Output then rose again in 2025, when the EIA estimates national production at 528.4 million tons.
Surface and underground mining at the big producers
The EIA counted 524 producing US coal mines in 2024. Its Table 1 shows 177 underground mines that produced 206.2 million tons and 339 surface mines that produced 305.8 million tons, so surface mines supplied about 60% of the coal. The split explains much of the difference between the companies.
Peabody’s PRB mines, Core’s Black Thunder, NTEC’s Wyoming and Montana mines and NACCO’s North Dakota lignite mines are large surface operations. Draglines and truck-and-shovel fleets strip the rock above thick, shallow seams, which keeps the cost per ton low. Alliance, Warrior, Alpha, Ramaco and Core’s Pennsylvania and Leer mines are mostly underground. Many use longwall mining, in which a shearer moves along a wall of coal several hundred metres long while hydraulic roof supports advance behind it. Underground mines cost more per ton, but they reach the deeper, higher-quality seams that met coal buyers want.
For an investor or business owner, the mining method affects what can go wrong. Surface mines are exposed to rail service, weather and the pace of power demand, as Peabody’s PRB results show. Underground mines carry geological and safety risks: fires, roof falls and longwall moves can stop output for weeks, as the Leer South fire did for Core in 2025.
▶ Strip mining explained: how surface mines remove overburden to reach coal, with the pros and cons. · 4:37
Biggest coal mines in the US and who runs them
The largest companies own the largest mines. Eight of the ten biggest US coal mines in 2024 were surface mines in the Powder River Basin and North Dakota; the two exceptions were Core’s Bailey and Enlow Fork longwall mines in Pennsylvania.
| Mine | Operator group | State | Type | 2024 output (million short tons) |
|---|---|---|---|---|
| North Antelope Rochelle | Peabody | Wyoming | Surface | 59.8 |
| Black Thunder | Core (Thunder Basin Coal) | Wyoming | Surface | 44.5 |
| Antelope | NTEC | Wyoming | Surface | 15.0 |
| Belle Ayr | Eagle Specialty Materials | Wyoming | Surface | 14.6 |
| Spring Creek | NTEC | Montana | Surface | 13.1 |
| Freedom | NACCO (Coteau) | North Dakota | Surface | 11.9 |
| Eagle Butte | Eagle Specialty Materials | Wyoming | Surface | 11.0 |
| Caballo | Peabody | Wyoming | Surface | 10.8 |
| Bailey | Core (Pennsylvania Mining Complex) | Pennsylvania | Underground | 10.8 |
| Enlow Fork | Core (Pennsylvania Mining Complex) | Pennsylvania | Underground | 9.2 |
Source: EIA Annual Coal Report 2024, Table 9 (mines producing more than 4 million short tons). North Antelope Rochelle and Black Thunder together produced 104.3 million tons, about one fifth of the US total. For a map of active US mines across all commodities, see our US mining map by state.
US coal production trend and forecast
US coal output has fallen over the long term as gas and renewables replaced coal in power plants. The EIA’s annual reports show 535.4 million tons in 2020, a recovery to 594.2 million tons in 2022 and a drop to 512.5 million tons in 2024. The EIA’s Short-Term Energy Outlook of October 2026 estimates 528.4 million tons for 2025, then forecasts 521.4 million tons for 2026 and 513.9 million tons for 2027.
Chart
US coal production, 2020 to 2027
Million short tons; 2025 is an EIA estimate, 2026 and 2027 are forecasts
The same outlook shows where the coal goes. Power plants burned an estimated 417.0 million tons in 2025, and the EIA forecasts 390.8 million tons for 2026. Exports were 92.6 million tons in 2025, of which 50.1 million tons were met coal, and the EIA forecasts 102.4 million tons of exports for 2026. The Western region, which is mostly the PRB, produced 285.8 million tons in 2025, more than half the national total.
The EIA’s Quarterly Coal Report put second-quarter 2026 production at 125.4 million tons, 2.2% lower than a year earlier. For the companies, this means thermal producers depend on how hard utilities run their coal plants, while met producers depend on steel demand and export prices.
Coal stock facts to check before you compare companies
Readers searching for the best coal stocks or the best coal companies to invest in will find the same name in many lists for different reasons. Instead of a verdict, here are the facts that separate one company from another. None of this is a recommendation to buy or sell.
- Thermal or met mix. Peabody, Core and Alliance sell mostly thermal coal into the US power market; Alpha, Warrior, Coronado and Ramaco sell mostly met coal for steel. The two markets move on different prices.
- Domestic or export customers. Thermal coal from the PRB goes mainly to US utilities under contract. Met coal is largely exported, so it depends on seaborne prices and on freight and port capacity.
- Contracted volumes. Each company publishes how much of next year’s sales is already committed and priced. Alliance, for example, said in February 2026 that most of its 2026 volume was committed and priced; Warrior said 90% of expected 2026 sales were under contract.
- Mine life and reserves. The Form 10-K of each US-listed company reports coal reserves by mine. Long-life PRB reserves differ from a single new longwall mine.
- Non-coal income. Alliance has oil and gas royalties, NACCO has fee-based contracts and contract mining, and Ramaco has a rare earth project. Coal is only part of the story for these three.
- Corporate changes. Arch and CONSOL now trade together as Core. Older articles that name Arch Resources (ARCH) or CONSOL Energy (CEIX) as separate stocks are out of date.
- Reclamation and closure costs. Mine operators must restore land after mining. NACCO, for example, notes that its customers fund final reclamation at three of its four mines, while it carries that cost at the Mississippi mine.
For the economics of a single mine rather than a listed company, our guide to mining profitability explains margins, costs and payback.
What coal companies earn per ton
A coal company’s revenue is its tons sold multiplied by its realized price per ton, and its cash margin is that price minus its cash cost per ton. The gap between basins is large. Peabody’s February 2026 release guided first-quarter 2026 PRB sales of about 21 million tons at an average price of about US$13.40 per ton with costs of about US$11.75 to US$12.25 per ton. Core said it had signed 2.0 million tons of coking coal for North American customers at a fixed price of around US$125 per ton for 2026. Met coal therefore earns roughly ten times more per ton than PRB thermal coal, although its mining costs are also much higher.
Alliance’s 2026 guidance assumes an average coal sales price of US$54 to US$56 per ton, between the two. These are company figures for specific periods and products; prices change every month. The calculator below lets you test any volume, price and cost.
Calculator
What is a year of coal sales worth?
Enter tons sold, a price and a cash cost to estimate revenue and a cash margin.
- Cash cost for the year (US$ million): $400
- Cash margin (US$ million): $100
- Margin per ton (US$): 10.00
- Revenue change per US$1/ton (US$ million): $10
Example values only, not a company result or a forecast. Prices are inputs: use today’s price for the coal type and basin. Cost is cash cost per ton, an example. Results are before royalties, taxes, capital spending and freight.
Where satellite imagery fits for coal and mineral companies
Coal companies already use aerial and satellite imagery to track pit advance, spoil piles and reclamation progress, because surface mines can be measured from above. Owners and investors use the same imagery to check that a mine’s footprint matches what a company reports. Several coal producers are also looking beyond coal: Ramaco’s Brook Mine targets rare earths, and Peabody’s February 2026 release said it was evaluating rare earth and critical mineral potential on its land.
Farmonaut screens licence areas with satellite data for alteration and structural targets for metals and critical minerals ahead of drilling; details are on our satellite-based mineral detection page, and project requests go through the mining query form or the contact page. Satellite results are exploration targets, not resource estimates. Owners thinking of selling a mining property can also read how to sell a mine.
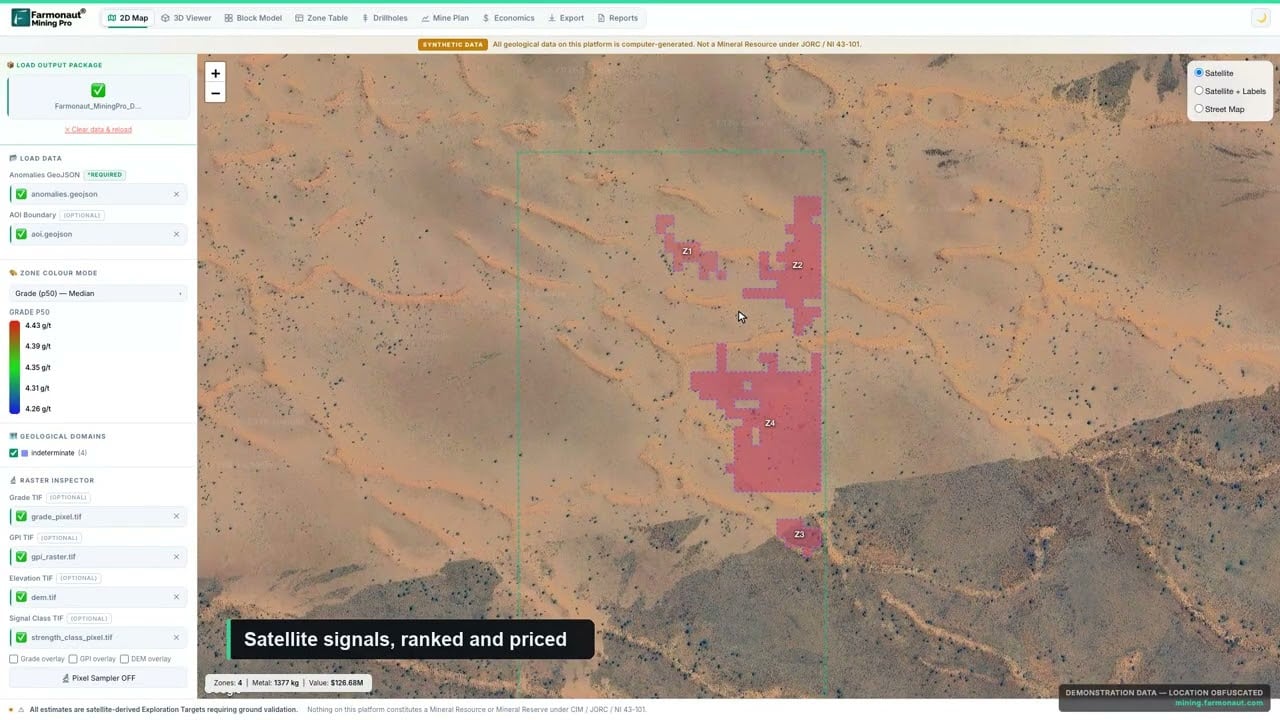
▶ A short look at Farmonaut Mining Pro, which turns a licence boundary into a geological and economic picture. · 4:56
Frequently asked questions
What is the largest coal company in the US?
Peabody Energy. It controlled 95.8 million short tons, 18.7% of US coal production, in 2024 (EIA Annual Coal Report 2024). It also runs the country’s biggest mine, North Antelope Rochelle in Wyoming.
What are the biggest coal companies in the US?
By 2024 output, the top five were Peabody Energy, Core Natural Resources, Navajo Transitional Energy Company, Alliance Resource Partners and the Jamison and Koivula group behind Eagle Specialty Materials (EIA). The top 20 controlled 84.5% of US output.
Which coal companies are publicly traded?
US coal producers with listed shares include Peabody (NYSE: BTU), Core Natural Resources (NYSE: CNR), Alliance Resource Partners (Nasdaq: ARLP), NACCO Industries (NYSE: NC), Alpha Metallurgical Resources (NYSE: AMR), Warrior Met Coal (NYSE: HCC), Ramaco Resources (Nasdaq: METC) and Coronado Global Resources (ASX: CRN).
What happened to Arch Resources and CONSOL Energy?
They merged. The deal closed on 14 January 2025, and the combined company, Core Natural Resources, began trading on the NYSE as CNR on 15 January 2025.
How much coal does the US produce?
The EIA counted 512.5 million short tons in 2024 and estimates 528.4 million tons for 2025. Its October 2026 outlook forecasts 521.4 million tons for 2026.
Which US coal companies mine metallurgical coal?
The main US met coal producers are Alpha Metallurgical Resources, Warrior Met Coal, Coronado Global Resources and Ramaco Resources. Core Natural Resources also mines met coal at Leer and Leer South in West Virginia.
Where is most US coal mined?
In the West, mostly Wyoming’s Powder River Basin. The EIA estimates the Western region produced 285.8 million tons in 2025, more than half the US total, while Appalachia produced 160.0 million tons.
Are coal stocks a good investment?
This page does not give investment advice. It sets out output, guidance and business mix from public filings so readers can compare companies. Speak to a licensed adviser and read each company’s latest filings before any decision.
How many coal mines operate in the US?
The EIA counted 524 producing coal mines in 2024, down from 560 in 2023 (Annual Coal Report 2024, Table 1).
What is the difference between thermal and metallurgical coal?
Thermal coal is burned to make electricity and steam. Metallurgical coal has properties that let it be turned into coke for steelmaking, and it sells for a much higher price per ton.
This page is for information only. It is not investment advice. It rates no company and names no security to buy or sell. Check company filings and speak to a licensed adviser.
Farmonaut mining
Screen your exploration ground from space
Farmonaut screens licence areas with satellite data to help rank metal and critical-mineral targets before drilling.

Mining Pro sample view, synthetic data
Keep reading
Sources
- US EIA, Annual Coal Report 2024 (November 2025): eia.gov
- US EIA, Annual Coal Report 2023: eia.gov
- US EIA, Annual Coal Report 2022: eia.gov
- US EIA, Annual Coal Report 2021: eia.gov
- US EIA, Annual Coal Report 2020: eia.gov
- US EIA, Short-Term Energy Outlook, October 2026: eia.gov
- US EIA, Quarterly Coal Report: eia.gov
- Peabody, results for the quarter and year ended 31 December 2025 (5 February 2026): peabodyenergy.investorroom.com
- Core Natural Resources, merger completion release (14 January 2025), SEC filing: sec.gov
- Core Natural Resources, 2024 Form 10-K: sec.gov
- Core Natural Resources, fourth quarter 2025 results (12 February 2026): filecache.investorroom.com
- Alliance Resource Partners, fourth quarter 2025 results and 2026 guidance (2 February 2026): sec.gov
- NACCO Industries, 2025 Form 10-K: sec.gov
- Alpha Metallurgical Resources, fourth quarter and full year 2025 results (27 February 2026): sec.gov
- Warrior Met Coal, fourth quarter and full year 2025 results (12 February 2026): sec.gov
- Coronado Global Resources, 2025 full year results, ASX (24 February 2026): announcements.asx.com.au
- Ramaco Resources, 2025 Form 10-K: sec.gov
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS

 Exploration consultancy · South Africa · Gold










