

Reviewed September 2026 against AgDirect’s published rate sheet and USDA Farm Service Agency lending-rate announcements.
Try it: Run your own numbers →
Table of Contents
- AgDirect Financing: The Short Answer
- Trivia: How Big Is AgDirect’s Loan Book
- AgDirect Rates vs. USDA FSA Rates: The Comparison Table
- Ag Equipment Financing: What Actually Drives the Cost
- Financing for Land in Texas and Other US Farm States
- Equipment Financing Near Lexington and Other Farm Credit Territories
- Equipment Loan Payment Calculator
- How Digital Underwriting Changes the Approval Process
- A Durable Checklist: How to Compare Any Ag Loan Offer
- Where Farmonaut Fits: Data for Loan and Insurance Verification
- Frequently Asked Questions
- Conclusion
AgDirect Financing: Rates, Terms, and How It Compares to USDA Loans
AgDirect financing is a point-of-sale equipment lending program, underwritten by Farm Credit Services, that lets US producers finance tractors, combines, sprayers, and other machinery directly through participating equipment dealers. As of September 2026, AgDirect’s published fixed rate runs from 6.50% on loans of $250,000 or more (2–7 year terms) up to 7.95% on small equipment loans between $5,000 and $24,000, with a 5.99% variable rate available across all loan sizes, according to AgDirect’s own rate sheet at agdirect.com/rates. That single page is also the fastest way to check today’s number, since AgDirect updates it directly and rates move monthly.
That’s the core answer for anyone searching “agdirect financing” or “agdirect.” The rest of this article covers how those rates stack up against USDA Farm Service Agency (FSA) direct loans, what “financing for land in Texas” actually involves, what equipment financing looks like for producers near Lexington-area Farm Credit territories, and a calculator to run your own numbers before you sign anything.
Trivia: AgDirect’s rate sheet publishes two structurally different products under one brand: a fixed rate that drops as loan size rises ($250k+ loans price nearly 1.5 points below sub-$25k loans) and a flat variable rate that ignores loan size entirely. That spread exists because small-ticket loans carry higher relative servicing cost per dollar lent — a pattern worth checking for on any equipment lender’s rate sheet, not just AgDirect’s.
AgDirect Rates vs. USDA FSA Rates: The Comparison Table
Producers searching for AgDirect financing are usually comparing it, whether they realize it or not, against USDA’s direct farm loan programs. The two are not identical products — AgDirect finances equipment at the dealer point of sale, while FSA direct loans are federal loans applied for through a local FSA office — but the rate comparison is the number most people actually want. FSA rates are set monthly; the table below carries the two most recent published sets alongside AgDirect’s current sheet.
| Loan Product | Rate | Period | Source |
|---|---|---|---|
| AgDirect equipment loan, fixed, $250k+, 2–7 yr | 6.50% | Sept 2026 | AgDirect |
| AgDirect equipment loan, fixed, $5k–$24k | 7.95% | Sept 2026 | AgDirect |
| AgDirect equipment loan, variable, any size | 5.99% | Sept 2026 | AgDirect |
| USDA FSA Farm Operating Loan (Direct) | 5.250% | August 2026 | USDA FSA |
| USDA FSA Farm Ownership Loan (Direct) | 6.000% | August 2026 | USDA FSA |
| USDA FSA Farm Operating Loan (Direct) | 4.750% | March 2026 | USDA FSA |
| USDA FSA Farm Ownership Loan (Direct) | 5.875% | March 2026 | USDA FSA |
| USDA FSA Farm Storage Facility Loan (3-yr term) | 3.625% | March 2026 | USDA FSA |
| USDA FSA Farm Ownership Loan (Direct), Texas | 5.750% | February 2026 | USDA FSA |
Two things stand out. First, FSA Farm Operating rates moved from 4.750% in March 2026 to 5.250% in August 2026 — a half-point rise in five months, which is the pace to expect from a federally set rate tied to Treasury borrowing costs, not a one-time jump. Second, AgDirect’s large-loan fixed rate (6.50%) sits above the August 2026 FSA Farm Ownership rate (6.000%) but below its small-loan fixed rate (7.95%), which means the “cheaper” option depends entirely on loan size and whether you qualify for FSA direct lending (which has eligibility limits FSA-financed commercial lenders don’t apply). Neither page is static: FSA republishes rates on the first business day of most months at fsa.usda.gov under “USDA announces [month] lending rates,” and AgDirect updates its sheet on the same rhythm.
Ag Equipment Financing: What Actually Drives the Cost
Rate is only one side of an equipment loan; the other is how much machinery actually costs to own per acre, which determines how much you need to finance in the first place. University of Illinois Farmdoc Daily tracks Midwest farm machinery-related expenses — depreciation, fuel, repairs, labor, and interest combined — as a per-acre figure drawn from Illinois farm business record data. That figure was $136 per acre in 2021 and rose to $171 per acre in 2024, a 26% increase over three years, according to Farmdoc Daily’s February 2026 analysis. That single number explains why equipment financing volume has grown even in years when new-equipment sales units were flat: the same fleet costs more to carry every year, whether or not a producer is trading up.
- Loan size band: AgDirect’s own sheet shows a nearly 150-basis-point spread between its smallest ($5k–$24k, 7.95% fixed) and largest ($250k+, 6.50% fixed) loan tiers — check where your equipment purchase actually falls before assuming the headline rate applies.
- Fixed vs. variable: At 5.99%, AgDirect’s variable rate is 51 basis points below its own $250k+ fixed rate and up to 196 basis points below its small-loan fixed rate (as of Sept 2026) — the tradeoff is payment certainty against future rate risk, not a free discount.
- Per-acre carrying cost: At $171/acre (2024, Farmdoc Daily), a 2,000-acre operation is carrying roughly $342,000 a year in machinery-related expense before financing a single new purchase — a baseline worth calculating for your own acreage before you evaluate any loan offer.
- Try it: Run your own numbers
AgDirect does not publish average loan size, default rates, or its share of the US farm equipment financing market, and none of the sources gathered for this article cover those figures. If you need them for underwriting or competitive analysis, the method is to request them directly through an AgDirect dealer relationship manager, or to check USDA’s Economic Research Service farm income and finance data, which tracks aggregate US farm debt by lender category.
Financing for Land in Texas and Other US Farm States
“Financing for land in Texas” is a distinct product from equipment financing — it’s typically a longer-term real estate loan, not a point-of-sale dealer loan, and the two shouldn’t be shopped against the same rate sheet. The clearest published reference point for Texas specifically is USDA FSA’s direct Farm Ownership Loan rate, which was set at 5.750% for Texas in February 2026, according to USDA’s February 2026 announcement. FSA sets Farm Ownership rates by state and territory because they’re tied to the government’s cost of borrowing for that jurisdiction’s loan portfolio, so a Texas-specific number will move independently of the national figure in the same announcement.
Beyond FSA direct lending, land purchases are also financed through Farm Credit System associations (which serve Texas through several regional associations), commercial agricultural banks, and seller-financed contracts. None of the sources in this article’s research base cover current commercial bank or Farm Credit land rates for Texas specifically — if that’s what you need, the durable method is: call your regional Farm Credit association directly, request their current real estate loan rate sheet, and compare it against the FSA direct rate above as your federal-program baseline. FSA direct loans also carry acreage, income, and “family farm” eligibility caps that commercial land loans don’t, so the lower headline rate isn’t automatically available to every applicant.
- FSA Farm Ownership (direct), national August 2026: 6.000% — the baseline to compare any state-specific or commercial land offer against.
- FSA Farm Ownership (direct), Texas, February 2026: 5.750% — check fsa.usda.gov monthly for the current state rate before applying, since FSA republishes these announcements roughly monthly and a rate quoted here can already be superseded.
- Farm Storage Facility Loan (3-yr), March 2026: 3.625% — relevant if the “land financing” need is actually on-farm grain storage infrastructure rather than raw acreage.
Equipment Financing Near Lexington and Other Farm Credit Territories
Searches for “equipment financing lexington” typically mean one of two things: financing through a dealer located near Lexington, Kentucky (or another Lexington — several US states have a farm town by that name), or financing through the regional Farm Credit association that services that territory. AgDirect operates through equipment dealers nationally, including in Kentucky and other Farm Credit territories that cover Lexington-area counties, but this article’s research base does not include a Lexington-specific rate sheet or dealer directory, because AgDirect does not publish rates by geography — its published rate sheet at agdirect.com/rates is a single national table by loan size and term, reproduced in the comparison table above.
The practical path for a Lexington-area producer: confirm which Farm Credit association holds AgDirect’s underwriting relationship for your county (this is published per-region on AgDirect’s own site, not in the rate table), then apply through a local participating equipment dealer, who quotes against the same national fixed/variable tiers shown above. There is no separate “Lexington rate” to find — the loan-size and fixed/variable tiers are what actually move your number, which is also why the calculator below is built around loan size and term rather than location.
Equipment Loan Payment Calculator
Run your own equipment loan amount, term, and down payment against AgDirect’s currently published rate tiers to see the estimated monthly payment before you talk to a dealer.
Run your own numbers
Assumptions: standard amortizing fixed or variable-rate loan, rates as published by AgDirect at agdirect.com/rates for September 2026 (see comparison table above), no fees, no balloon payment, no trade-in credit. Excludes dealer fees, sales tax, insurance requirements, and any promotional or dealer-subsidized rate. Variable-rate payments shown here will not reflect future rate changes. Confirm your actual quote with a participating dealer before purchase.
How Digital Underwriting Changes the Approval Process
Whether the lender is AgDirect, an FSA direct loan officer, or a Farm Credit association, the underwriting process across US ag lending has moved toward faster, data-supported approvals over paper-based collateral review. The features driving that shift are consistent across lenders:
- Mobile applications: loan submission and document upload from a phone, cutting the round-trips a paper application requires.
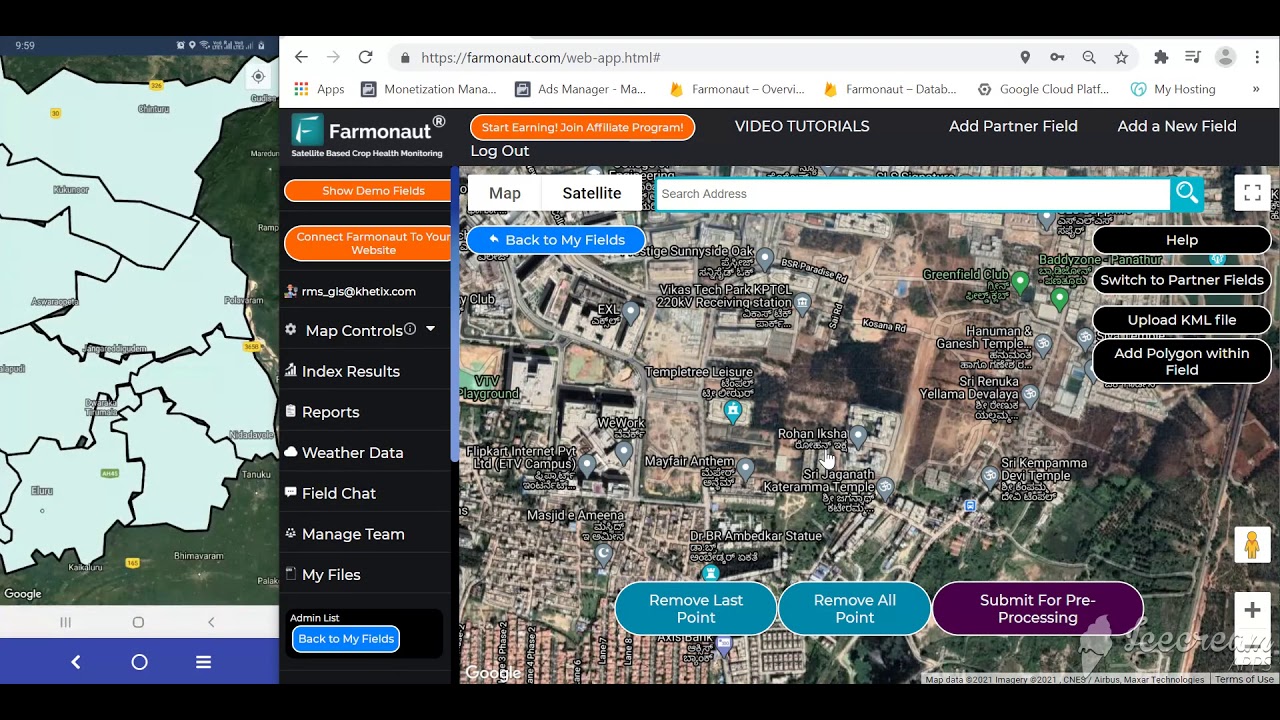
- Remote-sensing risk data: satellite crop-health and field-history data lets lenders assess collateral condition and production history without an in-person visit for every renewal.
- Open APIs: platforms such as Farmonaut’s satellite API let a lender’s own systems pull field-level data directly rather than requesting it from the borrower.
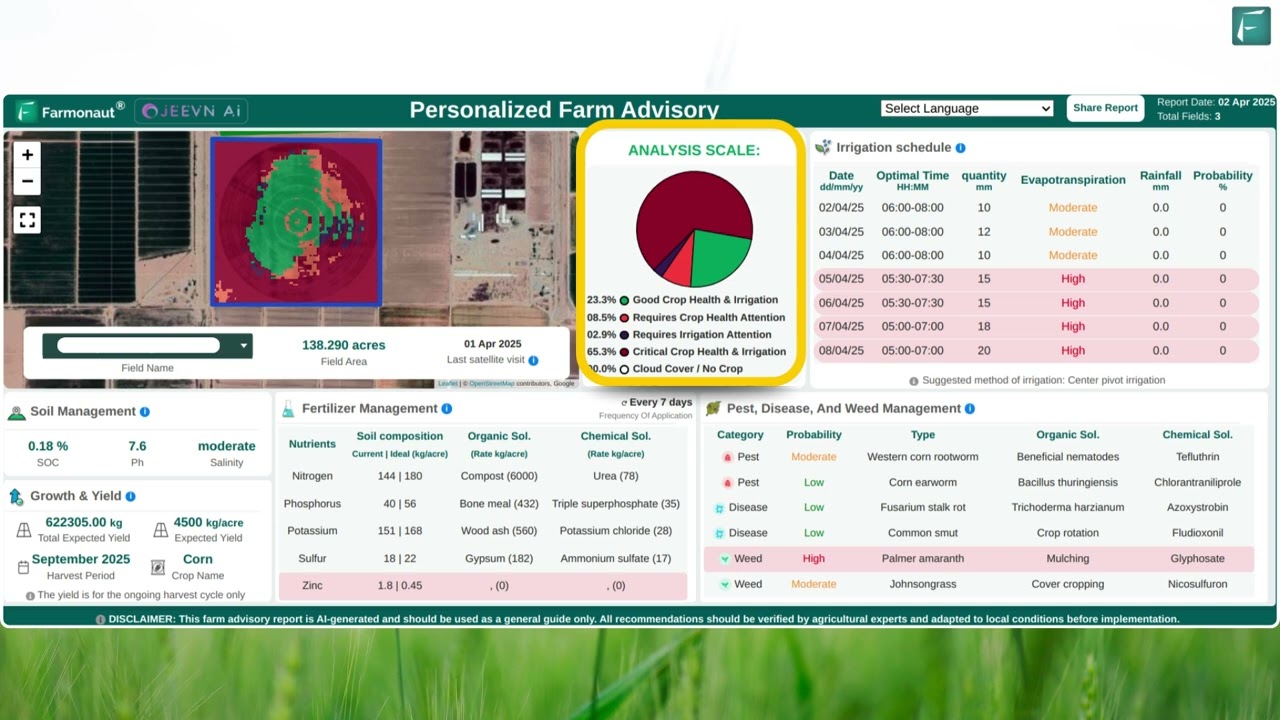
- Advisory tools tied to cash flow: apps like Jeevn AI connect weather and crop-health advisories to the same calendar a loan’s repayment schedule is built around.

None of this replaces the underlying credit decision — a faster application doesn’t change whether a $171-per-acre machinery cost load (2024, Farmdoc Daily) fits a given operation’s revenue. What it changes is how much friction sits between “I want to buy this equipment” and “I have an answer,” which is the actual pain point behind most equipment-financing searches.
A Durable Checklist: How to Compare Any Ag Loan Offer
Rates move monthly; this checklist doesn’t. Use it on any equipment or land financing offer, whether it’s AgDirect, FSA, or a Farm Credit association, regardless of what the headline rate happens to be when you read this.
- Check today’s rate at the source, not a cached figure. AgDirect republishes at agdirect.com/rates; FSA republishes monthly at fsa.usda.gov under “USDA announces [month] lending rates.”
- Identify which loan-size tier you fall into. AgDirect’s spread between its smallest and largest tiers is nearly 150 basis points (Sept 2026) — confirm your purchase amount against the current tier boundaries before comparing headline rates.
- Decide fixed vs. variable deliberately. A variable rate quoted lower today (5.99% vs. 6.50%–7.95% fixed, Sept 2026) carries rate risk over a multi-year term; FSA’s own rate moved 50 basis points in five months during 2026, which is the scale of shift to expect.
- Check eligibility, not just rate, for federal programs. FSA direct loans carry income, acreage, and “family farm” eligibility limits that AgDirect and commercial lenders don’t apply — a lower headline FSA rate is irrelevant if you don’t qualify.
- Calculate your real per-acre carrying cost. Farmdoc Daily’s $171/acre (2024) Midwest machinery-expense figure is a useful sanity check against your own operation’s numbers before adding new debt.
- Get the state-specific number for land loans. FSA Farm Ownership rates are set by state (Texas: 5.750% in February 2026) and diverge from the national figure — always check your own state’s current rate rather than the national headline.
Where Farmonaut Fits: Data for Loan and Insurance Verification
Farmonaut doesn’t originate or broker ag loans. Its role in this picture is the data layer lenders and borrowers use to support an application or a renewal:
- Satellite-based crop monitoring: field-level imagery that supports crop loan and insurance validation, giving both farmers and financiers a shared view of field condition.
- Fleet management: Farmonaut’s fleet management tools track equipment utilization and logistics — the same equipment a financing decision is being made about.
- Carbon and sustainability tracking: carbon footprinting tools document practices that some lenders factor into sustainability-linked loan terms.
- Supply chain traceability: blockchain-based product traceability for operations that need to demonstrate compliance to lenders or buyers.
- Large-scale farm management: the Agro Admin App gives cooperatives and larger operations remote, API-driven oversight across multiple fields.
- APIs for lenders and fintech platforms: the Farmonaut API and its developer documentation let financial institutions pull field data directly into their own underwriting systems.
Access is through web and mobile: the web app, Android app, and iOS app.





Frequently Asked Questions
What is AgDirect’s current equipment financing rate?
As of September 2026, AgDirect’s fixed rate ranges from 6.50% on loans of $250,000 or more (2–7 year terms) to 7.95% on small equipment loans of $5,000–$24,000, with a 5.99% variable rate available across all loan sizes. Check agdirect.com/rates for the current figure, since AgDirect updates this table directly and it moves over time.
How does AgDirect compare to a USDA FSA farm loan?
They’re different products. AgDirect is dealer point-of-sale equipment financing; FSA direct loans are federal loans with eligibility limits, applied for through a local FSA office. In August 2026, FSA’s direct Farm Ownership rate was 6.000% and its Farm Operating rate was 5.250%, per USDA’s August 2026 announcement — compare both the rate and your eligibility before choosing.
What’s the current rate for financing land in Texas?
USDA FSA’s direct Farm Ownership Loan rate for Texas was 5.750% in February 2026, according to USDA’s February 2026 announcement. FSA republishes state-specific Farm Ownership rates roughly monthly, so confirm the current figure before applying.
Is there a separate AgDirect rate for equipment financing near Lexington?
No — AgDirect’s published rate sheet is national, organized by loan size and term rather than by location. A Lexington-area producer applies through a local participating dealer and Farm Credit association, but is quoted against the same fixed and variable tiers shown in the comparison table above.
How much does farm equipment actually cost to carry per acre?
University of Illinois Farmdoc Daily put Midwest machinery-related expenses (depreciation, fuel, repairs, labor, and interest) at $171 per acre in 2024, up from $136 per acre in 2021 — a 26% rise over three years, per Farmdoc Daily’s February 2026 report.
How does Farmonaut support agricultural loan or insurance applications?
Farmonaut’s satellite monitoring and AI-powered advisory tools supply field-level data lenders and insurers use for loan eligibility and claims verification — through crop loan and insurance validation — accessible via web, Android, and iOS apps.



Conclusion
AgDirect’s Sept 2026 rate sheet (6.50%–7.95% fixed, 5.99% variable) and USDA FSA’s Aug 2026 direct loan rates (5.250% operating, 6.000% ownership) are two different products solving two different problems, and neither is fixed — both are republished on a roughly monthly cadence at their respective sources. Texas land financing has its own state-specific FSA number (5.750% in February 2026) that diverges from the national figure. What doesn’t change month to month is the method: confirm the current rate at the source, identify your loan-size tier, decide fixed versus variable deliberately, check your eligibility for federal programs before comparing headline rates, and size the decision against your own per-acre carrying cost. That checklist works whether you’re reading this in 2026 or two years from now, regardless of where the rates have moved by then.

 Godrej Agrovet
 Hayleys Agriculture
 Linx Agritech
 Adinet
 Save Your Soils
 GalaxEye Space
 Grandstream Algérie
 XOS Realty
 Geospatial Lab Africa
 Agro La Gándara
 HIPSAC
 ZOL Zimbabwe
 Juligerm
 AdBio
 MISE Maroc
 NWNS
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 DnCubed
 Indosistim Teknologi
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC
 AgroRisk
 Oath Inc
 Esri North East Africa
 MDCV UK
 Etech Consulting Madagascar
 Vestlandsforsking
 WB Dev
 Sama Premium
 Tres Valles
 Blickwinkel
 Agricultural Credit Policy Council
 eKGIS
 Mostas Tech
 Andex
 Deluxe Conseil
 WICO
 Chimera Innovation
 SkyHarvest
 Teledarbas
 Exurbia Geospatial
 FieldZero

