

Reviewed September 2026 against USDA NASS and USDA Farm Service Agency data.
Try it: Enter values above to estimate loan amount and payment. →
Ag land loans finance the purchase or refinance of farmland, and lenders price them off two things: the land’s classification (arable cropland vs. broader agricultural land) and current farm real estate values. US cropland averaged $5,830 per acre and pastureland $1,920 per acre in 2025, per USDA NASS — a gap that changes how much you can borrow and against what collateral. This guide covers loan rates, how arable and agricultural land differ for underwriting purposes, and what “large” land loans require in documentation.
- Arable Land vs Agricultural Land: The Actual Definitions
- US Farmland Values: Cropland, Pasture, and the National Average
- Ag Land Loans: How They’re Underwritten
- Agricultural Loan Interest Rates: Current FSA Figures
- Large Land Loans for Ag: What Changes at Scale
- Land Loans in Rockwall and Similar Texas Counties
- Loan Sizing Calculator
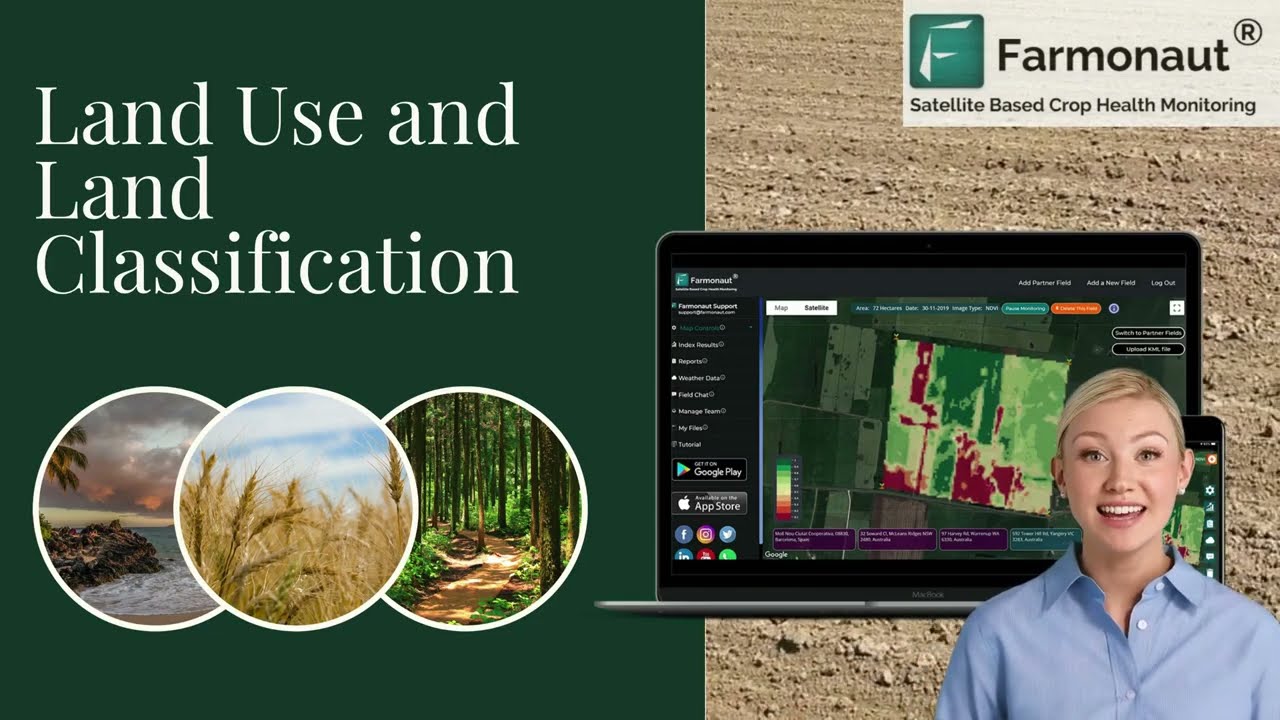
- Satellite Verification: Speeding Up Land Classification Checks
- Soil and Water Monitoring for Loan-Backed Land
- Practical Steps Before You Apply
- FAQ: Ag Land Loans and Land Classification
- Conclusion



Arable Land vs Agricultural Land: The Actual Definitions
These two terms get used interchangeably in casual conversation, but lenders, appraisers, and government statisticians treat them differently — and that difference affects loan underwriting.
Arable land is land suited to growing crops that are replanted each season: corn, wheat, soybeans, cotton, and similar row crops. It excludes land under permanent crops (orchards, vineyards) and permanent pasture. The World Bank tracks this globally: arable land made up 16.57% of total US land area in 2023, per World Bank Development Indicators.
Agricultural land is the umbrella term. It includes arable land plus orchards, vineyards, permanent pasture, and rangeland — anything in active farm use, cropped or not. USDA’s Census of Agriculture reported 880.1 million acres of total land in farms across the United States in 2022, a figure that includes cropland, pasture, woodland, and farmstead acreage combined.
Within that total, USDA’s Economic Research Service put US cropland used for crops and other temporary uses at 328 million acres in 2024. Not all of that acreage is harvested in a given year — USDA ERS data on land use put the share of cropland actually cultivated and harvested at 87% as of 2017, with the remainder in fallow, failed plantings, or idle rotation.
US Farmland Values: Cropland, Pasture, and the National Average
Land value is the single biggest input into any ag land loan — it sets both the purchase price and the collateral base a lender will lend against. USDA NASS publishes farm real estate values annually, typically in August, covering the prior 12 months.
| Land Type | Value per Acre (2025) | Value per Acre (2024) | Change |
|---|---|---|---|
| Average farm real estate (all uses combined) | $4,350 | Not broken out separately in the brief above | +4.3% year-over-year |
| Cropland (arable, irrigated + rainfed combined) | $5,830 | $5,570 | +4.7% |
| Pastureland (agricultural, non-arable) | $1,920 | Not broken out separately in the brief above | — |
Source for all three rows: USDA NASS, 2025 Land Values Summary and the 2024 Land Values Summary. The gap between cropland and pastureland — $3,910 per acre in 2025 — is the arable-vs-agricultural distinction expressed in dollars: arable ground commands roughly three times the per-acre value of pasture because it can carry an annual cash crop instead of only grazing.
Refresh path: USDA NASS releases the next annual Land Values report in August. Search “Land Values” at nass.usda.gov and filter to the current year for updated per-acre figures by state and region.

Ag Land Loans: How They’re Underwritten
An ag land loan (also called a farmland loan or farm real estate loan) is secured by the land itself, similar to a mortgage. Underwriting differs from residential lending in three ways specific to farmland:
- Land use classification. Lenders and USDA Farm Service Agency (FSA) programs distinguish arable cropland from pasture, timber, or non-productive acreage. Arable cropland with a documented cropping history usually appraises higher and supports a larger loan-to-value ratio because it produces a predictable annual cash flow.
- Farm Service Agency loan programs. FSA offers direct and guaranteed Farm Ownership Loans (for purchasing land) and Farm Operating Loans (for annual inputs, equipment, and operating costs). Both carry government-set rates that reset monthly.
- Documentation. Lenders typically require recorded land classification from county or state records, a current appraisal, and — increasingly — satellite or geospatial verification of actual land use versus what’s on the deed. Farmonaut’s Crop Loan & Insurance Platform is built for this: it cross-checks claimed cropland against multi-season satellite imagery so a lender isn’t relying only on paper records.
A loan-to-value ratio or approval-rate breakdown specific to farm size isn’t published by USDA in the sources gathered for this article — if you need that figure for underwriting, ask your FSA county office or lender directly, since terms vary by program and by lender risk appetite.

Agricultural Loan Interest Rates: Current FSA Figures
USDA’s Farm Service Agency sets direct-loan interest rates monthly, and the agency announces them in a public notice near the start of each month. These are the only nationally standardized reference point for agricultural loan interest rates in the US — private lender rates float on top of their own cost of funds and are not centrally published.
| Loan Program | Rate | Effective Period |
|---|---|---|
| Farm Operating Loan (direct) | 4.625% | January 2026 |
| Farm Operating Loan (direct) | 5.125% | February 2025 |
| Farm Ownership Loan (direct) | 5.500% | February 2025 |
Source: USDA Farm Service Agency, January 2026 lending rates announcement and the February 2025 lending rates announcement. Between February 2025 and January 2026, the direct Farm Operating Loan rate moved from 5.125% down to 4.625% — a 0.5 percentage point drop over roughly eleven months.
Refresh path: FSA re-announces rates monthly, usually between the 1st and 3rd. Go to fsa.usda.gov, then News > Announcements, and search “lending rates” for the current month’s figures, or call your local FSA county office — they carry the current rate sheet and can quote it over the phone.
Note on “agricultural loans interest rate” as a search: if you’re comparing a private bank or Farm Credit System loan against FSA’s direct rate, ask the lender for their current quote directly — FSA’s published rate only applies to FSA direct loans, not to loans made by commercial ag lenders, even when those lenders reference FSA guaranteed-loan programs.
Large Land Loans for Ag: What Changes at Scale
A large land loan for ag purposes — financing several hundred to several thousand acres — differs from a small parcel purchase in documentation depth, not in the underlying rate structure. FSA direct loan limits are capped per borrower, so operations buying beyond that threshold typically combine an FSA guaranteed loan (where FSA guarantees a portion of a loan made by a commercial lender) with private ag lending, or work entirely through a Farm Credit System association or commercial ag bank.
At scale, three things matter more than they do on a small purchase:
- Rented vs. owned acreage mix. USDA NASS reported 348 million acres of US farmland rented out by non-operator landowners in 2024. If part of a large acquisition is leased ground with existing tenants, lenders will want the lease terms and payment history, not just the deed.
- Multi-parcel classification consistency. A large tract often mixes arable cropland, pasture, and non-productive acreage (waterways, easements, farmstead). Each portion is valued and financed differently — cropland at the higher per-acre collateral value, pasture and other agricultural land at the lower rate shown in the values table above.
- Verification cost. Manually surveying land use across a large multi-parcel purchase is slow and expensive. Satellite-based verification tools can confirm actual cropping history across thousands of acres from historical imagery instead of requiring a field visit to every parcel — see the satellite verification section below.
There’s no published USDA figure on typical loan-to-value ratios for large ag land purchases in the sources gathered here — that number is set lender-by-lender and depends on the borrower’s balance sheet, so get it in writing from your specific lender before you budget around an assumed percentage.
Land Loans in Rockwall and Similar Texas Counties
Rockwall County, Texas sits in a fast-urbanizing corridor northeast of Dallas, where remaining agricultural parcels compete directly with residential and commercial development pressure. That dynamic changes how land loans work locally in a few concrete ways:
- Land value is driven by development potential, not just crop yield. In counties like Rockwall, appraisers and lenders weigh the parcel’s proximity to growth corridors alongside its farm income potential — a factor the national cropland/pasture averages above don’t capture, because those are national, not county-level, figures.
- Ag exemption status matters for taxes, not for loan eligibility directly. Texas agricultural (open-space) valuation reduces property tax burden on land actively used for agriculture, which affects a borrower’s carrying cost and therefore their debt service capacity — but it’s a state/county tax program, separate from FSA lending eligibility.
- Local lenders know the zoning trajectory. A Farm Credit association or community bank operating in the Dallas-Fort Worth exurbs will price a land loan against both current ag use and the parcel’s realistic path to rezoning, since that affects resale value if the loan is ever foreclosed.
No county-level land value or loan-approval figures for Rockwall County are in the research brief for this article — those aren’t tracked at the same granularity as national USDA data. For a current per-acre estimate in Rockwall or any specific Texas county, contact a local FSA office, a Texas AgriLife Extension county agent, or a regional Farm Credit association — they maintain county-level comparables that don’t appear in national USDA releases.
Loan Sizing Calculator
Estimate a rough loan amount and monthly payment using current land values and FSA’s published direct-loan rate as your starting reference point — adjust for your own lender’s actual quote.
Enter values above to estimate loan amount and payment.
Assumptions: fixed-rate, fully amortizing loan; per-acre values are 2025 USDA NASS national averages, not county-specific; excludes closing costs, taxes, insurance, and any FSA guarantee fees. Use your lender’s actual quoted rate and your county’s actual per-acre value for a real application.

Satellite Verification: Speeding Up Land Classification Checks
Lenders increasingly ask for independent confirmation that a parcel’s claimed use matches its actual, on-the-ground cropping history — especially on large or multi-parcel purchases where a physical inspection of every acre isn’t practical. Satellite imagery analyzed across multiple growing seasons can show whether a field has actually carried a row crop annually (arable use) or has sat in pasture or fallow.
Farmonaut’s Crop Loan & Insurance Platform is built for exactly this: multi-season NDVI history that a lender or appraiser can use to corroborate a parcel’s classification before closing. For operations managing verification across many parcels or large acreage — including tracts that mix arable and non-arable ground — the Large Scale Farm Management platform aggregates plot-level data into a single dashboard.
Developers building loan-origination or appraisal tools that need this data programmatically can pull imagery and vegetation-index data directly from the Farmonaut API, with implementation details in the Developer Docs.

Soil and Water Monitoring for Loan-Backed Land
Whether financed acreage is arable cropland or broader agricultural land, ongoing soil and water condition affects both productivity and the land’s long-term collateral value — a factor increasingly relevant to lenders doing multi-year risk assessment on large ag loans.
- Soil testing to track organic matter and nutrient depletion over the loan term
- Irrigation efficiency monitoring on irrigated cropland, which commands a premium over rainfed cropland in USDA’s combined $5,830/acre 2025 figure
- Carbon and sustainability tracking, increasingly tied to conservation-linked lending programs
Farmonaut’s Carbon Footprinting Product Page covers satellite-based carbon and soil health tracking relevant to both arable fields and diversified agricultural land under a loan.

For operations managing logistics across large financed acreage, Farmonaut’s Fleet Management Tools coordinate vehicles and machinery across multiple fields, and the Traceability Product supports buyers who need documented production history — useful when a lender or future buyer wants a produce paper trail tied to specific financed parcels.
Practical Steps Before You Apply
- Confirm classification. Check county land records for the parcel’s current designation — arable cropland, pasture, or mixed agricultural use.
- Pull current land values. Use USDA NASS’s most recent Land Values report (August release) for your state and land type, not a national average, if your lender allows state-level figures.
- Check the current FSA rate. Call your local FSA office or check fsa.usda.gov for this month’s direct-loan rates before comparing private lender quotes.
- Get multiple quotes. FSA direct loans, FSA guaranteed loans through a commercial lender, and Farm Credit System loans carry different rates and terms — compare all three if the acreage and your balance sheet qualify.
- Independently verify land use history on any parcel where the deed’s classification and the land’s visible condition don’t obviously match, especially on larger multi-parcel purchases.
FAQ: Ag Land Loans and Land Classification
1. What is the difference between arable land and agricultural land?
Arable land is land suited to annual, replanted crops like corn, wheat, or soybeans. Agricultural land is the broader category — it includes arable land plus pasture, rangeland, orchards, and other farm-use acreage. Arable land was 16.57% of total US land area in 2023, per the World Bank; total US land in farms (the agricultural land figure) was 880.1 million acres in the 2022 Census of Agriculture.
2. What is the current interest rate on an agricultural land loan?
USDA FSA’s direct Farm Operating Loan rate was 4.625% as of January 2026, down from 5.125% in February 2025. The direct Farm Ownership Loan rate was 5.500% in February 2025. These are FSA direct-loan rates only; private and Farm Credit System lenders set their own rates, which you should request directly since they’re not centrally published. Check fsa.usda.gov’s News > Announcements section for the current month’s rate.
3. How much does an acre of farmland cost in the US?
US cropland averaged $5,830 per acre in 2025, up from $5,570 in 2024 — a 4.7% increase, per USDA NASS. Pastureland averaged $1,920 per acre in 2025. The overall average farm real estate value (all land uses combined) was $4,350 per acre in 2025, up 4.3% year-over-year. These are national averages; state and county values vary and are published in the same USDA NASS report by region.
4. Do large land loans for ag purposes work differently than smaller loans?
The rate structure is the same, but large purchases typically combine FSA guaranteed loans with commercial or Farm Credit System financing once acreage exceeds FSA direct-loan limits. Large tracts also often mix land classifications — cropland, pasture, rented ground — each valued and financed at a different per-acre rate, so a single blended assumption across the whole tract will misstate the collateral value.
5. Can I get an agricultural loan if my land is classified as pasture rather than arable cropland?
Yes. Pastureland and other non-arable agricultural land qualify for FSA and commercial ag financing, just typically at the lower per-acre collateral value shown in USDA’s Land Values report ($1,920/acre for pasture in 2025 vs. $5,830/acre for cropland). Loan terms depend on the lender and program, not on arable status alone.
6. How is farmland rented out treated in a loan application?
USDA NASS reported 348 million acres of US farmland rented out by non-operator landowners in 2024. If you’re purchasing land with an existing tenant and lease, lenders will typically want the lease terms and rent payment history as part of underwriting, since that income stream affects debt service capacity on the loan.




Conclusion
Ag land loans are priced off two things that are both publicly documented and refreshed on a fixed schedule: USDA NASS’s annual land values (cropland $5,830/acre, pastureland $1,920/acre, both 2025) and USDA FSA’s monthly direct-loan rates (4.625% for Farm Operating Loans as of January 2026). Arable land — the cropland subset of the broader agricultural land category — commands roughly three times the per-acre collateral value of pasture, which is why lenders ask about classification before they quote a rate.
The durable method here doesn’t expire when these numbers do: check the parcel’s recorded classification, pull the current NASS values for your state, get this month’s FSA rate from your local office, and verify actual land use against multiple growing seasons of imagery before you rely on the deed alone. Do that regardless of what the rate or the per-acre value happens to be next year.
- ✔ Confirm classification before you assume a loan rate or land value applies to your parcel.
- ✔ Use the current month’s FSA rate, not a figure from a prior announcement.
- ✔ On large or multi-parcel purchases, value each land type separately rather than blending them.
- ✔ Consider Farmonaut’s solutions for satellite-based verification of land use history before closing.

 Godrej Agrovet
 Hayleys Agriculture
 Linx Agritech
 Adinet
 Save Your Soils
 GalaxEye Space
 Grandstream Algérie
 XOS Realty
 Geospatial Lab Africa
 Agro La Gándara
 HIPSAC
 ZOL Zimbabwe
 Juligerm
 AdBio
 MISE Maroc
 NWNS
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 DnCubed
 Indosistim Teknologi
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC
 AgroRisk
 Oath Inc
 Esri North East Africa
 MDCV UK
 Etech Consulting Madagascar
 Vestlandsforsking
 WB Dev
 Sama Premium
 Tres Valles
 Blickwinkel
 Agricultural Credit Policy Council
 eKGIS
 Mostas Tech
 Andex
 Deluxe Conseil
 WICO
 Chimera Innovation
 SkyHarvest
 Teledarbas
 Exurbia Geospatial
 FieldZero

