

Reviewed August 2026 against USDA Farm Service Agency, Moody’s Analytics, and InsightAce Analytics data.
Try it: Enter values above to calculate. →
Agriculture digital banking is the delivery of farm credit, insurance, and payments through mobile apps, satellite-verified risk data, and online lending portals instead of a branch visit. In the United States, the USDA Farm Service Agency backed a record $3.4 billion in direct and guaranteed loans to beginning farmers in FY 2025, much of it processed through digital application and monitoring tools. In Australia, banks carried $131 billion in agribusiness lending in 2023-24, growing 6% the prior year as digital risk tools reshaped how that credit gets underwritten. This article covers what digital lending for farmers actually looks like in the US and Australia, what banking in the agriculture sector costs and delivers, and how satellite verification from platforms like Farmonaut fits into loan and insurance decisions.
Table of Contents
- Agriculture Digital Banking: What It Is and Why It’s Growing
- Digital Lending for Farmers in the United States
- Digital Banking in Australia’s Agriculture Sector
- Core Technologies Behind Agri Banking
- Agricultural Banking Institutions: How Loan and Insurance Processing Changed
- Banking Solutions for Farmers: Closing the Adoption Gap
- Sustainability and Productivity Effects
- Farmonaut: Satellite Verification for Agri Banking
- Market Size Comparison Table
- Calculator: Estimate Your Digital Ag Loan Cost
- FAQ: Agriculture Digital Banking
- Conclusion and How to Track These Numbers Yourself



Agriculture Digital Banking: What It Is and Why It’s Growing
Agriculture digital banking is agri banking delivered through mobile apps, online lending platforms, and data feeds rather than in-person branch processes. It covers farm credit, crop insurance, input payments, and subsidy or program disbursement, and it increasingly draws on satellite imagery and weather data to price risk. The category is not niche: the global digital agriculture market, which includes these financial-services layers, was sized at $24.10 billion in 2025 and is projected by InsightAce Analytics to reach $64.58 billion by 2035 at a 10.4% compound annual growth rate (InsightAce Analytics).
Within that global figure, the US market alone was valued at $8.7 billion in 2024, with Statifacts projecting growth to $22.08 billion by 2034 at a 9.76% CAGR (Statifacts). That gap between the US number and the global total is the clearest signal of where the rest of the growth sits: other developed ag-banking markets, led by Australia, the EU, and Canada, are scaling from a smaller base and catching up fast.
This is banking in the agriculture sector adapting to three pressures at once: farm operating costs that reward faster access to cash, insurers that need objective loss data instead of a farm visit weeks after a weather event, and lenders that want a risk signal that updates continuously instead of once a year at loan renewal. Satellite crop monitoring, IoT soil sensors, and blockchain traceability are the specific tools filling that gap, covered section by section below.

Digital Lending for Farmers in the United States
The USDA Farm Service Agency (FSA) is the largest single channel for digital lending for farmers in the US. Its direct and guaranteed loan programs, which farmers now apply for and track through online portals, delivered a record $3.4 billion to beginning farmers in FY 2025 (USDA Farm Service Agency). For comparison, combined FSA direct and guaranteed farm ownership and operating loans across all borrower categories totaled $7.5 billion in FY 2021 — the beginning-farmer FY 2025 figure alone now represents nearly half of that entire 2021 total, in one borrower segment.
These figures move every fiscal year as FSA closes its books, so treat both numbers as a snapshot rather than a ceiling. The FSA publishes updated volumes in its farm loan programs report; check the USDA Farm Service Agency page directly for the current fiscal year’s totals before citing a figure from this article as current.
What “digital” means in this context is concrete: online eligibility pre-screening, e-signature loan closings, and — increasingly — satellite-based crop condition data submitted alongside a loan or insurance application instead of a physical inspection. For farmers evaluating banking solutions for farmers beyond FSA’s own programs, most major US agricultural lenders (Farm Credit System institutions, regional ag banks) now offer comparable online origination, though loan-level volume by private lender is not broken out in the sources gathered for this article — that data would need to come directly from each lender’s disclosures or from a Farm Credit Administration filing.
Digital Banking in Australia’s Agriculture Sector
Digital banking Australia agriculture data centers on lending volume rather than app adoption counts. Total lending to Australian agribusiness reached $131 billion in 2023-24, according to Moody’s Analytics, with the sector’s lending book growing 6% in 2022-23 per ABARES-sourced figures cited in the same analysis (Moody’s Analytics).
ABARES (the Australian Bureau of Agricultural and Resource Economics and Sciences) publishes farm lending and finance data quarterly through agriculture.gov.au/abares, with each release carrying fresh GDP, employment, and lending figures for the sector. Because that data updates on a quarterly cycle, a reader checking “banking for agriculture” conditions in Australia today should pull the latest ABARES snapshot rather than rely solely on the 2023-24 figure above — the method is to go to ABARES’ published release calendar and take the most recent quarter’s lending table.
The Moody’s analysis frames five specific trends reshaping how Australian banks underwrite agribusiness debt, including climate-risk-adjusted pricing and data-driven collateral assessment — both of which lean on the same satellite and IoT inputs covered in the technology section below. Australian agricultural banking is consolidating around fewer, larger relationship-lending banks that increasingly require digital farm records as a condition of the largest loan tiers.

Core Technologies Behind Agri Banking
Agricultural banking platforms in the US and Australia are built on five recurring technology layers. Each one changes a specific step in how a loan or insurance policy gets priced and paid out.
- Mobile banking and digital wallets: Real-time, cashless payment for input purchases and marketplace settlements, replacing check- and cash-based supply chain payments.
- AI-driven credit scoring: Models that combine yield history, weather records, and satellite imagery to price credit risk, instead of relying only on prior-year tax returns and collateral appraisals.
- Biometric authentication: Fingerprint or facial recognition on mobile banking apps, reducing fraud on remote-farm account access.
- IoT-enabled data collection: Soil moisture and equipment sensors feeding granular, farm-level data into insurance underwriting.
- Satellite monitoring: Platforms like Farmonaut provide NDVI crop health, soil condition, and carbon monitoring data that supports dynamic insurance premiums and ongoing loan-collateral monitoring.
- Try it: Enter values above to calculate.
Blockchain traceability is the sixth layer, used less for credit pricing and more for compliance: it records the farm-to-market chain of custody that export-oriented lenders and buyers now ask for as a condition of trade finance (see Farmonaut’s traceability solution).

Agricultural Banking Institutions: How Loan and Insurance Processing Changed
Agricultural banking institutions — from the USDA Farm Service Agency in the US to Farm Credit System lenders and Australia’s agribusiness-focused banks — have restructured around three digital processes:
- Faster loan decisioning: Digital documentation and pre-screening cut the time between application and disbursement, a factor behind the FSA’s ability to process a record $3.4 billion in beginning-farmer loans in FY 2025 without a matching increase in staff.
- Satellite-verified insurance claims: Crop condition and loss verification via satellite imagery lets insurers assess damage after a weather event without waiting for a field adjuster, shortening claim cycles (see how Farmonaut’s crop loan and insurance verification works).
- Continuous collateral monitoring: Rather than a single loan-origination inspection, lenders now track crop health data through the season, adjusting risk flags in real time.
This shift is also visible in Australia’s $131 billion agribusiness lending book: Moody’s notes banks are moving toward continuous, data-backed risk monitoring rather than annual review cycles, a direct consequence of the same satellite and IoT inputs used in US crop insurance.

Banking Solutions for Farmers: Closing the Adoption Gap
Digital literacy and platform design remain the binding constraint on adoption, not technology availability. Specific figures on mobile banking app adoption rates among US and Australian farmers were not available in the sources gathered for this article — this is a genuine data gap. The method to get a current figure: USDA’s State of the Farm Report, republished annually via AGDAILY, surveys US farmer technology and payment preferences each growing season, and is the right source to check for an adoption percentage rather than a market-size estimate.
In the absence of a published adoption rate, three design factors determine whether a bank’s digital tools actually get used on-farm:
- Simplified onboarding: Loan and insurance applications that pre-fill from existing farm records reduce the paperwork barrier that keeps older or larger operations on paper-based processes.
- Segment-specific products: Row-crop, livestock, and horticulture operations have different cash-flow cycles; a single generic loan product underperforms tailored terms for each.
- Feedback channels: Lenders that maintain a direct support line alongside the digital app see fewer farmers reverting to a branch visit for issues the app should resolve.

Sustainability and Productivity Effects
Digital banking in the agriculture sector is increasingly tied to sustainability incentives: lenders offering preferential rates for verified adoption of practices like cover cropping or reduced tillage, priced against satellite-tracked carbon and soil data rather than self-reported claims.
- Verified practice adoption: Carbon footprint tracking tools let lenders confirm — rather than take on faith — that a borrower adopted the practice tied to a preferential rate (Farmonaut’s carbon footprinting tool).
- Continuous productivity monitoring: Season-long crop monitoring supports both lender risk models and on-farm input decisions (explore large-scale farm management tools).
- Faster disaster response: Quicker insurance payouts following weather events, backed by satellite loss verification, reduce the cash-flow shock that follows a bad season.
Farmonaut: Satellite Verification for Agri Banking
Farmonaut provides the satellite data layer that agricultural lenders and insurers increasingly require as part of a digital loan or claim.
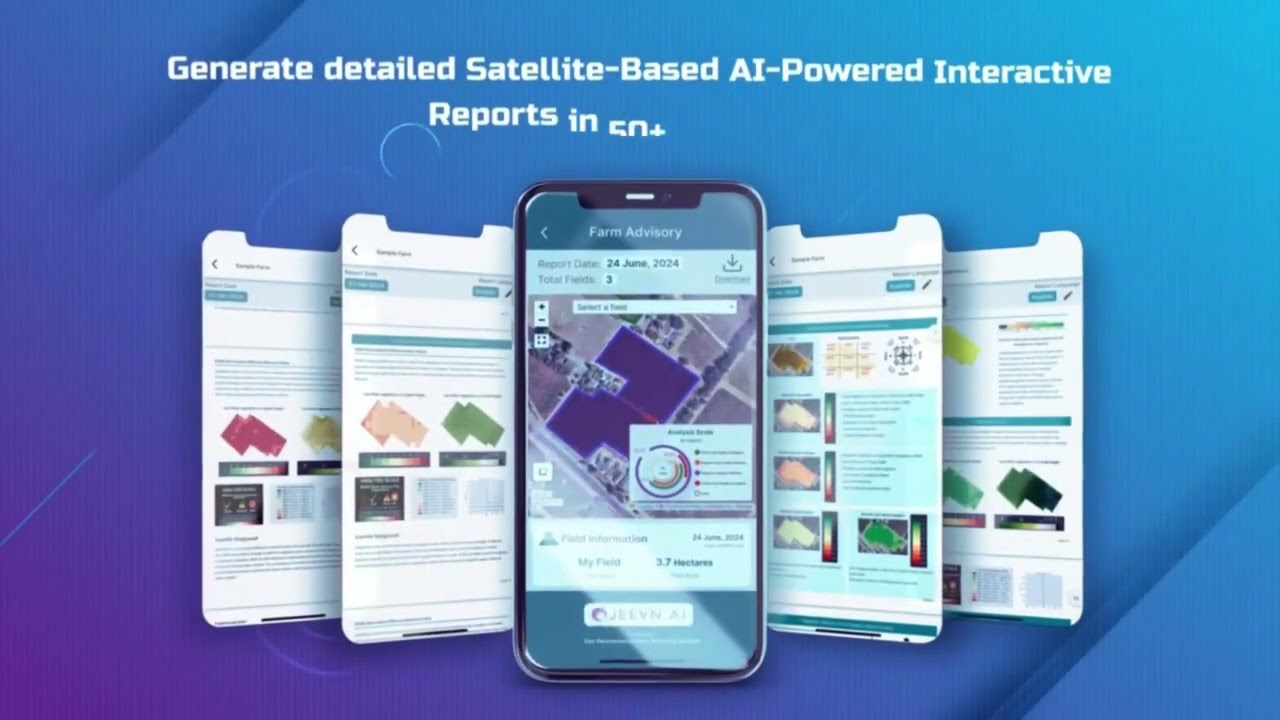
- Satellite-based crop monitoring: Multispectral imagery and NDVI analytics track crop health and soil conditions, giving lenders an independent data feed for collateral risk.
- JEEVN AI advisory: Real-time satellite and weather data drive location-specific input recommendations, supporting the productivity side of a loan’s risk profile (access the crop, plantation, and forest advisory).
- Blockchain traceability: Farm-to-market chain-of-custody records support trade-finance and export-compliance requirements (product traceability details).
- API integration: Lenders and agri-fintech platforms can integrate satellite verification directly via the Farmonaut API and developer documentation, automating collateral checks that once required a site visit.
Want to see how satellite data connects to a real loan or insurance workflow?
Market Size Comparison Table
| Market | Current Size | Projected Size | CAGR | Source |
|---|---|---|---|---|
| Global digital agriculture | $24.10B (2025) | $64.58B (2035) | 10.4% | InsightAce Analytics |
| US digital agriculture | $8.7B (2024) | $22.08B (2034) | 9.76% | Statifacts |
| US FSA beginning-farmer loans | $3.4B (FY 2025, record) | Not published | — | USDA Farm Service Agency |
| Australian agribusiness lending | $131B (2023-24) | Not published | 6% (2022-23 growth) | Moody’s Analytics / ABARES |
Each figure carries its own vintage. Market-size projections (InsightAce, Statifacts) republish annually in a February–March cycle; search “digital agriculture market” plus the current year for the newest projection. USDA FSA volumes close at fiscal year-end (September 30) and post shortly after. ABARES lending data refreshes quarterly.
Calculator: Estimate Your Digital Ag Loan Cost
Enter your own loan amount, rate, and term to see estimated annual payments and total interest — figures the article above will not do for you.
Enter values above to calculate.
Assumes a standard amortizing loan with equal annual payments and a one-time origination fee applied at closing. Excludes insurance premiums, servicing fees, prepayment penalties, and any government loan-guarantee fee. This is an estimate for comparison purposes, not a lending offer.
Farmonaut Subscription Plans: Satellite Data for Agri Finance
FAQ: Agriculture Digital Banking
1. What is agriculture digital banking?
Agriculture digital banking is farm credit, insurance, and payment services delivered through mobile apps and online platforms instead of branch visits. In the US, this includes the USDA Farm Service Agency’s online loan applications and satellite-verified crop insurance; in Australia, it includes the digital risk tools banks use across the $131 billion agribusiness lending book reported for 2023-24 (Moody’s Analytics).
2. How large is the digital lending market for farmers?
The global digital agriculture market, which includes lending and financial services, was $24.10 billion in 2025 and is projected to reach $64.58 billion by 2035 (InsightAce Analytics). The US portion alone was $8.7 billion in 2024, projected to $22.08 billion by 2034 (Statifacts).
3. How much does the USDA lend to farmers through digital channels?
The USDA Farm Service Agency backed a record $3.4 billion in direct and guaranteed loans to beginning farmers in FY 2025. Combined direct and guaranteed farm ownership and operating loans across all borrowers totaled $7.5 billion in FY 2021. Check the USDA Farm Service Agency report for the current fiscal year’s total.
4. What does banking in the agriculture sector look like in Australia?
Australian banks held $131 billion in agribusiness lending in 2023-24, with the lending book growing 6% in 2022-23 (Moody’s Analytics). ABARES publishes updated quarterly lending figures at agriculture.gov.au/abares.
5. How does AI-based credit scoring differ from traditional farm lending?
AI-based scoring combines satellite imagery, weather records, and transaction history to assess risk continuously, rather than relying solely on annual tax returns and collateral appraisals reviewed at loan renewal.
6. What role does satellite verification play in crop insurance claims?
Satellite imagery lets insurers assess crop loss after a weather event without a field visit, shortening claim timelines (see how Farmonaut’s crop loan and insurance verification works).
7. Are there mobile apps for managing agricultural finance and monitoring?
Yes. Farmonaut offers Android (download), iOS (download), and Web (access here) apps for crop monitoring and finance-related tracking.
8. Where can developers access APIs for satellite data in agri-finance?
Developers can use the Farmonaut API and the developer documentation to integrate satellite verification into lending or insurance platforms.
9. Is there published data on farmer adoption of mobile banking apps?
Not at the specificity of an adoption percentage in the sources reviewed for this article. USDA’s State of the Farm Report, republished annually via AGDAILY, is the right source to check for US farmer technology and payment-preference survey data.



Conclusion and How to Track These Numbers Yourself
Agriculture digital banking in the US and Australia is not a projected trend — it is measurable lending activity today: $3.4 billion in FY 2025 US beginning-farmer loans, $131 billion in 2023-24 Australian agribusiness lending, and a global digital agriculture market on a 10.4% CAGR path to $64.58 billion by 2035. What ties these together is satellite and IoT-verified risk data replacing manual inspection at every step — loan origination, ongoing collateral monitoring, and insurance claims.
To keep these figures current: check the USDA Farm Service Agency report after each fiscal year-end (September 30) for US lending volumes, the ABARES quarterly release for Australian agribusiness lending trends, and search “digital agriculture market” with the current year each February–March for updated global and US market-size projections from InsightAce Analytics and Statifacts. For lenders and platforms building on satellite-verified risk data, the Farmonaut API and developer documentation are the direct integration points.

 FarmSetu
 Progenseed
 SkyHarvest
 Polaris Digitech
 Teledarbas
 Wild Oak Farm
 SFX
 BACF Africa
 Doodlakine
 Exurbia Geospatial
 FieldZero
 Indico Company
 Kubota
 FFBS

