

Hay markets · US prices and margins
US Alfalfa Market: Prices, Acreage and Break-Even Math
Farmers received $208 per ton for alfalfa hay in September 2026, up from $172 a year earlier (USDA NASS), while 2026 output is forecast just 1% higher at 50.6 million tons. Prices by state and grade, production, exports, costs and a break-even calculator.
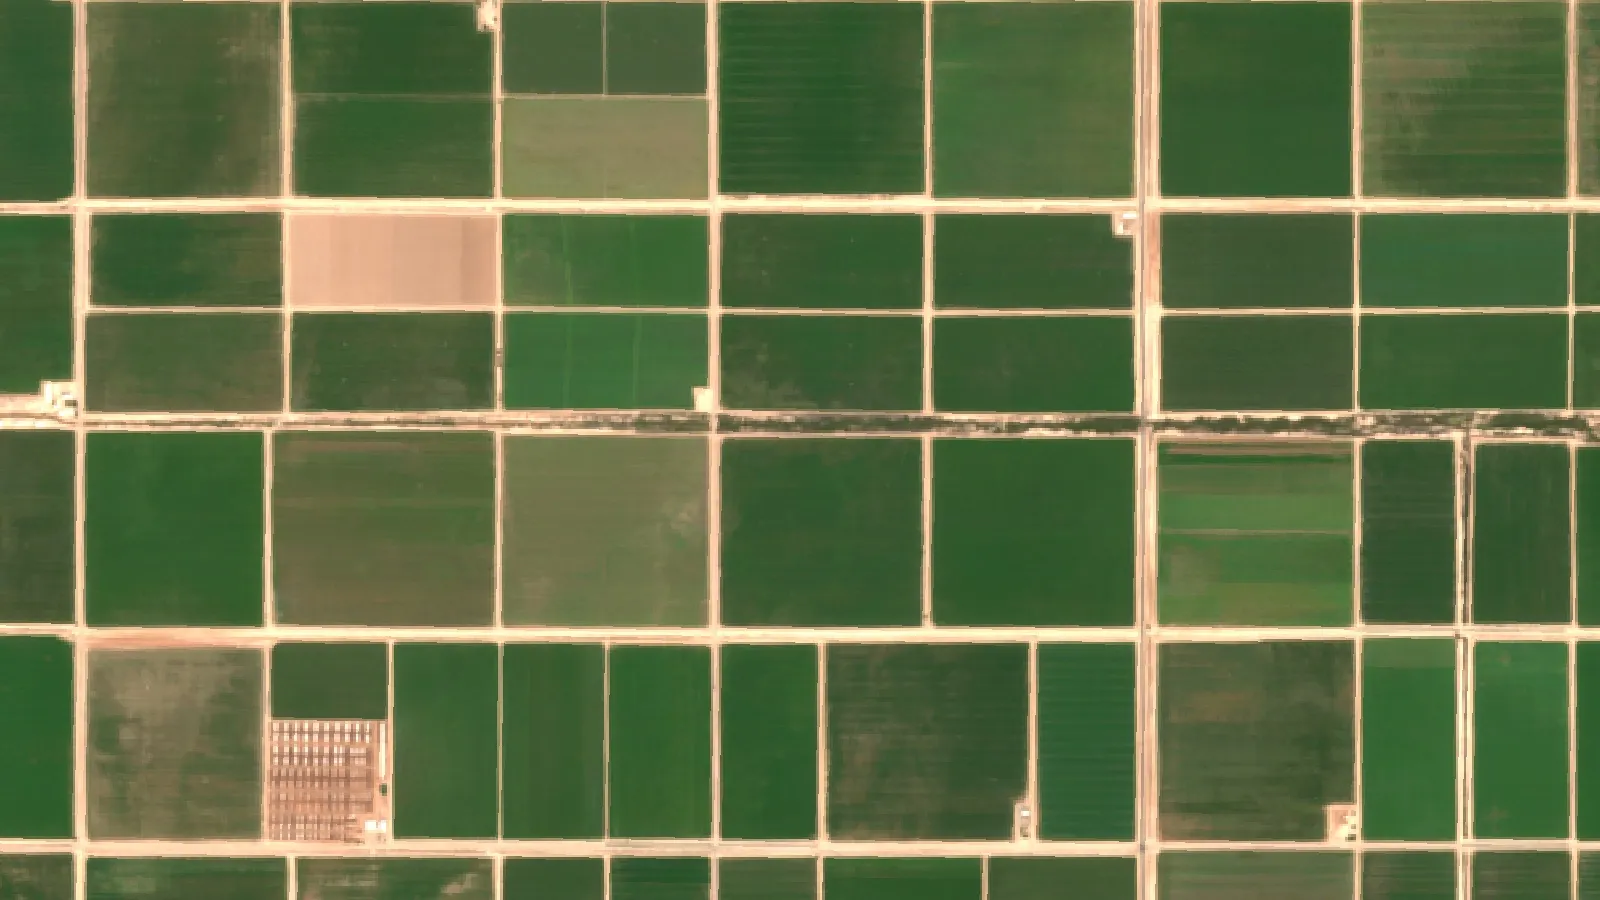
Key takeaways
- The US average alfalfa hay price received was $208 per ton in September 2026, up from $172 in September 2025 (USDA NASS Agricultural Prices, October 2026).
- NASS forecasts 2026 alfalfa hay production at 50.6 million tons on 14.7 million harvested acres, up 1% from 2025 (Crop Production, October 2026).
- State prices ranged from $275 per ton in New Mexico to $96 in North Dakota in September 2026; dairy-quality hay in the five top milk states averaged $241.
- AFBF put the average full cost of production at about $229 per ton and estimated 2025 grower losses at about $2.9 billion, or $203 per acre.
- China bought 560,000 metric tons of US alfalfa in January to September 2025, down from 1.28 million tons in the same months of 2022 (AFBF).
In this article
- US alfalfa market at a glance
- Alfalfa hay prices now
- Prices by state and by grade
- Acreage, yield and production
- Where US alfalfa is grown
- Why margins are thin: costs and water
- Alfalfa break-even and water cost calculator
- Exports and the China factor
- The alfalfa derivatives market
- Risk tools and safety nets
- Technology for alfalfa farms
- Challenges and sustainability
- Where the US alfalfa market may go next
- How we checked the numbers
The US alfalfa market in late 2026 is a story of firmer prices on a flat supply base. Farmers received an average of $208 per ton for alfalfa hay in September 2026, up from $172 a year earlier, according to the USDA NASS Agricultural Prices report for October 2026. Supply barely moved: USDA’s October crop forecast puts 2026 alfalfa hay output at 50.6 million tons on 14.7 million harvested acres, up 1% from 2025. Costs are still high, so the margin question has not gone away.
This guide brings together the latest official prices, acreage and production by state, the export picture, and what it costs to grow a ton of hay. It ends with a break-even calculator you can fill in with your own yield, price, cost and water numbers. Every figure has a date and a named source, so you can check for newer reports when you read this.
US alfalfa market at a glance
The table below sums up the main numbers. Prices are the monthly average prices received by farmers, as reported by USDA’s National Agricultural Statistics Service (NASS). They are not auction results or dealer asking prices.
| Measure | Latest figure | Period and source |
|---|---|---|
| Alfalfa hay price received, US average | $208 per ton | September 2026, NASS |
| Same month a year earlier | $172 per ton | September 2025, NASS |
| Season-average price | $170 per ton | 2025 marketing year, NASS Crop Values |
| Value of production | $7.63 billion | 2025, NASS Crop Values |
| Harvested area | 14.68 million acres | 2025 final, NASS |
| Yield | 3.42 tons per acre | 2025 final, NASS |
| Production | 50.2 million tons | 2025 final, NASS |
| Production forecast | 50.6 million tons | 2026, NASS forecast of 1 October 2026 |
| Average full cost of production | About $229 per ton | University budgets compiled by AFBF, 2025 |
| Estimated grower losses | About $2.9 billion ($203 per acre) | 2025, AFBF estimate |
Two points stand out. First, the September 2026 national price of $208 is still below the $229 average full cost that the American Farm Bureau Federation (AFBF) worked out for 2025, although several states now sell above it. Second, supply is steady, so most of the price change comes from demand, hay quality and regional weather rather than a big swing in national output.
Alfalfa hay prices now
National alfalfa prices fell hard after the drought years. AFBF notes that the national average fell from about $288 per ton in April 2023 to $164 per ton in November 2024, a 43% decline. Prices stayed low through 2025. The NASS Agricultural Prices report for January 2026 shows $164 per ton in December 2024, $159 in November 2025 and $161 in December 2025.
The turn came in 2026. The NASS report for September 2026 shows $203 per ton in July 2026 and $206 in August 2026. The October report then shows $208 in September 2026. That is about 21% above September 2025. The season-average price for the 2025 crop was $170 per ton, according to the NASS Crop Values 2025 Summary, down from $175 for 2024 and $225 for 2023.
These are average prices across all grades and all buyers. The price on your farm depends on quality, bale type, trucking distance and whether you sell to a dairy, a feedlot, a horse owner or an exporter.
Chart
US alfalfa hay price received by farmers
US$ per ton, monthly average for selected months, all grades
Prices by state and by grade
State prices vary much more than the national average. In September 2026, NASS reported alfalfa prices of $275 per ton in New Mexico, $270 in Pennsylvania and $230 in California, but $106 in Nebraska, $102 in South Dakota and $96 in North Dakota. Much of that gap likely reflects quality and freight. Western and Eastern dairy states buy more high-test hay, while the northern Plains sell more hay into beef cow herds.
Chart
Alfalfa hay price by state: Sep 2025 vs Sep 2026
US$ per ton, price received by farmers, selected states
Several Western states saw large gains over the year. Montana rose from $145 to $230 per ton between September 2025 and September 2026, Wyoming from $160 to $240, and Colorado from $170 to $245. California, a large dairy and export state, was flat at $230.
NASS also tracks premium and supreme alfalfa sold to dairies. For the five largest milk-producing states, the weighted average was $241 per ton in September 2026, up from $221 a year earlier. Pennsylvania ($355) and New York ($330) had the highest dairy-quality prices that month.
Grades follow feed tests. In its Kansas direct hay report for the week ending 23 October 2026, USDA’s Agricultural Marketing Service (AMS) lists the guidelines it uses: supreme hay has a relative feed value (RFV) above 185, premium 170 to 185, and good 150 to 170. A move of one grade can change the price by tens of dollars per ton, so cutting at the right stage and baling at the right moisture matter as much as the market itself. For moisture targets at baling, see our guide to baling alfalfa at the right moisture.
For weekly prices in one region, AMS publishes direct hay reports for many states, broken out by grade. Our California alfalfa hay price tracker follows the California reports.
Acreage, yield and production
US alfalfa acreage has been shrinking for decades. AFBF writes that from 2000 to 2025 harvested acres fell by nearly 40%, from about 23 million to about 14 million. The final NASS numbers for 2025 show 14.68 million acres harvested for alfalfa and alfalfa mixtures, up slightly from 14.61 million in 2024 but well below 15.60 million in 2023.
Yield has been steady. The NASS Crop Production 2025 Summary shows 3.19 tons per acre in 2023, 3.41 in 2024 and 3.42 in 2025. Production was 49.8 million tons in both 2023 and 2024 and 50.2 million tons in 2025.
The October 2026 Crop Production report forecasts 2026 production at 50.6 million tons, up 1% from 2025, with yield at 3.44 tons per acre. NASS forecasts record yields in Iowa, Utah and Wisconsin. Harvested area is forecast at 14.7 million acres, little changed from 2025.
Why does acreage stay low when prices rise? Alfalfa is a perennial. AFBF explains that stands are usually cut for five to seven years or longer, and a new stand can take one to two years to reach full output. So growers cannot add supply quickly when prices rise, and they often keep cutting old stands when prices fall. Rain-fed fields in the Midwest and upper Plains usually give three to four cuttings a year, while irrigated fields in parts of the West and Southwest can give seven or more.
Alfalfa also earns its place in a rotation. It fixes nitrogen, breaks pest cycles for the next crop and improves soil structure. For the agronomy, see our crop rotation and soil science guide.
Where US alfalfa is grown
Alfalfa is grown in almost every state, but output is concentrated where dairy and cattle herds are large. In 2025, South Dakota and Idaho each produced about 3.6 million tons, followed by Nebraska, California, Montana and Iowa, according to the NASS 2025 summary.
Chart
Top alfalfa hay producing states
Thousand tons of alfalfa and alfalfa mixture hay, 2025
Yields differ a lot by region. Irrigated desert ground in Arizona averaged 7.4 tons per acre in 2025 and California 6.8 tons. Montana averaged 2.2 tons and South Dakota 2.4 tons, but on far more acres. That is why a state can rank high on production with modest yields.
The split matters for prices too. Western irrigated hay is often sold on test to dairies and exporters. Northern Plains hay is more often fed on the farm or sold locally to cow-calf herds, where the price per ton is lower.
Why margins are thin: costs and water
Costs moved up while prices fell. AFBF says that university cost studies across the Plains and Western states show full costs from $165 to more than $300 per ton, depending on irrigation, yield and region. Input costs such as water, fertilizer, labor, fuel and machinery have risen 20% to 35% since 2020, according to the same analysis.
Chart
Value of US alfalfa hay production
US$ billion per year, NASS value of production
Using budgets from the Universities of California, Arizona, Nevada and Idaho and from Iowa State and Oklahoma State, AFBF put the average full cost at about $229 per ton. That figure includes operating costs, cash overhead, and the yearly cost of land, equipment and stand establishment. Against a 2025 price near $171 per ton, AFBF estimated a $2.9 billion shortfall in 2025, or about $203 per acre. This is an estimate based on budgets, not a survey of actual farm accounts.
Water is the biggest swing cost on irrigated farms. University of Nevada, Reno Extension says that irrigated alfalfa uses about 4 to 5 inches of water for every ton of hay produced. Use can be only 0.5 to 1 inch per week in late April, rising to as much as 2 inches per week in the hottest part of the season. The same bulletin cites a North Dakota study in which yield rose by 1/6 to 1/5 ton per acre for each added inch of water, up to a limit.
So a field yielding 6 tons per acre may need roughly 24 to 30 inches of water from irrigation, rain and soil storage. If the water costs you money per acre-inch, that bill can decide whether the crop pays.
Alfalfa break-even and water cost calculator
Use the calculator to test your own numbers against the national averages. Enter your cost per acre without water, then your water use and water cost. The tool shows your margin per acre and the price you need to break even.
The default values are examples set near break-even. They are not a benchmark. Replace each one with your own figures, and use today’s local price rather than the national average. For loans, leases or tax questions, get advice from a farm business adviser.
Try the numbers for your own farm below.
Calculator
Alfalfa break-even and water cost per acre
Enter your own yield, price, costs and water use.
- Revenue per acre: 832 US$
- Water needed: 18.0 inches
- Water cost per acre: 180 US$
- Break-even price: 208 US$/ton
Example values only, set near break-even; they are not a benchmark or forecast. The cost field should exclude water. The 4 to 5 inches of water per ton guide comes from University of Nevada, Reno Extension; use local guidance if your area differs. Program payments, insurance and taxes are not included.
Exports and the China factor
Exports matter most in the West. AFBF notes that roughly 31% of West Coast alfalfa and other hay production is exported, compared with about 3% of total US hay output. That makes Western prices more sensitive to overseas demand than prices in the Midwest.
China has been the largest foreign buyer by volume since 2012. In 2022, China bought about 1.66 million metric tons, 57% of total US alfalfa hay exports, according to AFBF. Purchases then fell. In January to September, China imported 1.28 million metric tons in 2022, 718,000 tons in 2024 and 560,000 tons in 2025, the lowest level since 2020. AFBF links the drop to trade tensions, inspection issues and changes in China’s dairy sector.
Other buyers have moved up and down. Japan, South Korea, Saudi Arabia, the United Arab Emirates and Taiwan have long bought US alfalfa, especially dairy-quality hay. AFBF reports that shipments to Saudi Arabia rose about 42% in 2023 to about 431,000 metric tons, then softened in 2024 and 2025. Japan’s purchases fell in 2023 and stayed low, partly because of the strong dollar.
For a Western grower, the practical point is simple. When export demand drops, more hay stays at home and competes for the same dairy and feedlot buyers. Prices in export regions can fall faster than the national average.
The alfalfa derivatives market
Beyond baled hay, alfalfa is processed into meal, pellets, cubes, extracts and powder. These go into animal feed, dietary supplements, pharmaceutical products and cosmetics. Market-research firm Verified Market Research values the global alfalfa derivatives market at $2.82 billion in 2025 and forecasts $4.56 billion by 2033, a 6.2% yearly growth rate. It describes animal feed as a large outlet, with supplements, pharmaceuticals and cosmetics growing.
Treat these figures with care. They are a private forecast, not official statistics, and they cover a global market rather than US farm sales. For most US growers, the main link is through pellet and cube plants that buy hay locally, often at prices tied to the hay market.
Buyers of supplement or export-grade product may ask for proof of origin and input records. Keeping field-level records of cuttings, inputs and test results makes those sales easier.
Risk tools and safety nets
Alfalfa has few of the support programs that corn, soybeans and wheat have. AFBF points out that alfalfa has never been a covered commodity under the farm bill’s Price Loss Coverage (PLC) and Agriculture Risk Coverage (ARC) programs. AFBF also writes that alfalfa is not eligible for the $11 billion Farmer Bridge Assistance Program.
Some crop insurance exists, but cover is uneven. In certain states, growers can buy yield-based policies for alfalfa hay or seed. The tool most forage growers use is the Pasture, Rangeland and Forage (PRF) rainfall index program, which pays when rainfall in a chosen grid falls below its long-term average. Rules and availability change by state and year, so check current terms with your crop insurance agent or the USDA Risk Management Agency before you rely on any policy.
Without a price safety net, growers lean on other tools: forward contracts with dairies or exporters, storage to sell later in the season, and steady quality so hay sells on test rather than at commodity prices.
Technology for alfalfa farms
Precision tools help on the cost side. Satellite crop monitoring tracks plant vigor (NDVI) across each field between cuttings and can show dry or weak patches before they are easy to see from the road. Soil moisture sensors and variable-rate irrigation help growers apply water against the 4 to 5 inch per ton guide instead of a fixed schedule. Drones add close-up detail on problem spots.
Farmonaut Satellite + AI Farm Monitoring System gives growers satellite vegetation and soil moisture maps for their own fields on web and mobile. Developers can pull the same data through an API.
Larger farms with fields spread over many miles also use equipment scheduling and fleet tracking, so mowers, rakes and balers move between fields with less idle time during short drying windows.
▶ How NDVI maps from satellites show crop stress before it is easy to see in the field. · 4:09
Challenges and sustainability
Water supply is the biggest long-term risk in the dry West. AFBF notes that cuts to surface-water deliveries and tighter groundwater rules in California and Arizona led some growers to fallow alfalfa in 2021 and 2022. Drought also lowers both yield and quality. AFBF cites the US Drought Monitor: by early 2023, there had been 119 straight weeks with at least 40% of the lower 48 states in drought.
Other pressures include high input costs, state rules on water and nutrient use, and the need for skilled staff to run newer irrigation and monitoring systems. Practices that help include deficit irrigation late in the season where local rules allow it, keeping stands healthy so they last longer, integrated pest management, and soil testing before applying phosphorus or potassium. Check product labels and local rules before using any pesticide or fertilizer.
Alfalfa also has benefits that buyers increasingly value. It is a perennial cover that protects soil from erosion, and it fixes its own nitrogen. Farms that record these benefits may find it easier to meet buyer and lender reporting requests.
▶ Six plain steps to start precision farming without buying a robot. · 4:18
Where the US alfalfa market may go next
Three things will shape prices over the coming year. The first is supply. NASS expects 2026 production to be only about 1% higher than 2025, so there is no sign of a large surplus. The second is dairy demand, which sets the price of top-grade hay. The third is exports, especially to China and the Middle East, which move Western prices.
Weather remains the wild card. A dry year in the West can lift prices quickly, as it did in 2021 and 2022. A wet year with good quality hay across the Plains can pull them down. Because stands last for years, growers have limited room to change acreage, so cost control and hay quality are the main levers.
When you read this, check the newest NASS Agricultural Prices report and your state’s AMS hay report. Prices can change by tens of dollars per ton within a few months.
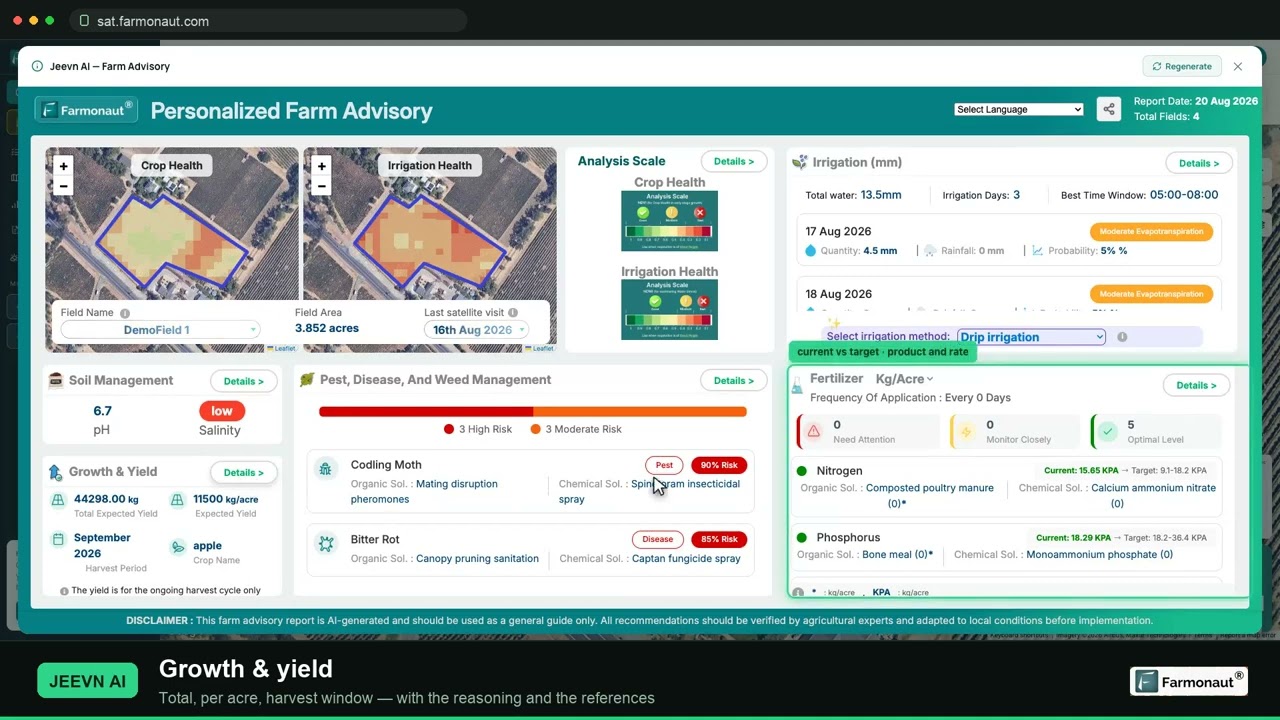
▶ A full walkthrough of satellite crop monitoring: reading NDVI and pulling a field report. · 19:36
How we checked the numbers
Prices come from NASS Agricultural Prices reports (January, September and October 2026) and the NASS Crop Values 2025 Summary. Acreage, yield and production come from the NASS Crop Production 2025 Summary and the October 2026 Crop Production report. Grade guidelines come from the AMS Kansas direct hay report. Cost, loss, export and program figures come from AFBF Market Intel, which draws on university budgets and USDA data. Water use comes from University of Nevada, Reno Extension. The derivatives forecast comes from Verified Market Research and is labelled as a private forecast.
Related pages on our site: web app for field maps · large-scale farm management · crop traceability · carbon footprint records · satellite data for crop loans and insurance · farm fleet tracking · satellite and weather API · API developer docs
FAQ
What is the current state of the US alfalfa market?
Prices have recovered while supply is flat. NASS reported an average alfalfa hay price of $208 per ton in September 2026, up from $172 a year earlier. Production is forecast at 50.6 million tons for 2026, about 1% above 2025. Harvested area is about 14.7 million acres, down from about 23 million in 2000.
Are alfalfa farms profitable?
It depends on the farm. AFBF estimated an average full cost of about $229 per ton and a 2025 industry loss of about $2.9 billion, or $203 per acre. With 2026 prices higher, farms with good yields, low water costs or premium dairy sales may cover their costs. Use the calculator on this page with your own numbers.
Which states produce the most alfalfa hay?
In 2025, South Dakota and Idaho each produced about 3.6 million tons, followed by Nebraska, California, Montana and Iowa, according to the NASS Crop Production 2025 Summary.
How much water does alfalfa need?
University of Nevada, Reno Extension says irrigated alfalfa uses about 4 to 5 inches of water per ton of hay. Peak use can reach 2 inches per week in the hottest weeks. Multiply your expected tons per acre by that range to estimate total water need.
Why did China’s alfalfa imports fall?
AFBF links the fall to trade tensions, inspection issues and changes in China’s dairy sector. China imported 1.28 million metric tons of US alfalfa in January to September 2022 and 560,000 tons in the same months of 2025.
Where can I find alfalfa prices for my state?
Use the monthly NASS Agricultural Prices report for state averages and the weekly USDA AMS direct hay reports for prices by grade and region. NASS Quick Stats has acreage and yield by state.
Farmonaut crop monitoring
Watch every alfalfa field between cuttings
Draw your fields once and Farmonaut shows satellite vegetation and soil moisture maps for them through the season, on web, Android or iOS.




Keep reading
Sources
- USDA NASS, Agricultural Prices (October 2026): release.nass.usda.gov
- USDA NASS, Agricultural Prices (September 2026): release.nass.usda.gov
- USDA NASS, Agricultural Prices (January 2026): release.nass.usda.gov
- USDA NASS, Crop Production (October 2026): release.nass.usda.gov
- USDA NASS, Crop Production 2025 Summary (January 2026): release.nass.usda.gov
- USDA NASS, Crop Values 2025 Summary (February 2026): release.nass.usda.gov
- USDA AMS, Kansas Direct Hay Report, week ending 23 October 2026: ams.usda.gov
- American Farm Bureau Federation, Market Intel: Alfalfa in the Red: Rising Costs, Falling Returns: fb.org
- University of Nevada, Reno Extension, How Much Water Does Alfalfa Need?: extension.unr.edu
- Verified Market Research, Alfalfa Derivatives Market report: verifiedmarketresearch.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 SFX
 BACF Africa
 Nivia
 Doodlakine
 Exurbia Geospatial
 FieldZero
 Indico Company
 Kubota
 FFBS
 Jontra
 Tucor
 Hayleys Agriculture

 Licence holder · Niger · Gold
 Licence holder · Nigeria · Gold + lithium
 Client · Tanzania · Gold
 Client · Somalia · Gold
 Client & affiliate partner · Ghana · Gold










