

De Beers · Market analysis
De Beers Lab-Grown Diamonds: Market Share, Prices, Sale
De Beers announced in May 2025 that it would close Lightbox, its lab-grown brand, after wholesale prices fell 90%. Its realised price fell 32% to US$105 per carat in the first half of 2026 while Anglo American sells the business.
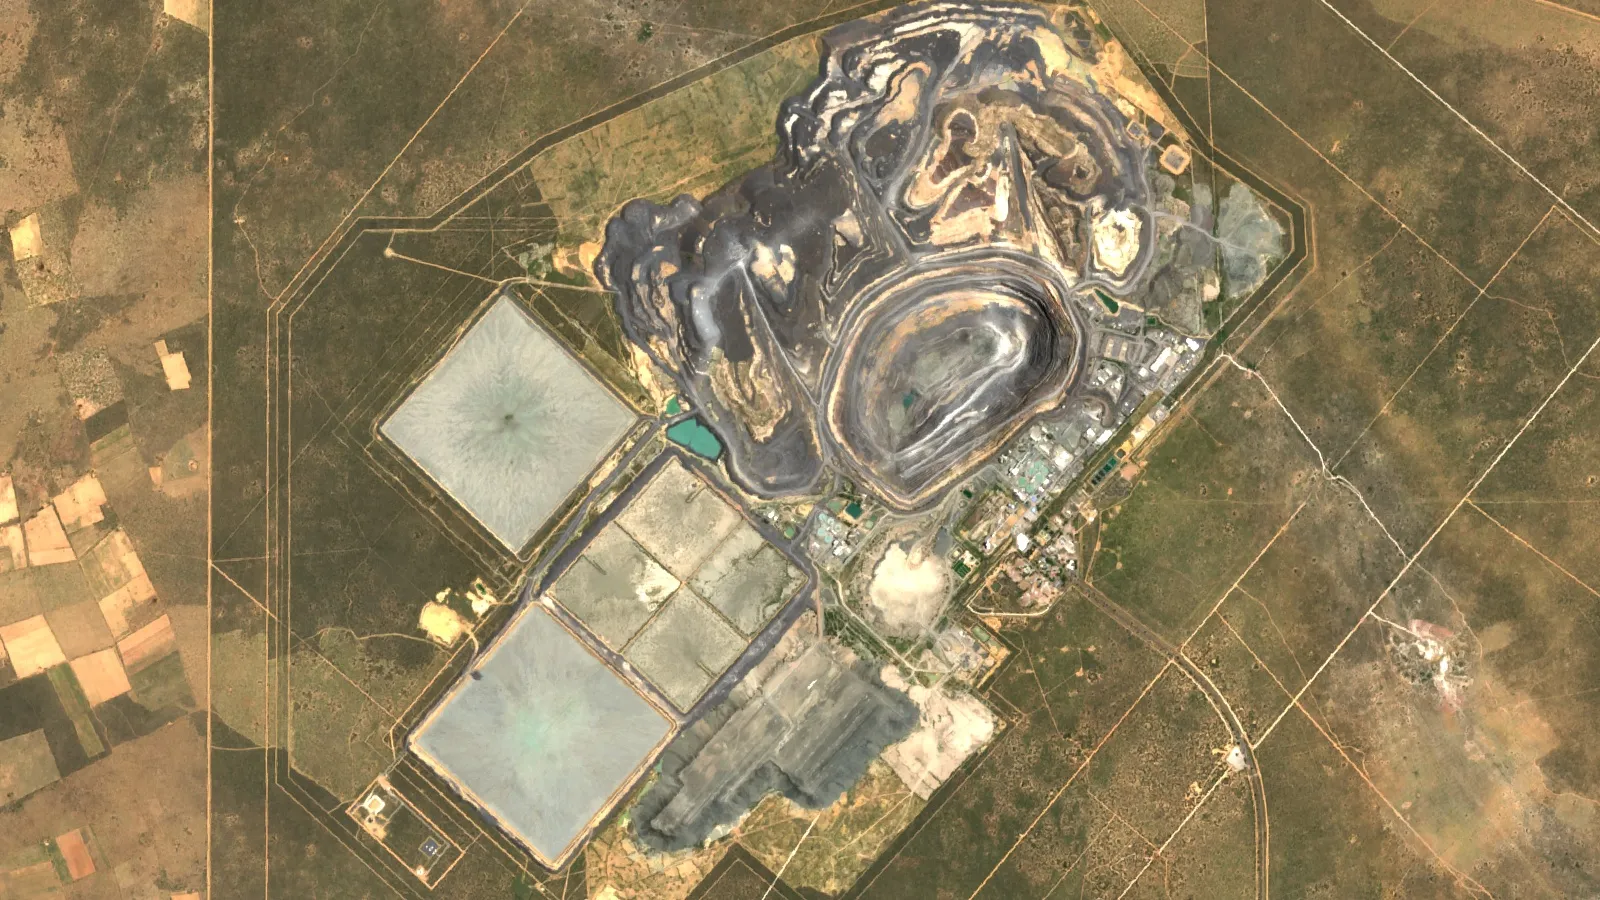
Key takeaways
- De Beers said on 8 May 2025 that lab-grown jewellery prices had fallen 90% at wholesale since Lightbox launched at US$800 per carat (De Beers, 2025).
- De Beers produced 21.7 million carats in 2025 on a 100% basis for joint ventures, and USGS estimates 69 million carats of gem-quality natural diamond worldwide (2025 estimate).
- Its average realised price fell 32% to US$105 per carat in the first half of 2026, and the underlying EBITDA loss was US$113 million (De Beers, July 2026).
- Lab-grown stones were 15% of diamond sales by value at US independent jewellers in 2025, against 85% for natural (De Beers data, 950 retailers).
- Anglo American is selling its 85% stake; Bloomberg reported on 15 October 2026, per Miningmx, that Richemont and Signet in advanced talks to join the leading bidder (via Miningmx).
In this article
- What De Beers did with lab-grown diamonds
- How much of the diamond market is lab-grown
- De Beers market share and output by country
- How De Beers prices and profit have moved
- Who is buying De Beers
- How the diamond industry is adapting to lab-grown growth
- Natural versus lab-grown diamonds compared
- Canada and Alberta: where new natural supply could come from
- What to check in a diamond producer's report
- Frequently asked questions
De Beers is leaving lab-grown jewellery. On 8 May 2025 the company announced that it would close Lightbox, its lab-grown brand, because wholesale prices for lab-grown jewellery stones had fallen 90% since the brand launched at US$800 per carat (De Beers Group, 8 May 2025). The stones still shape its numbers: De Beers says smaller, lower-quality natural diamonds are under price pressure from synthetics, its average realised price fell 32% to US$105 per carat in the first half of 2026, and its owner, Anglo American, is now selling the business (De Beers interim results, 30 July 2026). This page sets out what De Beers did about synthetic stones, how big its share of the market is, what the figures show, and how the industry is adapting. It is written for mining consultants, investors and licence owners, and it gives facts from filings, not forecasts.
What De Beers did with lab-grown diamonds
Lightbox was set up in 2018 as a separate lab-grown jewellery brand with a flat price per carat. De Beers says it helped to show that a factory-made stone is a different product from a mined one, with a different value. The plan did not hold against the market. Lab-grown prices fell, in De Beers’ words, towards a cost-plus model, and the company expects both cost and price to fall further as more low-cost production comes on stream in China and US supermarkets push jewellery prices down (De Beers Group, 8 May 2025).
The group’s synthetic arm, Element Six, did not close. It makes synthetic diamond for industry and technology, and De Beers said it would concentrate chemical vapour deposition (CVD) growth at its site in Oregon, United States. CVD grows a diamond from a carbon-rich gas on a small seed crystal. The other common method, high pressure and high temperature (HPHT), squeezes carbon around a seed until it crystallises (National Geographic).
So the answer to “does De Beers sell lab-grown diamonds” is now: not as jewellery. Its message to shoppers is that natural and lab-grown stones are two categories. Its category marketing, including the “Desert diamonds” campaign for coloured natural stones, promotes natural diamonds (De Beers, 30 July 2026).
How much of the diamond market is lab-grown
There is no single global share, because sources measure different things: carats, dollars, rings or all jewellery. The one dated figure from a producer is for the United States. De Beers’ point-of-sale data from 950 independent US jewellers show lab-grown stones at 15% of diamond sales by value in 2025 against 85% for natural, even though lab-grown unit sales are rising. The gap exists because lab-grown retail prices keep falling. The same data show a drop in lab-grown sales above 3 carats (De Beers, 11 June 2026). Treat this as one producer’s view of one channel: independent jewellers are not the whole market, and De Beers sells natural stones.
Chart
US laboratory-created gemstone production
Value of US output, US$ million
A second look comes from official US statistics. The US Geological Survey (USGS) records the value of laboratory-created gemstones made in the United States, which fell from US$87.1 million in 2022 to an estimated US$37 million in 2025. USGS names one leading US synthetic diamond company in Oregon that stopped operating in July 2025 as a major reason for the 35% fall in 2025 (USGS Mineral Commodity Summaries 2026, gemstones). It measures US output only; De Beers points to growing low-cost production in China.
Natural diamonds have been through a weak spell. USGS describes a downturn in the natural diamond market that began in early 2023 and hit stones of one carat or less hardest, driven by weaker luxury demand, extra inventory and the growing popularity of cheaper synthetic stones (USGS, 2026).
De Beers market share and output by country
De Beers produced 21.7 million carats in 2025 on a 100% basis, meaning joint ventures are counted in full (Gahcho Kué in Canada is counted at De Beers’ 51% share). USGS estimates that the world mined about 69 million carats of gem-quality natural diamond in 2025 and about 38 million carats of industrial-grade natural diamond, a total of about 107 million carats (USGS gemstones; USGS industrial diamond).
Chart
Gem-quality natural diamond output, selected countries
Million carats, 2025 estimate
Russia is the largest producer. USGS says it made roughly 30% of the world’s gem-grade diamonds by volume in 2025, and that US, EU and G7 sanctions bar the import of Russian rough and finished stones, including those processed in third countries. Botswana, Angola and Canada each mined about 13 million carats of gem-quality stones. For a country-by-country ranking with values, see our guide to the top diamond-producing countries.
De Beers’ own table shows where its carats come from and how different the economics are. Botswana is the volume engine. Namibia earns the highest price per carat. South Africa and Canada earned less than or about the same as their unit cost in 2025.
| Operation | Production (million carats) | Realised price (US$ per carat) | Unit cost (US$ per carat) |
|---|---|---|---|
| Botswana | 15.1 | 110 | 38 |
| Namibia | 2.1 | 353 | 244 |
| South Africa | 2.2 | 66 | 110 |
| Canada | 2.2 | 50 | 51 |
| De Beers total | 21.7 | 142 | 86 |
Source: De Beers Group, preliminary financial results, 20 February 2026. Production is on a 100% basis except Gahcho Kué (51%). De Beers states that the realised price includes non-equity product and is therefore not directly comparable with unit cost, so read the last two columns as a guide, not as a margin per carat.
How De Beers prices and profit have moved
The 2025 results show how the price pressure reached the mines. De Beers’ average rough price index fell 12% in 2025, or 25% once stock rebalancing is counted (selling low-demand goods at lower prices to clear inventory). The average realised price fell 7% to US$142 per carat, and the underlying EBITDA (earnings before interest, tax, depreciation and amortisation) was a loss of US$511 million, against a loss of US$25 million in 2024 (De Beers, 20 February 2026). Anglo American also wrote down its carrying value of De Beers by US$2.3 billion, which it linked to lower forecast prices from a greater shift in customer preference between natural and laboratory-grown stones, and a surplus of rough relative to demand.
Chart
De Beers average realised price by operation
US$ per carat, first half of each year
The first half of 2026 shows two forces at once. Realised price fell from US$155 to US$105 per carat. De Beers puts that down to two causes: a sales mix with more lower-value goods, and a 16% fall in the average rough price index. Unit cost fell 26% to US$64 per carat, and the underlying EBITDA loss narrowed to US$113 million from US$189 million (De Beers, 30 July 2026). The company says demand for larger, higher-quality natural diamonds stayed resilient, while smaller and lower-quality stones faced pricing pressure from synthetic lab-grown diamonds. That split matters for a mine: a pipe that yields mostly small stones has more exposure than one that yields large ones.
Not every operation lost price. In the chart, Namibia’s average price rose while Canada, South Africa and Botswana fell.
Who is buying De Beers
Anglo American owns 85% of De Beers and the Government of Botswana owns 15%. Anglo says it is committed to selling its stake and is running a formal process, with an update expected during 2026 (De Beers, 30 July 2026). On 30 July 2026 Anglo’s chief executive, Duncan Wanblad, said Anglo was not exclusive with any one bidder and that more than one consortium was in the process. Press reports named the Global Diamond Consortium, believed to be led by former De Beers managing director Gareth Penny and including Angola and Namibia, as the group Anglo had chosen. Bloomberg reported a price as low as US$1 billion for the 85% stake, with roughly US$750 million upfront and US$250 million later (Miningmx, 30 July 2026). Bloomberg cited people familiar with the transaction; the price is not an Anglo figure.
Bloomberg reported on 15 October 2026, per Miningmx, that Richemont, owner of Cartier, and the US jewellery retailer Signet were in advanced talks to join the consortium, and that Botswana was in talks to raise its stake from 15% to about 25%. Bloomberg’s sources said there was no guarantee either company would join, and the size of any stake was unclear but expected to be small (Miningmx, 15 October 2026). Anglo has also agreed to sell its steelmaking coal business in Australia, with completion expected by the first quarter of 2027 (Anglo American Q2 2026 production report).
The mines are being run for cash while the sale proceeds. De Beers announced its intention to pause Venetia in South Africa for two years, paused the Tuzo Phase 3 open-pit expansion at Gahcho Kué, cut capital spending by 33% to US$115 million in the half-year, and kept 2026 production guidance at 21 to 26 million carats with Orapa and Jwaneng maintenance in the second half (De Beers, 30 July 2026). In the second quarter alone production rose 88% to 7.8 million carats against a quarter in 2025 hit by extended maintenance at Orapa (Anglo American).
How the diamond industry is adapting to lab-grown growth
A common question is how the industry is adapting. From the producers’ own reports, five responses stand out.
- Separating the two products. De Beers announced the closure of Lightbox (8 May 2025) and says the growing price gap should help consumers see natural and lab-grown stones as separate categories (De Beers, 30 July 2026).
- Selling natural diamonds on emotion and occasion. De Beers’ US study of 18,500 women found Gen Z now accounts for 23% of natural diamond demand by value, that non-bridal occasions are three-quarters of US demand, and that the average natural diamond jewellery piece cost US$4,063 in 2025 against US$3,242 in 2023 (De Beers, 11 June 2026). It is a producer’s survey, so read it as the industry’s own view.
- Cutting supply and cost. Pauses at Venetia and Tuzo, lower capital spending and a unit cost cut from US$87 to US$64 per carat in the half-year.
- Moving synthetic know-how into industry. Element Six now targets industrial and technology uses only.
- Waiting for supply to shrink. De Beers expects world rough output to fall in the coming years, and USGS says the largest diamond mines are mature, past peak output, and that several are expected to close (USGS, 2026).
How fast is lab-grown diamond technology advancing?
The technology is not new, and the big change is cost, not quality. Synthetic diamond already makes up more than 99% of the diamond used in industry. USGS estimates world manufactured industrial diamond at more than 15 billion carats, with China, the United States and Russia making about 99% of it, and at least 15 countries having the technology to produce synthetic diamond (USGS, 2026). For jewellery, both CVD and HPHT stones can be cut and polished like mined ones, and growth takes weeks. Experts with the right tools can still tell the two apart by their chemical fingerprints (National Geographic). The commercial effect is what De Beers describes: falling wholesale prices and low-cost capacity in China.
Are regulations keeping pace with lab-grown diamond innovation?
In the United States the rules are guides from the Federal Trade Commission (FTC), not a diamond-specific law. The guides’ definition of a diamond (16 CFR 23.12) describes a mineral of pure carbon crystallised in the isometric system and does not say the stone must be mined. The same section allows the word “cultured” for a laboratory-created diamond only with a clear disclosure such as “laboratory-grown” (16 CFR 23.12, 2023 edition). Section 23.25 says that the name of a stone, or words such as “gem” and “stone”, used for a laboratory-grown, synthetic or simulated stone should be immediately preceded by a disclosure such as “laboratory-grown” (16 CFR 23.25, 2023 edition). Rules in other countries differ, and the text above is from the 2023 edition, so check the current code before you rely on it.
Natural versus lab-grown diamonds compared
The table lists only points that a source supports. Some commonly repeated comparisons, such as carbon per carat, are left out because published figures depend on the power source and the study’s boundaries, and some sellers do not disclose them (National Geographic).
| Point | Natural diamond | Lab-grown diamond |
|---|---|---|
| Origin | Mined from kimberlite and alluvial deposits; about 107 million carats in 2025 (USGS estimate) | Grown by CVD or HPHT in a factory in weeks |
| Price trend | De Beers average rough price index down 12% in 2025 (25% including stock rebalancing) and 16% in the first half of 2026 (now reported including rebalancing) | Jewellery stones down 90% at wholesale since 2018 (De Beers, May 2025) |
| Share of US independent jewellers’ diamond sales by value, 2025 | 85% (De Beers data) | 15% (De Beers data) |
| Supply outlook | Mature mines; production expected to decline (USGS; De Beers) | Technology to make it in at least 15 countries (USGS); more low-cost output from China (De Beers) |
| US naming rules | Meets the FTC definition of a diamond | Meets the same definition; the FTC guides call for a clear qualifier such as “laboratory-grown” (sections 23.12 and 23.25) |
Mining has real environmental costs, from land disturbance to water and energy use, and any comparison should state its boundaries. Our short explainer below covers the seven impacts that mines are usually judged on.
▶ The seven environmental impacts of mining, explained in claymation. · 2:31
Canada and Alberta: where new natural supply could come from
Canada is the main hope for new North American supply, but its output is falling. Natural Resources Canada reports 13.3 million carats of rough diamonds worth C$1.47 billion in 2024, down 17% in volume and 30% in value from 2023, and expects production to keep trending lower as mines close, high-capacity sections are exhausted and ore grades decline (Natural Resources Canada, Diamond facts). Canada held 12.3% of world production by carats in 2024 (preliminary data).
Chart
Canadian rough diamond output
Million carats a year; chart starts at the 2018 peak (2015: 11.7)
Alberta has diamond-bearing kimberlite but remains an exploration area. In the mid-1990s a geologist at Alberta Energy Company spotted shallow magnetic anomalies that matched breaks in seismic lines near the Buffalo Head Hills and suggested they could be kimberlite pipes. Ashton Mining discovered kimberlites there in 1997, and 38 pipes have since been located. Many are diamond-bearing, at least six have estimated grades above 3 carats per hundred tonnes, and one pipe, K252, gave a preliminary mini-bulk sample grade of 55 carats per hundred tonnes (Alberta Geological Survey, Special Report 79, 2006). A grade is the amount of diamond per unit of rock, and a mini-bulk sample is a test sample of kimberlite processed to count the diamonds. That report dates from 2006, so use it for the geology and check company filings and the survey for the current status.
The lesson for exploration is that kimberlite pipes are small targets, and in Alberta they were found through magnetic and seismic anomalies, which are then tested by drilling. Satellite data does not see a buried pipe, but it can map structure, surface geology and cover to rank ground before ground geophysics, and it fits the early screening stage. Farmonaut lists diamonds among the minerals its satellite mineral detection service screens for, and results are exploration targets, not a resource estimate. For how indicator grains lead to pipes, see our guide to diamond exploration.
▶ What remote sensing for mining means, in three minutes. · 2:01
What to check in a diamond producer’s report
- Basis of production. Is it 100% of joint ventures or the company’s attributable share? De Beers uses 100% except Gahcho Kué.
- Price and mix. Realised price falls when the sales mix shifts to cheaper goods even if the price index is flat. De Beers separates the two in its commentary.
- Price versus unit cost. Compare them by operation, not for the group, and note the company’s own caveat on comparability.
- Stock rebalancing. Sales of old inventory at low prices can create trading losses that have nothing to do with mine costs.
- Currency. De Beers’ 2026 unit cost guidance assumes about 16.50 rand per US dollar, so a currency move changes the figure.
- Ownership change. A sale can change reporting, so check which entity a figure belongs to.
The calculator below shows why the gap between price and cost matters. Enter your own carats sold, price and cost figures, then test a price fall. It is an illustration with round example numbers, not a De Beers forecast. Licence owners who need a quote for a screening of their own ground can use our mining query form or contact us. For where to find licence records, see our guide to mining cadastre portals by country.
Calculator
How much margin is left after a price fall?
Enter your own carats, price and cost to see the break-even price fall.
- Revenue (US$ million): $1,000
- Operating margin now (US$ million): $300
- Operating margin after the fall (US$ million): $200
- Margin per carat after the fall (US$): 20.00
Round example values, not a De Beers forecast. The price is an input: example, use today’s price. Money is in US$; carats in millions, so US$ per carat times million carats gives US$ million. Operating margin here is price minus unit cost only, before royalties, tax and capital spending.
▶ The three limits of satellite exploration that matter in due diligence. · 2:08
If this topic matters to you, read Minelab Gold Monster 1000: Price, Specs, Verdict next.
Related reading on this site: Energy Costs in Mining: Share of Gold and Copper Cost.
Frequently asked questions
Does De Beers still sell lab-grown diamonds?
Not as jewellery going forward. De Beers announced on 8 May 2025 that it would close Lightbox, and its synthetic arm Element Six now serves industrial and technology users only (De Beers, 8 May 2025).
Why did De Beers close Lightbox?
The company says lab-grown jewellery prices fell 90% at wholesale from the US$800 per carat launch price, which moved closer to a cost-plus model and undercut the brand’s purpose of showing a value gap. It chose to put its marketing money into natural diamonds.
What is De Beers’ market share of the diamond market?
No single basis gives a clean share: De Beers reports 21.7 million carats for 2025 on a 100% basis for joint ventures, while USGS estimates world output at about 69 million carats gem-quality and 38 million industrial. Compare like with like before quoting a percentage.
Who owns De Beers?
Anglo American owns 85% and the Government of Botswana 15%. Anglo is selling its stake, and on 15 October 2026 Bloomberg reported (via Miningmx) that a consortium led by Gareth Penny was the preferred bidder and that Richemont and Signet were in advanced talks to join.
Is De Beers making a profit?
Not at the underlying EBITDA level. De Beers reported losses of US$511 million in 2025 and US$113 million in the first half of 2026, an improvement on the US$189 million loss in the first half of 2025.
How is the diamond industry adapting to lab-grown growth?
Producers are separating the two categories in marketing, aiming natural diamonds at Gen Z and non-bridal occasions, cutting costs and pausing mines, and moving synthetic technology into industry. See the list above for the figures.
How fast is lab-grown diamond technology advancing?
Industrial synthetic diamond is already more than 99% of use. In jewellery the change is lower cost and falling prices rather than a new method; both CVD and HPHT are established.
Are regulations keeping pace with lab-grown diamond innovation?
In the US the FTC guides accept lab-grown stones as diamonds when clearly described as laboratory-grown, and they are updated by the FTC, not by industry. Check the current code and local rules.
What share of diamond jewellery sales is lab-grown?
De Beers’ data from 950 US independent jewellers show 15% by value in 2025. Other sources use other bases, such as units or engagement rings, and give different figures.
Are lab-grown diamonds better for the environment?
It depends on the power used and on the study’s boundaries. Some producers use renewable power or offsets, and some do not disclose their footprint, so look for a published, audited figure before accepting a claim.
Could Alberta become a diamond producer?
The Buffalo Head Hills field has 38 known pipes and grades above 3 carats per hundred tonnes in at least six of them (Alberta Geological Survey, 2006), but turning a field into a mine needs bulk sampling, a resource estimate, permits and a market that pays for the stones.
This page is for information only. It is not investment advice and gives no price targets or share prices. The sale price and bidder details come from Bloomberg reports relayed by Miningmx, not from Anglo American or De Beers filings. It is not legal advice either; check the current FTC guides and local rules before you rely on the disclosure points.
Farmonaut mining
Screen a licence area from space before drilling
Consultants can see how satellite data ranks ground for diamonds and other minerals as an exploration target, ahead of any resource estimate.

Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026: gemstones: pubs.usgs.gov
- USGS, Mineral Commodity Summaries 2026: diamond (industrial): pubs.usgs.gov
- De Beers Group, intention to close Lightbox (8 May 2025): debeersgroup.com
- De Beers Group, preliminary financial results for 2025 (20 February 2026): debeersgroup.com
- De Beers Group, interim financial results for 2026 (30 July 2026): debeersgroup.com
- De Beers Group, latest research on US consumer trends (11 June 2026): debeersgroup.com
- Anglo American, Q2 2026 production report: angloamerican.com
- Miningmx, Anglo not exclusive with any buyer for De Beers (30 July 2026): miningmx.com
- Miningmx, Richemont and Signet in talks to join bid for De Beers (15 October 2026): miningmx.com
- Natural Resources Canada, Diamond facts: natural-resources.canada.ca
- Alberta Geological Survey, Special Report 79: Buffalo Head Hills kimberlites (2006): ags.aer.ca
- Code of Federal Regulations, 16 CFR 23.12 (2023 edition): govinfo.gov
- Code of Federal Regulations, 16 CFR 23.25 (2023 edition): govinfo.gov
- National Geographic, Are synthetic diamonds really better for the planet?: nationalgeographic.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited

 Exploration consultancy · South Africa · Gold










