

Gold in the DRC · Mines, output and exports
Gold Mining in DRC: Mines, Output and Exports
The DRC’s industrial gold comes almost entirely from Kibali, which produced 673,520 oz in 2025. Recorded exports were over 28.2 tonnes, and only about 2.8 tonnes of that was artisanal.
Key takeaways
- Kibali produced 673,520 oz in 2025, down 2% on 2024; reserves are 11 Moz at US$1,500/oz (AngloGold Ashanti technical report, 31 December 2025).
- Recorded gold exports were over 28.2 t worth about US$2.84 billion in 2025, against 27.93 t and US$1.53 billion in 2024 (CTCPM data via Bankable, April 2026).
- Recorded artisanal exports were 2.83 t in 2025, about a tenth of the total; much artisanal gold is not recorded.
- Kibali’s AISC was US$1,337/oz on Barrick’s 45% basis in 2025 (Barrick Annual Report 2025).
- Twangiza has been under M23 control since May 2025 (Northern Miner, 21 October 2025); check who controls the ground before the geology.
In this article
- How much gold does the DRC produce
- Main gold mines and projects in the DRC compared
- Kibali: the mine that dominates DRC gold
- Kibali revenue and costs over three years
- Geology and mining methods at Kibali
- Artisanal gold in the DRC: what the numbers show
- Conflict and gold in South Kivu and Ituri
- Rules, royalties and the state gold buyer
- What to check before you back a DRC gold project
- How satellites help screen DRC licence areas
- Frequently asked questions
Gold mining in the Democratic Republic of the Congo (DRC) is dominated by one industrial mine, Kibali in the north-east, which produced 673,520 troy ounces (about 21 tonnes) in 2025 (AngloGold Ashanti Kibali technical report summary, 31 December 2025). Officially recorded gold exports were more than 28.2 tonnes worth about US$2.84 billion in 2025, against 27.93 tonnes and US$1.53 billion in 2024 (Bankable, 3 April 2026, quoting the state mining planning cell CTCPM). Only about 2.8 tonnes of that came from artisanal miners (the export total and the Kibali ounces use different bases, explained below), even though artisanal digging is spread across Ituri, South Kivu, Maniema and Haut-Uélé. The gap between what is exported and what is dug is the main thing to understand about this sector.
This guide is for licence owners, consultants and investors who need facts rather than headlines. It covers how much gold the country produces, the main mines and projects side by side, what Kibali costs to run, what the artisanal numbers do and do not show, the conflict risk in the east, the royalty and the state buyer, a checklist for due diligence, and a calculator for a Kibali-style mine. Every figure carries its source and date. Mining terms are explained the first time they appear.
How much gold does the DRC produce
There is no single clean number. The US Geological Survey (USGS) does not list the DRC as its own line in its 2026 gold table. It groups the country inside “Other countries”, which together mined an estimated 1,000 tonnes of the world’s 3,300 tonnes in 2025 (USGS Mineral Commodity Summaries 2026, gold). So the best country-level evidence comes from company reports and from export statistics.
Chart
Kibali gold produced, Barrick 45% share
Thousand troy ounces per year
Kibali is the anchor. In 2024 it supplied more than 99% of the DRC’s industrial gold output, and in the first quarter of 2025 it supplied 99.5% of the output the country reported (African Exponent, 2025). Its 2025 output of 673,520 oz, which is about 20.9 tonnes, was 2% below 2024 (AngloGold Ashanti, 2025). Barrick’s 45% share was 303,000 oz, below its guidance range of 310,000 to 340,000 oz, mainly because the ore processed had a lower grade than planned (Barrick Annual Report 2025).
Export data and company data do not match exactly. Bankable notes that the CTCPM reported more than 25 tonnes from Kibali for 2025, while Barrick and AngloGold Ashanti reported 673,520 oz, about 21 tonnes (20.95 t at 31.1035 g per ounce). The two figures have different bases. The CTCPM numbers come from company declarations and administrative reconciliations of what is reported to the state; Barrick’s come from audited ounces produced under international financial reporting standards (Bankable). The 25 t also matches the export record: 28.2 t of total exports less 2.8 t of artisanal exports leaves about 25.4 t of industrial gold. The gap is similar in 2024, when the state-based figure for Kibali was about 26.1 t (African Exponent) against about 21.4 t from the company’s 687,000 oz. For a mine model use the company ounces (about 21 t); for national export totals use the CTCPM figures.
Gold output grows slowly because the one big mine is mature. The chart below shows Barrick’s 45% share of Kibali falling from 343,000 oz in 2023 to 303,000 oz in 2025, while the average price Barrick realised on its sales rose from US$1,948 to US$3,501 an ounce (Barrick Annual Report 2025). Higher prices lifted revenue; they did not lift ounces.
Main gold mines and projects in the DRC compared
How we chose: this table lists the DRC gold operations and projects for which we could open an owner filing, a regulator-linked statistic or a specialist news report dated 2019 or later. It is not a complete cadastre, and it leaves out the many small licences held by cooperatives and junior companies. Where a source is old, the table says so.
| Operation | Province | Owner and operator | What the sources show |
|---|---|---|---|
| Kibali | Haut-Uélé | Barrick (operator) 45%, AngloGold Ashanti 45%, state company SOKIMO 10% | 673,520 oz in 2025; reserves 11 Moz; planned life to 2043 (AngloGold Ashanti, 2025) |
| Twangiza | South Kivu | Twangiza Mining, linked to Baiyin International Investments | Under M23 control since May 2025; force majeure declared (Northern Miner, 21 October 2025). Latest dated source found: 11 November 2025, rebels trying to restart mining after army air strikes (Bankable) |
| Adidi-Kanga (formerly Mongbwalu project) | Ituri | Vector Resources (ASX-listed) completed the purchase of a 60% interest in January 2019, from Mongbwalu Goldfields Investments | About 3.2 Moz at 6.6 g/t, JORC resource reported at the 2019 sale (Miningmx, 11 January 2019) |
| Artisanal and semi-industrial sites | Ituri, South Kivu, Maniema and others | Cooperatives, individual miners, local traders | Official artisanal exports of 2.83 tonnes in 2025 (Bankable, April 2026) |
Grade is the amount of gold in each tonne of rock, in grams per tonne (g/t). A JORC resource is an estimate prepared under the Australasian JORC Code; it is not the same as a reserve, which must also pass mining and economic tests. The Adidi-Kanga figure is the one reported at the 2019 sale. The latest dated source we found is from 2019 (the 3.2 Moz figure is the same one reported by Vector at completion). No later feasibility study, mining decision or production was found in searches in October 2026, so treat it as an old reference point.
Kibali: the mine that dominates DRC gold
Kibali is in the Haut-Uélé district of north-eastern DRC, about 1,800 km north-east of Kinshasa. Kibali Goldmines SA is owned 45% by Barrick, 45% by AngloGold Ashanti and 10% by the Congolese state company SOKIMO, and Barrick operates it (AngloGold Ashanti technical report summary, 31 December 2025).
The technical report gives the following for the whole mine (100% basis): reserves of 110 million tonnes at 2.97 g/t, holding 11 million ounces (Moz), estimated at a gold price of US$1,500 per ounce; measured and indicated resources of 200 million tonnes at 2.79 g/t (18 Moz); and inferred resources of 49 million tonnes at 2.1 g/t (3.3 Moz). Open pits are planned to run to 2041 and underground mining to 2043. In 2025 the plant treated 8.322 million tonnes at a head grade of 2.79 g/t and recovered about 90% of the gold. Recovery is the share of the gold in the ore that ends up in the final product.
Costs rose faster than output. On Barrick’s 45% basis, 2025 total cash costs were US$1,099 per ounce and all-in sustaining costs (AISC, the cost of producing an ounce including the capital needed to keep the mine going) were US$1,337 per ounce. In 2024 the AISC was US$1,123 (Barrick Annual Report 2025). Barrick said lower grades and higher royalties linked to the higher gold price drove the increase. Even so, Barrick’s share of Kibali earned US$527 million of income on US$1,040 million revenue in 2025.
Two other facts matter to anyone assessing the mine. A 16 MW solar plant with battery storage is being added to the existing hydropower, to raise the renewable share of the mine’s power from 81% to 85% (Barrick Annual Report 2025). And an employee died in an underground incident on 15 December 2025, which Barrick linked to a short stoppage and lower fourth-quarter output.
Kibali revenue and costs over three years
The table uses Barrick’s 45% basis, taken from its 2025 annual report. The rise in revenue came almost entirely from price, not volume, and costs per ounce rose with lower grades and higher royalties.
Chart
Kibali 2025: price versus cost per ounce
US$ per ounce, Barrick 45% basis
| Measure (Barrick 45% share) | 2023 | 2024 | 2025 |
|---|---|---|---|
| Gold produced (thousand oz) | 343 | 309 | 303 |
| Barrick realised gold price (US$/oz) | 1,948 | 2,397 | 3,501 |
| Revenue (US$ million) | 670 | 743 | 1,040 |
| Income (US$ million) | 243 | 316 | 527 |
| Total cash costs (US$/oz) | 789 | 905 | 1,099 |
| All-in sustaining costs (US$/oz) | 918 | 1,123 | 1,337 |
| Average grade processed (g/t) | 3.21 | 2.82 | 2.79 |
Two readings follow. First, the grade processed fell from 3.21 g/t to 2.79 g/t in two years, a 13% drop, and ounces fell with it. Second, the gap between the realised price and the AISC widened from about US$1,030 an ounce in 2023 to about US$2,164 in 2025, which is why income more than doubled while output fell. A mine with this margin can absorb cost rises; a smaller project with a high AISC cannot. Both gold price and costs are inputs in the calculator on this page, so you can test your own case.
The mine also pays the state directly. Under the 2018 Mining Code the royalty is 3.5% of gold sales, and Kibali’s state partner SOKIMO holds 10% of the company. Barrick’s own filing says higher royalties linked to the higher gold price were one reason costs per ounce rose.
Geology and mining methods at Kibali
Kibali sits in the Moto Greenstone Belt, a Neoarchean (more than 2.5 billion years old) belt of rock in the north-east of the Congo Craton. The host rocks are mainly sandstones, banded iron formation (BIF, a layered iron-rich rock), chert, conglomerates and carbonaceous shales. The gold is of the orogenic type, meaning it was deposited by hot fluids moving through faults and folds during mountain building. It is mostly held in pyrite, an iron sulphide, in disseminated, replacement and vein styles (AngloGold Ashanti technical report summary, 31 December 2025).
Chart
Kibali reserves and resources, 100% basis
Million ounces of gold at 31 December 2025
The main deposit is KCD (Karagba-Chauffeur-Durba). It has five semi-stacked lodes that extend more than 2.5 km down plunge. The 3000 Lode is 2.2 km long and 240 m wide. Other deposits include Gorumbwa, Pakaka and Mengu Hill. Open pits work Gorumbwa, Pamao, Kalimva and other deposits, while KCD is mined underground. The report recommends reviewing in-pit dumping and considering owner-operated open pit mining to cut cost.
The plant has a design capacity of 7.2 million tonnes a year and uses two routes. Ore whose gold is easy to recover, by gravity and carbon-in-leach (CIL, a process that dissolves gold in a cyanide solution and catches it on carbon), goes one way. Gold locked inside sulphides goes through flotation, ultrafine grinding and cyanide treatment of the concentrate. First commercial production was in 2013, and 91% of employees are Congolese, 54% from the local area.
The next ounces may come from ARK (Agbarabo-Rhino-Kombokolo), a fold-controlled system about 1.5 km along strike. Barrick reported that drilling in the fourth quarter of 2025 extended ARK a further 300 m down plunge (Barrick Annual Report 2025), and the technical report recommends a trade-off study of mining options. Kalimva, about 1.4 km along strike and 600 m deep, remains open at depth. Exploration results are not reserves until a study turns them into one.
▶ Follows gold from rock to bar: drilling, crushing, dissolving, carbon, melting and refining. · 5:27
Artisanal gold in the DRC: what the numbers show
Artisanal and small-scale mining (ASM) means gold dug and processed by individuals or small groups with basic tools, usually without a large licence. No named source gives a reliable share of national output for artisanal miners. What can be shown is the official export record.
Chart
Recorded gold exports, 2024 versus 2025
Tonnes
Recorded artisanal exports were 2,834.72 kg in 2025, up about 61% from 1,755.82 kg in 2024, which is roughly one tenth of total recorded gold exports (Bankable, April 2026, from CTCPM data). The state buyer opened offices across the country in 2025, and that helped formal exports grow even after the artisanal hub of Bukavu fell to M23 rebels.
The same source cannot say how much was dug and not exported. In Ituri, the research group IPIS found in 2023 that gold is mined there exclusively by artisanal and semi-industrial miners, and that armed groups run mines, tax production, or take part in trading and smuggling (IPIS, Djugu report, 2023). When output is informal, the export figure is a floor, not a measure of production.
For consultants this has a practical effect. Any resource estimate near an artisanal zone should assume that surface and shallow gold has already been worked, and a site visit should record the pits, dumps and processing areas that satellite images show. Workforce and productivity data are also much thinner than in countries such as Australia, where mining workforce statistics are published every year.
Conflict and gold in South Kivu and Ituri
Twangiza in South Kivu shows how conflict reaches an industrial mine. Banro Corporation began commercial production there in 2012. Chinese firm Baiyin International Investments bought the mine in 2020 for a nominal US$1, because its liabilities were larger than its projected revenue. M23 has controlled the concession since May 2025. The company declared force majeure, said it had lost more than 100 kg of gold a month since the seizure, and said rebels had taken at least 500 kg of gold worth about US$70 million at then-current prices. A drone strike on 15 October 2025 destroyed the power infrastructure, and responsibility for it is unclear (Northern Miner, 21 October 2025). The loss figures are the company’s own claims.
In Ituri, IPIS describes gold as an important source of income for armed groups, although it concludes that gold is not the root cause of the conflict there. The fighting began in 2017-2018 in farming areas with few mines and moved towards the gold zones around Mongbwalu in 2020-2021 (IPIS, 2023). Industrial mining in the area, which boomed in the 20th century, gave way to artisanal and semi-industrial work after decades of civil war and neglect of mining infrastructure.
For a project in the east the security question comes before the geology. A licence on paper can be unusable if the road, the power line or the site is under another group’s control.
Rules, royalties and the state gold buyer
The DRC revised its Mining Code in March 2018. The change raised the gold royalty from 2.5% to 3.5% of the value of production (ITSCI, 27 March 2018). A royalty is a payment to the state on the value of the metal sold, due whether or not the mine makes a profit. Bankable still gave 3.5% as the statutory gold royalty on 31 August 2026, and we found no change to the gold rate since 2018. A separate 50% tax on excess profits can apply when prices rise more than 25% above the feasibility-study assumption (Article 251 bis; Bankable, 31 August 2026).
The state has also moved into the artisanal trade. DRC Gold Trading S.A., a state-owned company, buys, markets and exports artisanal gold. On 10 February 2026 it opened a branch in Lubumbashi, Haut-Katanga, and a second buying office in Durba, Haut-Uélé. Its stated targets are ten offices nationwide, artisanal exports of 15 to 18 tonnes a year and more than US$2.6 billion in export revenue (Ecofin Agency, February 2026). The recorded 2.83 tonnes in 2025 shows how far the company is from that target.
Foreign buyers and refiners usually apply the OECD Due Diligence Guidance for Responsible Supply Chains of Minerals from Conflict-Affected and High-Risk Areas, which sets steps for tracing gold back to its mine of origin. Companies that handle DRC gold should expect to show the chain of custody from the mining site to the export bar.
Foreigners who want a small-scale licence face limits in many African countries, and the rules differ by country, so read the cadastre guidance for the DRC before you commit money. For a wider view of national gold inventories see the Farmonaut guide to countries with the most gold reserves, and for licensing practice in neighbouring countries see the guides to gold exploration in Zambia and gold exploration in Tanzania. A French-language guide covers reading a DRC licence square by satellite.
▶ Explains how small-scale mining licences work for foreigners in Africa. · 5:16
What to check before you back a DRC gold project
- Licence status. Confirm the licence type, holder, expiry and boundaries with the mining cadastre, and look for overlap with artisanal zones.
- Who controls the ground. Check security reports from IPIS and the United Nations for the territory, not only for the province.
- Resource basis. Ask whether figures are JORC or NI 43-101 reports by a qualified person, what gold price they assume (Kibali’s reserves use US$1,500 per ounce) and the date.
- Power and roads. Kibali has its own hydropower and a solar addition. Most sites have neither.
- Chain of custody. Know which export route and which buyer will take the gold, and what traceability paperwork they require.
- Costs. Compare the project with Kibali’s AISC of US$1,337 per ounce on Barrick’s 2025 basis, and remember that a remote site with no grid will usually cost more.
None of this is investment advice. It is a list of questions that a consultant or an owner can use to test a claim.
Calculator
What could a Kibali-style mine earn per year?
Enter your own ore tonnage, grade, recovery, price and cost.
- Revenue at your price (US$): $1,944,475,702
- Margin after all-in sustaining cost (US$): $1,101,869,565
- Royalty at 3.5% of revenue (US$, normally already inside AISC): $68,056,650
Example values only, not a forecast or any company’s figures; the default tonnage, grade and recovery are rounded from Kibali’s 2025 operating data (AngloGold Ashanti technical report summary). Prices and costs are inputs: example, use today’s price, in US$ per ounce.
How satellites help screen DRC licence areas
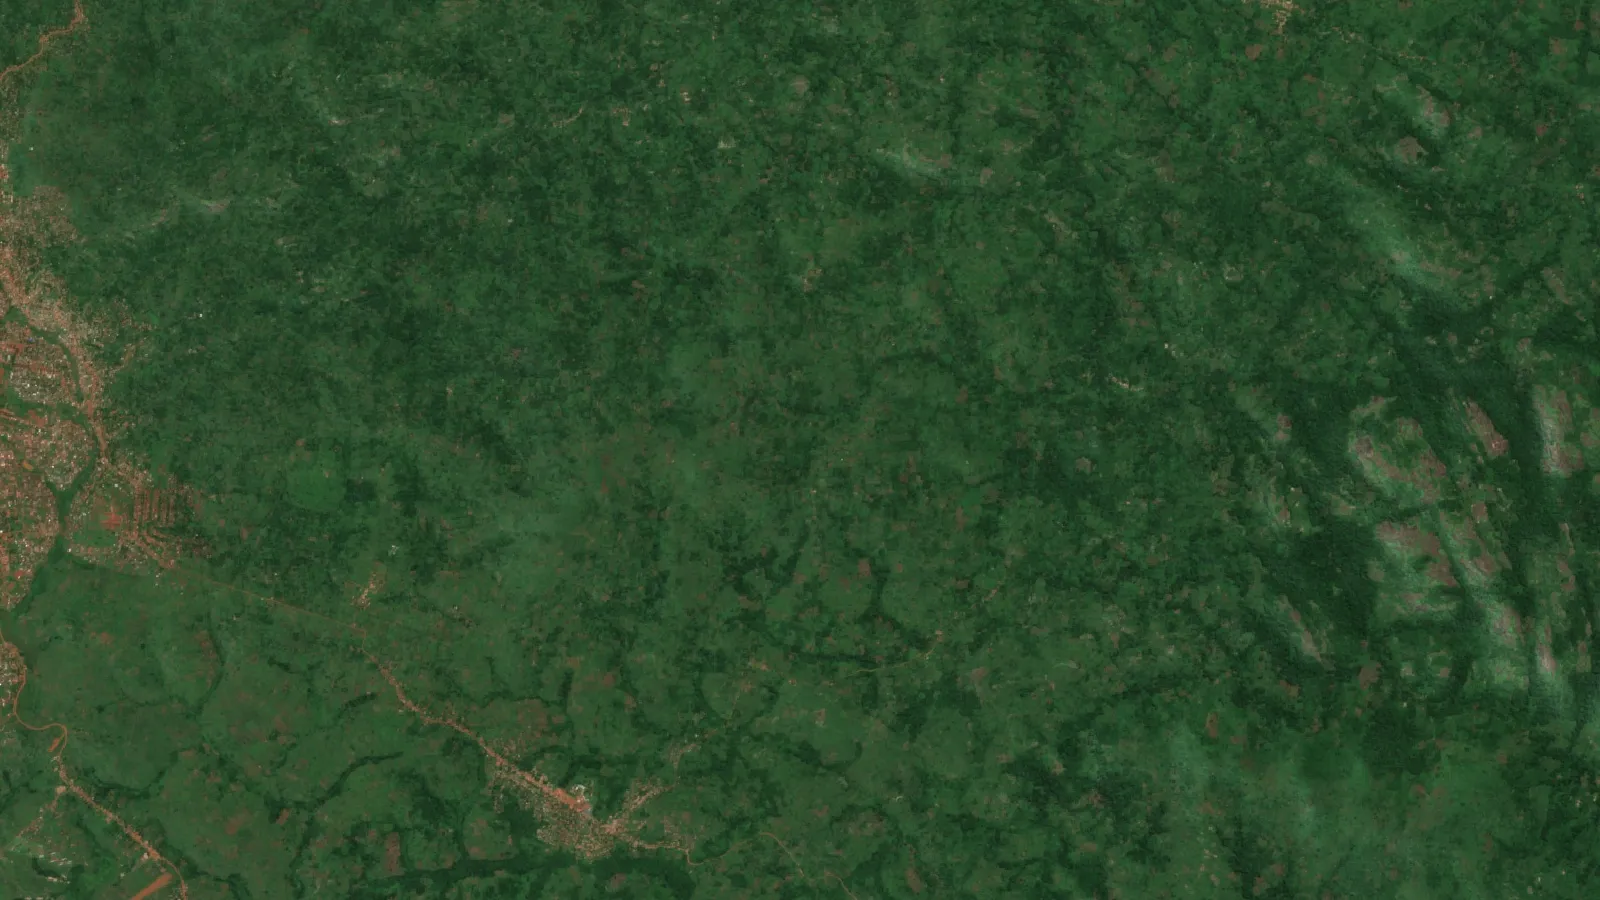
Satellites cannot see gold. They can map the rock around it: iron-oxide staining, clay minerals and fault lines left by hot fluids. In the forested east the cover is thick, so the useful products are alteration maps for exposed ground, change maps that show new pits and tracks, and terrain models for planning access. Farmonaut turns a licence boundary into an exploration-target map and a land screen; the results are exploration targets that sit ahead of a resource estimate, and they are not an environmental or social clearance. Farmonaut also offers traceability, fleet management and carbon footprinting tools for operating sites.
▶ Explains how satellites map the rock around gold rather than the gold itself. · 4:25
For a closer look at a related question, see our guide: Largest Cobalt Mines in the DRC, Ranked by Output.
Frequently asked questions
Which is the biggest gold mine in the DRC?
Kibali, in Haut-Uélé. It produced 673,520 oz in 2025 and held 11 Moz of reserves at the end of that year, and it supplied more than 99% of the industrial gold the country reported in 2024.
How much gold does the DRC export?
Recorded exports were more than 28.2 tonnes in 2025, worth about US$2.84 billion, compared with 27.93 tonnes and US$1.53 billion in 2024 (CTCPM data via Bankable, April 2026).
Who owns Kibali?
Barrick and AngloGold Ashanti own 45% each, and the Congolese state company SOKIMO holds 10%. Barrick operates the mine.
How much of DRC gold is artisanal?
No named source gives a reliable share. Recorded artisanal exports were 2.83 tonnes in 2025, about a tenth of recorded exports, but much artisanal gold is not recorded.
What is the gold royalty in the DRC?
The 2018 Mining Code raised it from 2.5% to 3.5% (ITSCI, 2018). It was still 3.5% in August 2026 (Bankable, 31 August 2026).
What happened at the Twangiza mine?
M23 took control of the concession in May 2025. The operator declared force majeure and said it had lost gold and equipment. A drone strike hit the power infrastructure on 15 October 2025 (Northern Miner, 21 October 2025).
Is gold mining in the DRC legal for foreigners?
Foreign companies hold industrial licences, as Barrick and AngloGold Ashanti do at Kibali, usually with a state partner. Small-scale licences are restricted in many African countries, so check the cadastre rules before you commit money.
Where is the gold in the DRC?
The main areas in the sources are Haut-Uélé (Kibali), Ituri (Mongbwalu and Adidi-Kanga), South Kivu (Twangiza) and Maniema. Gold also occurs in other provinces.
What does it cost to produce an ounce at Kibali?
On Barrick’s 45% basis, total cash costs were US$1,099 per ounce and all-in sustaining costs were US$1,337 per ounce in 2025.
Does gold mining harm the forest and rivers in the DRC?
Artisanal mining can clear forest and pollute water, especially where mercury is used. Mercury, used to bind fine gold, is toxic to miners and to people downstream. Satellite change maps can show where new pits appear.
This page is for information only. It is not investment advice and not legal advice. Confirm licence and royalty rules with the DRC regulator. Artisanal gold mining needs permission from the licence holder and the authorities, and mercury should not be used.
Farmonaut mining
Map your mining site from space
Consultants can screen a licence boundary for exploration targets with satellite data before a site visit.

Mining Pro sample view, synthetic data
Keep reading
Sources
- AngloGold Ashanti, Kibali technical report summary (31 December 2025): sec.gov
- Barrick, Annual Report 2025: s25.q4cdn.com
- AngloGold Ashanti, Annual Report 2025: minedocs.com
- Bankable, DR Congo gold exports flat in 2025 (3 April 2026): bankable.africa
- Northern Miner, Congo rebels loot US$70M in gold from Twangiza mine (21 October 2025): northernminer.com
- Ecofin Agency, DRC expands state gold buying (February 2026): ecofinagency.com
- ITSCI, DRC mineral royalty increases with mining code revision (27 March 2018): itsci.org
- IPIS, Armed groups, territorial control, land disputes and gold exploitation in Djugu (2023): ipisresearch.be
- Miningmx, Vector buys former AngloGold Mongbwalu prospect (11 January 2019): miningmx.com
- USGS, Mineral Commodity Summaries 2026: gold: pubs.usgs.gov
- African Exponent, Top 10 gold producers in Africa in 2025: africanexponent.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Energy and Resources Ltd
 Mwerezi Minerals Company Limited
 Congo Mining Solutions
 Mining SARL
 SenGold Invest SAS
 Sania Corporation
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL

 Licence holder · Nigeria · Gold + lithium










