

Mining business models · Company facts
Evolution Mining B2B vs B2C: Who Buys Its Gold
Evolution Mining (ASX: EVN) sells only to businesses: gold doré to refiners and copper-gold concentrate to smelters. Below: its FY26 numbers, where the consumer gold market really starts, Agnico Eagle and Freeport compared, smelter charges, and a per-tonne concentrate calculator.
Key takeaways
- Evolution Mining is B2B: doré goes to refiners and copper-gold concentrate to smelters and traders; it reports no consumer sales.
- FY26 (to 30 June 2026): 715 koz gold, 66 kt copper, record statutory profit of A$1,475 million, AISC A$1,717/oz (Evolution FY26 results).
- Consumer gold demand starts at the refiner: Q2 2026 bar and coin demand was 307.1 t and jewellery 278.2 t (World Gold Council).
- Freeport sold 43% of its 2025 mined copper as concentrate, 33% as cathode and 24% as rod, all to businesses (2025 Form 10-K).
- The 2026 copper TC/RC benchmark was set at US$0; spot terms later went below minus US$300 a tonne (Reuters via Kitco).
In this article
- Is Evolution Mining B2B or B2C? The short answer
- Evolution Mining's business model at a glance
- Evolution Mining's products and who buys them
- Where the B2C market for gold really starts
- Evolution Mining vs Agnico Eagle vs Freeport-McMoRan
- Why a miner cannot choose B2C: price-taker economics
- Copper treatment charges: the real negotiation
- Concentrate payability calculator
- How mining companies sell: what B2B marketing looks like
- How to check any miner's B2B or B2C split
- What the business model means for exploration
- Frequently asked questions
Is Evolution Mining B2B or B2C? The short answer
Evolution Mining is a business-to-business (B2B) company. It has no consumer channel. Its revenue comes from two industrial products: gold-silver doré bars sold to precious metals refiners, and copper-gold concentrate sold to smelters and traders. In the year to 30 June 2026 it produced 715,000 ounces of gold and 66,000 tonnes of copper and reported a record statutory net profit of A$1,475 million, all of it from those trade sales (Evolution Mining FY26 results, 19 August 2026).
Nobody buys gold from Evolution Mining with a credit card, and the company does not set its own prices. Its metal is settled against market reference prices, so its business model is that of a price-taker: it decides how much to produce and at what cost, and the market decides what each ounce and tonne is worth.
This page explains the products, the buyers behind each one, where the consumer market really starts, how the same answer applies to Agnico Eagle and Freeport-McMoRan (the two companies most often searched alongside Evolution), and how to check any miner’s business model from its own filings. A concentrate calculator lets you test what a smelter deal is worth per tonne.
A few terms used below: doré is an unrefined bar of mostly gold and silver poured at the mine; concentrate is a damp powder made by grinding and floating ore, holding much more metal than the rock it came from; a smelter melts concentrate to make metal; AISC (all-in sustaining cost) is the cost of producing an ounce including sustaining capital, royalties and overheads; and an offtake agreement is a contract under which a buyer agrees to take a mine’s output over a set period.
Evolution Mining’s business model at a glance
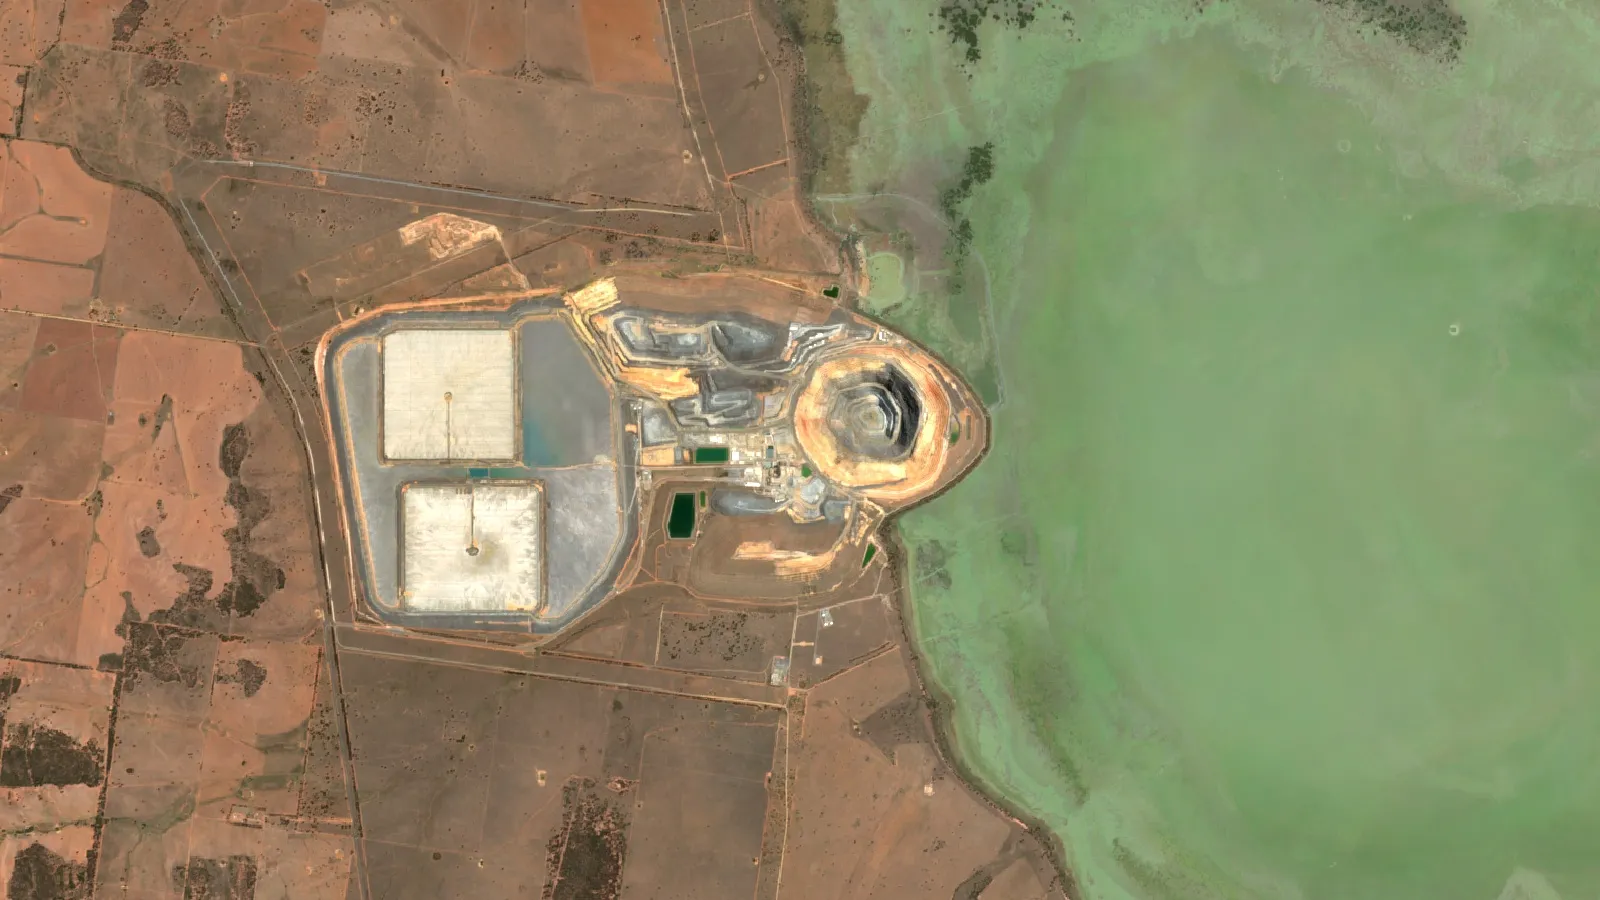
Evolution Mining Limited is listed on the Australian Securities Exchange as ASX: EVN. Its FY26 results list its operations as Cowal in New South Wales, Ernest Henry and Mt Rawdon in Queensland, Mungari in Western Australia, Red Lake in Ontario, Canada, and an 80% share of Northparkes in New South Wales. Mt Rawdon was processing its last low-grade stockpiles in the September 2026 quarter, according to the same release.
Australia mined an estimated 280 tonnes of gold in 2025, out of a world total of about 3,300 tonnes, and Evolution is one of its larger producers (USGS Mineral Commodity Summaries 2026, gold). Its 715,000 ounces in FY26 equal about 22 tonnes.
Those mines turn rock into two kinds of product, and each kind has its own buyer:
- Gold doré from the gold mills (Cowal, Mungari, Red Lake and Mt Rawdon), sold to refiners.
- Copper concentrate carrying gold from Ernest Henry and Northparkes, sold to smelters or traders who place it with smelters.
Every step of the model faces another business. The company reports its results to investors in ounces, tonnes, cost per ounce and achieved price, which is how a commodity producer measures itself. There is no customer count, no retail revenue line and no marketing spend figure in the results, because there is nothing to report in those categories.
For FY26 the company reported an achieved gold price of A$6,023 an ounce (FY25: A$4,300), an achieved copper price of A$18,051 a tonne (FY25: A$14,470), AISC of A$1,717 an ounce (FY25: A$1,572) and record Group cash flow of A$1,389 million. It ended June 2026 with A$1,347 million of cash against A$1,329 million of debt, a small net cash position. Its FY27 guidance is 660,000 to 730,000 ounces of gold and 63,000 to 70,000 tonnes of copper at AISC of A$1,795 to A$1,995 an ounce.
Evolution Mining’s products and who buys them
Doré: from mine to refinery
At the gold mills, gold is recovered from crushed ore and poured on site into doré bars. A doré bar is not a product anyone can use as it is. It goes to a precious metals refinery, which assays (measures) the gold and silver content, refines it to market purity and credits the metal to an account. The refiner, or the bullion bank that holds the metal account, is the customer. Each shipment is one transaction with one institution, priced against the gold market rather than a negotiated retail price.
Infographic
From pit to consumer in 5 steps
- 1MineOre is mined and milled at sites such as Cowal or Ernest Henry.
- 2Doré or concentrateGold is poured as doré; copper ore becomes concentrate.
- 3Refiner or smelterThe miner’s customers: they refine or smelt the product.
- 4Mint, mill or makerCoins, bars, rod, wire and jewellery are made.
- 5ConsumerHouseholds buy finished products, never from the mine.
Copper concentrate: from mine to smelter
Ernest Henry, near Cloncurry in Queensland, and Northparkes, near Parkes in New South Wales, produce copper concentrate that also carries payable gold. Concentrate usually holds roughly 20% to 30% copper. Only a smelter can turn it into metal, so the buyers are smelters or traders who sell on to smelters, usually under multi-year offtake contracts.
The price of concentrate is not simply the copper price. A smelter pays for a share of the contained metal (the “payable” share), then deducts a treatment charge per dry tonne of concentrate and a refining charge per pound of payable copper. Those two charges are known together as TC/RCs and are the main point negotiated between miners and smelters.
Evolution has been adding copper. On 27 July 2026 it announced the acquisition of Carnaby Resources to expand copper growth options near Ernest Henry, according to its FY26 results. More copper means more of its sales follow the smelter model rather than the refiner model, but both are B2B.
The full chain from pit to consumer
| Step | Product | Buyer | Type of sale |
|---|---|---|---|
| Gold mine (Evolution, Agnico Eagle) | Doré bar | Precious metals refiner or bullion bank | B2B, priced against the gold market |
| Copper mine (Ernest Henry, Northparkes, Freeport) | Copper concentrate | Smelter or concentrate trader | B2B, offtake with TC/RC deductions |
| Smelter and refinery | Copper cathode | Rod mills, brass mills | B2B, exchange price plus premium |
| Rod mill | Copper rod | Wire and cable makers | B2B, conversion contracts |
| Refiner, mint, jeweller, manufacturer | Coins, bars, jewellery, products containing copper wire | Households and retail investors | B2C starts here, three to five steps from the mine |
Where the B2C market for gold really starts
The question “is Evolution Mining B2B or B2C” comes up because gold has a large, visible consumer market. It does, but not at the mine gate. In the second quarter of 2026 the World Gold Council recorded 307.1 tonnes of bar and coin demand and 278.2 tonnes of jewellery consumption, within total demand (including over-the-counter trade) of 1,269 tonnes. Central banks bought about 289 tonnes in the same quarter (World Gold Council, Gold Demand Trends Q2 2026).
Chart
Global gold demand by buyer type, Q2 2026
Tonnes in the quarter, selected demand categories (ETFs and OTC excluded)
Every ounce in the bar, coin and jewellery categories passed through a refiner and then a mint, fabricator or retailer before a consumer touched it. Central banks buy in the wholesale market, not from mine sites. Mine supply in the quarter was 965.6 tonnes, and it entered that chain as doré and concentrate.
So the accurate wording is: Evolution Mining’s gold eventually reaches consumers, but none of Evolution Mining’s revenue comes from consumers. Even the most retail-looking end of the market, a coin from a national mint, is a B2B relationship for the miner, because the refiner or mint is the customer.
The World Gold Council updates these figures every quarter, so check its latest Gold Demand Trends report for a newer quarter.
Evolution Mining vs Agnico Eagle vs Freeport-McMoRan
All three companies give the same answer to the B2B or B2C question. What differs is how far each one goes down the chain.
Chart
How Freeport sold its mined copper in 2025
% of mined copper by product form
Agnico Eagle
Agnico Eagle Mines (NYSE and TSX: AEM) is a Canadian gold producer. It produced 3,447,367 ounces of payable gold in 2025 at AISC of US$1,339 an ounce, on an average realised gold price of US$3,453 an ounce, and reported record cash generation, with US$6,817 million of cash from operating activities. It forecasts payable production of about 3.3 to 3.5 million ounces a year from 2026 to 2028 (Agnico Eagle Q4 and full year 2025 results, 12 February 2026). Its output is gold doré and gold-bearing concentrate, with by-product silver, zinc and copper, sold to refiners and smelters. Its results contain no consumer segment and no retail revenue line.
Freeport-McMoRan
Freeport-McMoRan (NYSE: FCX) reported consolidated revenues of US$25.9 billion in 2025. Its 10-K says revenue “primarily” comes from copper concentrate, copper cathode and copper rod, plus gold and molybdenum. In 2025, 43% of its mined copper was sold as concentrate, 33% as cathode and 24% as rod (Freeport-McMoRan 2025 Form 10-K).
Freeport goes further down the chain than Evolution. It runs a copper smelter and rod mill in Miami, Arizona, a refinery and rod mill in El Paso, Texas, and owns Atlantic Copper, a smelting and refining business in Spain. Rod is the input wire and cable makers use. That is vertical integration, but every buyer is still a business: smelters, cathode users and wire and cable manufacturers.
Side-by-side comparison
| Company | Main products | Who buys | Consumer sales | Latest full-year figures |
|---|---|---|---|---|
| Evolution Mining (ASX: EVN) | Gold-silver doré; copper-gold concentrate | Refiners; smelters and concentrate traders | None reported | FY26 (to 30 June 2026): 715 koz gold, 66 kt copper, A$1,475m statutory profit |
| Agnico Eagle (NYSE/TSX: AEM) | Doré and gold concentrate; by-product silver, zinc, copper | Refiners, bullion banks, smelters | None reported | 2025: 3,447,367 oz payable gold, AISC US$1,339/oz |
| Freeport-McMoRan (NYSE: FCX) | Concentrate, cathode, copper rod, gold, molybdenum | Smelters, rod and brass mills, wire and cable makers | None reported | 2025: US$25.9bn revenue; copper sold 43% concentrate, 33% cathode, 24% rod |
For wider rankings, see our lists of the top 20 gold mining companies by output and the largest copper mining companies ranked by output.
Why a miner cannot choose B2C: price-taker economics
A consumer business sets a price and defends its margin with a brand. A miner cannot. The price of an ounce or a tonne is set in the market, and the only things management controls are how much it produces and what each unit costs. That is why miners’ investor reports are built around cost per ounce rather than customers.
Chart
Evolution Mining achieved gold price vs AISC
A$ per ounce, financial years to 30 June
Evolution’s own numbers show the pattern. Between FY25 and FY26 its achieved gold price rose 40%, from A$4,300 to A$6,023 an ounce, while AISC rose 9%, from A$1,572 to A$1,717. The record profit came from the market price, with cost control keeping most of the gain. Nothing in that result came from winning customers.
Agnico Eagle’s 2025 figures make the same point: a realised price of US$3,453 an ounce against AISC of US$1,339. The gap between those two numbers is the whole commercial case. If you want to compare margins across metals, our guide to mining profitability and AISC by metal sets them side by side.
Prices keep moving. On 28 October 2026 gold traded at about US$4,046 an ounce and copper at about US$6.62 a pound, roughly US$14,600 a tonne (Trading Economics, gold; Trading Economics, copper). Neither Evolution nor any other miner set those figures.
Provisional pricing: how a mine invoice really works
Concentrate and cathode are usually sold on provisional prices. Freeport’s filings explain that the final price is set in a future month, generally one to four months after shipment, based mainly on the average London Metal Exchange (LME) settlement price for that month. The company invoices at the then-current price and adjusts later (Freeport-McMoRan second-quarter 2026 results). No consumer would accept a price that is fixed months after the sale; only industrial buyers trade this way.
Copper treatment charges: the real negotiation
If there is any real bargaining in mining B2B, it happens over smelter charges. Traditionally the miner pays the smelter to process its concentrate. In December 2025 Antofagasta and a Chinese smelter agreed the 2026 benchmark treatment and refining charges at US$0 a tonne and 0 cents a pound, against US$21.25 a tonne and 2.125 cents a pound for 2025, because mine supply was short (Kitco/Reuters, 19 December 2025).
Spot terms then moved below zero, meaning smelters paid miners to secure concentrate. In October 2026 Reuters reported that Antofagasta had been paid more than US$300 a tonne in recent tenders, and that Teck sold Highland Valley concentrate at treatment charges in the minus US$370s, as talks on 2027 terms began (Kitco/Reuters, 16 October 2026).
For a copper-gold producer like Evolution, that shift changes how much of the exchange value it keeps. It is a good example of B2B power: when there are few qualified buyers and few sellers, terms swing with supply, not with branding.
Concentrate payability calculator
Use the calculator below to estimate what one dry tonne of copper concentrate is worth to the seller after the smelter’s charges. Enter your own grade, payable share, copper price and TC/RC terms. A negative treatment charge (smelter pays the miner) can be entered as a negative number.
The calculator covers copper only. Gold and silver credits, penalty elements such as arsenic, moisture, freight, insurance and quotational-period adjustments are left out, and each of them changes the answer.
Calculator
What is a dry tonne of copper concentrate worth after smelter charges?
Enter your own grade, payable share, copper price and TC/RC terms.
- Gross copper value per tonne, US$: $3,650
- Payable copper value, US$: $3,504
- Total smelter charges, US$: $0
- Payable copper, lb per tonne: 529
Example values only, not a benchmark. Copper only: gold and silver credits, penalties, moisture, freight and quotational-period changes are excluded. The copper price is an example, use today’s price (Trading Economics showed about US$6.62/lb, roughly US$14,600/t, on 28 October 2026). The 2026 benchmark TC/RC was US$0/t and 0 c/lb (Reuters via Kitco, December 2025); spot terms have since been negative. 1 tonne = 2,204.62 lb.
How mining companies sell: what B2B marketing looks like
People who search for mining B2B marketing often expect the usual toolkit: funnels, lead generation and brand campaigns. Large miners use almost none of it, and seeing why makes the business model clearer.
- The customer list is short. There are a limited number of copper smelters and accredited gold refiners in the world. Relationship management replaces lead generation, and a commercial team may deal with fewer counterparties in a year than a software company signs in a week.
- The specification is the pitch. Concentrate is sold on its assay: copper grade, gold and silver credits and penalty elements. A cleaner concentrate wins better terms. That assay sheet, not a brochure, is the sales document.
- Investor relations carries the brand. The audience being persuaded is the capital market. Results releases, quarterly reports, guidance and reserve statements are the public communication programme.
- Events are for deals. Industry conferences such as Diggers & Dealers in Kalgoorlie serve as meeting places for offtake, finance and merger talks.
For smaller companies the buyer is often another miner. Selling a project, a licence or a whole operation is also B2B; our guide on how to sell a mine covers valuation, buyer types and deal structures.
How to check any miner’s B2B or B2C split
Every figure on this page will age. This method will not. Use it on Evolution Mining or any other producer.
- Find the revenue note in the annual report. Under IFRS it is usually headed “Revenue from contracts with customers”. It breaks revenue down by metal and often by product (doré or concentrate). A consumer channel would need its own line here.
- Read the customer concentration disclosure. Accounting standards require companies to disclose reliance on major customers. A miner whose sales sit with a small number of refiners, smelters or traders is B2B by definition.
- Check the segment note. Mining segments are named after mines and regions. Consumer businesses segment by channel or customer type.
- Search the filing for “offtake”, “quotational period” and “provisional pricing”. These words only appear in contracts between industrial parties.
- Look at the realised price table. If the company reports an achieved price per ounce or per tonne against a market benchmark, it is a price-taker selling into a market.
- Check where the company stops in the chain. Freeport sells rod; Evolution sells doré and concentrate. Neither reaches a household.
Evolution’s reports sit on its ASX announcements page; Agnico Eagle files with SEDAR+ and the US SEC as a Form 40-F filer; Freeport files a Form 10-K with the US SEC. Our list of US copper mining companies ranked by US output shows the same structure across other American producers.
▶ Remote sensing for mining explained in plain words: the six instrument families. · 2:01
What the business model means for exploration
Because a miner cannot raise its price, its long-term value rests on finding and proving ounces and tonnes at a competitive cost. Evolution says drilling has started at Two Times Fred in British Columbia and at Corella near Ernest Henry, according to its June 2026 quarterly report (Evolution Mining June 2026 quarterly report).
For consultants and licence holders, satellite imagery is one low-cost way to narrow a large tenement to ranked targets before a drill rig is booked. Multispectral data can map alteration minerals and structures across the whole area with no ground disturbance, which helps decide which licence deserves a field season. Farmonaut offers satellite-based mineral detection; to scope an area you can use the mining query form or contact the team.
▶ What an AI mining app really does: find places to look, plan the mine, run it. · 3:52
Frequently asked questions
Is Evolution Mining B2B or B2C?
B2B. It sells gold-silver doré to refiners and copper-gold concentrate to smelters and traders. It reports no retail or direct-to-consumer revenue.
What is Evolution Mining’s business model?
It is a mid-tier gold and copper producer that mines ore in Australia and Canada, processes it to doré or concentrate and sells it to industrial buyers at market-linked prices. Profit depends on volume, grade and cost per ounce, not on pricing power.
Does Evolution Mining sell gold to the public?
No. Retail bars and coins come from refiners and mints that buy refined metal. Evolution’s doré is an unrefined alloy that must be assayed and refined first.
Who are Evolution Mining’s customers?
By type: precious metals refiners for doré, and copper smelters or concentrate traders for Ernest Henry and Northparkes concentrate. Any reliance on major customers is disclosed in the notes to its annual financial report.
Which mines does Evolution Mining own?
Its FY26 results list Cowal (NSW), Ernest Henry and Mt Rawdon (Queensland), Mungari (Western Australia), Red Lake (Ontario, Canada) and an 80% share of Northparkes (NSW). Mt Rawdon was finishing low-grade stockpiles in the September 2026 quarter.
Is Agnico Eagle B2B or B2C?
B2B. Agnico Eagle sells doré and concentrate to refiners and smelters and reports no consumer segment.
Is Freeport-McMoRan B2B or B2C?
B2B. Freeport sells concentrate, cathode and copper rod to smelters, mills and wire and cable makers. It owns smelting and rod-making steps, but its buyers are all businesses.
How does Agnico Eagle buy goods and services?
Its purchasing is B2B as well: a large miner buys equipment, fuel, explosives, reagents and contract services from other businesses for each operation. Mining is B2B on both the buying side and the selling side.
How do treatment and refining charges change what a miner receives?
They turn an exchange price into a net payable amount. The smelter pays for a share of the contained metal, then deducts a charge per dry tonne and a charge per payable pound. When charges are negative, as in late 2026 spot deals, the smelter pays the miner instead.
Why does B2B vs B2C matter to an investor or analyst?
It shows where the risk sits. A B2B commodity producer has no pricing power and no customer churn; its risks are price, volume, grade, cost inflation and counterparty risk. That is why analysts focus on AISC and realised price.
This page describes how these companies sell their products, using their published reports. It is not investment advice and makes no recommendation to buy or sell any security. Company figures and prices change; check the latest filings.
Farmonaut mining
Map your mining site from space
Consultants use Farmonaut to map alteration and structure across a client's licence, so field and drilling budgets go to the strongest targets first.

Mining Pro sample view, synthetic data
Keep reading
Sources
- Evolution Mining, FY26 full year financial results and final dividend (19 August 2026): announcements.asx.com.au
- Evolution Mining, June 2026 quarterly report: yourir.info
- World Gold Council, Gold Demand Trends Q2 2026: gold.org
- Agnico Eagle, fourth quarter and full year 2025 results (12 February 2026): s205.q4cdn.com
- Freeport-McMoRan, 2025 Annual Report on Form 10-K: s22.q4cdn.com
- Freeport-McMoRan, second-quarter 2026 results (23 July 2026): s22.q4cdn.com
- Kitco/Reuters, Antofagasta agrees zero copper processing charges for 2026 (19 December 2025): kitco.com
- Kitco/Reuters, Antofagasta nets its highest ever copper treatment charges in auction (16 October 2026): kitco.com
- Trading Economics, gold price (28 October 2026): tradingeconomics.com
- Trading Economics, copper price (28 October 2026): tradingeconomics.com
- USGS, Mineral Commodity Summaries 2026: Gold: pubs.usgs.gov
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Klusetic Mining Investments
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited











