

Reviewed September 2026 against USDA Farm Service Agency and USDA National Agricultural Statistics Service (NASS) data.
Try it: Run your own numbers →
Agriculture Loans Rates: Financing Big Sandy Forestry and Big Timber Farming
As of the March 2025 USDA Farm Service Agency (FSA) rate announcement, the Direct Farm Operating Loan monthly rate stood at 5.50% and the Direct Farm Ownership Loan monthly rate stood at 5.88% — both up from 4.50% and 5.13% respectively in November 2024. There is no separate federal “forestry loan” or “timber loan” rate: producers in Big Sandy, Montana; Big Timber, Montana; and Giddings, Texas finance timberland through the same FSA and Farm Credit System channels used for row-crop and livestock operations, layered with timber-specific underwriting. This page breaks down what those rates actually are, where to check them monthly, and how forestry financing differs from standard farm credit.
Current Agriculture Loan Rates: USDA FSA Direct Loans
USDA’s Farm Service Agency publishes Direct Loan interest rates monthly, typically between the 1st and 3rd of the month, covering Farm Operating Loans, Farm Ownership Loans, Emergency Loans, Commodity Loans, and Storage Facility Loans. These are the base rates against which most agriculture loan quotes — including those referenced by lenders serving Big Sandy and Giddings — get compared.
- November 1, 2024 announcement: Direct Farm Operating Loan monthly rate 4.50%; Direct Farm Ownership Loan monthly rate 5.13%, per the USDA FSA November 2024 lending rates release.
- March 3, 2025 announcement: Direct Farm Operating Loan monthly rate rose to 5.50%; Direct Farm Ownership Loan monthly rate rose to 5.88%, per the USDA FSA March 2025 lending rates release.
That’s a 100-basis-point move on the Operating Loan rate and a 75-basis-point move on the Ownership Loan rate in the four months between those two releases. Rates move with Treasury yields underlying the FSA formula, so a rate quoted in one month can be stale within weeks — there is no way around checking the current release before you apply.

Forestry Loans and Timber Loans: How They’re Actually Financed
There is no USDA-published “forestry loan rate” or “timber loan rate” distinct from general farm credit — federal lending statistics don’t break timber and forest operations out as their own category. Forestry and timberland financing runs through the same instruments as farm lending, with underwriting adjusted for the asset:
- Long-Dated Amortization: Timberland loans commonly run 15–30 years, matched to growth and harvest cycles rather than a single crop year.
- Underwriting on Physical and Biological Value: Appraisals weigh site productivity, species mix, stocking, and growth models rather than a single season’s yield.
- Programs Aimed at Timber Specifically: The USDA Forest Service and state forestry agencies operate the Timber Production Expansion Guaranteed Loan Program in some states, where the loan guarantee comes from the program but the interest rate is negotiated directly between the borrower and the participating lender — it is not a published federal rate, so there is no single number to quote here.
- Staggered Draw Schedules: Credit for road construction or milling upgrades is often released against completed milestones rather than disbursed in full at closing.
- Environmental and Harvest Covenants: Lender agreements frequently tie continued access to credit to annual harvest limits, reforestation commitments, and sustainable-management documentation such as FSC or SFI certification.
If you need a timber-specific rate quote, the honest answer is that you have to call a lender active in forestry finance directly — a regional Farm Credit association, a USDA Forest Service state office, or a commercial ag lender with a timberland desk — because no agency publishes one centrally.

Agriculture Loans in Big Sandy, MT and Giddings, TX: What’s Local and What Isn’t
Searches for “agriculture loans Big Sandy MT” and “agriculture loans Giddings” are looking for a county- or town-level rate, and it’s worth being direct about what exists: neither USDA nor the Federal Reserve publishes lending rates or loan volume broken out by county or town. Rate and volume data is published at the state level (NASS) and at the Federal Reserve district level (Kansas City Fed for Montana, Dallas Fed for Texas) — Big Sandy, Big Timber, and Giddings borrowers use the same national FSA rate schedule and the same regional Farm Credit associations as the rest of their states.
What is specific to the region:
- Montana forest land base: Montana carries 14.6 million acres of privately owned forest land, per the USDA NASS Montana 2024 Annual Statistical Bulletin. That acreage is the collateral base local lenders in Big Sandy and Big Timber are appraising against when they underwrite a timberland loan.
- Which office to call: Your county FSA Service Center is the entry point for Direct and Guaranteed loan applications regardless of whether you’re in Chouteau County (Big Sandy), Sweet Grass County (Big Timber), or Lee County (Giddings, Texas) — find your local office through the FSA service center locator.
- What isn’t published: A Big Sandy-specific or Giddings-specific interest rate does not exist as a discrete figure. If a lender quotes you a “local rate,” it is their own pricing built on the national FSA or Farm Credit baseline plus their assessment of your operation — ask them to show you how it was built.
Farm Credit System: Volume, Growth, and Where Rates Come From
The Farm Credit System — the network of borrower-owned lending cooperatives that includes the associations serving Montana and Texas — held a total loan portfolio of $456.9 billion in 2025, according to reporting on Farm Credit System data by Capital Press. That figure reflects a system where loan volume has grown even as the number of individual lending institutions has consolidated — relevant context if you’re comparing a large regional Farm Credit association’s offer against a smaller community bank’s.
What this means when you’re shopping a timberland or farm loan: Farm Credit associations price loans individually, at the local association level, using their own cost of funds and the borrower’s collateral and cash flow — there is no single national “Farm Credit rate” published the way FSA publishes its Direct Loan rates. Expect variation between the association serving north-central Montana and the one serving central Texas, and ask each for a written rate sheet rather than relying on a verbal quote.
What Lenders Look For in Timber and Farm Financing
Whether you’re applying through FSA, a Farm Credit association, or a commercial ag lender, underwriting for agriculture and timberland loans converges on the same core categories:
- Management Plans: Sustainability certification status, harvest schedules, yield projections, and cash flow models.
- Asset Quality: Land appraisals anchored in current value, site productivity, road infrastructure, and processing access.
- Species Mix and Diversity: Diversified crop and timber portfolios reduce concentration risk in a lender’s eyes.
- Debt Serviceability: Repayment plans stress-tested against realistic harvest windows and price volatility.
- Insurance and Risk Tools: Crop and hazard insurance integrated with any government buffer programs.
- Compliance and Traceability: Documentation of origin and environmental impact is increasingly requested, particularly for export-oriented wood products.
Loan Type Comparison: Rates, Terms, and What Sets Each Apart
This table separates the one federally published rate series (FSA Direct Loans) from the products where rates are lender-negotiated and not centrally published. Treat the “negotiated” rows as a starting point for a conversation with your lender, not a quote.
| Loan Type | Rate Basis | Latest Published Rate | Typical Term | Where Published |
|---|---|---|---|---|
| FSA Direct Farm Operating Loan | Federal statutory formula, published monthly | 5.50% (Mar 2025) | 1–7 years | USDA FSA |
| FSA Direct Farm Ownership Loan | Federal statutory formula, published monthly | 5.88% (Mar 2025) | Up to 40 years | USDA FSA |
| FSA Guaranteed Farm Loans | Negotiated with participating lender, FSA guarantees a portion | Not centrally published — lender-set | Varies by loan purpose | Ask your FSA-approved lender directly |
| Farm Credit System loans | Negotiated at the local association level | Not centrally published — association-set | Varies; timberland terms run 15–30 years | Ask your regional Farm Credit association |
| Timber Production Expansion Guaranteed Loan | Negotiated between borrower and participating lender; program provides the guarantee only | Not published — no fixed rate set by the program | Long-dated, matched to harvest cycle | USDA Forest Service / participating state forestry agency |
Data Note: The FSA rows are the only two lines in this table with a nationally published, dated figure. Every other row is priced by the individual lender — get a written quote before comparing.

Satellite Monitoring and Loan Applications: What It Can and Can’t Do
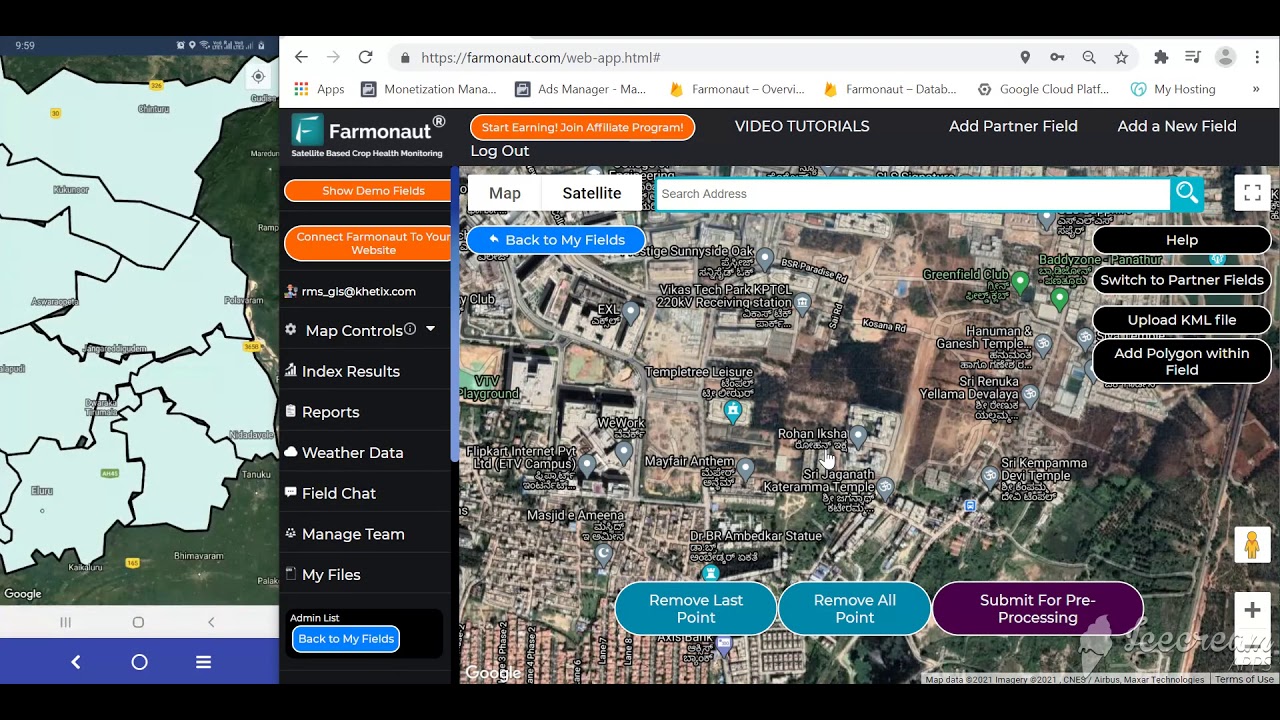
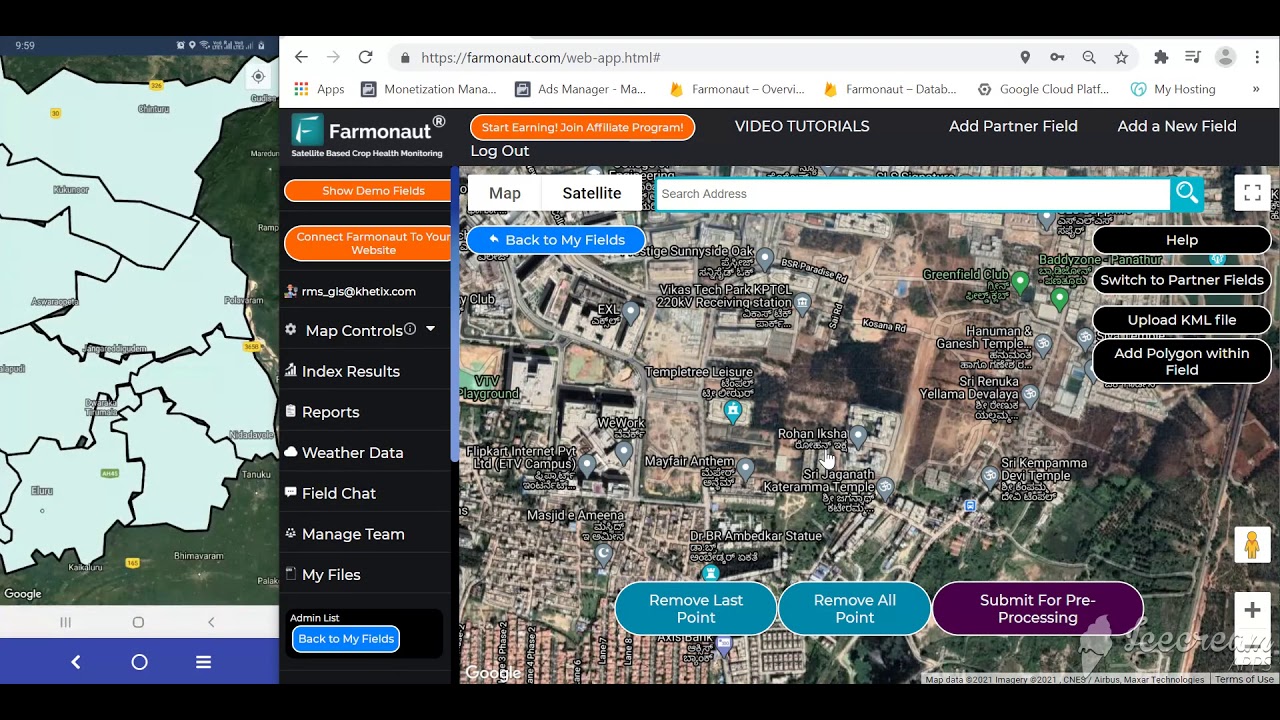
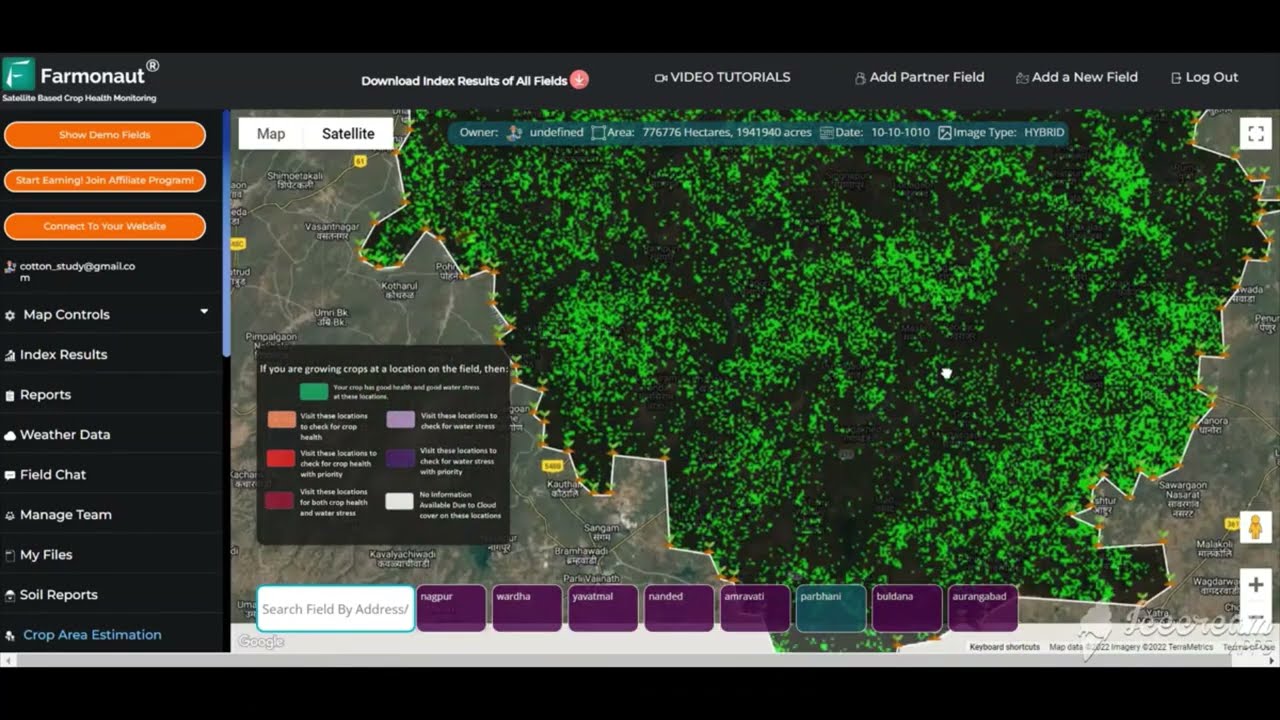
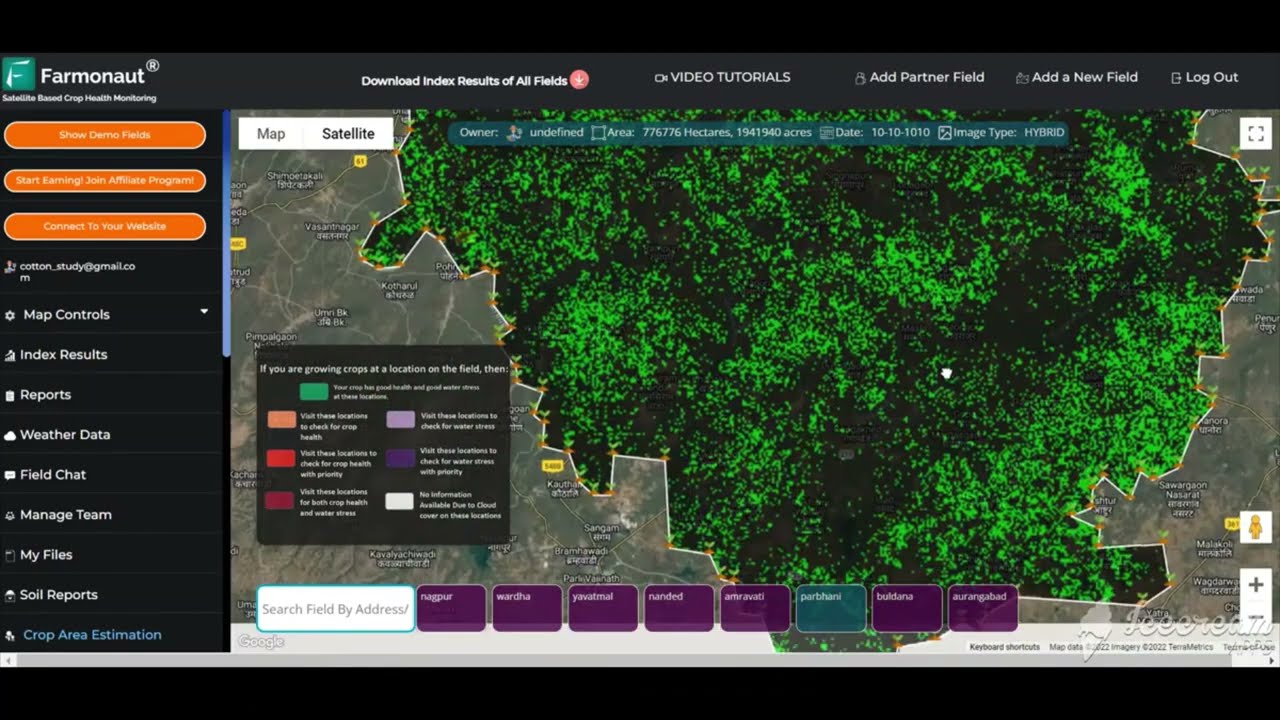
Satellite and AI-based monitoring tools don’t change your interest rate, but they change what you can document when you apply — and documentation quality is one of the underwriting criteria listed above. Farmonaut’s tools relevant to a forestry or farm loan application include:
- Real-time crop and forest monitoring with multispectral satellite imagery — vegetation health (NDVI), soil moisture, and harvest forecasting data a lender can review alongside your management plan.
- AI-driven advisory through Jeevn AI, generating operational strategies that support the cash-flow projections a loan application needs.
- Blockchain-based traceability (see: Traceability Solution): documents product origin — relevant for certified wood export and sustainability-linked loan covenants.
- Environmental impact monitoring (Carbon Footprinting): quantifies carbon emissions or sequestration, which is the documentation basis behind sustainability-linked loan pricing where lenders offer it.
- Fleet and resource management (Fleet Management Tools): tracks vehicle and equipment usage relevant to processing and infrastructure loan applications.
Our satellite-based verification also supports financial institutions directly through Crop Loan & Insurance Verification, giving lenders an independent data source for loss verification and collateral checks. The Large Scale Farm Management Platform is built for operations managing mixed crop and timberland portfolios — exactly the profile most Big Sandy and Big Timber applicants have.




Timberland Loan Payment Calculator
Use your own principal, an FSA-published or lender-quoted rate, and a term within the 15–30 year range typical for timberland loans to estimate a monthly payment before you apply.
Run your own numbers
How to Get the Current Rate — Every Month
Because every rate figure in this article has a publication date attached, here is the durable part: the method for getting a number that's newer than ours, whenever you're reading this.
- FSA Direct Loan rates: Published monthly, 1st–3rd of the month, at fsa.usda.gov/news-events/news. Subscribe to FSA news releases or check this page directly before applying — do not rely on a rate quoted in any article, including this one, without confirming the current release.
- Farm Credit System lending activity: The Federal Reserve Bank of Kansas City surveys agricultural lenders quarterly and publishes "Growth in Farm Lending Activity" updates, typically about 60 days after each quarter-end.
- Montana forest and farmland statistics: NASS publishes the Montana Agricultural Statistics Annual Bulletin each fall; find the current and prior editions at nass.usda.gov/Statistics_by_State/Montana.
- Timber Production Expansion Guaranteed Loan Program rate quotes: Not published anywhere centrally — call a participating lender in your state directly and ask for a current quote against your specific timberland asset.
Frequently Asked Questions
-
What is the current agriculture loan interest rate?
USDA FSA's Direct Farm Operating Loan monthly rate was 5.50% and the Direct Farm Ownership Loan monthly rate was 5.88% as of the March 2025 announcement. FSA republishes these rates monthly at fsa.usda.gov/news-events/news — check that page for the current figure rather than relying on any past announcement. -
Is there a separate "forestry loan" or "timber loan" interest rate?
No. Federal lending data does not track forestry or timber loans as a category distinct from general farm credit. Timberland financing uses the same FSA and Farm Credit System products, with rates on guaranteed programs like the Timber Production Expansion Guaranteed Loan Program negotiated directly between borrower and lender rather than published centrally. -
Are agriculture loan rates different in Big Sandy, MT or Giddings, TX?
No county- or town-level rate is published by USDA or the Federal Reserve. Borrowers in both towns use the same national FSA rate schedule; any "local rate" you're quoted is a lender's own pricing, not a distinct published figure. -
How large is the Farm Credit System, and does its size affect my rate?
The Farm Credit System held a $456.9 billion total loan portfolio in 2025, per Capital Press reporting on system data. System-wide size doesn't set your individual rate — that's negotiated at your local association — but it indicates the scale of competition and capital available in the market. -
How much forest land does Montana have, and why does that matter for a loan?
Montana has 14.6 million acres of privately owned forest land, per the USDA NASS Montana 2024 Annual Statistical Bulletin. That's the collateral base lenders draw on when appraising timberland loans in Big Sandy and Big Timber specifically. -
What role does Farmonaut's technology play in securing agriculture or timber loans?
Satellite-enabled verification, crop and woodland monitoring, and AI-based risk assessments improve the documentation quality of a loan application and support ongoing compliance reporting for both lenders and borrowers — they don't change the published rate itself.





Final Thoughts
The honest picture: there is one nationally published, dated rate series relevant to agriculture and forestry borrowing — USDA FSA's Direct Loan rates, which moved from 4.50%/5.13% (Operating/Ownership) in November 2024 to 5.50%/5.88% in March 2025. Everything else — Farm Credit System pricing, Timber Production Expansion Guaranteed Loan Program terms, and any "local" rate quoted in Big Sandy, Big Timber, or Giddings — is negotiated between you and a specific lender and isn't published centrally. That's not a gap in this article; it's the actual structure of how these loans are priced.
The durable move is the checklist, not a specific number: pull the current FSA release before you apply, get a written quote from your Farm Credit association or commercial lender rather than a verbal estimate, confirm your state's Timber Production Expansion Guaranteed Loan Program terms directly with a participating lender, and bring documented, satellite-verified operational data to strengthen your application regardless of which product you choose.
Quick Checklist Before You Apply
- ✔ Pulled the current-month FSA Direct Loan rate release, not a cached figure
- ✔ Requested a written rate quote from at least one Farm Credit association and one commercial lender
- ✔ Confirmed whether the Timber Production Expansion Guaranteed Loan Program is active with a lender in your state
- ✔ Documented management plan, harvest schedule, and sustainability certification status
- ✔ Assembled seasonal and multi-year cash flow forecasts
- ✔ Compiled satellite or remote-monitoring data to support the application
Interested in streamlined, tech-powered forestry or agriculture financing documentation? Experience our platform today and access satellite insights for field, forest, and finance.

 CGIAR
 Hayleys Agriculture
 Linx Agritech
 Adinet
 Save Your Soils
 GalaxEye Space
 Grandstream Algérie
 XOS Realty
 Geospatial Lab Africa
 Agro La Gándara
 HIPSAC
 ZOL Zimbabwe
 Juligerm
 AdBio
 MISE Maroc
 NWNS
 Red August Group
 Farm Inc
 WeMe Global

