

Lithium · Company comparison
Lithium Mining Companies: 13 Listed Names Compared
SQM, Albemarle and Rio Tinto lead listed lithium miners in LCE terms, while PLS and Mineral Resources lead Australian spodumene output. Compare 13 companies by ticker, mines and latest reported volume, with filings dated 2026.
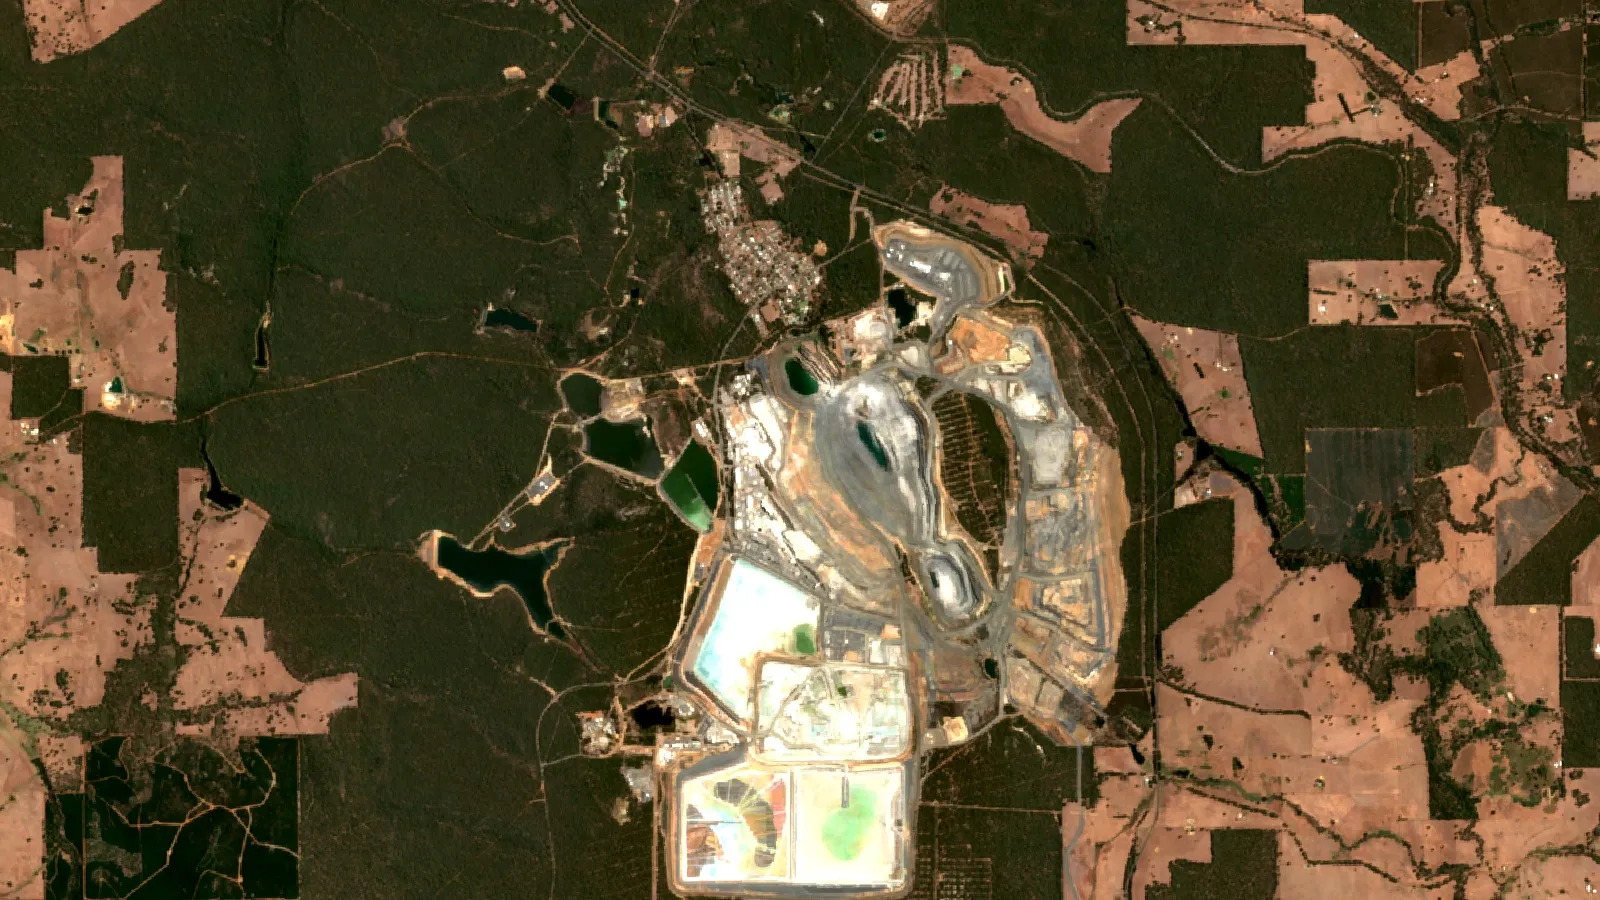
Key takeaways
- SQM sold over 84 kt LCE and Albemarle 65 kt LCE in the second quarter of 2026 (company results, August 2026).
- PLS produced a record 267.6 kt of spodumene concentrate in the September 2026 quarter; MinRes produced 166 kt SC6 attributable (ASX reports, October 2026).
- Livent, Arcadium and Piedmont no longer trade: their assets now sit with Rio Tinto and Elevra Lithium; Pilbara Minerals is now PLS.
- World lithium mine output was about 290,000 t in 2025, led by Australia at 92,000 t (USGS, 2026).
- China’s lithium carbonate price was CNY 90,650/t on 12 November 2026 (Trading Economics). This page is not investment advice.
In this article
- Lithium mining companies ranked by latest reported output
- How we chose and ranked these lithium stocks
- The biggest lithium mining companies compared
- Diversified majors: SQM, Albemarle and Rio Tinto
- Australian spodumene producers: PLS, Mineral Resources, IGO and Liontown
- Chinese-listed lithium miners: Ganfeng and Tianqi
- Mid-size and US-listed producers and developers
- Old lithium stock names that no longer trade
- Where the world's lithium is mined
- Lithium prices and what they mean for miners' revenue
- Calculator: spodumene output to revenue
- How to evaluate lithium mining stocks before you buy
- Where satellite screening fits for lithium projects
- Frequently asked questions
Lithium mining companies ranked by latest reported output
The largest listed lithium mining companies by reported volume are SQM, Albemarle, Rio Tinto and the Australian spodumene miners PLS and Mineral Resources. SQM sold more than 84,000 tonnes of lithium carbonate equivalent (LCE) in the second quarter of 2026, a record for the company (SQM, 19 August 2026), and Albemarle sold 65,000 tonnes LCE in the same quarter (Albemarle, second-quarter 2026 results). PLS produced a record 267,600 tonnes of spodumene concentrate in the quarter to 30 September 2026 (PLS September 2026 quarterly report).
This page compares 13 listed lithium mining companies: what each one mines, where, on which stock exchange, and what its latest report shows. It also flags the old ticker names that no longer trade, shows the country and price data behind every lithium stock, and gives a calculator for turning a miner’s output into revenue at your own price. It states facts from company filings and is not investment advice.
Two units appear throughout. LCE (lithium carbonate equivalent) is the tonnage of lithium carbonate a product would make, so brine and chemical producers can be compared. Spodumene concentrate is the crushed and upgraded hard-rock mineral that Australian, Brazilian and Canadian mines sell; “SC6” means concentrate with 6% lithium oxide (Li2O). Roughly, several tonnes of SC6 are needed to make one tonne of LCE, so a concentrate tonnage always looks larger than an LCE tonnage for the same lithium.
How we chose and ranked these lithium stocks
We included listed companies that either run a producing lithium mine or brine operation, or are building a mine that already has full construction funding. Each company must publish production in English-language quarterly or annual reports. We checked every name, ticker and owner against the company’s own filings from 2025 and 2026, because this sector has merged and renamed several companies in two years.
The order follows the latest reported lithium volume, but the units differ. Brine and chemical producers (SQM, Albemarle, Rio Tinto, Lithium Argentina) report tonnes LCE. Hard-rock miners (PLS, Mineral Resources, IGO’s Greenbushes interest, Liontown, Sigma, Elevra) report tonnes of spodumene concentrate. Ganfeng and Tianqi report mainly in Chinese-format annual reports, so we show their main assets rather than a quarterly figure. Lithium Americas is a developer with no output yet.
We left out explorers with no funded mine, pure chemical converters that buy all their feed, and battery makers. Share prices and market values are not shown because they change every trading day; check them with your broker on the day you read this.
The biggest lithium mining companies compared
| Company | Main listing (ticker) | Main lithium assets | Latest reported volume |
|---|---|---|---|
| SQM | NYSE: SQM; Santiago | Salar de Atacama brine, Chile (via Nova Andino Litio); Mount Holland, Australia (50%) | Over 84 kt LCE sold, Q2 2026 |
| Albemarle | NYSE: ALB | Greenbushes (49%), Wodgina, Australia; Atacama brine, Chile; Silver Peak, Nevada | 65 kt LCE sold (Energy Storage), Q2 2026 |
| Rio Tinto | ASX, LSE, NYSE: RIO | Olaroz, Fenix, Sal de Vida and Rincon, Argentina; Nemaska, Canada | 27.3 kt LCE produced, H1 2026; 61-64 kt guided for 2026 |
| PLS (formerly Pilbara Minerals) | ASX: PLS | Pilgangoora, Western Australia; Colina, Brazil | 267.6 kt concentrate, September quarter 2026 |
| Mineral Resources | ASX: MIN | Wodgina, Mount Marion, Bald Hill, Western Australia | 166 kt SC6 attributable, September quarter 2026 |
| IGO | ASX: IGO | Minority interest in Greenbushes through Tianqi Lithium Energy Australia | Greenbushes 1,410 kt concentrate, year to June 2026 |
| Tianqi Lithium | SZSE: 002466; HKEX: 9696 | Greenbushes (51% of Talison via TLEA); Kwinana hydroxide plant | See 2025 annual report |
| Ganfeng Lithium | SZSE: 002460; HKEX: 1772 | Cauchari-Olaroz (with Lithium Argentina) and Mariana, Argentina; Goulamina, Mali | See company reports |
| Liontown Resources | ASX: LTR | Kathleen Valley, Western Australia | 103 kdmt concentrate, June quarter 2026 |
| Elevra Lithium | ASX: ELV; Nasdaq: ELVR | North American Lithium, Quebec; Moblan (stake), Quebec | 54.5 kdmt concentrate, June quarter 2026 |
| Sigma Lithium | Nasdaq and TSXV: SGML | Grota do Cirilo, Minas Gerais, Brazil | 35.4 kt concentrate, Q2 2026 |
| Lithium Argentina | NYSE and TSX: LAR | Cauchari-Olaroz, Jujuy, Argentina (with Ganfeng) | 9.28 kt lithium carbonate, Q2 2026 (operation total) |
| Lithium Americas | NYSE and TSX: LAC | Thacker Pass, Nevada (under construction) | No production yet |
Sources: each company’s report named in the sections below. kt = thousand tonnes; kdmt = thousand dry metric tonnes.
Diversified majors: SQM, Albemarle and Rio Tinto
SQM (NYSE: SQM)
Sociedad Química y Minera de Chile pumps lithium-rich brine from the Salar de Atacama and concentrates it in evaporation ponds. From 2025 its Atacama business runs through Nova Andino Litio, a joint venture in which state copper miner Codelco holds control (Codelco-SQM partnership). SQM also owns half of Covalent Lithium, which runs the Mount Holland spodumene mine and the Kwinana hydroxide refinery in Western Australia with Wesfarmers. Best for: readers who want a low-cost brine producer with a second business in iodine and plant nutrients. Watch: the Codelco agreement changes how Atacama profits are shared from 2031.
Albemarle (NYSE: ALB)
Albemarle, based in Charlotte, North Carolina, owns 49% of Greenbushes, the large hard-rock mine in Western Australia, plus the Wodgina mine, Atacama brine in Chile and the Silver Peak brine operation in Nevada, the continental brine operation in Nevada that the USGS describes as the only commercial-scale US lithium production (USGS Mineral Commodity Summaries 2026). Its Energy Storage unit sold 65 kt LCE in the second quarter of 2026 at an average realised price of US$19.53 per kg, up from US$12.17 a year earlier. Best for: the widest spread of mines across brine and hard rock. Albemarle also plans to reopen its Kings Mountain mine in North Carolina, which the US Department of Energy reviewed in a final environmental assessment in March 2026. Watch: a fire at Talison’s CGP3 plant on 9 June 2026, which the company said would have minimal effect on volumes.
Rio Tinto (ASX, LSE, NYSE: RIO)
Rio Tinto became a lithium producer when it completed its purchase of Arcadium Lithium in March 2025. Its lithium division runs the Olaroz and Fenix brine operations in Argentina, is building Sal de Vida and Rincon, and controls Nemaska Lithium in Quebec. The company produced 57 kt LCE in 2025 from the date of the acquisition (Rio Tinto fourth-quarter 2025 production results) and 27.3 kt in the first half of 2026, with 2026 guidance of 61 to 64 kt. Lithium is still a small part of Rio’s revenue next to iron ore and copper. Best for: lithium exposure inside a large, diversified miner. Watch: weather at the Argentine salt flats, which slowed evaporation in early 2026.
Australian spodumene producers: PLS, Mineral Resources, IGO and Liontown
Australia mined about 92,000 tonnes of lithium content in 2025, more than any other country (USGS, 2026). Most of it leaves as spodumene concentrate for converters in China, so these companies earn the concentrate price, not the chemical price. For a mine-by-mine view see our list of Western Australian lithium and gold mines.
Chart
Spodumene concentrate output, latest quarter
Thousand tonnes of concentrate; quarters differ (see source); MinRes is attributable mixed grade
PLS (ASX: PLS)
Pilbara Minerals renamed itself PLS Group from 27 November 2025, so older articles use the old name. It owns the Pilgangoora operation in the Pilbara and the Colina project in Brazil. In the September 2026 quarter it produced 267.6 kt of concentrate, sold 223.6 kt at an estimated US$1,809 per tonne (about SC5.2 grade), had unit operating costs of A$539 per tonne and held A$2,217 million in cash. It has taken a final investment decision on the P2000 expansion, aimed at about 2 million tonnes a year of concentrate capacity. Best for: a pure-play spodumene producer with a large cash balance. Watch: all revenue moves with the concentrate price.
Mineral Resources (ASX: MIN)
Mineral Resources (MinRes) mines lithium at Wodgina and Mount Marion and restarted Bald Hill in 2026, alongside its iron ore and mining-services businesses. Its attributable spodumene output was 166 kt SC6 (200 kt at mixed grades) in the September 2026 quarter, up 17% on the prior quarter (MinRes Q1 FY27 report). Bald Hill was ramping towards a design rate of 140 kt a year of SC6. Best for: lithium plus iron ore and services in one stock. Watch: higher debt than the pure lithium producers and an underground move at Mount Marion.
IGO (ASX: IGO)
IGO holds its lithium through a minority stake in Tianqi Lithium Energy Australia, which owns 51% of Talison, the operator of Greenbushes. Greenbushes produced 1,410 kt of spodumene concentrate in the year to June 2026, down from 1,479 kt the year before (IGO 2026 Annual Report). IGO also reports nickel output. Best for: indirect exposure to one of the lowest-cost hard-rock mines. Watch: the joint venture’s Kwinana hydroxide plant has struggled to reach its design rate.
Liontown Resources (ASX: LTR)
Liontown runs the Kathleen Valley mine north of Leinster, which is moving from open pit to underground mining. It produced 103 thousand dry metric tonnes of concentrate in the June 2026 quarter and held about A$561 million in cash at the end of the quarter, according to its quarterly report summarised by Kalkine Media. Best for: a single-mine Australian producer in ramp-up. Watch: underground development rate and concentrate grade (about 5.0% Li2O in that quarter).
Chinese-listed lithium miners: Ganfeng and Tianqi
Tianqi Lithium (Shenzhen 002466, Hong Kong 9696) controls Greenbushes through its 51% share of Tianqi Lithium Energy Australia, with Albemarle owning the other 49% of Talison (Tianqi 2025 annual report). Ganfeng Lithium (Shenzhen 002460, Hong Kong 1772) is a partner in Cauchari-Olaroz in Argentina, runs the Mariana brine project in Salta and the Goulamina spodumene mine in Mali, and also makes lithium chemicals and batteries. Both companies are large, but their shares trade mainly in Shenzhen and Hong Kong, which matters for foreign investors who need access to those markets.
China mined about 62,000 tonnes of lithium in 2025, the second-highest national total after Australia (USGS, 2026), and it refines most of the world’s lithium chemicals. That refining position is why Chinese buyers set much of the spodumene price that Australian miners receive.
Mid-size and US-listed producers and developers
Sigma Lithium (Nasdaq and TSXV: SGML)
Sigma mines spodumene at Grota do Cirilo in Minas Gerais, Brazil. In the second quarter of 2026 it produced 35,400 tonnes of concentrate and reported total cash costs of US$668 per tonne, with net debt cut to US$125 million (Sigma Lithium, 2Q 2026 results). Total cash cost is the cost of mining, processing and shipping the concentrate, per tonne, before sustaining capital. Watch: the company’s agreement talks with the state of Minas Gerais.
Lithium Argentina (NYSE and TSX: LAR)
Lithium Argentina owns a share of the Cauchari-Olaroz brine operation in Jujuy with Ganfeng. The operation produced 9,280 tonnes of lithium carbonate in the second quarter of 2026 and kept 2026 guidance of 35,000 to 40,000 tonnes (Lithium Argentina, Q2 2026). A Stage 2 plan would add 45,000 tonnes a year of LCE capacity, starting with a 10,000-tonne modular direct lithium extraction (DLE) plant.
Elevra Lithium (ASX: ELV; Nasdaq: ELVR)
Elevra was formed when Sayona Mining merged with Piedmont Lithium in 2025. It runs the North American Lithium (NAL) operation in Quebec, which produced 54,479 dry tonnes of concentrate at 5.0% Li2O in the June 2026 quarter, at an operating cost of US$907 per tonne sold (Elevra quarterly report, 28 July 2026). It holds an interest in the Moblan project and offtake rights to 60% of Moblan’s output.
Lithium Americas (NYSE and TSX: LAC)
Lithium Americas is building Phase 1 of Thacker Pass, a claystone lithium deposit in Humboldt County, Nevada. By 30 June 2026 it had drawn US$1.209 billion of its US Department of Energy loan and was targeting mechanical completion of the processing plant in late 2027, against a total capital estimate of US$2.93 billion (Lithium Americas, Q2 2026). As a developer it carries construction and start-up risk that producers do not. See our guide to lithium mines in Nevada for the other projects in the state.
Old lithium stock names that no longer trade
Many lists of lithium stocks still name companies that have gone. Check the current ticker before you research any of these:
- Livent (LTHM) merged with Allkem in January 2024 to form Arcadium Lithium.
- Arcadium Lithium (ALTM) was bought by Rio Tinto, completed in March 2025; its assets now sit in Rio Tinto’s lithium division.
- Piedmont Lithium (PLL) combined with Sayona Mining in 2025; the merged company is Elevra Lithium (ELV, ELVR).
- Pilbara Minerals is now PLS Group Limited; the ASX code PLS did not change.
- Lithium Americas (Argentina) Corp renamed itself Lithium Argentina (LAR) after separating from the Nevada business, which kept the Lithium Americas name.
Where the world’s lithium is mined
World mine production reached about 290,000 tonnes of lithium content in 2025, up from 222,000 tonnes in 2024, and world reserves are put at 37 million tonnes (USGS, 2026). Australia led with about 92,000 tonnes, followed by China (62,000), Chile (56,000), Zimbabwe (28,000) and Argentina (23,000). US output is withheld to protect company data. Batteries took an estimated 88% of lithium use worldwide.
Chart
Lithium mine production by country, 2025
Tonnes of lithium content, USGS estimates; US withheld
The country mix tells you which governments, royalty rules and currencies sit behind each stock. Chile and Argentina host the large brine operations; Australia, Brazil, Canada, Zimbabwe and Mali are hard-rock producers. Chile has the largest reserves at 9.2 million tonnes, then Australia at 8.4 million (USGS, 2026). For producer-by-producer rankings see our pages on the largest lithium producers and major lithium producers in the world, and for the European pipeline our guide to lithium mining in Europe.
Extraction method changes costs and timelines. Brine operations need years of pond evaporation but have low running costs; hard-rock mines ramp up faster but cost more per tonne. Our explainers on the lithium brine extraction process and lithium from unconventional sources, including DLE, cover both.

▶ How satellite images help find lithium-bearing ground, explained simply. · 10:49
Lithium prices and what they mean for miners’ revenue
The USGS puts the average battery-grade lithium carbonate price at about US$63,700 per tonne in 2022, falling to US$11,800 in 2024 and about US$9,000 in 2025, in real terms (USGS, 2026). Prices then rose: Rio Tinto said the carbonate price climbed 55% in the fourth quarter of 2025, and Albemarle’s realised price was 60% higher in the second quarter of 2026 than a year before.
Chart
Realised lithium prices, 2025 vs 2026
US$ per tonne LCE; Albemarle Q2, Rio Tinto first half
Chart
Battery-grade lithium carbonate, annual average
US$ per tonne, real terms; 2025 is an estimate
The rise has not been steady. China’s lithium carbonate price was CNY 90,650 per tonne on 12 November 2026, down about 19% over the month but about 7% higher than a year earlier, according to Trading Economics. Spodumene producers sell at a separate concentrate price; PLS, for example, received an estimated US$2,077 per tonne on an SC6 basis in the September 2026 quarter.
Three points decide how a price move reaches a company’s results. First, the product: chemical producers earn the carbonate or hydroxide price, concentrate miners earn the spodumene price, which usually follows with a lag. Second, the contract: some sales are fixed or lagged by one to three months, so a quarter’s realised price can differ from spot. Third, cost: a producer with AISC well below the price keeps a margin through a downturn. The longer demand view is in our lithium demand forecast.
Calculator: spodumene output to revenue
Use the calculator below to turn a mine’s concentrate output into revenue and an operating margin at a price you choose. Enter the tonnage from the company’s latest report, the grade it sold at, today’s SC6 price and its stated unit cost. The result is a rough guide to how much a price change moves one producer, not a valuation.
Calculator
What is a quarter of spodumene output worth?
Enter a miner’s reported concentrate output, grade, price and unit cost.
- Operating cost (US$ million): 140.0
- Operating margin (US$ million): 226.7
- Revenue change per US$100/t (US$ million): 18.3
Example values only, not a forecast or a company result. Price is an input: use today’s SC6 price. Revenue is scaled from SC6 to the grade sold in proportion to Li2O content, a simplification; real contracts use their own grade adjustments. Excludes royalties, tax, freight differences and capital spending.
How to evaluate lithium mining stocks before you buy
The same steps work for a large producer or a junior explorer. Work through them with the company’s latest filings open.
- Confirm the name, ticker and exchange. Use the company website or the exchange’s own search (ASX, TSX, NYSE, Nasdaq). Many lists still show Livent, Arcadium or Piedmont.
- Find what the company actually owns. Note each mine’s ownership share; a 49% or 51% stake gives half the tonnes.
- Read the product and price basis. Concentrate, carbonate or hydroxide; spot, lagged or fixed contracts.
- Compare unit cost to price. Find AISC or unit operating cost per tonne and set it against today’s price for the same product and grade.
- Check cash and debt. Look at cash, net debt and when loans fall due, and whether construction is fully funded.
- Check the jurisdiction. Royalties, export rules and state partners differ between Chile, Argentina, Australia, Brazil, Canada and the United States.
- Check reserves and mine life. Ore reserve tonnes and grade (in % Li2O for hard rock, mg/L lithium for brine) show how long output can last.
- Read the risks section. Annual reports list the operating, permitting and market risks the company itself sees.
Junior lithium stocks, the small explorers and developers, add exploration and financing risk on top: they may need to raise money several times before any production. For other battery and critical metals, see our pages on iron ore mining and US copper mining companies, and for gold miners in Canada our Canadian gold deposits and stocks guide.
▶ What AI in mineral exploration can and cannot do in finding mines. · 4:37
Where satellite screening fits for lithium projects
Before drilling, explorers and the investors who back them use satellite images to map pegmatite outcrops, clay alteration and salt-flat extent across a licence. Farmonaut screens licence areas from satellite data to help rank targets ahead of drilling; results are exploration targets, not resources. Our pages on AI in geology and mining technology cover the wider tools.
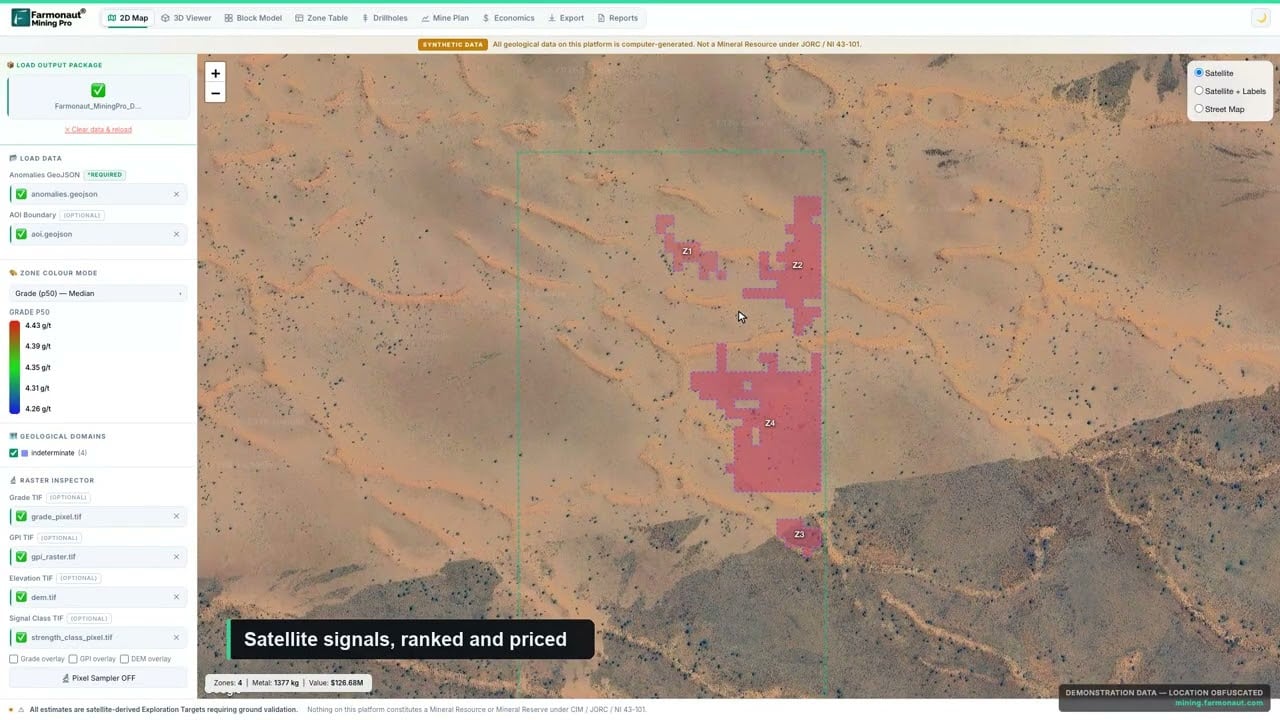
▶ A short look at Farmonaut Mining Pro, which turns a licence boundary into a geological picture. · 4:56
Frequently asked questions
Who are the largest lithium mining companies?
By reported volume in 2026, SQM, Albemarle and Rio Tinto lead in LCE terms, and PLS, Mineral Resources and the Greenbushes owners (Tianqi, IGO and Albemarle) lead in spodumene concentrate. Ganfeng and Tianqi are the largest Chinese-listed names.
Which lithium mining companies are publicly traded in the US?
On US exchanges you can find Albemarle (ALB), SQM (SQM), Rio Tinto (RIO), Lithium Argentina (LAR), Lithium Americas (LAC), Sigma Lithium (SGML) and Elevra Lithium (ELVR). Albemarle runs the only commercial US brine operation, Silver Peak in Nevada.
Are lithium stocks safe to invest in?
No mining stock is safe in the way a deposit account is. Lithium prices fell by more than 80% between the 2022 and 2025 annual averages (USGS), and producers’ profits fell with them. Cost position, cash and debt decide which companies get through a weak market.
What is the difference between lithium carbonate and spodumene prices?
Lithium carbonate is a refined chemical sold to battery makers. Spodumene concentrate is the mined mineral, usually around 5-6% Li2O, sold to converters. Concentrate prices are much lower per tonne and usually follow chemical prices with a lag.
What happened to Livent and Piedmont Lithium?
Livent merged with Allkem to form Arcadium Lithium in 2024, and Rio Tinto bought Arcadium in March 2025. Piedmont Lithium merged with Sayona Mining in 2025 to form Elevra Lithium.
Is Pilbara Minerals the same company as PLS?
Yes. Pilbara Minerals changed its name to PLS Group Limited from 27 November 2025 and kept the ASX code PLS.
Which country produces the most lithium?
Australia, with about 92,000 tonnes of lithium content in 2025, followed by China at 62,000 and Chile at 56,000 tonnes (USGS, 2026).
What are junior lithium mining stocks?
Juniors are small companies that explore or develop lithium deposits without a producing mine. They can rise or fall sharply on drill results, permits and funding, and often issue new shares to pay for work.
How do I invest in lithium without picking one miner?
Some exchange-traded funds hold baskets of lithium miners and battery makers. Read each fund’s holdings and fees on the issuer’s site; many hold more battery makers than miners.
What does AISC mean for a lithium miner?
All-in sustaining cost is the cost per tonne to mine, process, ship and keep an operation running, before growth spending. Compare it with the price for the same product and grade.
More from Farmonaut: farmonaut.com, agro admin app, carbon footprinting, crop loan and insurance, farmonaut satellite weather api developer docs, fleet management, traceability.
This page is for information only. It is not investment advice. It rates no company and names no security to buy or sell. Check company filings and speak to a licensed adviser.
Farmonaut mining
Screen a lithium licence from space
For investors weighing an explorer, Farmonaut maps pegmatite and alteration targets across a licence area before drilling.

Mining Pro sample view, synthetic data
Keep reading
Sources
- USGS, Mineral Commodity Summaries 2026: Lithium: pubs.usgs.gov
- Trading Economics, Lithium carbonate price (12 November 2026): tradingeconomics.com
- SQM, results for six months ended 30 June 2026: nasdaq.com
- Albemarle, second-quarter 2026 results: albemarle.com
- Rio Tinto, fourth-quarter 2025 production results (January 2026): announcements.asx.com.au
- Rio Tinto, 2026 half-year results: riotinto.com
- PLS, September 2026 quarterly activities report: announcements.asx.com.au
- Mineral Resources, Q1 FY27 quarterly activity report: mineralresources.com.au
- IGO, 2026 Annual Report: igo.com.au
- Tianqi Lithium, 2025 Annual Report (HKEX): www1.hkexnews.hk
- Kalkine Media, Liontown June 2026 quarter: kalkinemedia.com
- Sigma Lithium, 2Q 2026 results: nasdaq.com
- Lithium Argentina, second-quarter 2026 results: nasdaq.com
- Elevra Lithium, quarterly activities report (28 July 2026): nasdaq.com
- Lithium Americas, second-quarter 2026 results: nasdaq.com
- Codelco-SQM partnership: acuerdocodelcosqm.cl
- FilingReader, Pilbara Minerals renamed PLS Group (November 2025): filingreader.com
- Investing News Network, biggest lithium-mining companies (May 2026): investingnews.com
- US Department of Energy, Final EA for Kings Mountain Lithium Mine Project (March 2026): energy.gov
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Southbridge & Wess PDC Ltd
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited

 Client · Oregon, USA · Gold










