

Reviewed August 2026 against the USDA Farm Service Agency, USDA National Agricultural Statistics Service, and USDA Economic Research Service.
Try it: Run your own numbers →
Table of Contents
- Summary: What an Agricultural Land Loan Actually Costs
- Understanding Agricultural Loans and Agri Land Loans
- Land Loans NC: North Carolina-Specific Considerations
- Ranch Land Loans: How They Differ From Cropland Financing
- Interest Rates for Agricultural Land Loans
- Farmland Values: What You’re Actually Borrowing Against
- Technology Transforming Agricultural Lending
- How Satellite & AI Support Smarter Agri Loan Decisions
- Comparison of Agricultural Loan Types
- Land Loan Payment & Break-Even Calculator
- Challenges and Solutions in Agri Loan Access
- Agribusiness Loans vs. Standard Business Loans
- Satellite-Powered Apps & APIs for Agri Finance
- Farmonaut Subscriptions
- Frequently Asked Questions
- Conclusion
- Try it: Run your own numbers
Summary: What an Agricultural Land Loan Actually Costs
A land loan for agricultural property in the United States is priced very differently depending on whether it comes from the USDA Farm Service Agency (FSA), a Farm Credit System lender, or a commercial bank. As of August 2026, the FSA’s own direct-lending rates run from 3.750% on Emergency Loans to 6.000% on standard direct Farm Ownership Loans, with a lower 4.000% rate available on the joint-financing option, according to the USDA Farm Service Agency’s August 2026 lending rate announcement. Meanwhile, US cropland averaged $6,020 per acre and pastureland averaged $2,000 per acre in the July 2026 USDA National Agricultural Statistics Service farmland value report — numbers that directly determine how large a loan you’ll need and how much collateral you actually have.
This guide breaks down agri land loans, ranch land loans, and North Carolina-specific land financing by rate, loan cap, and lender type, then shows how satellite-verified farm data is starting to change how these loans get underwritten and monitored.
Understanding Agricultural Loans and Agri Land Loans
An agricultural loan is credit extended specifically against farm assets — land, growing crops, livestock, or equipment — rather than general business collateral. An agri land loan (sometimes searched as “agriculture term loan”) is the subset used specifically to buy, refinance, or improve farmland, as opposed to a working-capital loan for seed and fertilizer. In the US, three channels dominate:
- FSA direct loans — the government lends directly. Farm Ownership Loans max out at $600,000 and Farm Operating Loans at $400,000, per the USDA FSA guaranteed and direct loan program page.
- FSA guaranteed loans — a commercial bank, credit union, or Farm Credit association makes the loan, and FSA guarantees up to 95% of it. The guaranteed loan ceiling is $2,343,000 for 2026, far above the direct-loan caps, making it the relevant program for a full-size land purchase.
- Conventional/commercial ag loans — banks and Farm Credit System lenders price these against their own cost of funds and the borrower’s balance sheet. The FSA publishes only its own government-backed rates; commercial land loan rates are not centrally published and must be quoted directly by the lender.
Modern farming technology increasingly factors into how lenders view an application, because verified yield and land-condition data reduces the lender’s uncertainty about repayment capacity — more on that below.

Land Loans NC: North Carolina-Specific Considerations
Searches for “land loans NC” typically come from buyers looking at rural or agricultural parcels in North Carolina rather than urban construction lots, and the financing path differs from a standard residential mortgage in three concrete ways.
- Raw or unimproved land needs a land-specific loan, not a mortgage. Residential mortgage underwriting assumes an existing structure; a bare agricultural or timber tract in NC is financed instead through a farm real estate loan, a Farm Credit association serving the state, or an FSA direct or guaranteed loan.
- FSA eligibility and caps apply the same way in North Carolina as nationally. The $600,000 direct Farm Ownership cap and $2,343,000 guaranteed cap set by the USDA FSA program page are national figures — North Carolina applicants use the same FSA county office network as any other state, and eligibility (owner-operator requirement, US citizenship or lawful residency, first-time or existing farmer status) does not change by geography.
- Land value benchmarks differ regionally. The July 2026 NASS report groups states into regions rather than reporting every state individually in its national summary; North Carolina falls within the broader Southeast reporting region, and buyers should pull the state-level detail tables from the USDA NASS farmland value report directly rather than relying on the $6,020/acre US average, which is pulled upward by high-value Corn Belt and Pacific cropland.
A North Carolina buyer’s practical checklist: confirm parcel zoning and any conservation easements with the county register of deeds, get a current appraisal (land values move enough that a report even six months old can misstate loan-to-value), check FSA county office eligibility if pursuing a government-backed loan, and compare at least one Farm Credit association quote against one commercial bank quote — rate spreads between the two can be wide enough to matter on a six-figure loan.
Ranch Land Loans: How They Differ From Cropland Financing
A ranch land loan finances pastureland and rangeland for livestock operations rather than row-crop ground, and lenders treat the two differently for one central reason: pastureland is worth less per acre and produces income on a slower, less predictable cycle than annual cropland.
- Lower per-acre collateral value. US pastureland averaged $2,000 per acre in July 2026 against $6,020 per acre for cropland — a ranch loan of the same dollar size requires roughly three times the acreage as collateral compared with a cropland loan, per the USDA NASS farmland value report.
- Income timing is different. Cropland cash flow follows an annual harvest; a cow-calf or stocker operation’s income follows breeding, weaning, and market cycles that can run 12-24 months, which is why ranch loan underwriting weighs herd size, carrying capacity, and grazing lease income more heavily than a single season’s crop receipts.
- FSA treats ranch and cropland purchases under the same Farm Ownership Loan program — the $600,000 direct cap and $2,343,000 guaranteed cap apply regardless of whether the land is used for grazing or row crops, per the USDA FSA guaranteed farm loans page. The difference shows up in the lender’s appraisal and cash-flow projection, not in the program’s stated limits.
Ranch buyers evaluating a parcel should run the same $2,000/acre pastureland benchmark against the specific carrying capacity of the tract — grazing land in regions with higher rainfall and better forage supports more animal units per acre than arid rangeland, which changes the effective income-per-acre a lender will underwrite against even at the same purchase price.
Interest Rates for Agricultural Land Loans
The only interest rates published centrally and updated on a fixed schedule are the FSA’s own direct-loan rates. As of the August 2026 announcement, they stand at:
| Loan Program | Interest Rate |
|---|---|
| Farm Operating Loan (Direct) | 5.250% |
| Farm Ownership Loan (Direct, standard) | 6.000% |
| Farm Ownership Loan (Joint Financing option) | 4.000% |
| Emergency Loan | 3.750% |
Source: USDA Farm Service Agency, August 2026 lending rate announcement. These rates are set and republished monthly — check the FSA news page directly for the current month’s figures rather than relying on this table beyond a few weeks old, since FSA typically posts updated rates within the first three days of each month.
FSA guaranteed loans and commercial/Farm Credit loans are priced by the individual lender against its own funding cost, the borrower’s credit profile, and loan-to-value, and there is no single published index for these commercial rates — this is a genuine gap in publicly available data, not an oversight in this article. To get a real commercial quote, contact a Farm Credit System association or ag-lending bank directly and ask for both a fixed and variable quote at your specific loan-to-value ratio, then compare that quote against the FSA direct rates above as your benchmark floor.
One demand-side data point worth knowing: new operating farm loan volume rose 40% year-over-year in Q4 2025, according to the National Survey of Terms of Lending to Farmers cited by the American Farm Bureau Federation’s Market Intel analysis — a signal that more farmers are borrowing for working capital even as land loan rates sit well above pre-2022 levels.
Farmland Values: What You’re Actually Borrowing Against
Loan size and loan-to-value both depend on what the land is worth, and that number varies sharply by region and use. The July 2026 NASS report puts the national average farm real estate value (land plus buildings) at $4,500 per acre, but regional cropland averages diverge well beyond that blended figure:
- Corn Belt cropland (Illinois, Indiana, Iowa, Missouri, Ohio) averaged $8,590 per acre in July 2026.
- Pacific region cropland (California, Oregon, Washington) averaged $8,440 per acre in July 2026.
- National average cropland stood at $6,020 per acre, and national average pastureland at $2,000 per acre.
Cropland values have climbed 21.8% since 2022, per the same USDA NASS report — a four-year run-up that matters directly to loan sizing, because a buyer pricing a purchase against 2022-era comparable sales will underestimate today’s required loan by roughly a fifth. NASS releases this report quarterly; pull the latest edition from nass.usda.gov before finalizing any purchase offer or refinance.
At the sector level, the USDA Economic Research Service forecasts total US farm sector debt at $624.7 billion for 2026, split between $404.3 billion in farm real estate debt and $220.4 billion in non-real estate debt, with total farm interest expense forecast at $33 billion for the year, according to the USDA Economic Research Service farm sector debt and finance data. ERS updates this forecast annually, typically in early in the calendar year — check that page for the current-year projection before citing this figure past its year.
Technology Transforming Agricultural Lending
Lenders underwriting land and operating loans increasingly pull in data sources beyond the tax appraisal and a site visit:
-
Satellite-Verified Land and Crop Condition
Remote sensing lets a lender check vegetation health, field boundaries, and land use history for a parcel before approving a loan, rather than relying solely on the borrower’s self-reported acreage and condition.
-
Digital Application and Underwriting
FSA and most Farm Credit associations now process direct and guaranteed loan applications through online portals, cutting the paperwork cycle compared with a fully paper-based application.
-
Sustainability-Linked Terms
Some lenders offer rate or fee adjustments tied to conservation practices, cover cropping, or reduced-tillage adoption — verified increasingly through remote monitoring rather than self-attestation.
-
Flexible, Seasonal Repayment Structures
Operating and land loan repayment schedules are increasingly built around actual harvest and marketing timing for the specific crop or livestock enterprise, rather than a flat monthly amortization.
How Satellite & AI Support Smarter Agri Loan Decisions
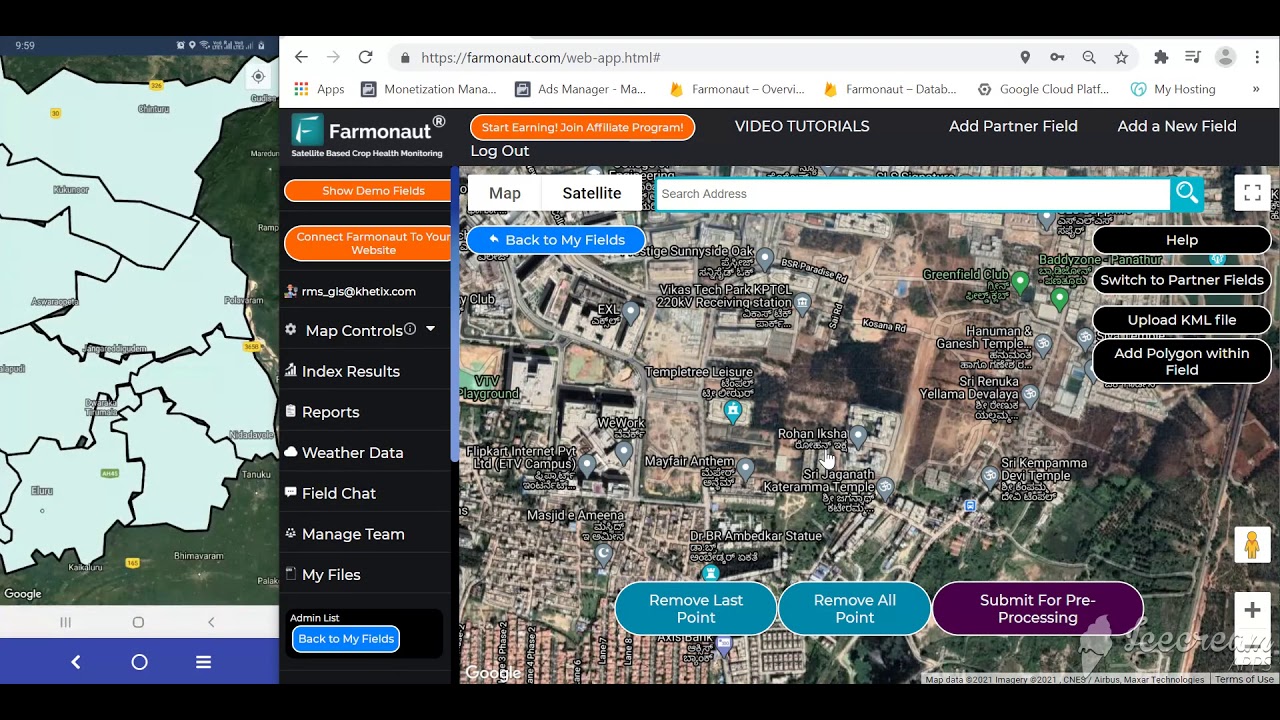
Farmonaut’s satellite monitoring platform gives lenders and borrowers a third-party, remotely verified view of a parcel’s condition that sits alongside — not instead of — the appraisal and credit file a bank or Farm Credit lender requires:
- Verify crop health, soil condition indicators, and land use history on a parcel before a loan to buy agricultural land closes.
- Track productivity through the growing season, giving lenders an ongoing signal for existing land and operating loans rather than a single point-in-time snapshot.
- Use blockchain-based traceability to document land history and operational records that support a loan file.
Explore Farmonaut’s carbon footprinting feature to document environmental practices that may qualify for sustainability-linked loan terms from participating lenders.
End-to-end product traceability gives lenders a documented chain of custody for land and produce, which can support a loan application’s credibility during underwriting.

For farms and agribusinesses managing multiple parcels under one or several loans, Farmonaut’s large-scale farm management tools centralize mapping, resource tracking, and compliance records that a lender may request during annual loan review.
Comparison of Agricultural Loan Types
| Loan Type | Typical Use | Program Cap | Rate as of Aug. 2026 | Rate Source |
|---|---|---|---|---|
| FSA Direct Farm Ownership Loan | Buy or consolidate agricultural land, incl. ranch land | $600,000 | 6.000% (4.000% joint financing option) | USDA FSA, published monthly |
| FSA Direct Farm Operating Loan | Working capital: seed, fertilizer, livestock feed | $400,000 | 5.250% | USDA FSA, published monthly |
| FSA Emergency Loan | Recovery from qualifying disaster losses | Set per disaster designation | 3.750% | USDA FSA, published monthly |
| FSA Guaranteed Farm Loan | Larger land purchases via bank/Farm Credit lender, FSA-backed | $2,343,000 | Set by originating lender, not centrally published | Lender-specific quote required |
| Commercial/Farm Credit Land Loan | Land loans NC, ranch land loans, general ag land purchase | No federal cap; set by lender | Not centrally published | Lender-specific quote required |
Rows without a published rate are not a gap in this article — they reflect that FSA is the only lender in this table required to publish a fixed, centrally-tracked rate. For the two lender-specific rows, request a same-day quote from at least one Farm Credit association and one commercial ag lender, and use the FSA direct rates above as your comparison floor.

Land Loan Payment & Break-Even Calculator
Use the FSA rates and NASS land values above as starting points, then plug in your own loan amount, rate, and term to see the monthly payment and how many acres of production income it takes to cover it.
Run your own numbers
Assumptions: fixed-rate amortizing loan with no fees, points, or balloon payment; “net income per acre” is whatever you enter and should reflect your own crop or livestock budget after input costs, not gross revenue. This does not model variable rates, FSA subsidy adjustments, property taxes, insurance, or a guaranteed loan’s lender fees — treat the output as a planning estimate, not a loan offer.
Challenges and Solutions in Agri Loan Access
Several structural barriers still slow down agricultural loan access, even with FSA programs and digital applications in place:
- Collateral and credit history gaps for first-time buyers and smaller operations without an existing land-secured track record.
- Rate uncertainty on the commercial side — because commercial and guaranteed-loan rates are not centrally published the way FSA direct rates are, a borrower cannot comparison-shop without contacting multiple lenders directly.
- Land value volatility — a 21.8% cropland value increase since 2022 cuts both ways: it improves collateral value for existing owners but raises the entry cost and loan size for new buyers.
Solutions Worth Using
- FSA First-Time Farmer Support: Direct Farm Ownership Loans specifically accommodate applicants without an existing credit history in farm real estate.
- Collateral Alternatives: Warehouse receipts and digital land records, supported by blockchain traceability tools, are increasingly accepted alongside traditional land collateral.
- Risk-Sharing and Insurance: Pairing a land loan with crop insurance reduces a lender’s perceived repayment risk — see Farmonaut’s crop loan & insurance resources.
- Multiple Quotes: Because commercial ag land loan rates are not published, request quotes from at least a Farm Credit association and a commercial bank before assuming the FSA rate is your only option.
Agribusiness Loans vs. Standard Business Loans
An agribusiness loan differs from a standard commercial business loan in three concrete ways that matter when comparing offers:
- Collateral type. Standard business loans are typically secured by receivables, inventory, or general business assets; agribusiness and agri land loans are secured by farmland, growing crops, or livestock — assets whose value is published quarterly by USDA NASS rather than assessed continuously like inventory.
- Repayment timing. Standard business loans usually assume steady monthly revenue; agricultural loans are structured around harvest and marketing cycles, and FSA’s own programs explicitly build in seasonal repayment flexibility.
- Government-backed options. Standard businesses have SBA-guaranteed loans; agriculture has the parallel FSA direct and guaranteed loan system, with its own published rate schedule and the $600,000 / $2,343,000 caps described above — a financing channel that does not exist for a typical non-farm small business.
Farmonaut supports both sides of this — lenders and borrowers — with satellite-based land and crop verification that can substitute for some of the manual, on-site documentation a standard business loan file would not require.

Satellite-Powered Apps & APIs for Agri Finance
Lenders, agribusinesses, and individual farmers evaluating a land loan can access Farmonaut’s satellite monitoring, traceability, and analytics tools through several channels:



- Farmonaut Web App: Browser and mobile access for real-time land, crop, and environmental monitoring — useful for lenders evaluating a loan applicant’s parcel. Try it now!
- Farmonaut API Access: Integrate satellite, farm, and climate data directly into a lending or fintech platform via the Farmonaut Satellite API.
- API Documentation: Full endpoint reference in the API developer docs.
- Mobile Apps: Available for Android and iOS for field-level review of a loan applicant’s land.
- For sustainability-linked loan documentation, see also the eco-friendly equipment context in this related Farmonaut guide.

Farmonaut Subscriptions
Farmonaut offers subscription-based access to satellite monitoring, AI analytics, and blockchain traceability for individual farmers, agribusinesses, and financial institutions evaluating or managing agricultural loans.
Choose a plan to monitor farm health, document loan eligibility, or track land value factors:
Frequently Asked Questions
What is the current interest rate for an agricultural land loan?
It depends on the lender. FSA’s own direct loan rates as of August 2026 run from 3.750% (Emergency Loan) to 6.000% (standard Farm Ownership Loan), with a 4.000% joint-financing option, per the USDA FSA rate announcement. FSA guaranteed loans and commercial/Farm Credit loans are priced individually by the lender and are not centrally published — get a direct quote to compare against the FSA rate.
How much can I borrow with an FSA loan to buy agricultural land?
A direct Farm Ownership Loan caps at $600,000. An FSA guaranteed loan — originated by a bank or Farm Credit lender and backed by FSA — caps at $2,343,000 for 2026, per the USDA FSA program page.
What’s different about a land loan in NC compared with other states?
The FSA program rules, rate schedule, and national caps are identical in North Carolina to the rest of the country. What differs is land value: NC falls in a Southeast reporting region in USDA’s farmland value data rather than in the higher-value Corn Belt ($8,590/acre) or Pacific ($8,440/acre) regions — check the state-level detail tables in the USDA NASS report for the current NC-specific figure before sizing a loan.
Is a ranch land loan different from a regular agricultural land loan?
The FSA program and caps are the same, but the collateral value differs sharply: pastureland averaged $2,000 per acre versus $6,020 per acre for cropland nationally in July 2026. Lenders also weigh herd size and grazing income differently than a single annual crop harvest.
What are the top lenders for small-farmer agricultural loans, and how do they compare?
For US borrowers, the three channels to compare are FSA direct loans (fixed, published rate, lower caps), FSA guaranteed loans through a bank or Farm Credit association (higher caps, lender-set rate), and fully commercial ag loans (no federal cap, rate and terms set entirely by the lender). This article covers the US market specifically; lender comparisons for other countries are outside its scope and rates for foreign markets are not included here.
What’s the difference between an agribusiness loan and a standard business loan?
Agribusiness loans use farmland, crops, or livestock as collateral and structure repayment around harvest cycles; standard business loans use general business assets and assume steadier monthly cash flow. Agriculture also has its own government-backed channel — FSA direct and guaranteed loans — that parallels but is separate from SBA lending for non-farm businesses.
Are there sustainability-linked incentives in agricultural lending?
Some lenders offer rate or fee adjustments for conservation practices or eco-friendly equipment adoption. Farmonaut’s carbon footprinting tools can help document practices that support such applications, though specific incentive terms vary by individual lender and should be confirmed directly with them.
Conclusion: Comparing Land Loans on the Numbers That Actually Change
The figures that decide whether a land loan is affordable — FSA’s rate schedule, regional cropland and pastureland values, and total farm sector debt — all move on fixed public schedules: FSA rates monthly, NASS land values quarterly, and ERS debt forecasts annually. None of them are static, and none require guessing: check the FSA rate page before locking a direct loan, pull the current NASS farmland value report before setting a purchase offer, and get at least two lender quotes for anything the FSA doesn’t price directly.
Whether you’re comparing a land loan in North Carolina, a ranch land loan against grazing income, or a straightforward agri land loan for cropland expansion, the process is the same: confirm the program’s current rate and cap, confirm the land’s current per-acre value for your region, and get the collateral itself independently verified. Satellite-based tools from Farmonaut exist specifically to support that last step for lenders and borrowers alike.

 Godrej Agrovet
 Hayleys Agriculture
 Linx Agritech
 Adinet
 Save Your Soils
 GalaxEye Space
 Grandstream Algérie
 XOS Realty
 Geospatial Lab Africa
 Agro La Gándara
 HIPSAC
 ZOL Zimbabwe
 Juligerm
 AdBio
 MISE Maroc
 NWNS
 Red August Group
 Farm Inc
 WeMe Global
 Agrotoken
 Blue BearX
 Insignito
 DnCubed
 Indosistim Teknologi
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC
 AgroRisk
 Oath Inc
 Esri North East Africa
 MDCV UK
 Etech Consulting Madagascar
 Vestlandsforsking
 WB Dev
 Sama Premium
 Tres Valles
 Blickwinkel
 Agricultural Credit Policy Council
 eKGIS
 Mostas Tech
 Andex
 Deluxe Conseil
 WICO
 Chimera Innovation
 SkyHarvest
 Teledarbas
 Exurbia Geospatial
 FieldZero

