

Largest Agricultural Companies: Seed, Equipment & Robotics
Reviewed August 2026 against USDA/Seed World census data, Mordor Intelligence market reports, and USDA Farm Service Agency lending rates.
Try it: Run your own numbers →
Table of Contents
- Who Are the Largest Agricultural Companies?
- Agricultural Seed Companies: Who Controls the Market
- Agricultural Equipment Companies: Revenue and Focus
- Agricultural Equipment Financing Companies: What It Costs to Borrow
- Precision Agriculture Robotics Companies: Market Size and Leaders
- Comparison Table: Seed, Equipment, and Robotics Players
- Equipment Financing Cost Calculator
- Where Satellite Monitoring Fits Into This Landscape
- How to Verify These Figures Yourself
- FAQ
Who Are the Largest Agricultural Companies?
Three groups dominate large-scale agriculture in the United States and its trading partners: seed and crop-protection majors (Bayer, Corteva, Syngenta), equipment manufacturers (John Deere, CNH Industrial, AGCO), and a fast-growing cluster of precision agriculture robotics companies (DJI Agriculture, XAG, AgEagle, Iron Ox, Naïo Technologies). Each operates in a market with distinct financial scale: North America’s commercial seed market was valued at $28.76 billion in 2026 by Mordor Intelligence, U.S. precision farming reached $16.61 billion the same year, and global agricultural robotics stood at $23.31 billion, growing at an 18.07% compound annual rate from 2026 through 2031.
These are not interchangeable categories. A seed company’s competitive position is measured by market share concentration; an equipment company’s by annual revenue; a robotics company’s by growth rate in a market that is still forming. The rest of this article breaks down each category with sourced figures, then adds an equipment financing cost estimate most guides skip entirely.

Agricultural Seed Companies: Who Controls the Market
The U.S. seed market is not fragmented. According to USDA census data covering 2018–2020 (the most recent complete USDA seed-industry breakdown, reported by Seed World), Corteva and Bayer together held 71.6% of the U.S. corn seed market and 65.9% of the U.S. soybean seed market. Widen the lens to four firms — Bayer, Corteva, Syngenta, and BASF — and their combined share of the U.S. corn seed market reaches 83.9%. That is a duopoly-plus-two structure, not a competitive marketplace with dozens of viable suppliers.
This concentration matters for anyone searching for “agricultural seed companies” with a purchasing or investment intent: there are really only four buyers’ decisions to track in corn and soybean genetics, and two of them (Corteva and Bayer) set the terms for most of the market. Bayer Crop Science’s Short Stature Corn hybrids are one visible product of that scale — bred for wind resistance and higher planting density on the same acre. Corteva runs digital breeding platforms to shorten trait-development timelines, and Syngenta pairs seed recommendations with weather-forecasting data.
The USDA figures above are from the last full census cycle (2018–2020); USDA does not republish seed-specific market-share breakdowns annually the way it does crop production data. For a current read, check the Seed World summary of USDA data directly, since any newer USDA release will supersede the 2018–2020 figures cited here.
Agricultural Equipment Companies: Revenue and Focus
Among agricultural equipment companies, John Deere (Deere & Company) reported $45.7 billion in annual revenue for fiscal 2025, a figure that put it on the Fortune 500 alongside AGCO, according to AGCO’s own investor announcement of its Fortune 500 placement. That single number explains why “largest agricultural companies” searches skew toward equipment makers: Deere’s revenue alone is larger than the entire North America commercial seed market ($28.76 billion in 2026).
Equipment companies compete less on chemistry and genetics and more on integration: GPS guidance that keeps planters from overlapping rows, autonomous tractor programs, fleet management platforms for tracking machine location and utilization, and variable-rate technology (VRT) that adjusts seed or input rates in real time based on soil sensor data. These are the features buyers actually compare before purchase — not just horsepower.
- ✔ Precision Planters — row-level accuracy that cuts seed and fertilizer overlap
- ✔ Autonomous & GPS-Guided Tractors — reduce labor hours per acre
- ✔ Connected Implements — real-time equipment health and failure prediction
- ✔ Fleet Tracking — route optimization across multiple fields or contracts
- ✔ Satellite Data Integration — feeds into carbon footprinting and product traceability reporting
- Try it: Run your own numbers



What isn’t published anywhere: verified revenue figures for CNH Industrial, Kubota, and other equipment manufacturers outside the U.S. Fortune 500 list. Deere and AGCO appear because they file U.S.-listed financials; CNH Industrial, Kubota, Mahindra, and CLAAS report under different jurisdictions and disclosure schedules. If you need a specific manufacturer’s current revenue, go to that company’s own investor-relations page and its most recent 10-K or annual report — don’t trust a secondhand figure that doesn’t cite one.
Agricultural Equipment Financing Companies: What It Costs to Borrow
Equipment financing is the piece most “largest agricultural companies” roundups skip, and it’s a real search intent: growers comparing whether to buy new machinery want to know what borrowing actually costs before they call a dealer’s captive finance arm. Here’s what’s publicly documented and what isn’t.
The USDA Farm Service Agency (FSA) publishes its direct farm operating loan rate monthly. In December 2024, the FSA-announced rate for direct farm operating loans was 4.750%, according to the FSA’s own December 2024 lending-rate announcement. That is a government program rate, not a commercial equipment-financing rate — private lenders and manufacturer captive finance companies (like John Deere Financial) set their own rates based on credit profile, term length, and equipment type, and those specific commercial rates are not published in a single public table.
If you’re evaluating an equipment loan, the FSA rate is a useful floor reference — commercial financing for equivalent risk is typically priced above the government program rate, not below it. For the current FSA rate (it’s republished monthly), check the FSA’s lending rate announcements page directly rather than relying on this article’s December 2024 figure once it ages.
Precision Agriculture Robotics Companies: Market Size and Leaders
This is the fastest-moving category on this page. DataM Intelligence sized the global robotics-in-agriculture market at $23.31 billion, and Mordor Intelligence separately projects the agricultural robots segment to grow at an 18.07% compound annual growth rate between 2026 and 2031. That growth rate is roughly double what mature equipment categories post, which is why “top precision agriculture robotics companies” is a query with rising search volume even though the market is still smaller than either the seed or the core equipment segment.
The companies leading this category split into two functional groups:
- ✔ Drone and spray robotics: DJI Agriculture and XAG (both China-based) lead in multispectral sprayer drones; AgEagle (USA) focuses on cloud-based drone data analytics rather than the aircraft itself.
- ✔ Field and crop robotics: Iron Ox (USA) builds autonomous hydroponic systems for controlled-environment agriculture; Naïo Technologies (France) makes autonomous weeding robots aimed at replacing herbicide passes.
Multispectral sensors carried on these platforms measure crop health and soil moisture the same way satellite-based monitoring does at a different scale — see satellite-plantation monitoring for the orbital-scale complement to drone-level data. The distinction that matters when evaluating a robotics vendor: drones cover more acres per hour but at lower resolution; ground robots cover fewer acres but can act (weed, plant, harvest) rather than just sense.
Comparison Table: Seed, Equipment, and Robotics Players
The table below separates what’s independently verifiable (revenue, market share, growth rate, sourced to the citations above) from what would need direct company disclosure to confirm. Where a source doesn’t publish a figure, the cell says so instead of guessing.
| Company / Segment | Category | Verified Figure | Source & Period |
|---|---|---|---|
| Corteva + Bayer | Seed (corn) | 71.6% combined U.S. market share | USDA census 2018–2020, via Seed World |
| Corteva + Bayer | Seed (soybean) | 65.9% combined U.S. market share | USDA census 2018–2020, via Seed World |
| Bayer, Corteva, Syngenta, BASF | Seed (corn, top 4) | 83.9% combined U.S. market share | USDA census 2018–2020, via Seed World |
| John Deere (Deere & Company) | Equipment | $45.7 billion annual revenue | Fiscal year 2025, AGCO/Fortune 500 reporting |
| CNH Industrial, Kubota, CLAAS | Equipment | Not published in U.S. Fortune 500 data | Check each company’s own investor relations / annual report |
| DJI Agriculture, XAG, AgEagle | Robotics — drones | Part of $23.31B global robotics-in-ag market | DataM Intelligence, 2026 |
| Iron Ox, Naïo Technologies | Robotics — field/CEA | Part of 18.07% CAGR 2026–2031 segment | Mordor Intelligence, agricultural robots market |
| North America seed market (overall) | Seed | $28.76 billion market size | Mordor Intelligence, 2026 |
| U.S. precision farming (overall) | Precision ag / robotics adjacent | $16.61 billion market size | Mordor Intelligence, 2026 |
| USDA FSA direct operating loans | Equipment financing (government) | 4.750% interest rate | USDA FSA, December 2024 |
Note the gaps deliberately left in that table: precision agriculture adoption rate (% of U.S. farms using GPS guidance or VRT) is not published by USDA NASS as a standalone figure, and seed production volumes (bushels of corn/soybean seed produced, as distinct from harvested grain) aren’t tracked the way commodity production is. If those numbers matter to your decision, USDA NASS’s Census of Agriculture (conducted every five years) is the closest primary source — check its release schedule rather than assuming an annual update.
Explore Farmonaut API for agriculture, mining, and infrastructure monitoring.
Developers—find full API docs here.
Equipment Financing Cost Calculator
Estimate the total interest cost of an equipment loan across a term, using your own quoted rate rather than a generic assumption:
Run your own numbers
Assumes a standard fixed-rate fully amortizing loan with equal monthly payments; excludes fees, taxes, insurance, balloon payments, and variable-rate structures. The USDA FSA’s December 2024 direct operating loan rate was 4.750% — use that only as a government-program floor reference, not as your expected commercial rate. Enter the actual APR your lender quotes for an accurate estimate.
Where Satellite Monitoring Fits Into This Landscape
Seed genetics, equipment automation, and ground/air robotics all generate data — soil moisture readings, spray logs, planting maps. Satellite monitoring is the layer that ties that data to a specific field over time without requiring a drone flight or a sensor installation. Farmonaut provides multispectral satellite imagery for vegetation health and soil condition tracking, a smart farming system that layers onto whatever equipment or seed genetics a grower already uses.
- ✔ Satellite-Based Monitoring: Multispectral imagery for vegetation health and soil conditions.
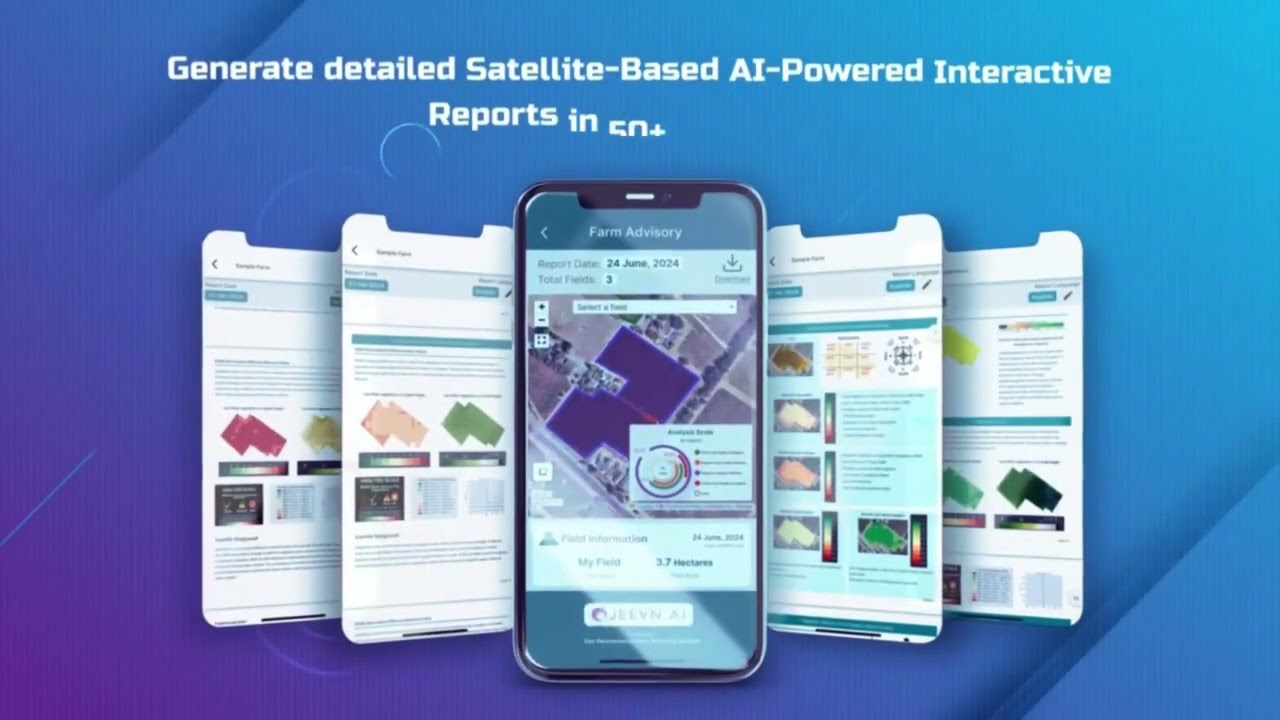
- ✔ Jeevn AI Advisory: Weather, crop, and risk alerts.
- ✔ Blockchain Traceability: Records across agricultural and mining supply chains via product traceability.
- ✔ Fleet Management: Real-time tracking via fleet management.
- ✔ Environmental Impact Tracking: Carbon footprinting for compliance reporting.
Accessible via an app (web, Android, iOS) or the Farmonaut API, with developer documentation for teams integrating it into existing farm management systems.
How to Verify These Figures Yourself
Every figure in this article expires eventually. Here’s the durable method for checking whether it’s still current, organized by category so you can spot-check just the segment you care about:
- Seed market share: USDA publishes census data on seed industry concentration roughly every few years, not annually. Search USDA’s Economic Research Service and NASS releases directly, or check whether Seed World has published a newer summary than the 2018–2020 breakdown cited here.
- Equipment company revenue: Go to the company’s own investor relations page for its latest 10-K (U.S.-listed) or annual report (foreign-listed). Fortune 500 rankings republish annually each spring.
- Equipment financing rates: The USDA FSA republishes its direct loan rates monthly at fsa.usda.gov/news-events/news. Commercial lender rates require calling or requesting quotes directly — no public aggregator tracks them.
- Market size and growth-rate forecasts (seed, precision farming, robotics): Mordor Intelligence and DataM Intelligence update these reports periodically; check the report’s own “last updated” date before citing a figure as current.
This method — go to the primary source, check its publication cadence, don’t assume last year’s figure still holds — is the part of this article that won’t go stale even after every number above does.

FAQ
-
What are the largest agricultural companies by revenue?
Among equipment makers, John Deere reported $45.7 billion in fiscal 2025 revenue. Among seed companies, Bayer and Corteva together hold 71.6% of the U.S. corn seed market and 65.9% of the U.S. soybean seed market (USDA census data, 2018–2020), which makes them dominant by market control even where standalone revenue figures aren’t directly comparable across segments. -
Who are the leading agricultural seed companies?
Bayer Crop Science, Corteva Agriscience, and Syngenta, plus BASF for the top-four grouping. Together these four hold 83.9% of the U.S. corn seed market, per USDA data reported by Seed World. -
Which agricultural equipment companies dominate the market?
John Deere and AGCO are the two U.S. equipment manufacturers with Fortune 500-verified revenue; John Deere’s fiscal 2025 revenue was $45.7 billion. CNH Industrial, Kubota, and other global manufacturers don’t appear in U.S. Fortune 500 data and require checking their own investor disclosures directly. -
How do agricultural equipment financing companies set their rates?
The only publicly benchmarked rate is the USDA FSA’s direct operating loan rate — 4.750% as of December 2024, republished monthly. Commercial lenders and manufacturer captive finance arms (like John Deere Financial) price independently based on credit and term; get a quoted APR directly rather than assuming it tracks the FSA rate. -
What companies lead in precision agriculture robotics?
DJI Agriculture and XAG lead in agricultural drone spraying; AgEagle focuses on drone data analytics; Iron Ox and Naïo Technologies lead in ground-based field robotics (hydroponics and autonomous weeding, respectively). The global robotics-in-agriculture market was valued at $23.31 billion, growing at an 18.07% CAGR from 2026 to 2031. -
How can satellite technology complement these companies’ equipment and robotics?
Platforms like Farmonaut provide field-level monitoring that doesn’t require owning a drone or installing ground sensors, useful as a cross-check against equipment-embedded sensor data. -
How do I get started with satellite-based farm monitoring?
Download the Farmonaut app, or integrate directly via the API.
Explore satellite-based farm monitoring at Farmonaut’s platform or integrate directly with the API integration suite.

 eKGIS
 Mostas Tech
 AgroStar
 Native Seeds
 Andex
 FCF India
 Unifrutti Gulf
 Deluxe Conseil
 TVS Electronics
 BW Pipelines
 WICO
 Chimera Innovation
 SkyHarvest
 Polaris Digitech
 Teledarbas

