
Reviewed February 2026 against farmdoc daily (University of Illinois, using USDA NASS data), Arizton, and Research and Markets.
Try it: Run your own numbers →
Table of Contents
- US Tractor Sales: The Current Numbers
- Tractor Telematics Market: Size, Growth, and What’s Driving It
- Why Tractor Prices Have Outrun Sales Volume
- Tractor Sales Near Me: How to Read Local Dealer Inventory
- Tractor Sales Forecast Table Through 2030
- Telematics and Fleet Technology: What’s Actually on Tractors Now
- Tractor Marketing: What Moves Buyers in a Falling Market
- Market Headwinds: Tariffs, Rates, and Aging Fleets
- Telematics ROI Calculator
- Where Satellite Data Fits Into Tractor and Fleet Decisions
- Tractor Market Outlook: What Would Change This Story
- FAQ: Tractor Sales and Telematics
US Tractor Sales: The Current Numbers
US farm tractor sales came in at 195,857 units in 2025 (preliminary), down 9.86% from 217,279 units in 2024, according to farmdoc daily’s analysis of USDA NASS data. That 2024 figure was itself a 13.16% drop from 2023. Two straight double-digit declines have pulled the market well below its recent peak of 317,944 units in 2021 — meaning current volume sits roughly 38% under the post-pandemic high. This isn’t a blip; it’s the third consecutive year of contraction, and it’s the number that should anchor any conversation about the agricultural tractor market right now.
At the same time, the tractor telematics market serving North America is expanding fast: $487.1 million in 2025, projected to reach $2,090 million by 2034, a 17.6% compound annual growth rate, per Research and Markets. That’s the paradox worth understanding — unit sales are shrinking while the technology layer riding on top of each unit is growing at double-digit rates. The rest of this article works through both halves of that story with sourced numbers, not impressions.
US tractor unit sales are contracting for a third straight year, yet the tractor telematics market in North America is compounding at 17.6% annually through 2034. Buyers are replacing fewer machines but equipping the ones they keep with more sensors and connectivity.
Tractor Telematics Market: Size, Growth, and What’s Driving It
“Tractor telematics” covers the onboard hardware and software that reports a machine’s location, engine hours, fuel burn, fault codes, and field performance back to a dealer or farm-management platform in real time. Research and Markets sizes the North American farm equipment telematics market at $487.1 million in 2025, growing to $2,090 million by 2034 — a 17.6% CAGR over that nine-year window. That’s more than a fourfold increase in market value while unit sales of the tractors themselves are falling.
Telematics doesn’t sit in isolation — it’s the connective layer of the broader precision agriculture market. Arizton and Mordor Intelligence put the North America precision agriculture market at $4.10 billion in 2025, forecast to reach $6.46 billion by 2032. Mordor Intelligence also reports that North America holds 38% of the global precision agriculture telematics market as of 2024, making it the largest single regional block ahead of Europe and Asia-Pacific.
Why the growth despite fewer new tractors sold? Three reasons show up consistently in the data:
- Retrofitting the existing fleet. With sales volume down and replacement cycles stretching, farms are adding telematics kits to tractors they already own rather than waiting for a new-machine purchase to get the data.
- Capital discipline. USDA’s Economic Research Service reports US farm capital equipment expenditures of $53 billion in 2025. When that budget has to stretch further, spending shifts toward software and sensors that extend the life and utilization of existing iron, rather than new sheet metal.
- Precision agriculture adoption climbing independent of unit sales. The $4.10B-to-$6.46B North America precision ag trajectory (2025-2032, Arizton/Mordor Intelligence) tracks acres under some form of guided or monitored management, not machine counts — so it keeps growing even as the tractor count shrinks.
- Try it: Run your own numbers
For readers evaluating Farmonaut Fleet Management Tools, this is the practical takeaway: telematics investment and new-tractor purchase decisions are now separate line items on a farm’s budget, not a bundled one.

Why Tractor Prices Have Outrun Sales Volume
Part of the sales decline traces directly to price. farmdoc daily’s analysis of USDA Agricultural Prices data shows that the price of a 200-horsepower tractor rose 287% between 1990 and 2024. That’s not a recent spike — it’s a 34-year compounding trend — but it accelerated enough in the past few years that many operators are stretching replacement cycles rather than trading in on schedule.
Put another way: a farm that budgeted for a new 200-hp tractor every seven years in the 1990s now faces a unit cost nearly four times higher in real dollar terms, even before financing costs. That single figure explains more of the sales slowdown than any single external shock — it’s a structural affordability shift, and it’s why used and certified pre-owned units, along with the retrofitted telematics on them, are absorbing more of the demand that would once have gone to new-tractor sales.
| Metric | 2021 | 2024 | 2025 (preliminary) |
|---|---|---|---|
| US tractor sales volume (units) | 317,944 | 217,279 | 195,857 |
| Year-over-year change | — | -13.16% (vs. 2023) | -9.86% (vs. 2024) |
| 200-hp tractor price change | +287% cumulative, 1990-2024 | ||
Source: farmdoc daily (University of Illinois), citing USDA NASS and USDA Agricultural Prices data, published February 2026: farmdocdaily.illinois.edu.
Tractor Sales Near Me: How to Read Local Dealer Inventory
National figures explain the trend, but they can’t tell you what’s sitting on a specific dealer’s lot this week — that data isn’t published at the state or dealership level by USDA NASS. Here’s the method to get a current, local read instead of relying on a stale national average:
- Check dealer floor-plan signals. farmdoc daily’s reporting notes dealer sentiment and inventory levels as part of its ongoing coverage — rising dealer inventory typically means more negotiating room; tight inventory means less. Read the current inventory commentary directly at the source rather than a secondhand summary: farmdoc daily’s farm machinery market update.
- Pull the monthly NASS release. USDA NASS publishes tractor sales data monthly, generally within about 30 days of month-end, via nass.usda.gov/quickstats. That’s the freshest official national number available at any given time — check it before quoting last year’s annual figure as current.
- Compare horsepower class, not just sticker price. Given the 287% price run-up on 200-hp units since 1990, ask any dealer for the horsepower-class breakdown of what’s in stock — a lower sticker price on a smaller-horsepower unit isn’t the same deal as a comparable trade-in on your existing class.
- Ask what telematics come standard versus retrofitted. With the North American telematics market scaling toward $2,090 million by 2034, the connectivity package is increasingly a separate negotiating line — confirm whether it’s bundled or an add-on before comparing prices across dealers.
This is a durable checklist: it works whether tractor sales are up or down next quarter, because it points you at the primary sources instead of a number that ages the moment it’s published.
Before visiting a dealer, pull the most recent USDA NASS monthly release for tractor sales and read the current farmdoc daily commentary on dealer inventory. Walking in with the current national trend gives you a stronger negotiating position than relying on last year’s headline number.

Tractor Sales Forecast Table Through 2030
Arizton forecasts US tractor unit shipments will reach 245,050 units by 2030, implying a 2.03% compound annual growth rate for unit shipments over the 2024-2030 period. Read that forecast carefully against the sales figures above: shipments and retail sales are measured differently (shipments reflect what manufacturers ship to dealers, sales reflect what moves off dealer lots to end buyers), so a modest shipment recovery projected for the back half of this decade doesn’t contradict the two consecutive years of retail sales decline reported by farmdoc daily for 2024 and 2025.
| Indicator | Figure | Period | Source |
|---|---|---|---|
| US tractor sales (actual) | 217,279 units → 195,857 units | 2024 → 2025 (prelim.) | farmdoc daily / USDA NASS |
| US tractor shipment forecast | 245,050 units | By 2030 | Arizton |
| Unit shipment CAGR | 2.03% | 2024-2030 | Arizton |
| NA telematics market | $487.1M → $2,090M | 2025 → 2034 | Research and Markets |
| NA precision ag market | $4.10B → $6.46B | 2025 → 2032 | Arizton / Mordor Intelligence |
Full methodology and underlying assumptions for the shipment forecast are in Arizton’s US Tractors Market report; check that page directly for any published update before citing the 245,050-unit figure as current, since market-report firms typically refresh projections annually.
Telematics and Fleet Technology: What’s Actually on Tractors Now
The technology driving the telematics market’s 17.6% CAGR isn’t speculative — it’s a specific set of capabilities now standard on new mid-to-large tractors and increasingly retrofitted onto older ones:
- 🚜 GPS-enabled auto-steering: Reduces overlap and skip in field passes, a direct input cost saving that shows up in fuel and input-application budgets.
- 📡 Telematics and IoT reporting: Engine hours, fault codes, location, and fuel burn stream to a dashboard or app. This is the core driver of the North American telematics market’s growth from $487.1M (2025) toward $2,090M (2034). Farms layering satellite-based fleet oversight on top of onboard telematics can review Farmonaut Fleet Management Tools for combined field-and-machine visibility.
- 🤖 Predictive maintenance: Fault-code pattern recognition flags likely failures before a breakdown during planting or harvest windows, when downtime cost is highest.
- 📊 Data-driven decision support: Precision ag platforms that consume telematics feeds alongside satellite and soil data — the layer behind the $4.10B-to-$6.46B North America precision agriculture trajectory.
Comparing telematics subscription costs against last year’s tractor price without checking the current USDA Agricultural Prices release understates the real cost gap. Given the 287% cumulative increase in 200-hp tractor prices since 1990, always re-check the latest monthly Agricultural Prices data before budgeting a purchase.
Tractor Marketing: What Moves Buyers in a Falling Market
With unit sales down 9.86% in 2025 on top of a 13.16% drop in 2024, dealers and manufacturers are marketing differently than they did during the 2021 peak of 317,944 units. Three shifts stand out in how tractor marketing is being positioned now:
- Total cost of ownership over sticker price. With the 287% price increase on 200-hp units since 1990 impossible to market around, messaging leans on financing terms, resale value, and telematics-driven uptime rather than the base price alone.
- Retrofitting as the pitch, not just new-unit sales. Since telematics revenue growth (17.6% CAGR to 2034) is outpacing unit sales growth, marketing budgets are shifting toward selling connectivity upgrades to owners of the existing fleet — a lower-cost conversion than a full tractor sale.
- Precision ag bundling. Positioning a tractor purchase alongside the broader $4.10B-to-$6.46B North America precision agriculture market gives buyers a reason to upgrade beyond raw horsepower — yield-mapping, variable-rate application, and satellite-fed field data become part of the sales conversation.
For farms and dealers building their own outreach, the API-first approach lets marketing and fleet tools plug satellite field data directly into buyer-facing dashboards — see the Farmonaut API and the API Developer Docs for the technical integration path.
Market Headwinds: Tariffs, Rates, and Aging Fleets
farmdoc daily’s February 2026 analysis frames the current downturn explicitly around “tariff headwinds” alongside the sales and inventory data — meaning trade policy is cited as a contributing factor in the reporting alongside price and financing pressure. Rather than restate a specific tariff rate that could change before this is read, the durable approach is to check the source directly for the current tariff situation each time you need it: farmdoc daily’s full analysis is updated as conditions change.
- Affordability: The 287% cumulative price increase on 200-hp tractors (1990-2024) is the single largest structural headwind to replacement-cycle sales.
- Two years of declining volume: -13.16% in 2024, -9.86% in 2025 (preliminary) — a trend, not a one-year anomaly.
- Aging fleet economics: As replacement slows, more of the working fleet ages past typical trade-in windows, which is part of why telematics retrofitting is growing faster than new-unit sales.
- Capital allocation pressure: $53 billion in US farm capital equipment expenditures for 2025 (USDA ERS) has to cover tractors, telematics, precision ag tools, and other equipment — a fixed pool being split more ways.
None of these are static. USDA NASS refreshes tractor sales monthly; USDA’s Agricultural Prices index updates monthly, generally released mid-month for the prior month; and market-report firms like Research and Markets and Mordor Intelligence typically issue updated annual reports in Q1/Q2. Re-check each before relying on the figures in this article a year from now.

Unlock scalable satellite, AI, and analytics tools for agricultural monitoring:
Telematics ROI Calculator
Use your own fleet size and downtime history to see where a telematics investment breaks even, based on the North American market data cited above.
Run your own numbers
Assumptions: this calculator assumes downtime cost and reduction percentage are constant across all tractors in the fleet and does not account for installation costs, financing, or telematics hardware purchase price — only the ongoing subscription. It excludes any tax treatment or depreciation effects. Adjust every field to your own fleet’s numbers; the defaults are illustrative starting points, not benchmarks.
Where Satellite Data Fits Into Tractor and Fleet Decisions
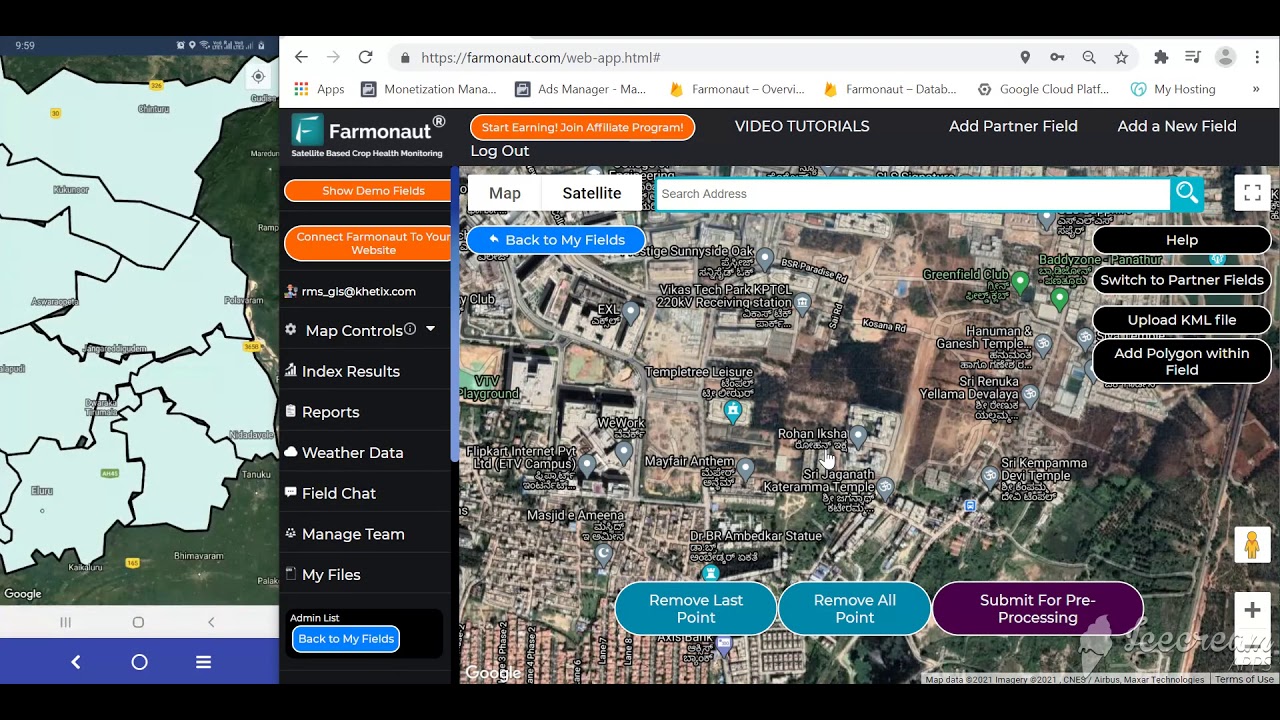
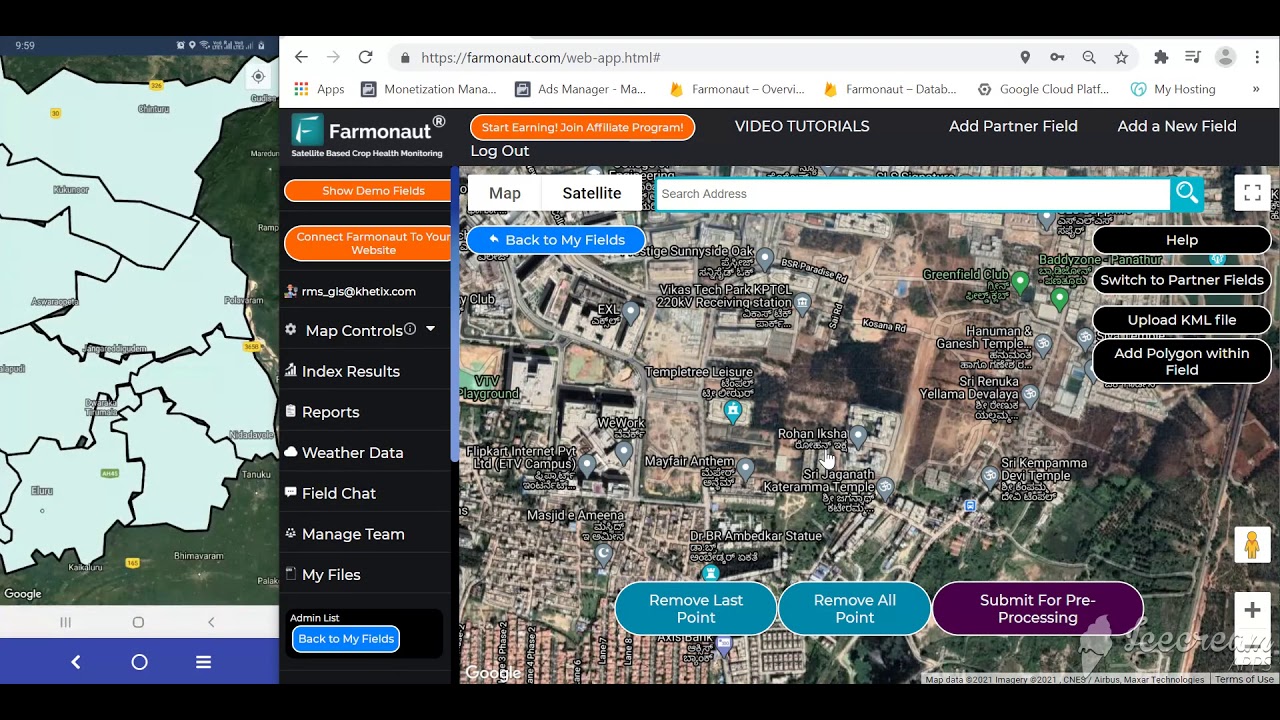
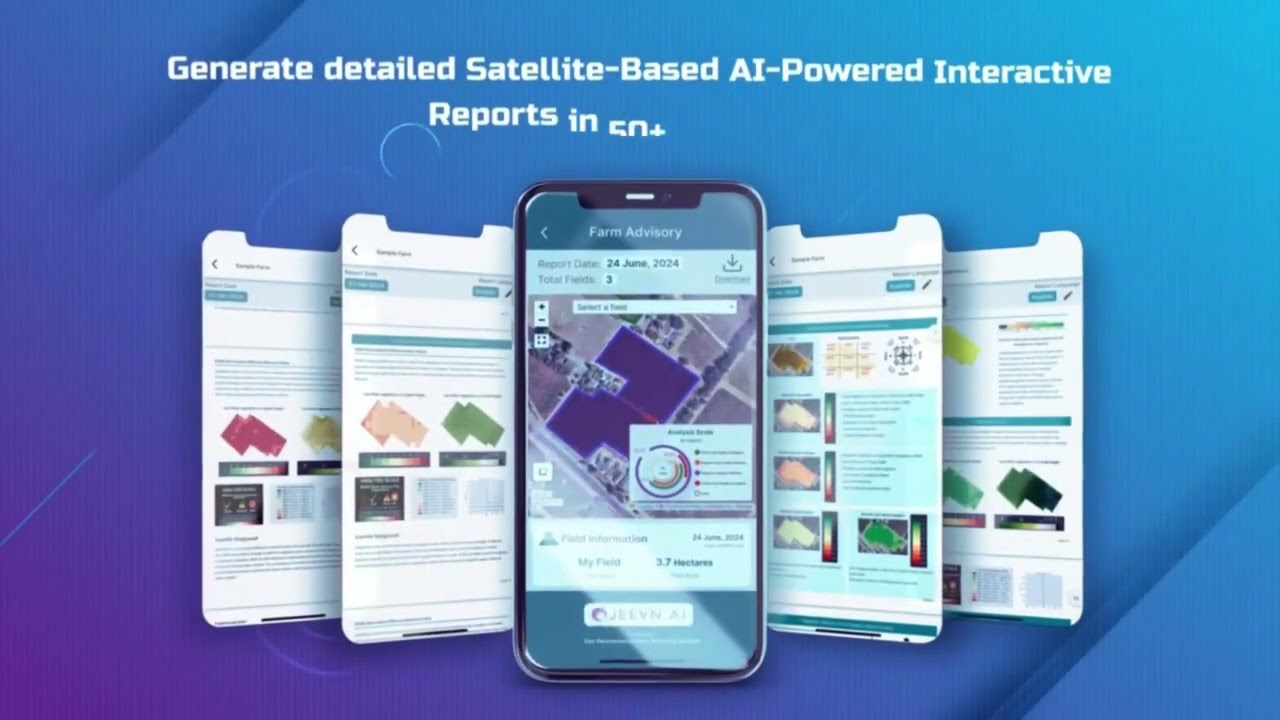
Tractor telematics reports what a machine is doing. Satellite monitoring reports what the field underneath it needs. Farmonaut combines multispectral satellite imagery with fleet and resource tools so tractor and machinery decisions are grounded in current field conditions rather than a fixed schedule.
- 🌾 Real-Time Monitoring: Multispectral satellite imaging tracks field and crop status, supporting optimal machinery use and timing.
- 🛰 Jeevn AI Insights: Advisories for planting, irrigation, and resource deployment that inform when and where fleet capacity is actually needed.
- ⚙ Fleet Management: Satellite and IoT data for scheduling, fuel-use optimization, and maintenance planning — see the Fleet Management Overview.
- 🪙 Blockchain Traceability: Field-to-market transparency for tractor-powered harvests, via Traceability Solutions.
- 🌎 Environmental Compliance: Carbon footprint measurement (Carbon Footprinting Solutions) and resource-use tracking that pairs with equipment efficiency data.
Farms financing new equipment can also use satellite-based field verification for lending and coverage decisions — see Crop Loan and Insurance Satellite Verification for how field data supports access to credit and risk assessment tied to machinery investment.
Explore the Large-Scale Farm Management Dashboard for combined satellite and fleet visibility across an operation’s tractors and fields.

Integrate the Farmonaut API for satellite-based crop, resource, and fleet data inside existing dealer or farm-management software — see the API Developer Docs for endpoints and authentication.
Tractor Market Outlook: What Would Change This Story
The current trajectory — two years of falling retail sales (217,279 units in 2024, 195,857 in 2025 preliminary) against a growing telematics and precision ag technology layer — is not fixed. Here’s what would actually move it, and where to check:
- A reversal in tractor sales volume would show up first in USDA NASS’s monthly releases at nass.usda.gov/quickstats, well before any annual report reflects it.
- A change in the 287% cumulative price trend would appear in USDA’s monthly Agricultural Prices index — a deceleration or reversal there would be the leading indicator for any sales recovery.
- Tariff policy shifts cited in farmdoc daily’s February 2026 analysis could ease or worsen the headwind; that source is the one to re-check rather than a general news search, since it ties tariff commentary directly to the sales and inventory data.
- Telematics market deceleration below the 17.6% CAGR Research and Markets forecasts for 2025-2034 would signal either market saturation or a pullback in ag-tech capital spending — worth checking against their published updates.
- Arizton’s 245,050-unit 2030 shipment forecast becoming public knowledge as either on-track or revised would be visible in their report updates, typically issued annually.
This is a continuing story, not a snapshot: the specific numbers above are only as good as their last refresh. Treat the sources linked throughout this article — not this page’s numbers alone — as the ongoing reference point.
OEM market share by brand, state-level tractor adoption rates, and the current percentage of the US tractor fleet running telematics are not published by USDA or the government sources cited here — they exist only in proprietary industry reports with restricted access. Treat any specific brand-share or adoption-percentage figure you see elsewhere with that gap in mind, and verify its source before relying on it.



FAQ: Tractor Sales and Telematics
195,857 units in 2025 (preliminary figure), down 9.86% from 217,279 units in 2024, per farmdoc daily’s analysis of USDA NASS data. USDA NASS publishes updated monthly figures at nass.usda.gov/quickstats, typically within 30 days of month-end — check there for the most current count.
$487.1 million in 2025, projected to reach $2,090 million by 2034 — a 17.6% compound annual growth rate, according to Research and Markets.
The price of a 200-horsepower tractor rose 287% between 1990 and 2024, per farmdoc daily’s analysis of USDA Agricultural Prices data. That cumulative increase is a major factor behind the recent decline in unit sales, as farms stretch replacement cycles.
USDA doesn’t publish dealer-level inventory. Check farmdoc daily’s ongoing dealer-sentiment and inventory commentary for the national trend, then ask individual dealers for their current floor-plan levels and horsepower-class breakdown directly.
Arizton forecasts US tractor unit shipments will reach 245,050 units by 2030, a 2.03% CAGR for 2024-2030. This shipment figure is separate from retail sales volume, which fell in both 2024 and 2025.
Scalable, subscription-based satellite, AI, and traceability solutions billed monthly or annually, for individual farmers, agribusinesses, and government agencies.

 Crossprod
 Aamoksh One Eighty
 Patrick America
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC
 AgroGreen Dynamics
 AgroRisk
 Oath Inc
 Reddane Farming
 Esri North East Africa
 Cresol
 MDCV UK
 Zerella Group
 Etech Consulting Madagascar
 Vestlandsforsking
 Delicio
 WB Dev
 Sama Premium

