

Table of Contents
- Introduction: Irrigated Farmland Investment
- What “Irrigated Land” Actually Means
- Benefits of Irrigated Row Crop Farmland
- Why Institutional Farmland Investors Favor Irrigated Acres
- Farmland Investment Newsletters & Where the Data Comes From
- Technology Reshaping Irrigated Farming Productivity
- Comparison: Irrigated vs. Non-Irrigated Farmland
- Calculator: Irrigated Cash Rent Premium
- Water Management & Sustainable Practices
- How Farmonaut Supports Irrigated Farmland Monitoring
- FAQ: Irrigated Farmland Investment
- Conclusion
Reviewed August 2026 against USDA NASS (Irrigation and Water Management Survey, Land Values and Cash Rents) and USDA ERS.
Try it: Run your own numbers →
Irrigated Farmland Investment: Yields, ROI & Rent Data
Irrigated cropland in the United States covers 53.1 million acres across 212,714 farms, and it produces more than half of the country’s total crop sales value from under 17% of harvested cropland, according to USDA’s 2023 Irrigation and Water Management Survey. Irrigated cropland rents for $244 an acre nationally against a $5,830-an-acre average land value, per USDA’s 2025 Land Values and Cash Rents report. This article lays out what irrigated farmland investment actually returns, how it’s priced relative to rainfed acres, and how to verify the numbers yourself before committing capital.
Irrigated farmland investment sits at the intersection of two separate questions: does the water access pay for itself, and is the land priced to reflect that. Both have documented answers from USDA’s National Agricultural Statistics Service (NASS) and Economic Research Service (ERS), which we cite throughout rather than estimate.
What “Irrigated Land” Actually Means
Irrigated land means cropland where water is applied through built infrastructure — center-pivot, drip, flood, or sprinkler systems — rather than relying solely on rainfall. The distinction matters for buyers because it changes both what a parcel can grow and what it’s worth. Non-irrigated (rainfed or “dryland”) acres depend entirely on precipitation timing, which is exactly the variable irrigation exists to remove.
Key Components of an Irrigated Farming System
- Controlled Water Delivery: Water is applied on a schedule set by the operator, not by weather. US farms applied 81 million acre-feet of water to irrigated cropland in 2023, per the same USDA NASS survey.
- Technology Integration: Drip, sprinkler, and center-pivot systems each trade off capital cost against water-use precision; a full breakdown of infrastructure cost and depreciation by technology type isn’t centralized in any public USDA dataset — request quotes from an irrigation equipment dealer or NRCS office for a site-specific figure.
- Supplementing Rainfall, Not Replacing It: Even irrigated fields depend on rainfall for a share of crop water needs; irrigation fills the gap precipitation leaves.
- Geographic Flexibility: Irrigation lets an operator grow water-intensive row crops in regions where rainfall alone wouldn’t support them — half of all US irrigated acres sit in just five states: Arkansas, California, Idaho, Nebraska, and Texas, according to USDA NASS’s Farm and Ranch Irrigation Survey program.
- Try it: Run your own numbers
The concentration of irrigated acreage in a handful of states is itself a data point worth acting on: an investor evaluating “irrigated farmland” as an asset class is really evaluating water rights and aquifer or river-basin access in a short list of regions, not a uniform national category.
Benefits of Irrigated Row Crop Farmland
The benefits of irrigated row crop farmland show up in three measurable places: yield, revenue concentration, and long-run yield trend — not just in qualitative claims about “resilience.”
1. A Documented Yield Gap
Irrigated cropland yields 2.7 times more than rainfed cropland on average, a gap that has widened over a 65-year trend tracked by the University of Nebraska in partnership with the Kansas City Federal Reserve (research.unl.edu). That’s not a one-season anomaly — it’s a multi-decade divergence, meaning the yield advantage of irrigated land has been growing rather than converging as dryland genetics and practices improve.
2. Outsized Share of Crop Sales Value
Irrigated farms generated more than 50% of total US crop sales value while sitting on less than 17% of harvested cropland acres, per the 2022 Census of Agriculture as summarized by USDA ERS. That ratio — three times the revenue concentration per acre relative to the rest of US cropland — is the clearest single number for why irrigated ground trades at a premium.
3. Multiple Cropping Cycles Where Climate Allows
- Extended Growing Windows: Controlled water supply supports multiple cropping cycles in regions where the frost-free season and water access both allow it.
- Crop Diversification: Reliable water access supports corn, soybeans, wheat, and cotton — the row crops that dominate irrigated acreage in Nebraska, Texas, and the California Central Valley.
4. Reduced Production Risk
The 212,714 US farms with irrigated acreage aren’t exposed to the same single-point-of-failure that a missed rainy season creates on dryland ground. That’s a structural risk reduction, not a marketing claim — it’s the mechanical result of controlling the water input directly rather than depending on precipitation timing.
5. Soil Health Effects Cut Both Ways
Well-managed irrigation — applied on a schedule matched to crop need — helps prevent the erosion associated with rainfall-dependent systems. Poorly managed irrigation carries its own risk of salinity build-up, which is why scheduling technology (covered below) matters as much as water access itself.
6. Land Value and Rent Premium
Irrigated cropland carries roughly a 53% price premium over comparable non-irrigated parcels, according to farmland-finance data compiled by FBN. National average irrigated cash rent stood at $244 an acre in 2025, but that figure spans a wide state range — from $80 an acre in Wyoming to $483 an acre in California, per USDA NASS. That six-fold spread means “irrigated cropland” quoted as a single national average tells you almost nothing about what a specific parcel should rent for — the state figure is the number to check.



Why Institutional Farmland Investors Favor Irrigated Acres
Institutional farmland investment — pension fund allocations, farmland REITs, and private equity vehicles — has gravitated toward irrigated row-crop ground for reasons that show up directly in the USDA data above, not just in investor sentiment.
1. Documented Long-Run Farmland Returns
US farmland overall has returned an average of 10% annually since 1990, tracked by the NCREIF Farmland Index and reported by AcreTrader. That figure covers all farmland, irrigated and non-irrigated combined — the irrigated share of that return is not separately published as a portfolio-level IRR or cash-on-cash figure by NCREIF or USDA, so an investor comparing irrigated-specific returns should build the estimate from the rent and value figures above (cash rent ÷ purchase price, adjusted for the state-level premium) rather than look for a single quoted “irrigated ROI” number, since none is published at that granularity.
2. Revenue Concentration Lowers Perceived Risk
The same >50% of crop sales value from <17% of cropland ratio (USDA ERS) that makes irrigated land attractive to farmers also makes it attractive to allocators who need a farmland book with predictable cash flow: fewer acres are doing more of the revenue work, and that revenue is buffered against the single largest driver of row-crop variance — rainfall timing.
3. A Shrinking, Not Growing, Supply
US irrigated cropland fell to 55 million acres in the 2022 Census of Agriculture — the lowest level since 1992 — per USDA ERS. A shrinking base of irrigated acreage against level or rising demand for the row crops it produces is a supply-constraint argument institutional buyers watch closely; it’s also a reason the state-by-state cash rent premium ($80 to $483 an acre, cited above) is worth re-checking each year rather than assumed static.
4. Technology Access for Portfolio Monitoring
Firms managing scattered irrigated parcels across several states increasingly rely on satellite data and remote monitoring rather than site visits alone to track crop condition and water stress across a portfolio — a capability covered in the technology section below.
5. Lower Correlation to Equity and Bond Markets
Farmland’s return profile — anchored in crop revenue and land appreciation rather than public-market sentiment — is the main reason it appears in institutional alternative-asset allocations alongside real estate and infrastructure. The 10% NCREIF long-run average cited above is the benchmark most farmland allocators size their return expectations against.
Farmland Investment Newsletters & Where the Data Comes From
Anyone tracking farmland investment newsletters will notice most recycle the same handful of primary sources rather than generate original data. Knowing those sources directly lets you skip the newsletter layer and check the numbers yourself, on the actual publication schedule:
- USDA NASS Land Values and Cash Rents: the source for the $5,830/acre cropland value and $244/acre irrigated cash rent figures cited above. Published annually every August at nass.usda.gov/Publications/Highlights — filter by year for the current release.
- USDA NASS Irrigation and Water Management Survey: the source for the 53.1 million irrigated acres and 81 million acre-feet figures, published at nass.usda.gov/Newsroom on a periodic cycle tied to the Census of Agriculture.
- USDA ERS Charts of Note: shorter-form analysis pieces, including the irrigated-share-of-crop-sales chart at ers.usda.gov, updated as new Census of Agriculture data is released (most recently 2022 data).
- NCREIF Farmland Index: the institutional benchmark for farmland total returns, summarized by services like AcreTrader.
A newsletter that cites a number without linking to one of these primary releases is passing along someone else’s interpretation, not the underlying data — worth checking before acting on the figure.
Technology Reshaping Irrigated Farming Productivity
The gap between the 2.7x irrigated yield multiplier as a raw average and what an individual parcel actually achieves comes down to how precisely water is scheduled and monitored. These are the technology categories doing that work today.
1. Smart Irrigation Scheduling
- Soil moisture sensors and controller software apply water on a schedule matched to measured crop need rather than a fixed calendar, reducing the over- and under-watering that drives both wasted input cost and yield loss.
- Weather-model integration lets scheduling adjust in real time as forecast conditions change, rather than on a fixed rotation.
- Solar-powered pumps are reducing the operating-cost side of irrigation, independent of water-use efficiency gains.
2. Satellite-Driven Crop and Water-Stress Monitoring
- Multispectral satellite imagery flags water stress, nutrient deficiency, and pest pressure before they’re visible on the ground, giving operators a lead window to act.
- Platforms including Farmonaut make this monitoring available to operations of any size, not only large-scale irrigated operations with dedicated agronomy staff.
3. Blockchain & Traceability
Blockchain-based tracking gives irrigated-crop buyers and processors a verifiable record from field to delivery, which matters increasingly for high-value row crop and specialty buyers requiring supply-chain documentation. Farmonaut’s traceability services apply this to irrigated operations directly.
4. Data Analytics & Advisory Systems
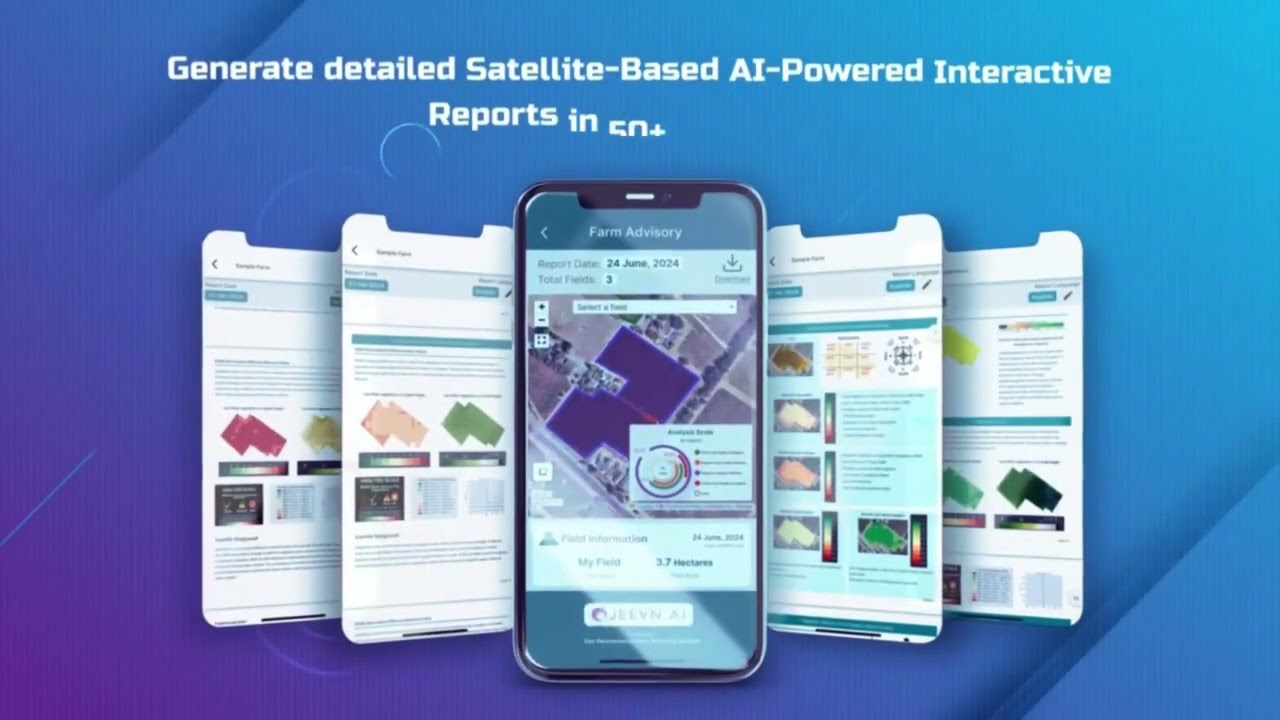
Farmonaut’s Jeevn AI Advisory System combines satellite and weather inputs to generate irrigation-scheduling and risk recommendations specific to a field’s measured condition, rather than a regional average.
5. Environmental Impact Tracking
Digital carbon and resource-use tracking — such as Farmonaut’s carbon footprint monitoring — is increasingly a documentation requirement for institutional buyers and sustainability-linked lenders, not just a voluntary add-on.
6. Farm Logistics & Resource Management
Fleet and resource management tools reduce the operational downtime that erodes the yield advantage irrigation is meant to deliver. Farmonaut’s fleet management platform applies this to irrigated row-crop operations specifically.
Comparison: Irrigated vs. Non-Irrigated Farmland
Here is the direct comparison using only the figures verified above. Where a data point isn’t published at this granularity, that’s stated rather than estimated.
| Metric | Irrigated Cropland | Non-Irrigated (Rainfed) Cropland |
|---|---|---|
| Yield multiplier | 2.7x rainfed baseline (65-year trend) | Baseline (1.0x) |
| Share of US crop sales value | >50% of total value | <50% of total value, from >83% of cropland acres |
| Share of harvested cropland acres | <17% | >83% |
| Total US acreage (2022 Census) | 55 million acres (lowest since 1992) | Remaining share of ~390M harvested cropland acres |
| Average cash rent (national, 2025) | $244/acre | Lower than irrigated; not separately itemized in this brief — see state NASS tables |
| Land value premium | ~53% above comparable non-irrigated parcels | Baseline |
| State cash rent range (2025) | $80/acre (Wyoming) to $483/acre (California) | Varies by state; check USDA NASS state tables directly |
The table makes one thing explicit that a single blended national average hides: irrigated land’s revenue advantage (>50% of value from <17% of acres) is a national aggregate, while the rent premium ($80 to $483 an acre) is a state-by-state figure — comparing a specific parcel requires the state number, not the national one.
Calculator: Irrigated Cash Rent Premium
Enter a parcel’s acreage and purchase price alongside the state irrigated cash rent to estimate the annual rent-to-price yield and compare it against the national irrigated average.
Assumptions: this calculator computes a simple rent-to-price yield (annual cash rent ÷ purchase price) and the rent premium in dollars over a comparable non-irrigated parcel. It excludes irrigation infrastructure capital cost, well or water-rights fees, property tax, financing cost, and land appreciation — none of which are centralized in a single public dataset for arbitrary parcels. Use the national ($244/acre) or state-level ($80–$483/acre) 2025 USDA NASS irrigated cash rent figures as your starting input, then substitute your state’s published number.
Water Management & Sustainable Practices
Irrigated farmland’s yield advantage depends on managing the water input well, not just having access to it. These are the practices that determine whether a parcel captures the full 2.7x yield multiplier or falls short of it.
1. Precision Scheduling & Conservation
Sensor-driven scheduling irrigates only when and where crop need is measured, rather than on a fixed rotation — the single biggest lever on both water cost and yield consistency.
2. Integrated Water Resource Management
Combining surface and groundwater sources, recycling, and on-farm storage reduces exposure to any single water source running short — relevant given that half of US irrigated acreage sits in five states (Arkansas, California, Idaho, Nebraska, Texas) where water-rights administration varies significantly.
3. Soil Health Conservation
Controlled traffic farming, rotational cropping, and cover crops paired with disciplined irrigation scheduling prevent the salinity build-up that over-irrigation can cause.
4. Environmental Impact Monitoring
Digital reporting of water use and emissions supports regulatory compliance in states with active groundwater management rules, and increasingly supports access to sustainability-linked financing.
5. Crop Insurance & Risk Management
Affordable insurance and financing reduce downside exposure even on irrigated ground, where crop failure risk is lower but not zero. Farmonaut’s Crop Loan & Insurance services apply satellite data to loan and insurance assessment.
6. Water Productivity — the Published Gap
Water productivity (crop yield per acre-foot applied) is the metric investors most want at the individual-crop, individual-region level, and it’s the metric least available in a single US public dataset — it appears more often in academic literature and FAO cross-country comparisons than in a standing USDA table. For a site-specific figure, pair the applied-water data in USDA’s Irrigation and Water Management Survey with your own yield records rather than relying on a single published national ratio.
Developer Docs for Farmonaut’s Satellite & Weather API provide quick, robust integration of live farm, crop, and water data.
How Farmonaut Supports Irrigated Farmland Monitoring
Farmonaut’s platform is built to close the gap between the USDA-level averages above and what’s happening on a specific irrigated parcel this week — using satellite imagery, AI advisory, and blockchain traceability tools.
Key Offerings for Irrigated Operations
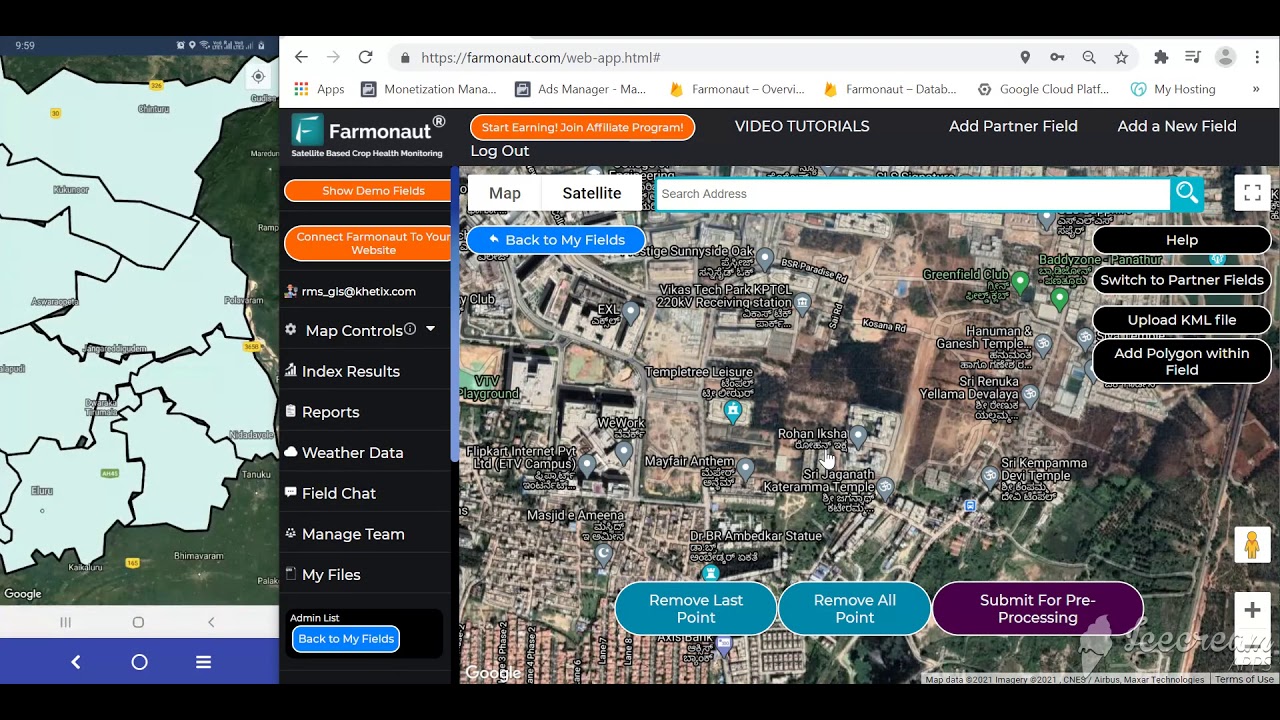
- Satellite-Based Crop Monitoring: Continuous insight into crop growth, soil health, water efficiency, and stress points across large-scale portfolios (Large-Scale Farm Management on Farmonaut).
- AI-Driven Farm & Irrigation Advisory: Jeevn AI generates irrigation scheduling and water-conservation recommendations from measured field conditions.
- Blockchain-Enabled Traceability: Traceability tools for secure, transparent tracking of irrigated-crop output from field to buyer.
- Real-Time Resource Management: Fleet and machinery tracking across irrigated operations (Fleet Management for Agriculture).
- Environmental Impact Assessment: Carbon and resource-use monitoring (learn more here) to support compliance and green-finance access.
The platform is available via Android, iOS, and web — letting individual operators and institutional portfolio managers apply the same monitoring standard across scattered irrigated holdings.
FAQ: Irrigated Farmland Investment
Q1: What does “irrigated land” mean in USDA data?
USDA classifies land as irrigated when water is applied through built infrastructure — pivot, drip, flood, or sprinkler systems — supplementing rainfall. The 2023 count stood at 53.1 million acres across 212,714 US farms, per USDA NASS; the 2022 Census of Agriculture put total irrigated cropland at 55 million acres, the lowest since 1992, per USDA ERS.
Q2: How much does irrigated farmland cost to rent versus buy?
National average irrigated cropland cash rent was $244/acre in 2025 against a $5,830/acre average cropland value, per USDA NASS. State rent ranges from $80/acre (Wyoming) to $483/acre (California) — check the state table directly since the national figure blends widely different regional markets.
Q3: How much higher is the yield on irrigated versus rainfed cropland?
2.7 times higher, based on a 65-year trend tracked by the University of Nebraska with the Kansas City Federal Reserve (research.unl.edu). That gap has widened, not narrowed, over the tracked period.
Q4: Is irrigated farmland investment only for institutional investors?
No. Institutional buyers favor irrigated ground for its documented revenue concentration (over 50% of US crop sales value from under 17% of cropland acres, per USDA ERS), but the same USDA data and satellite monitoring tools — including Farmonaut’s platform — are equally usable by individual landowners and smaller operations evaluating a single parcel.
Q5: What crops are grown on irrigated row crop farmland, and where?
Corn, soybeans, wheat, and cotton dominate US irrigated row-crop acreage, concentrated in Arkansas, California, Idaho, Nebraska, and Texas — the five states holding half of all US irrigated acres per USDA NASS’s Farm and Ranch Irrigation Survey.
Q6: Where can I check current irrigated cash rent and land value figures myself?
USDA NASS publishes Land Values and Cash Rents every August at nass.usda.gov/Publications/Highlights — filter to the current year for the latest release rather than relying on any single article’s snapshot.
Conclusion
The case for irrigated farmland investment rests on three published numbers: a 2.7x yield multiplier over rainfed cropland (University of Nebraska / Kansas City Federal Reserve), a revenue concentration of over 50% of US crop sales value from under 17% of harvested cropland (USDA ERS), and a national cash rent of $244/acre that ranges from $80 to $483/acre by state (USDA NASS, 2025). None of these figures require restating from memory next year — each source publishes on a fixed schedule (NASS Land Values and Cash Rents every August; ERS Charts of Note as new Census of Agriculture data lands), so the reader’s fastest path to a current number is the source link, not this page.
What doesn’t expire is the method: check the state-level rent figure against the national average before pricing a specific parcel, verify the irrigated acreage trend in your target region against USDA ERS before assuming supply is stable, and treat any newsletter figure without a primary-source link as secondhand. Combined with satellite-based monitoring tools like Farmonaut’s platform, that discipline is what separates an irrigated farmland investment priced on real data from one priced on a rounded-off multiple.

 Crossprod
 Aamoksh One Eighty
 Patrick America
 Liquify Digital
 CU Foods
 BeyondTech Global
 Rouge VC
 AgroGreen Dynamics
 AgroRisk
 Oath Inc
 Reddane Farming
 Esri North East Africa
 Cresol
 MDCV UK
 Zerella Group
 Etech Consulting Madagascar
 Vestlandsforsking
 Delicio
 WB Dev
 Sama Premium

