

Machinery · Lease guide
Farm Equipment Leasing: Costs, Terms, Lease Calculator
Farm equipment leasing usually runs three to five years often with a lower payment than a loan, but the dealer or lessor keeps the title. In Kansas State’s 2010 combine example, buying still cost less over five years. Compare lessors, terms and tax rules, then test your own quote.
Key takeaways
- A lease typically runs three to five years, and you still pay insurance, fuel and repairs not under warranty (Kansas State University, 2010).
- In one worked 2010 combine example (Kansas State University), the lease payment was $19,782 a year lower than the loan payment, yet buying cost about $10,700 less over five years after tax and resale.
- AgDirect’s posted fixed loan rates for November 2026 ran from 7.25% to 8.75%, a useful check on any lease quote.
- A contract with a nominal buyout may count as a conditional sale, which removes the rent deduction (IRS Publication 225, 2025).
- US tractor sales fell to a preliminary 195,857 in 2025 from 317,944 in 2021 (AEM data via farmdoc, 2026), so compare several quotes.
In this article
- Farm equipment leasing at a glance
- What does it cost to lease farm equipment?
- Who offers farm equipment leasing?
- Lease vs buy: when farm machinery leasing wins
- What do machinery costs look like now?
- Lease terms to check before you sign
- Lease to own and the tax trap
- Farm equipment lease calculator
- How to choose: a six-step process
- Where satellite data fits
- FAQ
Farm equipment leasing lets you use a tractor, combine or planter for a set term, usually three to five years, while the dealer or leasing company keeps ownership, according to Kansas State University’s guide to leasing vs. buying farm machinery. Leasing can lower the yearly payment, but it is not always the cheaper route. In that guide’s worked 2010 combine example, buying beat leasing by about $10,700 over five years once tax and resale were counted.
This guide shows who offers farm machinery leasing, what lease terms to expect, how a lease compares with a loan, a rental and custom hire, and which contract clauses change your tax position. The calculator lets you test your own quote. It is a planning aid, so check the tax points with your accountant before you sign.
Farm equipment leasing at a glance
Four routes can get a machine across your field. The table sets them side by side, based on the definitions in the Kansas State guide.
| Route | Usual length | Who owns it | Who pays repairs and running costs | Fits when |
|---|---|---|---|---|
| Loan and buy | Loan of several years | You | You | You will keep the machine and can use the tax deductions |
| Lease | 3 to 5 years | Dealer or lessor | You, except repairs under warranty | You need a lower payment or plan to trade up often |
| Rental | Days, weeks or months | Rental owner | You pay fuel, labor and routine upkeep; the owner covers major repairs | The job is short or the machine is used rarely |
| Custom hire | One job | Operator | Operator, built into the fee | You lack labor, time or the extra harvest kit |
A lease and a loan feel similar from the cab. In both cases you insure the machine, fuel it, service it and supply the driver. The differences are the title, the tax treatment and what happens on the last day of the contract. Kansas State also notes that a lease generally cannot be cancelled without a penalty, so treat it as a firm commitment for the whole term.
What does it cost to lease farm equipment?
We found no national price list for farm equipment lease rates, though AgDirect, for one, offers its lease residuals as a download. Your quote depends on the machine, its expected resale value, the hours you are allowed, your credit and the lender’s rate that month. So use dated reference points, and treat each one as an example rather than a market average.
A worked combine lease
The Kansas State guide, published in October 2010, compared four ways to harvest 2,300 acres a year for five years. The prices are old, so use the method and not the dollar figures. It assumed a 46.8% marginal tax rate and a $125,000 Section 179 deduction, and the result is sensitive to both.
- Combine price: $317,500, with a loan at 6.9% and 20% down.
- Loan payment: $61,782 a year, with a resale value of $162,000 after five years.
- Lease payment: $42,000 a year for five years, first payment at signing and no buyout at the end.
- Rent: $190 per separator hour for 200 hours a year.
- Custom hire: a base charge of $25 an acre.
The lease payment was about $19,800 a year lower than the loan payment. That is the main appeal of leasing, and it matters if your cash flow cannot carry the larger payment. But after tax, resale value and the timing of each payment, the ranking changed, as the chart shows.
Loan rates to compare against
A lease has a rate built into its payment, even when the contract does not show one. A loan quote gives you something to compare it with. AgDirect’s posted rates for November 2026 show fixed rates from 7.25% on $250,000 or more for up to five years, and up to 8.75% on $5,000 to $24,999 for six to seven years. Its variable rate was 6.50%. These are one lender’s posted rates, subject to credit approval and open to change, so ask for a dated quote of your own.
| Amount financed | Fixed, 2 to 5 years | Fixed, 6 to 7 years | Variable |
|---|---|---|---|
| $250,000 or more | 7.25% | 7.50% | 6.50% |
| $100,000 to $249,999 | 7.50% | 7.75% | 6.50% |
| $25,000 to $99,999 | 7.75% | 8.00% | 6.50% |
| $5,000 to $24,999 | 8.50% | 8.75% | 6.50% |
Tractor rental rates, for short jobs
If you only need a tractor for a season, an hourly rate may be a better comparison than a lease rate. The Texas Custom Rates Survey for 2026 reports what respondents charge for a tractor alone, without operator or fuel. The averages run from $64.32 an hour under 100 hp to $128.15 an hour above 250 hp. Each size class had 20 to 24 responses, and rates ranged widely.
In the Upper Midwest, University of Wisconsin custom rates for 2025 put four-wheel-drive tractors above 175 hp at an average of $117.44 from 9 responses, with reported rates from $50 to $250. In Canada, the Manitoba farm machinery cost guide for 2026/2027 sets out how to build a suggested rental rate from ownership and operating costs. These are survey results and suggested methods, not offers you can book.
Chart
Texas tractor rental rates by size
Average US$ per hour, tractor only, without operator or fuel, survey responses for 2026
Who offers farm equipment leasing?
Lessors fall into three groups. Which one suits you depends on the brand you run, the deal size and whether the machine is new or used. We list examples here, not a ranking. For a wider list of lenders, see our guide to agricultural equipment finance companies.
Manufacturer finance arms
Best for: new machines from one brand, especially during a dealer promotion. John Deere Financial, CNH Capital (Case IH and New Holland) and AGCO Finance (brands such as Massey Ferguson and Fendt) work through the dealer network. AGCO Finance says more than 190,000 farmers in more than 20 countries use its financing, and it runs local sites for the US, Canada, the UK, Australia and New Zealand, among others. Ask your dealer which lease programs apply to the exact model, since offers change often.
Farm lenders and specialist ag finance
Best for: comparing a quote from outside the dealership, or buying used. AgDirect offers loans and leases on new and used ag equipment. Its posted terms say leases are not available under $10,000 and that titled equipment is not eligible for a lease. Farm Credit is a nationwide network of customer-owned cooperatives, with a lender search by ZIP code. Ask your local association whether it offers leases as well as loans.
Local dealers and rental yards
Best for: seasonal needs and service close to home. Ask local dealers whether they run a rental fleet or arrange leases, including for a telehandler or a short-term tractor in a busy season. Check the minimum hours, the delivery charge and what happens if the machine breaks down in the middle of a job.
Krone, Moore, O’Bryan’s and other names people search
Some buyers search for one name rather than a category. Krone is a German maker of hay and forage machines such as balers, mower-conditioners and self-propelled forage harvesters. Moore and O’Bryan’s are names you will find attached to individual dealerships rather than to a single national brand, so a shared name tells you little. For any of them, ask the dealership directly which brands it carries, who its finance partner is and whether it writes leases itself. Marketplaces such as TractorHouse and Machinery Pete show dealer asking prices and auction results, which help you judge a resale value in a quote. Remember that an asking price is not a sale price.
Lease vs buy: when farm machinery leasing wins
The Kansas State example is close enough to show why no rule of thumb works. Buying was the cheapest route, but only by $899 against rent. On an annual basis, the four options sat between $30,924 and $33,337. The authors point out that the winner can change as terms change.
Chart
Five-year cost of a combine, four ways
Net present cost after tax, US$, harvesting 2,300 acres a year (2010 example)
Leasing tends to look better in these cases, based on that guide’s analysis:
- Tight cash flow. You cannot carry the larger loan payment or the down payment.
- Little use for the tax deduction. In the guide’s example, without a Section 179 deduction, the lease had the lower cost at marginal tax rates from 0 to 40%, while at the example’s 46.8% rate buying still won, by $875. With the full $250,000 deduction, the purchase won at every rate except 0%.
- Low taxable income. Section 179 cannot create a taxable loss, so a low-income year limits its value.
Buying tends to look better when you will keep the machine past the loan term, run many acres over it and can use the deductions. Rent or custom hire fits work you rarely do. Be careful with rentals in harvest, though: the guide warns that a rental machine may not be available when you need it, and that combine rental contracts commonly carry a minimum hour requirement. Custom hire had the highest cost in the example, yet it can still be the right choice if labor is short or if buying would also mean new heads, grain carts or trucks.
Why acres per machine matter
Spreading a machine over more acres also lowers its cost per acre. University of Illinois farmdoc estimates from October 2025 show that the cost of combining corn with a new machine was $54.10 an acre at 2,600 harvested acres and $43.40 an acre at 3,600, on farms with 60% of acres in corn. A lease with an hour cap can limit that gain, so match the cap to your real acres, including any custom work you do for neighbors.
What do machinery costs look like now?
Lease quotes rest on machine prices and resale values, and both have moved. The same farmdoc article reports that USDA’s tractor price index rose 21% from 2020 to 2023. On central Illinois farms in the Illinois Farm Business Farm Management records, machinery-related costs for corn rose 25%, from $136 an acre in 2021 to $171 in 2024.
Chart
Machinery cost for corn, central Illinois
US$ per acre, Illinois Farm Business Farm Management farms on high-productivity land
Yearly machinery cost per acre differs by farm size, though less than you might expect. A December 2025 farmdoc analysis of FINBIN data put 2024 corn machinery cost at $185 an acre on farms with under 250 acres of corn and $178 on farms with over 1,000 acres. For soybeans the figures were $122 and $108. The gap between the top 20% and bottom 20% of farms by net return was larger, at $95 an acre for corn, though the authors caution that machinery age affects that comparison. Use these as a check on your own books. They cover the whole machinery line, including depreciation, interest, repairs, fuel and custom hire, so they are not lease prices.
The market may help your negotiation
Dealers have been selling fewer machines. A February 2026 farmdoc review of Association of Equipment Manufacturers data shows US farm tractor sales falling from 317,944 in 2021 to a preliminary 195,857 in 2025. Combine sales fell to a preliminary 3,579 in 2025, down 35.58% on the year. The same review cites USDA data showing the machinery prices paid index still rose 0.8% in the year to December 2025, so new prices have not dropped with sales.
Used values matter to a lease because the lessor sets your payment partly on expected resale. The review cites Sandhills Global data for December 2025: used tractor auction values were down 2.54% on the year, while used combine auction values were up 7.47%. If the residual value in your quote looks high or low, ask why, and compare several quotes on the same machine. These figures date from early 2026, so check current data before you negotiate.
Chart
US farm tractor sales
Units sold per year; 2025 is preliminary
Lease terms to check before you sign
Two quotes with the same payment can cost very different amounts. Go through this list with each offer in hand.
- Payment timing. Many leases take the first payment at signing, as in the Kansas State example. A payment made a year earlier costs you more in real terms.
- Deposit. Ask whether it is refundable and how it is treated at the end.
- Hours or acres allowed. Get the yearly limit and the charge for each hour above it.
- End-of-term choices. Return, renew or buy. Find out whether a buyout is at market value or a stated price.
- Return condition. Get wear standards in writing. Ask who decides what counts as excess wear, and what tires, tracks and attachments must look like.
- Repairs and warranty. You typically pay for repairs not covered by warranty. Check how long the warranty runs against the lease term.
- Early exit. Ask for the exact formula. Leases generally carry a penalty if you cancel.
- Insurance and taxes. Ask what cover the lessor requires and whether sales or property tax is added to the payment.
Keeping leased machines in good shape protects you at the return inspection. Our guide on preventive maintenance of farm tools covers the routine.
Lease to own and the tax trap
“Farm equipment lease to own” deals need the most care. In a true lease, payments are generally deductible as rent. But if the contract is really a purchase, the IRS treats it as a conditional sales contract. Then you cannot deduct the payments as rent. You capitalize the cost and recover it through depreciation, and you can deduct the interest part.
IRS Publication 225, the Farmer’s Tax Guide (2025), says no single test decides this, and that the parties’ intent is judged from the contract and the facts. An agreement may count as a conditional sale if any of these is true:
- Part of each payment builds an equity interest you will receive.
- You get title after making a stated amount of payments.
- What you pay for short-term use is a large part of what it would cost to get title.
- You pay much more than the fair rental value.
- You can buy the machine at a nominal price compared with its value when you may exercise the option.
- You can buy it at a nominal price compared with the total you pay under the agreement.
- Part of the payments is labelled as interest, or is easy to recognize as interest.
A “$1 buyout” is one example of a nominal price. That does not make the deal bad, but it may mean your tax plan is wrong if you assumed a rent deduction.
What buying gives you at tax time
Tax rules for buying have changed since the Kansas State guide, which used a $250,000 Section 179 limit for 2009 returns. IRS Publication 946 for 2025 sets the limit at $2,500,000, reduced once qualifying purchases pass $4,000,000. It also reports that a 2025 law reinstated a 100% special depreciation allowance for certain qualified property acquired and placed in service after January 19, 2025. Rules and limits change each year, and your state may treat them differently, so get professional tax advice for your own farm.
Outside the US, tax treatment differs. Readers in Canada, the UK, Australia and New Zealand should ask an accountant how local rules treat lease payments and capital allowances on a machine. The cash comparison below still applies before tax.
Farm equipment lease calculator
Enter one machine and one real quote. The calculator adds up cash costs for the term before tax, and takes off resale value if you buy. Loan interest is estimated on a balance that falls evenly, so your lender’s schedule will differ a little. It leaves out tax effects and the value of having cash on hand earlier, which is why the Kansas State guide uses a fuller net present value method for a final decision.
Try the numbers for your own farm below.
Calculator
Does your lease quote cost more than buying?
Enter your own quote. All figures are before tax, in US$ or your own currency.
- Total cost if you buy, after resale: $184,000
- Total cost if you lease: $185,000
- Break-even yearly lease payment: $36,800
- Lease cost per acre per year: 18.50 US$/acre
Example values only, set close to break-even; they are not benchmarks or quotes, so use today’s price and your own terms. If you enter a buyout, the machine is treated as yours afterwards and its resale value is taken off the lease cost. Interest assumes a loan repaid in equal yearly principal, on the amount after your down payment. Leaves out tax, the time value of money, repairs (you pay these either way) and any lease fees or excess-hour charges. Get professional tax and finance advice before you decide.
How to choose: a six-step process
- Count your real use. Add up the acres and hours the machine would run each year. Your records are better than the sales estimate.
- Price all four routes. Get a loan quote, a lease quote, a rental rate and a custom rate for the same work.
- Get an independent resale figure. Check recent auction results for machines of the same age and hours.
- Run the numbers after tax. Ask your accountant to compare them on a present-value basis, as Kansas State does.
- Check timing risk. Ask who has the machine on your best harvest day. Late work has a cost that a table of payments does not show.
- Read the end of the contract first. Return condition, buyout and early exit are where costs tend to hide.
Some farms may also qualify for government-backed credit as an alternative to a lease. USDA’s Farm Service Agency says its farm operating loans can be used to buy farm equipment, with direct loans of up to $400,000 and guaranteed loans of up to $2,558,000, an amount it adjusts each year for inflation. FSA also requires applicants to show they cannot get credit elsewhere at reasonable rates and terms, among other tests, so check eligibility with your local office.
To estimate what owning would cost, Mississippi State University Extension’s machinery cost calculations set out cost per hour and per acre for tractors and implements, and show how to combine them.
▶ Six plain steps to start precision farming without buying expensive new machines. · 4:18
Where satellite data fits
Field records can make machine planning more realistic. Satellite vegetation maps from Farmonaut show how crop growth differs across fields, which can help you decide which fields to visit and when. They show a change in plant cover, not its cause, so ground checks still matter. If you are sizing a lease around acres, tracking the real area you farm each season gives you a firmer number for the contract’s hour limit.
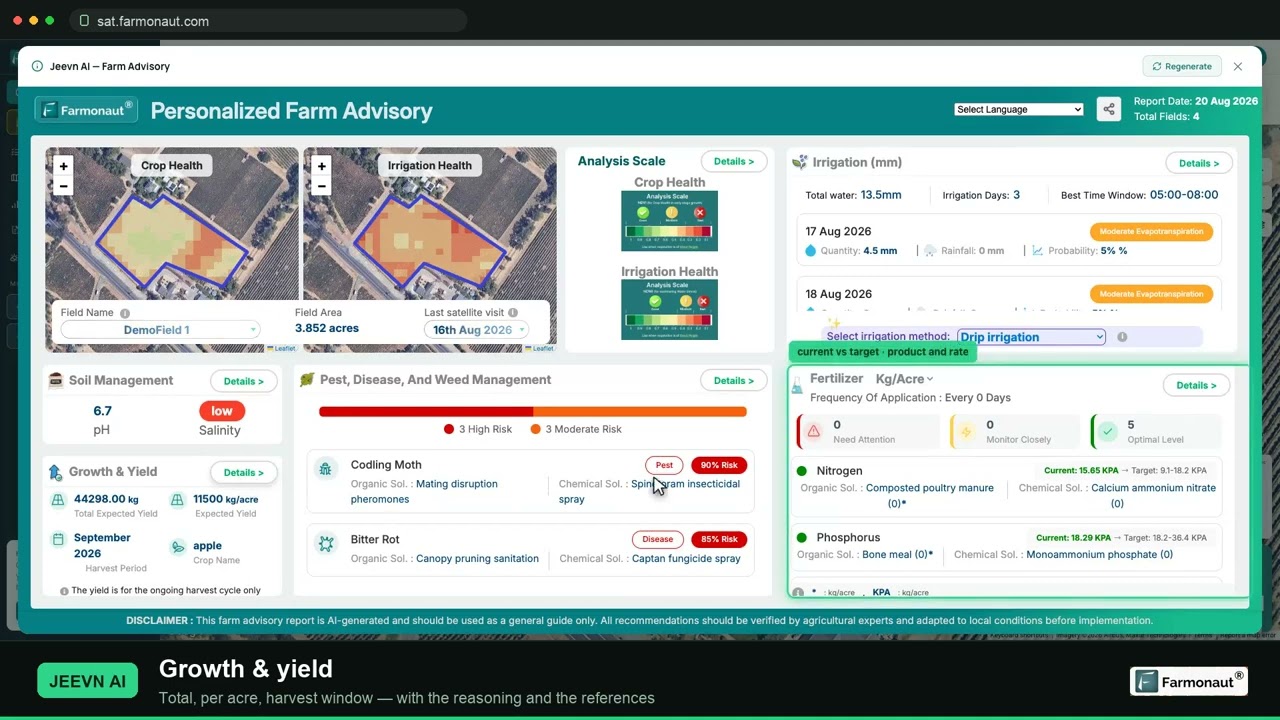
▶ A walkthrough of satellite crop monitoring: reading NDVI and pulling a report for your own field. · 19:36
Related pages on our site: machinery fleet tracking, crop loan and insurance checks, farm carbon footprint tracking, crop traceability, satellite and weather API docs.
FAQ
What is the difference between leasing and financing farm equipment?
With a loan you own the machine and can claim depreciation and interest. With a true lease, the dealer or leasing company keeps the title, and you can generally deduct the payments. Lease payments are often lower, but you have no machine to sell at the end unless you buy it out.
Is it cheaper to lease or buy a tractor?
It depends on your tax rate, the resale value and how long you keep the machine. In Kansas State’s 2010 combine example, buying cost about $10,700 less than leasing over five years, while the lease had the lower yearly payment. Run your own quote through the calculator above, then ask your accountant to check it after tax.
How long does a farm equipment lease last?
Kansas State describes typical leases as lasting three to five years. Rentals run for days, weeks or months. Ask whether the term can be matched to your crop cycle, and how the payment dates fall against your grain sales.
Can I lease used farm equipment?
Yes, some lenders offer it. AgDirect’s posted terms for November 2026 cover leases on new and used equipment, though not under $10,000 and not on titled equipment. Terms differ between lenders, so ask about age and hour limits on the machine you want.
What are typical tractor lease rates?
We found no published national rate, because each lease is priced on the machine’s value, expected resale, hours and your credit. For a short-term comparison, the Texas Custom Rates Survey for 2026 reports average rental rates from $64.32 to $128.15 an hour, by size class, without operator or fuel.
Do I need a down payment to lease?
Not always. Kansas State’s example needed no deposit, which it says is common in many leases, but a contract may ask for one. Payments are likely due at the start of each period, so expect the first at signing. Ask for all cash due on day one in writing.
Farmonaut crop monitoring
See your own fields from space
Check crop growth across your fields with the Farmonaut Satellite + AI Farm Monitoring System.




Keep reading

Sources
- Kansas State University, Leasing vs. Buying Farm Machinery, MF-2953 (October 2010): agmanager.info
- IRS, Publication 225, Farmer’s Tax Guide (2025): irs.gov
- IRS, Publication 946, How To Depreciate Property (2025): irs.gov
- University of Illinois, farmdoc daily, Large Increase in Machinery Costs (October 2025): farmdocdaily.illinois.edu
- University of Illinois, farmdoc daily, Crop Machinery Costs (December 2025): farmdocdaily.illinois.edu
- University of Illinois, farmdoc daily, The U.S. Farm Machinery and Equipment Market (February 2026): farmdocdaily.illinois.edu
- Texas A&M AgriLife Extension, Texas Custom Rates Survey (2026): agecoext.tamu.edu
- University of Wisconsin Extension, Custom Rates for 2025 Wisconsin Farm Operations: farms.extension.wisc.edu
- Manitoba Agriculture, Cost of Production: Farm Machinery (2026/2027): manitoba.ca
- Mississippi State University Extension, Farm Machinery Cost Calculations: extension.msstate.edu
- USDA Farm Service Agency, Farm Operating Loans: fsa.usda.gov
- AgDirect, Farm Equipment Financing, posted rates for November 2026: agdirect.com
- AGCO Finance, company site (accessed November 2026): agcofinance.com
- Farm Credit, network site (accessed November 2026): farmcredit.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Chimera Innovation
 Hiteshi Infotech
 Clubhouse OS
 Progenseed
 SkyHarvest
 Polaris Digitech
 Teledarbas
 Wild Oak Farm
 SFX
 BACF Africa
 Doodlakine
 Exurbia Geospatial
 FieldZero
 Indico Company

 Licence holder · Niger · Gold
 Client · Tanzania · Gold
 Client · Somalia · Gold
 Client & affiliate partner · Ghana · Gold










