

Diamond mining · Australia status guide
Diamond Mines in Australia: Operating, Closed, Planned
No Australian diamond mine has reported output since Argyle closed on 3 November 2020. This guide shows what became of Argyle, Ellendale and Merlin, how output and value per carat changed, and what a restart would need.
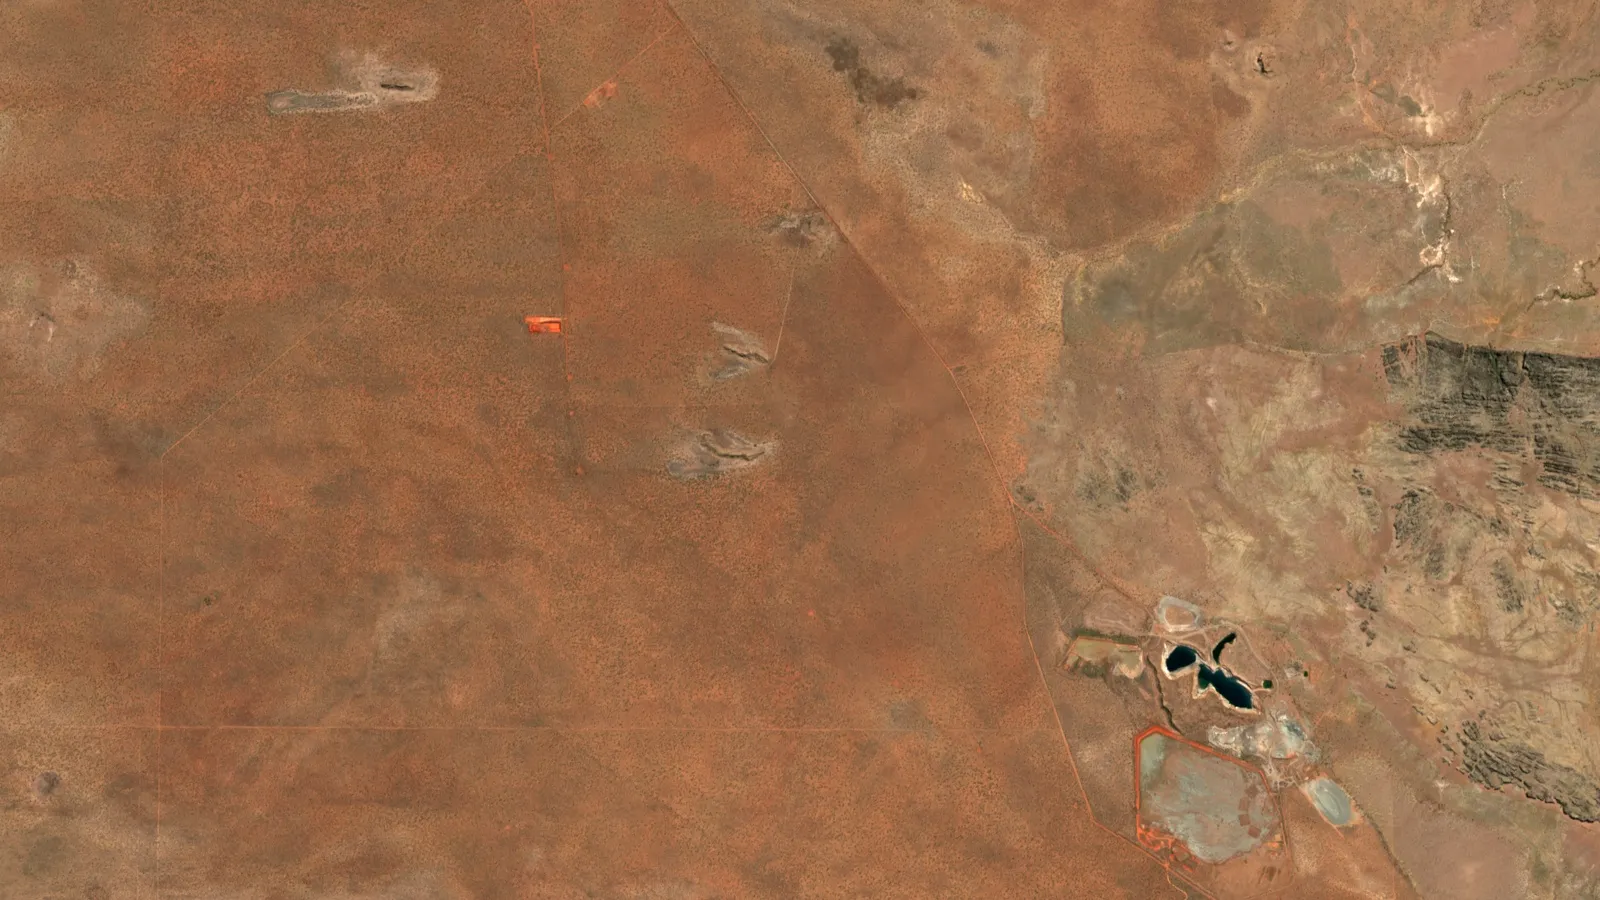
Key takeaways
- The Kimberley Process lists zero Australian rough diamond production for 2021 to 2025, after 10.9 million carats in 2020 (Kimberley Process).
- Argyle was responsible for all Australian diamond production in 2019, and national reserve life was one year (Geoscience Australia, 2020).
- Ellendale holds three granted mining leases (May 2024) and its owner is seeking a strategic investor (Gibb River Diamonds, December 2025).
- Merlin, bought by Lucapa in 2021, entered administration in May 2025, with a sale to Gaston International agreed in August 2025 but not confirmed complete (IDEX, 18 August 2025).
- Average Australian rough value fell from US$22.73 a carat in 2015 to US$10.77 in 2020 (Kimberley Process).
In this article
- Diamond mines in Australia: status at a glance
- Timeline of Australian diamond mining
- Is any diamond mine producing in Australia now?
- Gem, near-gem and industrial: why value per carat differs
- Which Australian diamond mines have closed or stopped?
- Ellendale restart: what has to happen first
- What happens to a closed diamond mine site
- Exploration after Argyle: Brooking and the Kimberley
- How much were Australian diamonds worth per carat?
- Australian pink diamonds after the mine
- Where Australia sits among diamond producers
- Will Australian diamond production restart?
- Test a small diamond project with your own numbers
- How to check a diamond project before you back it
No diamond mine in Australia has reported production since the Argyle mine in Western Australia stopped on 3 November 2020. The Kimberley Process, the international diamond-trade scheme, lists Australia’s rough diamond output as zero for every year from 2021 to 2025 (Kimberley Process, Australia participant page). Two idle projects, Ellendale in Western Australia and Merlin in the Northern Territory, are the ones people talk about as possible restarts.
This guide lists every diamond mine that matters in Australia’s history, says what state each is in (operating, closed, rehabilitating or waiting for a restart), and shows how output and value per carat changed. A carat is 0.2 gram. Each figure has a source and a date, and there is a calculator for testing a small diamond restart with your own numbers.
Diamond mines in Australia: status at a glance
The table covers the mines that produced diamonds at scale. Status is as reported by the source named in the last column, with the date of that source.
| Mine | Place | Status | Source |
|---|---|---|---|
| Argyle | East Kimberley, Western Australia | Closed. Last day of mining 3 November 2020; Rio Tinto says it is rehabilitating the site and is on track to finish infrastructure removal and revegetation in 2026 | Rio Tinto, Argyle page |
| Ellendale (pipes E4 and E9) | West Kimberley, Western Australia | Idle since 2015. Gibb River Diamonds holds three granted mining leases (May 2024) and says it is looking for a strategic investor (interim report to 31 December 2025) | Mining.com, 21 May 2024 |
| Merlin | Northern Territory, about 720 km south-east of Darwin | Rio Tinto-era mining stopped in 2003; later owners ran it only sporadically (2006 onward) and it has mostly been on care and maintenance. Bought by Lucapa (agreed May 2021, completed December 2021, from Merlin Diamonds’ liquidators); Lucapa entered administration in May 2025 and a rescue deal covering Merlin was signed in August 2025 (completion not confirmed) | Mining Technology |
| Brooking | West Kimberley, Western Australia | Exploration project near Ellendale; no mine | Mining Technology, GlobalData comment |
The short answer for anyone searching “aus diamonds” as a place to buy or invest: Australian rough is no longer being mined, so what reaches the market now is stock, jewellery and the Argyle pink brand, not new production.
Timeline of Australian diamond mining
- October 1979. The Argyle pipe is recognised (GIA, 2014).
- 1983 and 1985. Alluvial mining and then the open pit start at Argyle (GIA, 2014).
- February 1999. Merlin produces its first diamonds (Mining Technology).
- 2003. Merlin operations stop after about 500,000 carats.
- 2015. Ellendale’s operator collapses and the mine is suspended.
- 3 November 2020. Last day of mining at Argyle.
- May to December 2021. Lucapa agrees (May) and completes (December) the A$8.5 million purchase of Merlin.
- 21 May 2024. Gibb River Diamonds is granted three mining leases at Ellendale.
- 20 August 2025. A administrators sign a binding deal for Gaston International to buy Lucapa, owner of Merlin and Brooking; creditors meet on 20 August (completion not confirmed).
- 1 October 2026. The Argyle Pink Diamonds brand and last pink stock pass to Boodles.
Is any diamond mine producing in Australia now?
No. The Kimberley Process figures show output of about 13.6 million carats in 2015, a peak of about 17.1 million in 2017, 13.0 million in 2019 and 10.9 million in 2020, then zero from 2021 (Kimberley Process). Geoscience Australia, the national geological survey, says the Argyle pipe was responsible for all Australian diamond production in 2019 (Geoscience Australia, Australia’s Identified Mineral Resources 2020).
Chart
Australian rough diamond production
Million carats reported to the Kimberley Process, selected years
The same report shows how fast the cushion disappeared. Economic demonstrated resources (EDR), the part of a deposit that is both well known and worth mining at current prices, fell 57 per cent in one year, from 25.48 million carats in 2018 to 10.97 million in 2019. Geoscience Australia put the national reserve life at only one year.
Gem, near-gem and industrial: why value per carat differs
Geoscience Australia sorts diamonds into gem, near-gem and industrial quality. It notes that in rare cases up to 90 per cent of the diamonds in a deposit are gem quality, but most economic deposits hold 20 to 40 per cent (Geoscience Australia, 2010). Argyle’s output was mostly the cheaper categories, with a small, very valuable supply of pinks. Ellendale sold a much higher share of gem stone, including fancy yellows, which were 7 per cent of its 2009 sales at an average of US$2,480 per carat.
Diamonds reach the surface in two kinds of volcanic pipe. Kimberlite is the classic host; lamproite is a rarer relative, and Argyle and Ellendale are both lamproite fields. When pipes erode, the loose stones collect in river gravels, called alluvial deposits. Alluvial diamonds are often easier and cheaper to mine, which is why a project like Ellendale’s E12 deposit attracts attention.
Which Australian diamond mines have closed or stopped?
Argyle, Western Australia
Argyle ran for 37 years and mined more than 865 million carats of rough diamond (International Mining, 4 November 2020). Most of the output was low-value near-colourless to brown stone, but the mine also supplied more than 90 per cent of the world’s pink diamonds, which were less than 0.1 per cent of its production (GIA Gems & Gemology, Winter 2014). Its history, closure and rehabilitation have their own guide: Argyle mine location, history and closure.
Ellendale, Western Australia
Ellendale is a field of lamproite pipes (lamproite is a volcanic rock related to kimberlite, the classic diamond host) in the West Kimberley of Western Australia. The company that holds it today reports past production of about 1.3 million carats, including more than half of the world’s annual supply of fancy yellow diamonds (Gibb River Diamonds interim report, 31 December 2025). Its operator, Kimberley Diamond Company, collapsed in 2015 and the mine has been suspended since (Mining Technology).
In 2009 Ellendale treated 4.1 million tonnes of ore to recover 0.2 million carats at an average US$232 per carat, according to Geoscience Australia’s 2010 review. That is a grade of under 0.05 carat per tonne, which shows why small price changes decided whether the mine paid (Geoscience Australia, Australia’s Identified Mineral Resources 2010).
Merlin, Northern Territory
Merlin has 14 kimberlite pipes in Geoscience Australia’s 2010 count (Mining Technology counts 11 known diamondiferous pipes). Ashton Mining, later part of Rio Tinto, produced the first diamonds in February 1999 and the site made about 500,000 carats at an average of about US$108 per carat before operations stopped in 2003. In March 2002 it produced Australia’s biggest diamond, 104.73 carats (Mining Technology). Lucapa Diamond Company bought the project in May 2021 for A$8.5 million, with a resource of about four million carats.
Lucapa went into voluntary administration in May 2025. In mid-August 2025 its administrators (KordaMentha) signed a binding deal with a buyer, Gaston International of Dubai, to take over the whole company, including Merlin and the Brooking project; creditors were due to vote on 20 August 2025 (DLA Piper, 20 August 2025). A November 2025 report still described the sale as subject to creditor and court approval, so Lucapa remains Merlin’s owner on the record.
Ellendale restart: what has to happen first
Mining leases are only one step. Gibb River Diamonds (ASX: GIB) was granted three leases, M04/475, M04/476 and M04/477, on 21 May 2024. They cover the historic E4 and E9 workings and the bulk-sampled E12 alluvial deposit (diamonds in river gravel). The company listed debt, equity, partner and government funding as ways to pay for a restart (Mining.com, 21 May 2024).
By December 2025 a heritage survey with the Bunuba Traditional Owners had been completed over the E9 area, and the stated aim was to find a strategic investor to restart mining (Gibb River Diamonds interim report). On the same site, the Western Australian government’s Abandoned Mines Program reported the second season of Ellendale Stage 1 earthworks in 2024-25 (Government of Western Australia, Mining Rehabilitation Fund report). A restart therefore has to be planned around rehabilitation work that is already under way.
The usual order for a project like this is: leases, heritage clearance, funding, mine plan and approvals, then construction. Only the first two are reported as done at Ellendale.
What happens to a closed diamond mine site
Rehabilitation means removing buildings, reshaping the ground and replanting. Rio Tinto says Argyle’s closure includes 2,000 hectares of rehabilitation and that more than 35 per cent of the site works are delivered by Traditional Owner businesses (Rio Tinto). In February 2026 Traditional Owners publicly questioned whether the agreed criteria would be met before handback (Indigenous Business Review, 17 February 2026). Western Australia also keeps a Mining Rehabilitation Fund, which assessed A$51.6 million of levies in 2024-25 to pay for abandoned sites.
For a plain-language overview of what mining does to land, the video below covers seven common impacts.
▶ A plain-language claymation on the seven environmental impacts of mining. · 2:31
Exploration after Argyle: Brooking and the Kimberley
New finds are the only route to new mines. A 2019 GlobalData comment said no project could replace even part of Argyle’s output and that exploration was far more limited than in other diamond countries. It singled out the Brooking project, close to Ellendale, where first drilling recovered over 1,200 micro- and macro-diamonds from 265 kg of samples taken from two holes (Mining Technology). A sample like that shows diamonds are present. It does not give a grade, a stone value or a resource.
Argyle and Ellendale both sit in lamproite, which is why lamproite pipes remain the exploration target in the Kimberley (the Argyle pipe was recognised in October 1979, GIA, 2014). Largest diamond mines in the world compares the big producers elsewhere.
▶ Explains what remote sensing measures for mining and why agreement between instruments matters. · 2:01
How much were Australian diamonds worth per carat?
Australian rough was cheap per carat because most of it was industrial or near-gem stone. Kimberley Process data put the average at US$22.73 per carat in 2015, falling to US$10.77 in 2020 as Argyle’s mix and grades worsened (Kimberley Process). Compare that with Ellendale’s US$232 per carat in 2009 and Merlin’s roughly US$108 per carat (sources above): mine-level value varied by a factor of ten or more.
Chart
Average value of Australian rough diamonds
US$ per carat as reported by the Kimberley Process
This is why the grade of a deposit, in carats per tonne, is only half of the story. A mine needs the carats per tonne multiplied by the value per carat to beat its cost per tonne, which is what the calculator below tests.
Australian pink diamonds after the mine
With no new Argyle rough, pinks can only come from existing stock. On 1 October 2026 Rio Tinto announced that the Argyle Pink Diamonds brand, a set of trademarks and the last remaining pink inventory had passed to the jeweller Boodles (Rio Tinto, 1 October 2026). The background on that market is in our guide to Australian pink diamonds.
Where Australia sits among diamond producers
The US Geological Survey (USGS) estimates world gem-quality natural diamond output at 69 million carats in 2025, led by Russia at 21 million. Australia no longer appears in its table (USGS, Mineral Commodity Summaries 2026, gemstones). Geoscience Australia ranked Australia the sixth-largest producer by weight in 2009 (2010 review). For other countries see diamond mines in Canada and diamond mines in the United States; for the land footprint of the biggest operations see the world’s largest diamond mines.
Chart
Gem-quality natural diamond mine output, 2025 estimate
Thousand carats; leading producers listed by USGS (Australia is not listed)
The other large Rio Tinto diamond mine, Diavik in Canada, delivered its final production in March 2026 (Rio Tinto, 26 March 2026).
Will Australian diamond production restart?
Two projects have granted or purchased title and a history of production: Ellendale and Merlin. Neither has a reported restart date in the sources above, and the Kimberley Process lists zero output through 2025. What is confirmed is the work done (leases, heritage survey, rehabilitation earthworks) and the work still open (funding, approvals, construction). A realistic view is that any restart would be small next to Argyle, whose historical annual average was about 34 million carats (Geoscience Australia, 2010).
Test a small diamond project with your own numbers
The calculator below uses grade in carats per 100 tonnes, the way alluvial and small pipe projects often report it. Enter your own ore tonnes, grade, value per carat and cost per tonne. Capital, royalties and tax are left out.
Calculator
Does a small diamond project cover its costs?
Enter your own tonnes, grade, value per carat and cost per tonne.
- Carats recovered per year: 50,000
- Revenue per tonne (US$): 15.00
- Margin per tonne before capital (US$): 3.00
- Annual margin before capital (US$): $1,500,000
Example values only, not a benchmark for Ellendale, Merlin or any mine. Grade is in carats per 100 tonnes. Prices are inputs: example, use today’s price (US$ per carat). Capital, royalties and tax are left out.
How to check a diamond project before you back it
- Title. Are the leases granted, and which ones? Check the state register (the Western Australian and Northern Territory mining registries are public).
- Resource category. Inferred resources are a guess; indicated and measured resources, reported under the JORC Code, carry more weight.
- Value per carat. Ask for the sale price of a real parcel, not a model. Geoscience Australia’s 2010 review quotes a 2008 revaluation of Merlin stones at about US$200 per carat, so ask which basis a company is using.
- Funding. Has the money been raised, and how much is conditional?
- Heritage and rehabilitation. Heritage surveys with Traditional Owners and closure plans are part of the schedule, not an extra.
- Company status. Read the latest ASX announcements; Merlin’s owner was in administration in 2025.
Farmonaut’s satellite reports can show land cover and disturbance on a lease boundary over time. They do not detect diamonds, and they do not replace sampling.
▶ What AI does in mineral exploration, where it fails, and how to check any claim. · 4:37
If this topic matters to you, read Gold and Diamond Prospecting in Western Australia: Rules next.
Related reading on this site: Montana Gold and Silver Mines: Open, Closed, Proposed.
Frequently asked questions
Are there any diamond mines operating in Australia?
No mine has reported production since Argyle closed in November 2020. The Kimberley Process lists zero Australian rough output for 2021 to 2025.
Where did Australian diamonds come from?
Mainly the Argyle lamproite pipe in the East Kimberley. Smaller sources were Ellendale in the West Kimberley and Merlin in the Northern Territory.
Why did Argyle close?
Rio Tinto said it had exhausted its economic reserves. Geoscience Australia had reported a national reserve life of one year in 2019.
Is Ellendale going to reopen?
Gibb River Diamonds holds three granted mining leases and says it wants a strategic investor. No restart date has been announced in the sources above.
Who owns the Merlin diamond mine?
Lucapa Diamond Company bought it in May 2021. Lucapa went into administration, and administrators agreed a deal in August 2025 for Gaston International to buy the whole company. A November 2025 report still described the deal as subject to creditor and court approval, so Lucapa remains Merlin’s owner on the record.
How many carats did Australia produce each year?
About 13.6 million in 2015, 17.1 million in 2017, 13.0 million in 2019 and 10.9 million in 2020 (Kimberley Process).
What was the biggest diamond found in Australia?
Mining Technology reports the 104.73-carat Gungulinya-Bunagina diamond from Merlin in 2002 as Australia’s biggest.
Are Australian pink diamonds still available?
Only from existing stock. Rio Tinto passed the last Argyle pink inventory and the brand to Boodles on 1 October 2026.
Can I prospect for diamonds in Australia?
Only with the right tenement or permit from the state regulator, and with landowner and Traditional Owner consent where required. Mining Technology’s list of explorers shows the work is done by licensed companies.
Where does Australia rank among diamond producers now?
It is not listed in USGS’s 2025 estimates, which put Russia first with 21 million carats of gem-quality output.
This page is for information only. It is not investment advice. Company and ownership details change; confirm them in current ASX filings and the state or territory titles register.
Farmonaut mining
See a lease boundary from space
Investors and consultants can request a satellite view of a project area, including land cover and disturbance over time.

Mining Pro sample view, synthetic data
Keep reading
Sources
- Kimberley Process, Australia participant page (annual rough diamond summaries 2015-2025): kimberleyprocess.com
- Geoscience Australia, Australia’s Identified Mineral Resources 2020, commodity summaries: ga.gov.au
- Geoscience Australia, Australia’s Identified Mineral Resources 2010: ga.gov.au
- Mining Technology, Outlook for diamond mining in Australia after Argyle closure (GlobalData, 2019): mining-technology.com
- Mining Technology, Inside Australia’s newest diamond mine: Merlin timeline: mining-technology.com
- Mining.com, Past producing yellow diamonds mine set to reopen (21 May 2024): mining.com
- Gibb River Diamonds, interim financial report to 31 December 2025 (ASX, 13 March 2026): announcements.asx.com.au
- Government of Western Australia, Mining Rehabilitation Fund yearly report 2024-25: wa.gov.au
- DLA Piper, Gaston International proposed acquisition of Lucapa (20 August 2025): dlapiper.com
- Rio Tinto, Argyle operations page (accessed 16 October 2026): riotinto.com
- International Mining, Argyle closes after 37 years (4 November 2020): im-mining.com
- Indigenous Business Review, Traditional Owners and Argyle rehabilitation (17 February 2026): theibr.com.au
- GIA Gems & Gemology, 30th Argyle Diamond Tender (Winter 2014): gia.edu
- USGS, Mineral Commodity Summaries 2026, gemstones: pubs.usgs.gov
- Rio Tinto, Diavik final production (26 March 2026): riotinto.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited
 Mining SARL
 SenGold Invest SAS

 Exploration consultancy · South Africa · Gold










