

Feasibility studies · Worked examples
Mining Feasibility Study Example: 5 Real Studies
A feasibility study turns tonnes and grade into capex, NPV and IRR. Here are five published studies, from a PEA to a definitive study, with the real figures and what each section contains.
Key takeaways
- Five published studies show IRRs from 19% to 102% and up-front capital from A$133 million (Hillgrove) to US$1.43 billion (Santa Cruz), in different currencies, each on its own price basis (company releases and technical reports, 2023-2026).
- Cost accuracy tightens by stage: about plus or minus 50% for an initial assessment, 25% for a pre-feasibility study and 15% for a feasibility study (17 CFR 229.1302).
- At Bomboré, a 10% gold-price change moves NPV by about US$185 million; a 10% capital-cost change moves it by about US$21 million (Orezone technical report, 2023).
- A full feasibility study is indicatively 0.5% to 1.5% of project capital (SAIMM paper, 2004), before owner’s drilling and test work.
- Satellite imagery supports early screening of ground; it does not replace drilling or a Qualified Person.
In this article
- Five real studies compared: capex, NPV and IRR
- What each section of a feasibility study contains
- Worked example: where the money goes in a gold study
- Which assumption moves the value most
- Scoping, pre-feasibility and feasibility: what changes at each stage
- A JORC example: reserves and the production target at Hillgrove
- What a feasibility study costs
- How to read a feasibility study in ten minutes
- Feasibility study outline you can adapt
- Where satellite data fits before the study
- Frequently asked questions
A mining feasibility study is the document a lender, a partner or a board reads before it commits money to build a mine. The clearest way to understand one is to read real ones. This page walks through five published studies, from a Canadian NI 43-101 report to an Australian JORC study and a US SEC filing, and shows the capital cost, net present value (NPV, the value of all future cash flows at current value) and internal rate of return (IRR, the yearly return the project earns) that each one reported.
The studies below are real, public and dated. They are examples of how the numbers are built, not forecasts or advice. Each project was priced on its own metal prices and currency, so compare structure and method, not headline NPVs. For the step-by-step process of commissioning a study, see our guide to the key steps of a mining feasibility study.
Five real studies compared: capex, NPV and IRR
The table lists one study at each stage of detail. Capex means up-front capital cost. NPV is shown after tax at the discount rate the study chose, and the price basis is part of the result: change the metal price and every figure moves.
| Study (stage, code) | Project and commodity | Up-front capital | After-tax NPV and IRR | Life and price basis |
|---|---|---|---|---|
| Preliminary economic assessment (NI 43-101), report dated August 2025 | Luanga, Brazil: platinum-group metals, gold, nickel (Bravo Mining) | US$495.8 million initial | US$1,249 million at 8%; IRR 49%; payback 2.4 years | 17 years; palladium US$1,271/oz, gold US$3,251/oz, nickel US$8.00/lb |
| Pre-feasibility study (SEC S-K 1300), September 2026 | Santa Cruz, Arizona: copper cathode (Ivanhoe Electric) | US$1.43 billion initial | US$1.5 billion at 8%, IRR 19% (copper US$4.75/lb); US$3.5 billion, IRR 30% (US$6.79/lb, COMEX, 21 September 2026) | Average grade 1.08% copper; about 75,000 t of copper a year for the first 15 years |
| Feasibility study (NI 43-101), dated February 2026 | Angel Island, Nevada: lithium carbonate (Century Lithium) | US$997 million phase 1, US$660 million phase 2 | US$4.01 billion at 8%; IRR 27.4% | 40-year schedule; lithium carbonate US$24,000/t |
| Definitive feasibility study (JORC 2012), May 2025 | Hillgrove, New South Wales: antimony and gold (Larvotto Resources) | A$133 million (mid case, net of early revenue) | A$694 million at 8%; IRR 102%; payback 11 months | 8 years; gold US$2,850/oz, antimony US$41,000/t |
| Definitive feasibility study (NI 43-101), effective March 2023 | Bomboré phase II, Burkina Faso: gold (Orezone) | US$167.5 million, accuracy plus or minus 15% | US$636 million at 5% | 11.3 years; gold US$1,750/oz |
Sources: Bravo Mining, Luanga PEA technical report; Ivanhoe Electric, 2026 Santa Cruz study release; Century Lithium, Angel Island study release; Larvotto Resources, Hillgrove definitive feasibility study presentation; Orezone, Bomboré phase II technical report.
Three patterns show up. Capital cost per unit of output is very different for a lithium-chemical plant, an underground copper mine and a small antimony-gold mine. The earlier the stage, the wider the error band. And the price used is stated on page one.
What each section of a feasibility study contains
Canadian reports follow the layout of Form 43-101F1, set under National Instrument 43-101, the Canadian rule for public disclosure of mineral projects. The Bomboré report is a good template because it keeps every item in order. Items 1 to 13 describe the property and the data; items 14 to 22 are the engineering and economics that make it a feasibility study.
- Mineral resource estimate (item 14): tonnes and grade in categories of confidence. The Bomboré study reports resources inside a pit shell drawn at a gold price of US$1,700/oz.
- Mineral reserve estimate (item 15): the part of the resource that is economic after dilution and losses. Bomboré reserves use a lower long-term gold price of US$1,500/oz, so reserves are always a smaller, safer number than resources.
- Mining methods (item 16): open pit or underground, pit design, production schedule, fleet. Bomboré plans 64.6 million tonnes of oxide ore at 0.54 g/t gold and 38.9 million tonnes of hard rock at 1.02 g/t.
- Recovery methods (item 17): the plant flowsheet and how much metal it recovers, about 90.9% from oxide ore and 85.0% from hard rock in the same study.
- Infrastructure, markets and contracts (items 18 and 19): power, water, roads, tailings storage, and what the product is sold for.
- Environmental, permitting and community (item 20): permits held, studies done and closure plans.
- Capital and operating costs (item 21): built up line by line with a stated accuracy, here plus or minus 15% on US$167.5 million, including US$11.0 million of contingency.
- Economic analysis (item 22): the cash-flow model, NPV, IRR, payback and a sensitivity table.
- Interpretations, conclusions and recommendations (items 25 and 26): what the authors think should happen next, and what could still go wrong.
A Canadian technical report also needs a named Qualified Person who signs it. In Australia the equivalent is a Competent Person under the JORC Code. Our explainer on how to read a JORC resource table covers that side in detail.
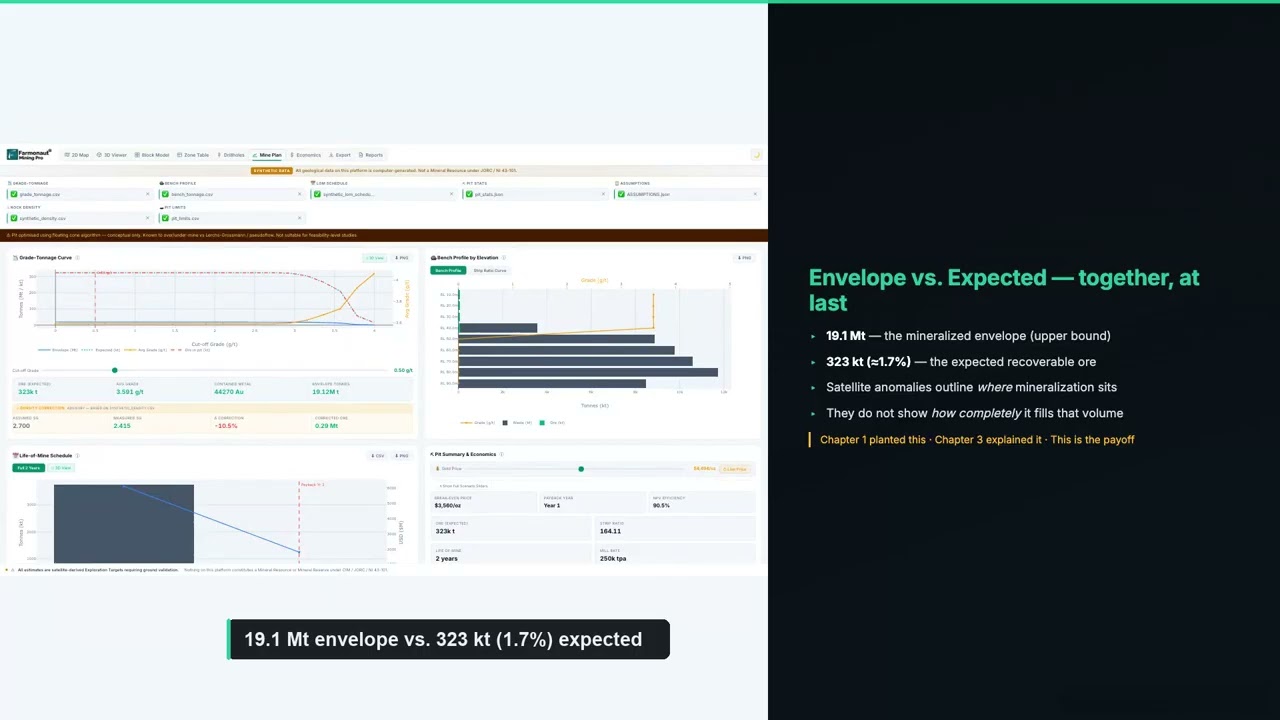
▶ How a pit shell and the grade-tonnage curve feed the mine plan · 18:56
Worked example: where the money goes in a gold study
The Bomboré cash-flow summary is a clean example of how a feasibility study turns tonnes and grade into dollars. Over 11.3 years it expects to sell 2.11 million ounces of gold for US$3,704 million in revenue, which is US$35.78 for every tonne of ore processed. Operating costs total US$2,257 million, or US$21.80 per tonne, leaving EBITDA (earnings before interest, tax, depreciation and amortization) of US$1,448 million. Capital spending of US$336 million and income tax of US$258 million come out next, with a small working-capital release of US$31 million added back, so after-tax cash flow is US$885 million.
Chart
Bomboré gold study: life-of-mine cash flow
US$ million, main lines of the cash-flow summary (11.3-year mine life)
Discounting that stream at 5% a year gives the headline NPV of US$636 million. The study also notes that a proposed royalty increase in Burkina Faso, if adopted in 2024, would have cut that NPV to US$607 million. A good study flags a change like this even when it is not yet law.
Which assumption moves the value most
Every feasibility study ends with a sensitivity table that changes one input at a time. In the Bomboré study, a 10% change in the gold price moves NPV by roughly US$185 million either way. A 10% change in operating cost moves it by about US$105 million. The same 10% change in capital cost moves it by only about US$21 million, because capital is spread over a mine that earns for 11 years. A 2% change in recovery moves NPV by about US$39 million. The report itself says the project is most sensitive to the gold price, followed by operating costs.
Chart
Bomboré NPV when one input changes
After-tax NPV at 5%, US$ million; base case US$636 million; recovery moved by 2%
The Hillgrove study shows how far a price case can swing. Its base case (gold US$2,400/oz, antimony US$25,000/t) gives an NPV of A$280 million, the mid case A$694 million and the spot case (gold US$3,300/oz, antimony US$57,000/t) A$1,269 million. The study’s own table puts antimony at US$25,000/t in the base case and US$41,000/t in the mid case. Always ask which price case the headline number belongs to.
▶ What P10, P50 and P90 mean in project economics and risk · 14:59
Scoping, pre-feasibility and feasibility: what changes at each stage
Studies are staged because each one costs more and is only worth doing if the last one passes. The US rule that governs SEC filings, 17 CFR 229.1302, sets minimum cost accuracy: about plus or minus 50% for an initial assessment, 25% for a pre-feasibility study and 15% for a feasibility study. Contingency, the allowance for the unknown, is capped at 25%, 15% and 10% respectively.
Chart
Minimum cost accuracy by study stage
Capital and operating cost range, plus or minus %
The Luanga PEA used measured, indicated and inferred resources in its mine plan, and its authors concluded that the project has enough economic potential to justify moving to a pre-feasibility or feasibility study. A PEA is therefore a screening step before the more detailed studies. Under the JORC Code, an Ore Reserve must be defined by a study of at least pre-feasibility level, as the ASX mining reporting FAQ explains.
A JORC example: reserves and the production target at Hillgrove
Hillgrove is useful because the study separates what is proven from what is hoped for. The JORC 2012 Ore Reserve is 3.01 million tonnes at 6.6 g/t gold equivalent, holding 636,000 ounces of gold equivalent. The eight-year production plan, however, mixes grades of confidence: 92% of the contained ounces come from Ore Reserves, 3% from Indicated Resources outside reserves and 5% from Inferred Resources. The average output is 80,400 ounces of gold equivalent a year.
Chart
Hillgrove after-tax NPV by price case
A$ million at 8%; base gold US$2,400/oz, antimony US$25,000/t; mid US$2,850 and US$41,000; spot US$3,300 and US$57,000
That footnote is the kind of detail to look for. A study that states its split lets a reader judge how much of the cash flow rests on reserves. The Australian JORC Code 2012 sets the reporting rules; the rules for how a Competent Person describes the modifying factors (mining, processing, cost, legal and environmental limits) are in the same document.
What a feasibility study costs
Few companies publish what they paid for a study, so cost is usually quoted as a share of the capital cost of the project. A South African Institute of Mining and Metallurgy paper (2004) gives indicative ranges: 0.1% to 0.3% for a scoping study, 0.2% to 0.8% for a pre-feasibility study and 0.5% to 1.5% for a full feasibility study, with the matching cost accuracy of 30-50%, 15-30% and 10-15%. These ranges leave out the owner’s own costs such as drilling, metallurgical testing and environmental baseline work.
Applying the paper’s feasibility range to the Bomboré capital of US$167.5 million gives an engineering fee of roughly US$0.8 million to US$2.5 million. The ranges are two decades old, so treat them as a way to size a budget, not as a quote.
How to read a feasibility study in ten minutes
- Find the stage and the code. The cover says whether it is a PEA, PFS or FS, and whether it follows NI 43-101, JORC or S-K 1300.
- Read the price basis. Compare the study’s price with the Santa Cruz spread: the same project shows an IRR of 19% at US$4.75/lb and 30% at US$6.79/lb (COMEX, 21 September 2026).
- Check the reserve share. How much of the mine plan sits in reserves, and how much in inferred resources?
- Look at the capital accuracy. Is it plus or minus 15% (feasibility) or 30% and wider (earlier stage)?
- Read the sensitivity table. Which input moves NPV most, and could that input realistically move that far?
- Look for permits and land. Santa Cruz states that the permits needed to start surface construction are in hand; for many projects the permit list is the real schedule risk.
- Check the discount rate. NPV at 5% (Bomboré) and at 8% (the other four) are not comparable. A higher rate lowers the NPV.
The calculator below applies the same logic in a simple form. Enter your own tonnes, grade, price and costs to see a rough payback. It uses no discounting, no tax and no ramp-up, so a real study will give a longer payback.
Calculator
What simple payback does your gold project show?
Enter your own tonnes, grade, recovery, price and costs.
- Gold produced per year (oz): 130,210
- Revenue per year (US$ M): 260.4
- Operating cost per year (US$ M): 135.0
- Cash flow before tax per year (US$ M): 125.4
- Mine-life cash flow less capital (US$ M): 1,004.2
Example values only, not a benchmark. Simple pre-tax payback: no discounting, tax or ramp-up, so a real study gives a longer figure. Gold price is an input: use today’s price. 31.1035 g per troy ounce.
Feasibility study outline you can adapt
If you are preparing the brief for a consultant, or checking whether a draft covers the ground, this outline follows the reports above. It also covers what earlier guides called a feasibility plan sample or a project feasibility report.
| Section | What goes in | Example from the studies above |
|---|---|---|
| Scope and objectives | Location, production rate, product, owner, and the decision the study supports | Angel Island: 7,500 tonnes a day in phase 1, rising to 15,000 tonnes a day in year 5 |
| Constraints | Land, permits, water, power, community and market access | Santa Cruz: private land and permits for surface works already obtained |
| Resource and reserve | Tonnes, grade, confidence class, price used | Hillgrove: 3.01 Mt at 6.6 g/t gold equivalent |
| Mining and processing plan | Method, schedule, plant flowsheet, recovery | Santa Cruz: 92.3% life-of-mine copper recovery from column tests |
| Market assessment | Who buys the product, at what price, under which contract | Hillgrove: a seven-year antimony offtake agreement |
| Costs and economics | Capex, opex, cash flow, NPV, IRR, payback | Bomboré: US$21.80 operating cost per tonne processed |
| Environmental and social | Baseline studies, water, waste, closure, community plan | Item 20 of every NI 43-101 report |
| Risk and sensitivity | Price, cost, recovery, schedule and permit risk | Bomboré sensitivity table |
| Implementation schedule | Detailed engineering, construction, first production | Santa Cruz: first copper cathode targeted for 2029 |
Where satellite data fits before the study
A feasibility study starts from a drilled resource, so satellite imagery does not replace any of the work above. Where it helps is earlier: screening ground before a claim is bought or a drilling programme is planned, and mapping alteration, structure and surface disturbance across a licence so that the first drill holes go to the best targets. Farmonaut produces that kind of satellite-based mineral detection screen from a boundary file. The output is a ranked set of exploration targets, not a resource estimate, and it is not a substitute for a Qualified Person or Competent Person.
If you own a licence and want it screened, send the boundary through the mining query form, or contact the team with questions about coverage.
▶ Remote sensing for mining, explained in three minutes · 2:01
Frequently asked questions
What is a mining feasibility study?
It is a technical and financial report that tests whether a deposit can be mined at a profit. It combines the resource and reserve estimate, a mine plan, a processing plan, capital and operating costs, permits and a cash-flow model. Canada, Australia and the United States each set rules for how it is disclosed, in NI 43-101, the JORC Code and SEC S-K 1300.
What is a good example of a feasibility study to read?
Read a recent one with a table of contents you can follow. The Bomboré phase II report shows every NI 43-101 item in order, the Hillgrove study shows a JORC reserve and production target, and the Santa Cruz release states that the study was prepared under SEC rule S-K 1300. The table near the top of this page lists all five.
What is the difference between a PEA, a PFS and a feasibility study?
The difference is detail and cost accuracy. A preliminary economic assessment screens the idea and may use inferred resources. A pre-feasibility study selects the mining method and the plant and has capital accuracy near plus or minus 25%. A feasibility study fixes the design and aims for plus or minus 15%, according to SEC rules.
What does a mine feasibility study cost?
Whether a mine is feasible is answered by its NPV, IRR and payback at stated prices; what the study itself costs is a separate figure. A 2004 South African Institute of Mining and Metallurgy paper put a full feasibility study at 0.5% to 1.5% of project capital, before the owner’s own drilling and test work. On a project with US$167.5 million of capital, that is roughly US$0.8 million to US$2.5 million.
Why are some NPVs quoted at 5% and others at 8%?
The discount rate is the study author’s choice. Bomboré uses 5% and the other four studies use 8%. A higher rate lowers the NPV, so compare NPVs only when the discount rate and the price basis match.
What is a good IRR for a mining project?
There is no universal threshold. The studies here range from 19% to 102%, and the number depends on price, discount rate and stage. Santa Cruz shows why: its IRR is 19% at US$4.75/lb copper and 30% at US$6.79/lb (COMEX, 21 September 2026), so check the IRR at more than one price.
Is NPV or IRR more important?
Read both. NPV shows the size of the value created at a chosen discount rate, and IRR shows how efficiently capital is used. A large project with a modest IRR, such as Santa Cruz at US$4.75/lb copper, can have a larger NPV than a small project with a very high IRR.
What does bankable mean?
A bankable study is detailed enough, and independent enough, for a lender to rely on it. In practice that usually means a feasibility study with a plus-or-minus 15% cost estimate, signed by qualified persons, with reserves, permits and offtake in place.
Can a small project use a shorter study?
A smaller operation can run a shorter study, but the main questions stay the same: what is the tonnage and grade, what will it cost to extract and process, who will buy the product, and what permits are needed. The stage and disclosure rules apply when a company reports results to the public or a stock exchange.
Where can I find real feasibility studies?
Canadian studies are filed on SEDAR+, Australian announcements are on the ASX platform and US filers use SEC EDGAR. Company websites also host the full technical reports, as the sources on this page show.
Does satellite data go into a feasibility study?
It can support the early sections, such as the geological setting, access, land disturbance and baseline mapping. The resource estimate itself still comes from drilling and assays. Satellite targets are exploration leads, not reported resources.
This page is for information only. It is not investment, legal or engineering advice. Figures come from company studies dated as shown and are not forecasts.
Farmonaut mining
Map your mining site from space
Send your licence boundary and get a satellite screen of exploration targets before you plan drilling.

Mining Pro sample view, synthetic data
Keep reading
Sources
- Bravo Mining, Luanga PGM-Au-Ni PEA NI 43-101 technical report (2025): bravomining.com
- Ivanhoe Electric, 2026 Preliminary Feasibility Study for Santa Cruz (23 September 2026): ivanhoeelectric.com
- Century Lithium, updated feasibility study for Angel Island (2026): centurylithium.com
- Larvotto Resources, Hillgrove Definitive Feasibility Study (May 2025): larvottoresources.com
- Orezone Gold, Bomboré Phase II Expansion NI 43-101 technical report (2023): minedocs.com
- Ontario Securities Commission, National Instrument 43-101: osc.ca
- Cornell LII, 17 CFR 229.1302 (Item 1302): law.cornell.edu
- JORC Code 2012: jorc.org
- ASX, Mining reporting FAQs: asx.com.au
- SAIMM, Rupprecht, Establishing the feasibility of your proposed mining venture (2004): saimm.co.za
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Critica Metals Limited
 Congo Mining Solutions
 Mining SARL
 SenGold Invest SAS
 Sania Corporation
 Sean Mining Limited
 NTS Group (Pty) Ltd
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading











