

Australian iron ore · Operator ranking
Iron Ore Mines in Australia: Top Operators Ranked
Australia has 55 operating iron ore mines (Geoscience Australia, 2025). Rio Tinto shipped 333 Mt from Western Australia in 2025-26, BHP 288 Mt and Fortescue 201 Mt. Here is each operator’s mines, the ports, build costs and a margin calculator.
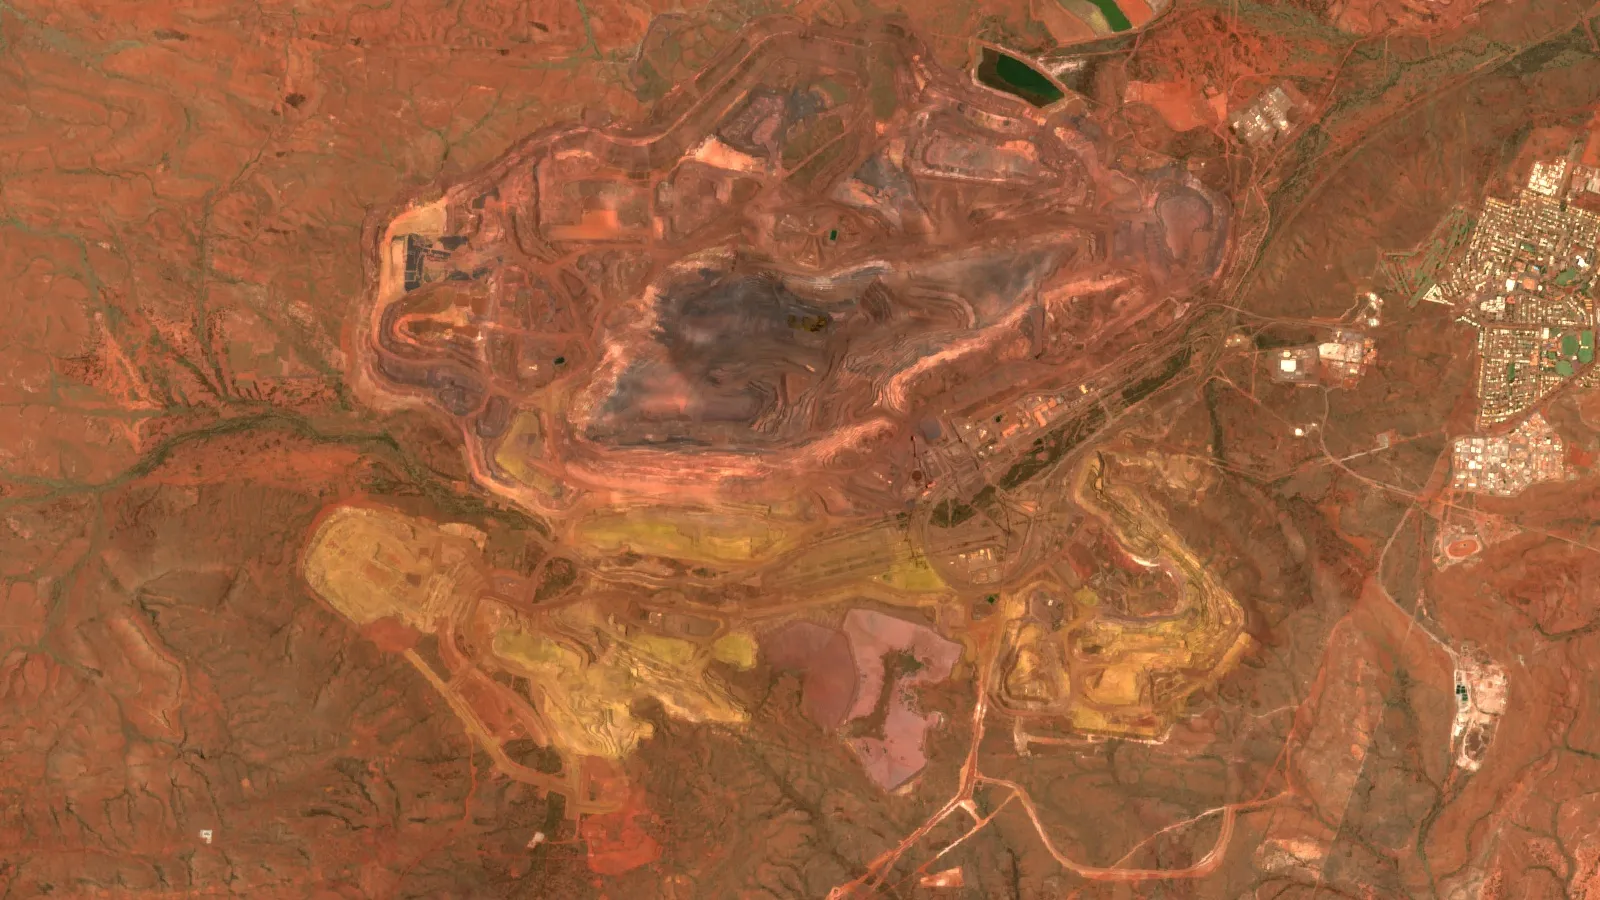
Key takeaways
- Geoscience Australia counts 55 operating iron ore mines at the end of 2025, with 961 Mt of production and 11,640 Mt of reserves at those mines.
- Rio Tinto (333 Mt), BHP (288 Mt) and Fortescue (201 Mt) shipped about 822 Mt from Western Australia in 2025-26, against state exports of 936 Mt (WA Government profile, Aug 2026).
- China took 85.7% of the value of Western Australia’s 2025-26 iron ore exports, and Port Hedland handled 550 Mt, or 59% of the volume.
- A new hematite mine cost roughly A$21 to A$120 per tonne of yearly capacity; Iron Bridge magnetite cost about A$255 (state profile project table, indicative).
- The World Bank benchmark averaged US$96.30 a tonne in August 2026; Fortescue’s cash cost was US$18.74 per wet tonne in the year to June 2026.
In this article
- How this ranking works
- Iron ore mines in Australia ranked by operator
- Why Australian iron ore matters to the economy
- Rio Tinto's Pilbara mines
- BHP's Western Australia Iron Ore hubs
- Fortescue's hematite hubs and Iron Bridge
- Hancock Iron Ore, Onslow Iron and Sino Iron
- Iron ore mines outside the Pilbara
- Where the ore goes: rail, ports and buyers
- How Australia compares with other producers
- What new Pilbara mines cost to build
- Iron ore price, costs and royalties
- Automation, AI and remote operations
- Power, land and water at the mines
Australia has 55 operating iron ore mines, and three companies ship most of the ore. In 2025-26 Rio Tinto shipped 333 million tonnes (Mt) from Western Australia, BHP 288 Mt and Fortescue 201 Mt, according to the Western Australian Government iron ore profile of August 2026, which draws on company reports. Together that is about 822 Mt, close to nine tenths of the 936 Mt the state exported. The mines sit in the Pilbara, a dry, thinly populated region in the north-west of the state, and Geoscience Australia counts 55 operating iron ore mines across the country at the end of 2025.
This page ranks the operators by shipments, names the mines each one runs, and adds the ports, the cost of building a new mine, the ore types and a margin calculator. It is written for investors and industry readers. It gives facts from company and government reports and is not investment advice.
How this ranking works
The metric is the latest full-year shipments in wet tonnes (ore as loaded, including moisture), taken from the operator or from the state government profile that compiles the operators’ reports. Most companies publish tonnes by hub, joint venture or whole system, not mine by mine. Rio Tinto, for example, reports its Hamersley mines as one group. So the honest ranking is by operator, with the mines listed under each one.
Every operator with a published tonnage is in the table. Smaller concentrate producers in the Mid West of Western Australia, such as Karara, are named in the state profile but not given a tonnage, so they are left out of the numbers. Shipments and production differ a little (stockpiles move), and joint-venture tonnes are shown on a 100% basis unless stated.
Iron ore mines in Australia ranked by operator
| Rank | Operator | Main mines | Shipments | Basis |
|---|---|---|---|---|
| 1 | Rio Tinto | Hamersley mines (Tom Price, Paraburdoo, Marandoo, Brockman 2 and 4, Gudai-Darri, Yandicoogina and others), Hope Downs, Robe Valley, West Angelas | 333 Mt | 2025-26, Western Australian operations |
| 2 | BHP | Newman (Mount Whaleback), Jimblebar, Yandi, Mining Area C, South Flank | 288 Mt | 2025-26, Western Australian operations |
| 3 | Fortescue | Cloudbreak, Christmas Creek, Solomon, Eliwana, Iron Bridge | 201 Mt | Year to June 2026 (201.3 Mt reported) |
| 4 | Hancock Iron Ore | Roy Hill, Atlas Iron operations, McPhee Creek | 61.6 Mt (Roy Hill) | Year to June 2025, wet tonnes; Atlas added about 10 Mt a year |
| 5 | Mineral Resources | Onslow Iron, Pilbara Hub (Iron Valley, Lamb Creek, Wonmunna) | 30.8 Mt through the port of Onslow | 2025-26, exports through the port of Onslow only (Onslow Iron); Pilbara Hub tonnes are not in this figure |
| 6 | CITIC Pacific Mining | Sino Iron (magnetite concentrate) | 14.9 Mt | 2024 exports, wet tonnes |
Chart
Iron ore shipments by operator
Million tonnes, latest reported year; bases differ (see table)
The Hancock row is Roy Hill’s last reported full year; the Atlas operations merged into the same company on 1 July 2025. The Sino Iron row is CITIC’s 2024 export figure, in wet tonnes.
Why Australian iron ore matters to the economy
Iron ore is the country’s largest export. The state profile puts the value of Western Australia’s iron ore exports at A$117.7 billion in 2025-26, up 2.3% on the year before, on a volume of 936 Mt (up 5.1%). China took A$100.9 billion of that, or 85.7%, with South Korea at 5.4% and Japan at 5.4% (WA iron ore profile, based on Australian Bureau of Statistics trade data).
The industry also pays and employs. Iron ore royalty receipts to the state were A$8.7 billion in 2025, which was 86% of all its royalty receipts, and direct employment reached a record 66,367 full-time equivalent jobs, about half of the state’s minerals workforce (same profile). That compares with a 2021 peak of A$12.4 billion, when the price in Australian dollars was exceptionally high.
Australia also faces new supply: the Simandou project in Guinea started operations in November 2025 and is planned to export up to 120 Mt a year once it has ramped up.
▶ Follows the money from the ground up: exports, jobs, revenue and why the world needs mined materials. · 5:03
Rio Tinto’s Pilbara mines
Rio Tinto is the largest operator. Its Pilbara mines produced 327.3 Mt in 2025 and shipped 326.2 Mt, flat on 2024, on a 100% basis (Rio Tinto, fourth quarter 2025 production results). In the first nine months of 2026 Pilbara production was 245.7 Mt, up 3%, with 83.4 Mt in the September quarter (Rio Tinto, third quarter 2026 production results).
Chart
Rio Tinto Pilbara output by operating group
Million tonnes produced in 2025, 100% basis
The company’s 2025 annual report splits the output into four operating groups, shown in the chart below. The largest group, the Hamersley mines, produced 229.6 Mt, counted at 100% because Rio Tinto manages and buys all of the output. It covers Paraburdoo, Mount Tom Price, Western Turner Syncline, Marandoo, Yandicoogina, Brockman, Nammuldi, Silvergrass, Channar, Gudai-Darri, Eastern Range and Western Range (Rio Tinto Annual Report 2025).
The other groups are Hope Downs (36.8 Mt, a 50-50 joint venture with Hancock Prospecting, covering Hope Downs 1 and 4), West Angelas (32.3 Mt) and Robe Valley (28.6 Mt, the Mesa A and Mesa J mines). West Angelas and Robe Valley belong to the Robe River joint venture, in which Rio Tinto holds 53%, Mitsui 33% and Nippon Steel 14%. Western Range is a joint venture with China Baowu Group in which Rio Tinto holds 54%; its first ore came in 2024.
These mines are old by mining standards. Mount Tom Price began in 1966, Paraburdoo in 1972, Yandicoogina in 1998 and Nammuldi in 2006. The newest, Gudai-Darri, railed its first ore in December 2021. The state profile’s project table lists a capital cost of A$4.3 billion for its 43 Mt-a-year capacity. The company moves ore on nearly 2,000 km of its own rail to four shipping terminals at Dampier and Cape Lambert.
Rio Tinto is replacing depleting mines. The state profile lists Western Range, Brockman Syncline 1, Hope Downs 2, West Angelas and Greater Nammuldi as replacement projects worth about 130 Mt a year of capacity in total, to hold the Pilbara system at 345 to 360 Mt a year.
BHP’s Western Australia Iron Ore hubs
BHP runs its Pilbara business as one system called Western Australia Iron Ore, or WAIO. A technical report that BHP filed with the US Securities and Exchange Commission, dated 30 June 2022, describes five mining hubs and four processing hubs linked to Port Hedland by more than 1,000 km of rail (BHP, WAIO technical report summary). The hubs and main deposits it lists are:
- Newman: Mount Whaleback, Eastern Ridge, Shovelanna and Western Ridge.
- Jimblebar: South Jimblebar, Wheelarra and Hashimoto.
- Yandi: the Yandi channel deposits, which the report describes as in end-of-life ramp-down from July 2021.
- Mining Area C: North Flank and Packsaddle.
- South Flank: BHP’s newest large mine, with first production in May 2021.
The report says BHP holds 85% of each of the four main joint ventures, with Mitsui and Itochu holding the other 15% (as at June 2022). In the year to June 2026 WAIO produced 291.2 Mt on a 100% basis, of which 256.9 Mt was BHP’s share, and BHP guides to 286 to 298 Mt for the year to June 2027 (BHP operational review, year to June 2026).
South Flank is designed for 80 Mt a year, with a listed capital cost of A$4.7 billion. A further 25 Mt-a-year project, Western Ridge, is listed as committed with a 2026 start. BHP and Rio Tinto are also exploring a joint plan for the neighbouring Yandi and Yandicoogina mines, which could process BHP’s Yandi Lower Channel Deposit ore through Rio Tinto’s plants and open up to 200 Mt of ore, with first ore possible early in the next decade (state profile).
Fortescue’s hematite hubs and Iron Bridge
Fortescue is the third operator. Cloudbreak, in the Chichester Ranges, made its first ore in 2008 and is now the flagship site (Fortescue, Cloudbreak). The company’s operations page lists Christmas Creek, Cloudbreak, Eliwana, Solomon and the Iron Bridge magnetite operation, linked to Port Hedland by 760 km of rail (Fortescue, operations).
In the year to June 2026 Fortescue shipped a record 201.3 Mt, passing 200 Mt for the first time. Of that, Iron Bridge concentrate was 9.0 Mt, up 27%. Its hematite cost (C1, a cash operating cost measure) was US$18.74 per wet tonne, and the average price it realised was US$91 per dry tonne. Guidance for the year to June 2027 is 197 to 207 Mt, including 11 to 14 Mt from Iron Bridge, and port capacity is about 205 Mt a year (Fortescue June 2026 quarterly report).
Iron Bridge is the one to watch. The state profile lists a 67% iron product there, against 62% for most of the hematite projects, but Fortescue has revised its ramp-up schedule. In the same report it said it expects a non-cash impairment of about US$525 million after tax on the project in its 2026 results.
Hancock Iron Ore, Onslow Iron and Sino Iron
Roy Hill and Atlas Iron, both part of the Hancock group, merged into Hancock Iron Ore from 1 July 2025. Atlas Iron shipped about 10 Mt a year when the merger was announced (International Mining, June 2025). Roy Hill shipped 61.6 Mt in the year to June 2025, and on 17 June 2026 Hancock said it would hold output above 63 Mt a year under a mine plan that extends the mine life by ten years (Argus Media). McPhee Creek, an A$840 million mine about 100 km north of Roy Hill, reached first ore on 30 June 2026, and its ore is trucked to Roy Hill for processing (Hancock Iron Ore). Hancock also holds half of the Hope Downs joint venture with Rio Tinto.
Mineral Resources (MinRes) runs two iron ore businesses. Its Onslow Iron project reached its 35 Mt-a-year nameplate in August 2025, three years after the investment decision (Mineral Resources annual results, August 2026). Its attributable shipments for the year to June 2026 were 19.7 Mt, and the Pilbara Hub added 9.9 Mt as Lamb Creek ramped up (Mineral Resources June 2026 quarterly report). Exports through the port of Onslow rose from 13.1 Mt to 30.8 Mt over 2025-26 (state profile). The same company is also a lithium producer; see our guide to lithium in Australia.
Sino Iron, at Cape Preston, is a magnetite mine that sells concentrate. It exported about 14.9 Mt of concentrate in 2024 against a design rate of 24 Mt a year, after the pit reached the edge of its approved footprint. Western Australia approved its mine continuation proposals in June 2025, for an interim period (Mysteel, citing CITIC Pacific Mining).
Iron ore mines outside the Pilbara
Western Australia accounts for nearly all of Australia’s iron ore production and reserves, and for 99% of its iron ore exploration spending, which was A$812 million in 2025-26 (state profile). Elsewhere the ore is small by comparison. In Tasmania, Grange Resources runs Savage River, which makes magnetite pellets. The company has approved a North Pit underground mine at an estimated A$287 million, with first underground ore in 2028 and pellet supply planned through 2035 (Smallcaps, citing Grange Resources).
Where the ore goes: rail, ports and buyers
All the big mines are tied to a port by a private railway. Port Hedland handled 59% of the state’s iron ore export volume in 2025-26, or 550 Mt, followed by Cape Lambert at 168 Mt and Dampier at 147 Mt. All other ports together handled 71 Mt, with Onslow the fast riser (state profile).
Infographic
From pit to ship in five steps
- 1Drill and blastOpen pits are drilled and blasted, then shovels load trucks.
- 2Crush and screenOre is crushed and screened into lump and fines, or washed in wet plants.
- 3Beneficiate if neededLower-grade ore is upgraded; magnetite is ground and separated.
- 4Rail to the coastPrivate heavy-haul railways carry ore to Dampier, Cape Lambert or Port Hedland.
- 5Ship to buyersOre is loaded at port and shipped, mostly to steel mills in China.
Chart
Western Australian iron ore exports by port
Million tonnes, 2025-26
How Australia compares with other producers
The US Geological Survey puts Australian usable ore output at 980 Mt in 2025 (estimate), out of about 2,600 Mt worldwide, so a share of about 38%. Geoscience Australia gives 37% for the same year. Brazil was next at 420 Mt. Reserves tell the same story: Australia holds an estimated 27,000 Mt of contained iron in reserves, against 15,000 Mt in Brazil and 14,000 Mt in Russia (USGS Mineral Commodity Summaries 2026).
Chart
Usable iron ore mine output, selected producers
Million tonnes of usable ore; the USGS table lists more countries
Geoscience Australia’s preliminary 2026 tables, with data to 31 December 2025, count Australia’s economic demonstrated resources of iron ore at 59,124 Mt, of which about 33,560 Mt is hematite and 26,552 Mt is magnetite (the two do not add exactly because of small data discrepancies). Ore reserves at operating mines are 11,640 Mt, or 12 years of production at the 2025 rate (Geoscience Australia).
What new Pilbara mines cost to build
The state profile lists the capital cost and capacity of recent and committed projects. Divide one by the other and you get a rough build cost per tonne of yearly capacity: about A$21 for West Angelas C+D, A$40 for Robe Valley, A$59 for South Flank, A$83 for Onslow Iron, A$100 for Gudai-Darri and A$120 for Western Range, against about A$255 for Iron Bridge. Several of these figures include rail and port works, so they are indicative, not like-for-like.
Chart
Capital cost against capacity, recent Pilbara projects
Figures as listed by the state profile; some include rail and port
The gap is the cost of magnetite. Hematite is mined and crushed. Magnetite deposits typically hold less iron per tonne of ore, so the ore is ground and separated by magnetism before it can be sold, which needs far more plant. The payoff is the higher grade and the premium it can earn. Explorers look for it differently from the hematite of the Pilbara; our guide to iron ore exploration covers how bulk deposits are found and tested.
Iron ore price, costs and royalties
The World Bank’s monthly benchmark (62% iron, delivered to China) averaged US$96.30 a tonne in August 2026, 1.9% lower than July. The Western Australian budget assumes US$85.2 for 2026-27, and US$72.0 a year from 2027-28 to 2029-30 (state profile). A Kallanish assessment for 62% ore at Qingdao stood at US$90.6 a tonne CFR on 13 October 2026 (GMK Center, citing Kallanish). Prices change daily, so check a live source.
Royalty works like this: for minerals sold crushed or screened, the Western Australian general rate is 7.5% of the royalty value, with 5.0% for concentrate (WA Government, mineral royalties fact sheet). Large projects are covered by their own state agreements, which can set different terms, so use your own agreement for a real project.
The calculator below turns shipments, moisture, price, cash cost and royalty into a rough pre-tax margin. It is a back-of-envelope tool, not a model of any company.
Calculator
What is the pre-tax margin of an iron ore mine?
Enter your own shipments, price and costs. All values are in US$.
- Revenue (US$ million): 1,656
- Margin per wet tonne (US$): 56.59
- Break-even price (US$ per dry tonne): 23.5
Example values only, not a benchmark. Fortescue reported a hematite cash cost (C1) of US$18.74 per wet tonne for the year to June 2026 (ASX, 31 July 2026). The 7.5% royalty is the Western Australian general rate for crushed or screened minerals (WA Government fact sheet, 2025); major projects can differ. The price is an input: example, use today’s price. Result is before shipping, sustaining capital, overheads and tax.
Automation, AI and remote operations
Automation is widespread in the Pilbara. Fortescue’s Integrated Operations Centre, the Hive, runs its pit-to-port chain remotely around the clock. In November 2019 Fortescue announced that trucks running Caterpillar’s autonomous system had moved one billion tonnes of material, with a 30% productivity gain at the site (MINING.COM).
BHP, in its year to June 2026 review, reported a trial of two Cat 793 XE battery-electric haul trucks at WAIO, described as an industry-first collaboration with Rio Tinto and Caterpillar.
▶ Explains the three jobs an AI mining app can do: finding places to look, planning the mine and running it. · 3:52
Power, land and water at the mines
Both Fortescue and Rio Tinto are building solar power at their Pilbara sites. Fortescue plans a Green Grid of 1.5 GW of solar, 900 MW of wind and 4 to 5 GWh of battery storage by 2028. At Cloudbreak a 60 MW solar farm already runs, with a 190 MW farm under construction and electric excavators in use. Rio Tinto lists a solar farm of up to 34 MW at Gudai-Darri in its 2025 annual report.
Land access is the other constraint. Rio Tinto notes that its Pilbara sales range depends on the timing of approvals for planned mining areas and heritage clearances (third quarter 2026 report). Fortescue’s June 2026 report records a new native title agreement and co-management agreement with the Puutu Kunti Kurrama and Pinikura people.
▶ Explains the seven environmental impacts of mining in plain words, with satellite maps. · 2:31
How satellites help screen iron ore ground
Iron minerals show up in optical and infrared satellite data, which makes them one of the minerals that can be screened from space before any ground work. Farmonaut’s satellite-based mineral detection takes a polygon or KML/KMZ file of your licence area and returns a report with prospective zones, delivered in 5 to 20 business days depending on size and mineral. The zones are exploration targets that sit ahead of a resource estimate, and they need drilling to test. You can request a quote on the mining query form. To see who holds the ground around a target, our guide to mining cadastre portals is a starting point.
If this topic matters to you, read Iron Knob Australia: Mine History and Current Status next.
Related reading on this site: Diamond Mines in Australia: Operating, Closed, Planned.
Frequently asked questions
How many iron ore mines are there in Australia?
Geoscience Australia counts 55 operating iron ore mines at the end of 2025, with ore reserves of 11,640 Mt at those mines and production of 961 Mt that year (preliminary 2026 tables).
Who owns the biggest iron ore mine in Australia?
No source ranks single mines by output, because companies report by hub or group. By published design capacity among the recent large projects in the state profile, BHP’s South Flank leads at 80 Mt a year. By operator, Rio Tinto is the largest, with 333 Mt shipped in 2025-26.
Where are most Australian iron ore mines located?
In the Pilbara of Western Australia. The state accounts for nearly all of Australia’s production and reserves, and for 99% of exploration spending on iron ore in 2025-26.
How much iron ore does Australia produce?
Geoscience Australia puts 2025 mine production at 961 Mt and the US Geological Survey at about 980 Mt of usable ore, close to 37% to 38% of the world total.
Who buys Australian iron ore?
China took 85.7% of the value of Western Australia’s iron ore exports in 2025-26, with South Korea at 5.4% and Japan at 5.4%.
What is the difference between hematite and magnetite ore?
Hematite is the main Pilbara ore and can often be shipped after crushing and screening. Magnetite has to be ground and concentrated first, which costs more, but it gives a higher iron product such as Fortescue’s 67% Iron Bridge concentrate.
What is the iron ore price now?
The World Bank benchmark averaged US$96.30 a tonne in August 2026, and a spot assessment was US$90.6 a tonne on 13 October 2026. Check a live source for today’s figure.
How long will Australia’s iron ore last?
Reserves at operating mines equal about 12 years of production at the 2025 rate, according to Geoscience Australia. Geoscience Australia’s resource-based estimates are longer, at 32 and 86 years depending on which resource categories are counted.
Are there iron ore mines outside Western Australia?
Yes, but they are small. Grange Resources runs the Savage River magnetite pellet operation in Tasmania.
Can satellites find iron ore?
Satellite data can flag iron-bearing zones for follow-up, and iron is one of the minerals Farmonaut screens. The output is an exploration target, not a resource estimate, and drilling is the only test.
This page is for information only. It is not investment advice.
Farmonaut mining
Screen your own licence area from space
Request a quote for a satellite screening of your licence area; results are exploration targets that sit ahead of a resource estimate.

Mining Pro sample view, synthetic data
Keep reading
Sources
- Western Australian Government, Western Australia Iron Ore Profile (Aug 2026): watc.wa.gov.au
- USGS, Mineral Commodity Summaries 2026: Iron ore: pubs.usgs.gov
- Geoscience Australia, Australia’s Identified Mineral Resources 2026 preliminary tables: ga.gov.au
- Rio Tinto, Annual Report 2025: sec.gov
- Rio Tinto, fourth quarter 2025 production results: riotinto.com
- Rio Tinto, third quarter 2026 production results: riotinto.com
- BHP, operational review for the year ended 30 June 2026: announcements.asx.com.au
- BHP, WAIO technical report summary (30 June 2022): minedocs.com
- Fortescue, June 2026 quarterly production report: announcements.asx.com.au
- Fortescue, operations: fortescue.com
- Fortescue, Cloudbreak: fortescue.com
- Mineral Resources, June 2026 quarterly report: announcements.asx.com.au
- Mineral Resources, annual results (27 Aug 2026): announcements.asx.com.au
- International Mining, Roy Hill and Atlas Iron to merge into Hancock Iron Ore (Jun 2025): im-mining.com
- Mysteel, CITIC’s Sino Iron Project secures approval for mining extension: mysteel.net
- Smallcaps, Grange Resources approves Savage River underground mine: smallcaps.com.au
- GMK Center, Iron ore prices in China remain within a narrow range (Oct 2026): gmk.center
- Western Australian Government, Mineral royalties fact sheet (Sept 2025): wa.gov.au
- MINING.COM, Caterpillar moves a billion tonnes autonomously at Fortescue (Nov 2019): mining.com
- Argus Media, Hancock to cut Roy Hill iron ore production (17 Jun 2026): argusmedia.com
- Hancock Iron Ore, McPhee Creek reaches first ore (30 Jun 2026): hancockironore.com.au
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Klusetic Mining Investments
 Mine4Africa
 Lithspo Minerals Limited
 Tintina Mining Group
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited











