

Mining finance · Funder guide
Mining Investment Companies: Who Funds Mines
Mines are funded in layers: shares for exploration, royalties, streams, private equity and bank debt for development. Junior miners raised US$21.43 billion in 2025 (S&P Global Market Intelligence).
Key takeaways
- Junior and intermediate miners raised US$21.43 billion in 2025, up 109%, but much went to development, not exploration (S&P, via BusinessDay).
- Gold took US$6.15 billion, about half of 2025 exploration budgets; grassroots work fell to a record-low 21% share.
- Wheaton, Franco-Nevada and Royal Gold each reported record 2025 income; stream cheques ran to US$300 million and US$670 million.
- Banks lend only against a feasibility study, and many follow the Equator Principles for projects of US$10 million or more.
- Governments now invest directly, for example the US Department of Defense in MP Materials in July 2025.
In this article
- Who funds a mine: eight sources compared
- Equity investors: shares in listed miners and juniors
- Royalty and streaming companies
- Price or volume: what lifted royalty and stream income
- Private equity and specialist mining funds
- Banks, development lenders and project finance
- Governments as mining investors
- Match the funder to your project stage
- What funders check before they commit
- How to approach a mining investment company: five steps
- Royalty or equity: what each route costs the owner
- Frequently asked questions
A mining investment company is any firm that puts money into mines in return for a share of the ownership, the metal or the revenue. Six types do most of the work: stock-market investors in listed miners, royalty and streaming companies, private equity funds, banks and development lenders, commodity buyers, and governments. In 2025, junior and intermediate miners raised US$21.43 billion from investors, up 109% on the year before, according to S&P Global Market Intelligence figures reported by BusinessDay. This guide shows who writes those cheques, what each one takes in return, and which type fits a licence at each stage, from first drill hole to a producing mine.
It is written for licence and claim owners who need money, consultants who advise them, and investors who want to know who else sits at the table. It names real firms and gives their own published figures with dates. It is not investment advice and it does not rank firms as good or bad buys.
Who funds a mine: eight sources compared
No single investor funds a mine from start to finish. Money arrives in layers, and each layer is priced for the risk at that stage. The table below sets the main sources side by side. Terms are explained in the sections that follow.
| Source | Typical stage | What the funder takes | Examples with published facts |
|---|---|---|---|
| Listed-company shareholders | Exploration to production | New shares, sometimes with warrants | Juniors and mid-tier miners on the TSX Venture, ASX and similar boards |
| Royalty companies | Development and production | A percentage of revenue or profit, no running costs | Franco-Nevada, Royal Gold |
| Streaming companies | Construction and production | Metal bought at a low fixed price after a large upfront payment | Wheaton Precious Metals |
| Private equity and specialist funds | Exploration to expansion | Equity or convertible stakes, board seats, sometimes credit and royalties | Resource Capital Funds, Appian Capital Advisory |
| Banks and project lenders | Construction and production | Interest and fees, secured on project cash flow | Lenders that follow the Equator Principles |
| Development finance institutions | Construction, often in emerging markets | Interest, plus environmental and social conditions | Multilateral and national development banks |
| Commodity buyers | Construction and ramp-up | Prepayment against future metal, or an offtake right | Trading houses and smelters |
| Governments | Strategic projects | Equity stakes, loans, price floors | US Department of Defense and MP Materials |
The first six rows are the ones most small owners will meet. The last two matter mainly for larger or strategic projects.
Equity investors: shares in listed miners and juniors
Most exploration companies are funded the same way: they list on a stock exchange, sell new shares to investors in a private placement or public offering, and spend the cash on drilling. A junior is a small company that explores but does not yet produce. An intermediate is a mid-sized producer. Both depend on investors who accept the risk that a drill programme finds nothing.
Chart
Where exploration money went in 2025
2025 nonferrous exploration budgets, selected commodities, US$ billion
The money moves with the metal price. In 2025, funds raised by junior and intermediate miners rose 109% to US$21.43 billion, the second-highest annual total on record, after three years of decline, and S&P linked the recovery to lower interest rates and stronger gold, copper and silver prices (BusinessDay, citing S&P Global Market Intelligence). Much of that capital went to mine development, not new exploration, which is why exploration budgets did not rebound with it.
Exploration spending shows where the equity money wants to go. Global nonferrous exploration budgets slipped 1% to US$12.4 billion in 2025, but gold rose 11% to US$6.15 billion and copper rose 2% to US$3.27 billion, while lithium fell 46%, nickel fell 37% and cobalt fell 41%. Junior budgets fell 13% to US$4.39 billion. Grassroots exploration, the earliest stage, fell to US$2.57 billion, only 21% of the total, the lowest share in S&P’s dataset, while work at existing mines reached a record US$5.63 billion. For a licence owner, the lesson is practical: investors in 2025 paid for gold and copper, and for ground near known mines, far more readily than for early-stage battery-metal ideas.
A fair question is how a small company raises equity at all. Typical steps are a technical report written by a qualified person, a legal opinion on title, and a use-of-funds plan that a broker can sell. Our guide to where to meet mining investors and what they check covers conferences and diligence lists in more detail.
Royalty and streaming companies
A royalty pays the holder a share of a mine’s revenue or profit for as long as the mine produces, for example a 2% net smelter return (NSR) royalty, which is 2% of what the mine receives from selling its metal after smelting and refining charges. A stream is a purchase agreement: the streaming company pays a large sum upfront, then buys a share of the mine’s metal at a low fixed price per ounce. Franco-Nevada describes the appeal for miners as low-cost and flexible financing that can ease fixed debt and avoid excessive equity dilution, and says it does not run mines or carry out exploration itself (Franco-Nevada, business model).
Chart
Revenue of three royalty and streaming firms
Full-year 2025 revenue, US$ billion (Royal Gold stated as about US$1 billion)
Three large listed gold-focused royalty and streaming firms all reported record figures for 2025. Wheaton Precious Metals reported revenue of about US$2.31 billion, net earnings of about US$1.47 billion and 651,311 gold equivalent ounces (GEOs) sold, with 23 operating mines and 25 development and other projects under agreement (Wheaton, 6-K results release). Franco-Nevada reported US$1,822.8 million of revenue and 519,106 GEOs sold, with cash of US$670.9 million and, in its CEO’s words, no debt and US$3.1 billion of available capital (Franco-Nevada, 6-K results release). Royal Gold said revenue was about US$1 billion and operating cash flow US$705 million, with gold supplying 78% of revenue, after it bought Sandstorm Gold and Horizon Copper (the deal closed on 20 October 2025) and a gold stream on the Kansanshi mine from First Quantum (Royal Gold, fourth-quarter 2025 call transcript).
New deals show how large the cheques are. In November 2025 Wheaton signed a stream on the Hemlo mine with US$300 million paid upfront and one on Spring Valley with US$670 million of total upfront consideration, paid in instalments from December 2025 (same Wheaton release). Franco-Nevada’s cash-flow statement shows US$2,191.6 million spent on royalty, stream and working interests in 2025.
These firms do not usually fund grassroots exploration. They buy into projects that already have a resource estimate and a path to production, and they want gold, silver, copper or platinum group metals from jurisdictions with clear mining law. Small royalties on exploration-stage ground do exist, and a licence owner can sell one to raise cash; the trade-off is giving up a slice of revenue for the life of the mine. For the gold-focused names see our overview of gold royalty companies and their key players.
Price or volume: what lifted royalty and stream income
Royalty income rises with the metal price even when output is flat. Wheaton said its revenue growth came from a 46% rise in the average realised price per gold equivalent ounce and a 23% rise in ounces sold. Its attributable production rose 8.6% to 689,864 GEOs, while sales rose from 529,493 to 651,311 GEOs. The gap between production and sales is timing: ounces produced are not always delivered and sold in the same year.
Chart
Wheaton: ounces produced and sold
Gold equivalent ounces (GEOs), attributable
The reverse also holds. A royalty owner earns nothing from a mine that stops. Franco-Nevada’s 2025 figures include 11,208 GEOs from Cobre Panamá, a mine that was still halted when Franco-Nevada reported in March 2026, and its 2026 guidance leaves that mine out. Funders in this group price in the risk of a stop, so they favour operators with a record of steady production and secure permits.
Private equity and specialist mining funds
Private equity firms in mining raise a fund from pension plans and other institutions, then buy stakes in private or listed miners and sell them years later. They often take board seats and help with technical and financial decisions, which is attractive to a licence owner who lacks a management team.
Resource Capital Funds describes itself as a global specialist investor in critical minerals, metals and mining from exploration through closure, and states 25-plus years of investing, more than 240 portfolio company investments, more than 190 fully realised investments, 55-plus countries and 25-plus mines brought into production (Resource Capital Funds, firm page). Appian Capital Advisory advises the Appian Natural Resources funds and says it invests through equity, credit and royalties; its page lists an Appian EM Fund with a US$1.0 billion target, Appian Credit Strategies I with a final close of US$374 million, 40 investments, 12 mines brought into production and 19 exits as of April 2026 (Appian Capital Advisory, firm page). Treat these as each firm’s own statements.
Funds like these want a clear exit: a sale to a larger miner, a listing, or a buy-back. They usually look for projects with a defined resource, a credible plan and room to add value, not for bare licences. Our guide to mining private equity and venture capital explains how funds pick projects, and the page on how to sell a mine covers the exit side.
Banks, development lenders and project finance
Once a mine has a feasibility study (an engineering and economic study that shows whether the mine can be built and run at a profit), banks can lend against it. In project finance the loan is repaid from the mine’s own cash flow and secured on the project assets, so lenders hire independent engineers to test the numbers. They also expect debt to be balanced with equity, hedging against price falls and insurance.
Many large lenders follow the Equator Principles, a risk framework for environmental and social risk that applies to project finance where total project capital costs are US$10 million or more. The fourth version (EP4) took effect for all adopting institutions on 1 October 2020 (Equator Principles, about the principles). In practice a licence owner needs environmental baseline studies, community consultation records and a closure plan before the loan committee will meet.
Development finance institutions, which are state-owned or multilateral banks, lend in emerging markets where commercial banks hold back. Their money comes with conditions on safety, water, tailings and community benefit. Commodity buyers add a third debt-like route: a trader or smelter may advance cash against future deliveries of concentrate or metal. Each route has its own covenants, so compare terms before you sign. Our overview of how mine projects are funded from licence to mill walks through the modelling.
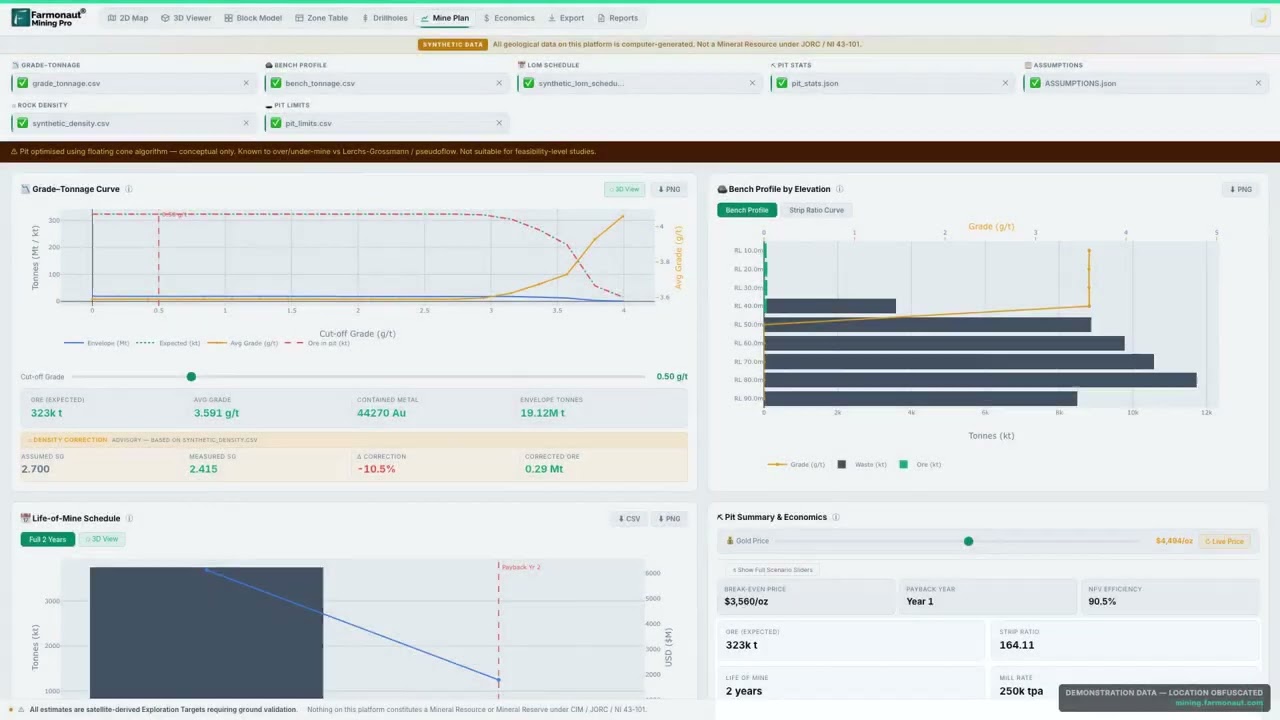
▶ Mine plan costs, all-in sustaining cost, break-even price and payback, the numbers lenders test. · 14:58
Governments as mining investors
Since 2025 governments have become direct investors in minerals. The clearest example is the US Department of Defense partnership with MP Materials, announced in July 2025: the Department bought US$400 million of convertible preferred stock plus a warrant (together about 15% of shares on an as-converted basis), committed to a 10-year price floor of US$110 per kilogram for neodymium-praseodymium (NdPr) products, and lent US$150 million for heavy rare earth separation. JPMorgan Chase and Goldman Sachs Bank committed US$1.0 billion to finance a new magnet facility (MP Materials, 8-K exhibit).
As of October 2025, the Columbia University Center on Global Energy Policy listed further US stakes: 5% in Lithium Americas and 5% in its Thacker Pass joint venture, and 10% in Trilogy Metals. Its analysts warn that stakes pick winners without a competitive process, can dilute other shareholders, risk losing taxpayer capital if a project fails, and may raise the cost of early-stage money for firms left out; they suggest tax credits, permitting reform and price floors as broader tools (Columbia CGEP, Q&A on equity stakes).
Public money is growing across the world. The International Energy Agency reports public finance commitments for critical mineral projects of US$65 billion between 2023 and 2025, a fourfold increase, even though investment in mining projects fell 9% in 2025 (Mining Digital, summarising the IEA outlook; see the IEA report page). Government programmes cover a narrow set of strategic minerals, so most owners of gold, silver or base-metal ground will still raise money from the sources above.
Match the funder to your project stage
The right source depends mainly on how much is known about the ground. The table gives a practical order.
| Stage | What you have | Most likely funders | What they will ask for |
|---|---|---|---|
| Grassroots | Licence, maps, early samples | Founders, angel and private investors, small share placements, joint-venture partners | Title, work plan, geology case |
| Drill-ready target | Anomaly, geophysics, first drilling | Listed-junior shareholders, flow-through or placement buyers, strategic stakes from majors | Qualified-person report, budget, team record |
| Resource defined | Resource estimate, scoping study | Private equity funds, small royalties, equity placements | Resource report, metallurgy, permit path |
| Feasibility complete | Feasibility study, permits | Streaming and royalty firms, banks, development lenders, commodity buyers | Bankable study, independent engineer review, environmental studies |
| Operating mine | Cash flow, reserves | Bank debt, expansion equity, royalty sales | Production record, cost per ounce, closure plan |
Costs rise with each step, and so does the evidence demanded. Cost per ounce is judged on a standard basis called all-in sustaining cost (AISC); see our guide to mining margins and AISC by metal for how funders read it.
What funders check before they commit
Every funder tests the same five things, whatever the instrument. First, title: who legally holds the licence, for how long, and what work is due. Second, geology: what the drilling proves, and how much of the story is still a model. Third, economics: grade, recovery, cost, price and tax. Fourth, permits and people: environmental approval, community support and land access. Fifth, management: whether the team has built a mine before.
Land access is the check that surprises owners most. Rock can be rich yet unmineable if it sits under a town, a park or a water source. The video below uses a survey in which 59% of the anomalous ground lay under a town. Resource numbers must also follow a recognised code such as NI 43-101 (Canada) or JORC (Australia) before most public investors will rely on them; satellite or desk screens are exploration targets, not resource estimates, and investors know the difference.
Evidence that costs little to gather helps most at the early stage. Satellite imagery can screen a licence for alteration, structure and land cover before a field season, so the first drilling money goes to better targets. That does not replace sampling or a qualified person; it shortens the list of places to sample first.
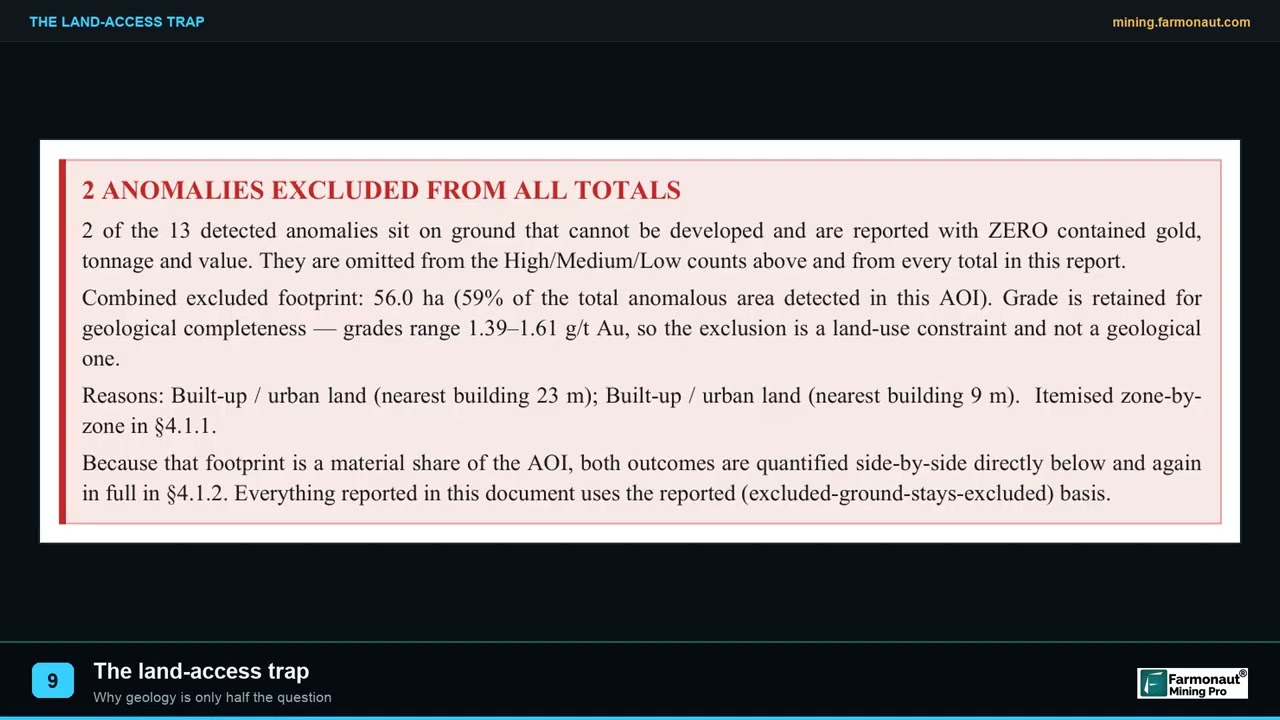
▶ Why rich rock can still be unmineable: a survey where 59% of anomalous ground lay under a town. · 2:05
How to approach a mining investment company: five steps
- Write a two-page summary. Include licence number and expiry, location, commodity, work done, planned programme, budget and what the money buys.
- Pick funders by stage. Use the table above; do not send a bare licence to a stream buyer.
- Prepare a data room. Title documents, maps, assay certificates, geophysics, environmental baseline, a project timeline.
- Check the funder. Confirm the firm and its people on company filings, the regulator’s register and its own website; reject anyone asking for a fee before any term sheet.
- Compare terms in dollars. Turn each offer into what you give up per year and over the mine life, using the calculator below.
Beware advance-fee schemes. A real fund or royalty company earns its fee from the deal; it does not ask a licence holder to pay for a “listing”, a “guarantee” or a “due diligence deposit” before talks begin. Get a lawyer who knows mining law in your jurisdiction to read every term sheet.
Royalty or equity: what each route costs the owner
The calculator below turns two offers into dollar figures. A royalty takes a share of revenue every year, whatever the costs. Equity takes a share of profit, so the funder shares the cost risk. Which is cheaper depends on margins, mine life and price; run your own numbers.
Calculator
Royalty or equity: what does each offer cost you?
Enter your own production, price and offer terms.
- Royalty over mine life (US$): $30,000,000
- Equity share of cash flow per year (US$): $6,000,000
- Equity share over mine life (US$): $60,000,000
Example values only, not a benchmark. Price is an example, use today’s price; money is in US$. A royalty is taken on revenue, equity on net cash flow.
Frequently asked questions
What does a mining investment company do?
It supplies money to mining projects in exchange for shares, a revenue royalty, metal at a set price, interest, or a mix. Some firms buy listed shares, some run private funds, and some only buy royalties or streams on producing mines.
What are the main types of mining finance companies?
Equity investors, royalty companies, streaming companies, private equity funds, banks, development finance institutions, commodity buyers and governments. The comparison table near the top of this page sets out the stage, return and examples for each.
Who invests in early-stage exploration?
Mostly founders, private investors and shareholders of listed juniors. In S&P’s 2025 data, grassroots exploration made up only 21% of budgets, US$2.57 billion, so early money is scarce compared with money for known deposits.
What is the difference between a royalty and a stream?
A royalty pays a percentage of revenue or profit. A stream is a right to buy metal at a low fixed price after paying a large upfront sum. Neither holder runs the mine. Both are paid only when the mine produces.
How much do royalty and streaming deals pay upfront?
It varies by mine. Wheaton’s November 2025 agreements paid US$300 million upfront for the Hemlo stream and US$670 million in total upfront consideration for the Spring Valley stream. Small royalties on early-stage ground are far smaller.
Can a small licence owner get a bank loan?
Rarely before a feasibility study. Banks lend against proven cash flow, supported by an independent engineer’s review and environmental and social studies, so owners of early-stage ground usually raise equity first.
Do governments invest in mines?
Yes, increasingly for strategic minerals. The US Department of Defense bought US$400 million of MP Materials preferred stock in 2025, and the US also holds stakes in Lithium Americas and Trilogy Metals, according to Columbia CGEP. Public finance for critical mineral projects reached US$65 billion in 2023 to 2025, per the IEA.
What do funders want to see in a mining project?
Clear title, drilling results interpreted by a qualified person, an economic model, permits and a plan for land access and community relations, and a management team with relevant experience.
How do I find a genuine investor and avoid scams?
Check the firm on company filings and regulator registers, speak to past investees, and refuse any request for an upfront fee before terms are agreed. Use a mining lawyer.
Which commodities attract the most exploration money?
Gold, with US$6.15 billion or about half of 2025 budgets, then copper at US$3.27 billion, per S&P Global Market Intelligence. Lithium, nickel and cobalt budgets fell sharply that year.
Is mining investment safe?
No. Drilling can find nothing, prices fall, permits can be refused and mines can stop, as the Cobre Panamá halt shows. This page is for information only and is not investment advice.
This page is for information only. It is not investment advice or legal advice. Confirm terms with a qualified lawyer and the regulator.
Farmonaut mining
Show funders what your ground looks like from space
Request a quote for a satellite screening report on your licence area, an exploration target ahead of drilling and not a resource estimate.

Mining Pro sample view, synthetic data
Sources
- Franco-Nevada, fourth-quarter and full-year 2025 results (6-K): sec.gov
- Wheaton Precious Metals, fourth-quarter and full-year 2025 results (6-K): sec.gov
- Wheaton Precious Metals, Q4 2025 results (PDF, production and sales table): s203.q4cdn.com
- Royal Gold, fourth-quarter 2025 earnings call transcript: s28.q4cdn.com
- BusinessDay, Gold drives mining exploration as global budgets fall for third year (S&P Global Market Intelligence data, 2026): businessday.co.za
- Mining.com / Northern Miner, Global exploration budgets fall as juniors tighten belts: S&P (2025): mining.com
- MP Materials, Department of Defense partnership (8-K exhibit, July 2025): sec.gov
- Columbia Center on Global Energy Policy, how the US is using equity stakes in critical minerals (Oct 2025): energypolicy.columbia.edu
- Mining Digital, IEA: investment in critical minerals has fallen 9% (2026): miningdigital.com
- IEA, Global Critical Minerals Outlook 2026: iea.org
- Resource Capital Funds, firm page: resourcecapitalfunds.com
- Appian Capital Advisory, firm page (April 2026 figures): appiancapitaladvisory.com
- Equator Principles Association, about the Equator Principles: equator-principles.com
- Franco-Nevada, business model: franco-nevada.com
Discussion
Questions, corrections or field experience? Share them below. First-time comments are reviewed before they appear, and your email is never published.
No comments yet. Be the first to add a question or your experience.

 Process Metrology LLC
 Dalgety Minerals Pty Ltd
 Vortex Minerals Pty Ltd
 Faith At Work (Pty) Ltd
 Geotech Mining Solutions plc
 Vulcan International Limited
 Kidepo Associates
 GKY Mining
 Alkimy SARL
 Double A Trading
 GemSprout Metals Limited
 Qader Group
 Ileys General Trading
 SG Gold Mining LLC
 VRV Global Pte Ltd
 Omsri International FZE
 G.I.T.T.
 Jaunita Erss Ltd
 Almosi SARL
 SRK Consulting
 Berks Gold Limited
 Mwerezi Minerals Company Limited

 Exploration consultancy · South Africa · Gold










